
 Motor Lamination Material Market | 2026-2036
Motor Lamination Material Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Lamination Material Market Analytics
Buyer concentration among electric vehicle original equipment manufacturers is recalibrating procurement volumes across the motor lamination supply chain. ArcelorMittal leverages its European production footprint to anchor premium non-oriented electrical steel supply for automotive traction motors. Baosteel dominates domestic Chinese demand through integrated hot-rolled to cold-rolled conversion capacity. JFE Steel differentiates via ultra-thin gauge silicon steel products targeting high-frequency inverter-driven motor applications.
Motor lamination material comprises thin-gauge ferrous alloys, typically silicon-alloyed electrical steel between 0.20 mm and 0.65 mm thickness, stamped or laser-cut into geometrically precise core segments that channel magnetic flux with minimal eddy current losses in rotating electrical machines. The material's silicon content, generally ranging from 0.5% to 6.5%, directly governs core loss performance and permeability characteristics under alternating magnetic fields. Electrical steel grades command the largest volume share across material types, though amorphous steel is expanding fastest in transformer and premium motor segments where core loss reduction justifies material cost premiums. Automotive end users generate the most intensive demand growth, driven by permanent magnet motor and induction motor proliferation in electrified powertrains.
The EPA enforces minimum efficiency standards under NEMA MG-1 that compel motor manufacturers to specify lower-loss lamination grades, while China's MIIT implements GB standards that progressively tighten motor efficiency tiers. Japan's METI directs industrial efficiency roadmaps that favor advanced electrical steel adoption through its Top Runner program. Stakeholders must monitor how regional efficiency mandates diverge in stringency and test methodology, as compliance fragmentation will shape sourcing strategies and material qualification investments.
Market Dynamics
Thin-gauge electrical steel substitution is compressing legacy lamination supply chains as permanent magnet motor architectures demand higher silicon grades and tighter thickness tolerances. This material specification escalation is redrawing procurement relationships between steel mills and automotive tier-one suppliers.
Growth Catalysts
- EPA NEMA MG-1 Efficiency Mandates:Tightened minimum efficiency tiers in US industrial motors are forcing manufacturers to specify lower-loss electrical steel grades, accelerating premium material qualification cycles.
- China's Dual Carbon Goals:MIIT motor efficiency roadmaps are systematically retiring IE2 and below classifications, creating sustained demand pull for high-silicon non-oriented electrical steel in domestic manufacturing.
- EV Powertrain Proliferation:Automotive traction motor volumes are concentrating procurement power among battery-integrated drivetrain producers, amplifying order visibility for amorphous and thin-gauge silicon steel suppliers.
Market Restraints
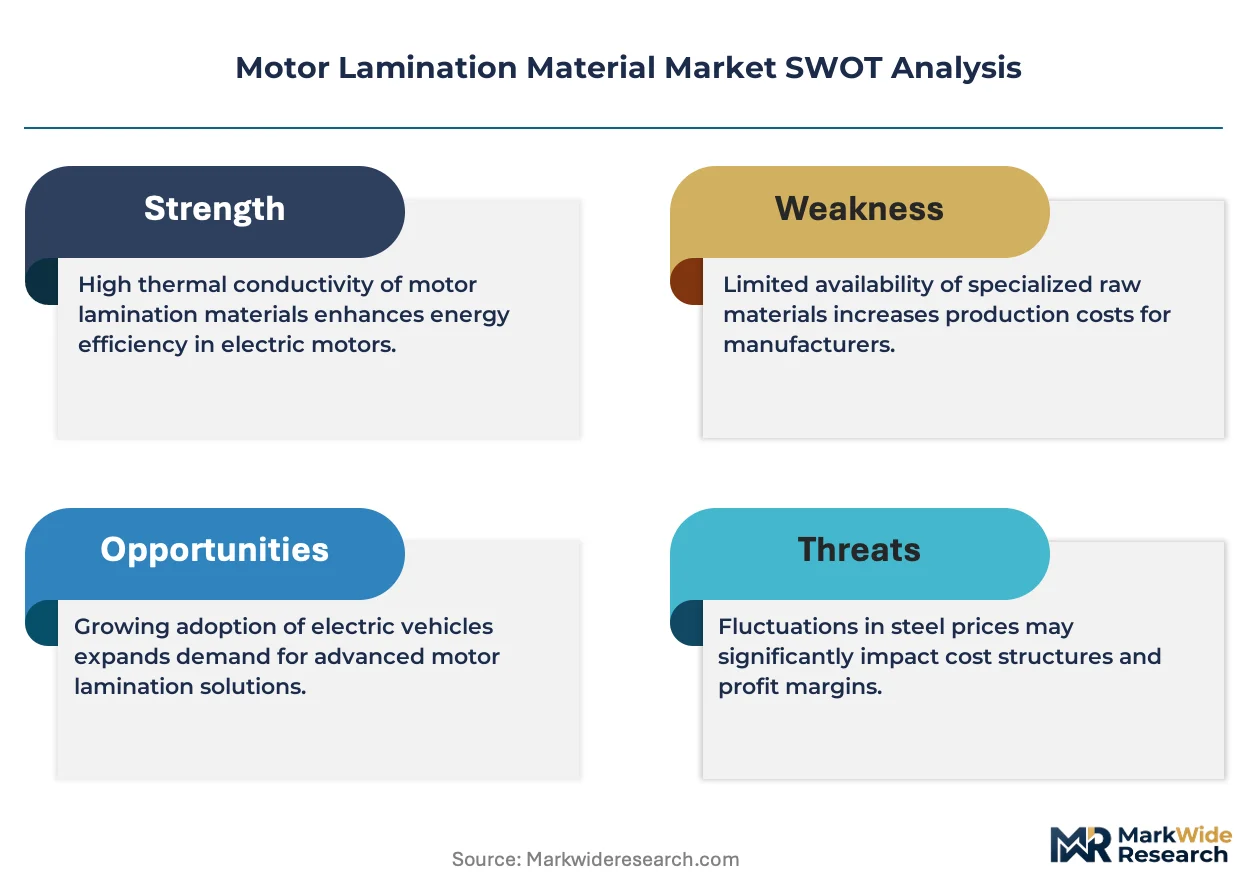
- Silicon Metal Price Volatility:Ferrosilicon alloy input costs fluctuate with Chinese smelter output curbs, compressing margin predictability for cold-rolled electrical steel producers.
- Amorphous Ribbon Supply Concentration:Metglas and limited Asian producers control liquid metal rapid-solidification capacity, creating single-source risk for transformer and premium motor designers specifying amorphous cores.
- Thin-Gauge Rolling Technical Limits:Sub-0.20 mm gauge production yields degrade exponentially, constraining volume scalability for ultra-thin silicon steel targeting high-frequency inverter applications.
Strategic Opportunities
- India Industrial Motor Upgrade Cycle:BIS efficiency labeling expansion and CEA mandatory standards are opening material substitution windows for electrical steel grades previously underutilized in domestic manufacturing.
- Amorphous-Steel Motor Hybrid Designs:Convergence of amorphous ribbon with conventional silicon steel in segmented stator cores is enabling core loss reduction without full material cost premiums.
- Direct Mill-to-Tier Procurement Channels:EV drivetrain producers are bypassing traditional steel service centers, creating volume commitment structures that stabilize capacity planning for integrated steelmakers.
Industry Challenges
- Magnetic Core Loss Certification Timelines:IEC 60404-8-3 and ASTM A343 test protocol alignment delays are extending material qualification cycles by 8-14 months for multi-regional motor platforms.
- Stamping Die Precision Engineering Scarcity:Tooling design for sub-0.25 mm gauge laminations requires specialized finite-element simulation expertise concentrated in Germany and Japan.
- Legacy Motor Remanufacturing Compatibility:Higher-efficiency lamination grades often retrofit poorly into existing stator geometries, complicating industrial motor upgrade pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Lamination Material Market |
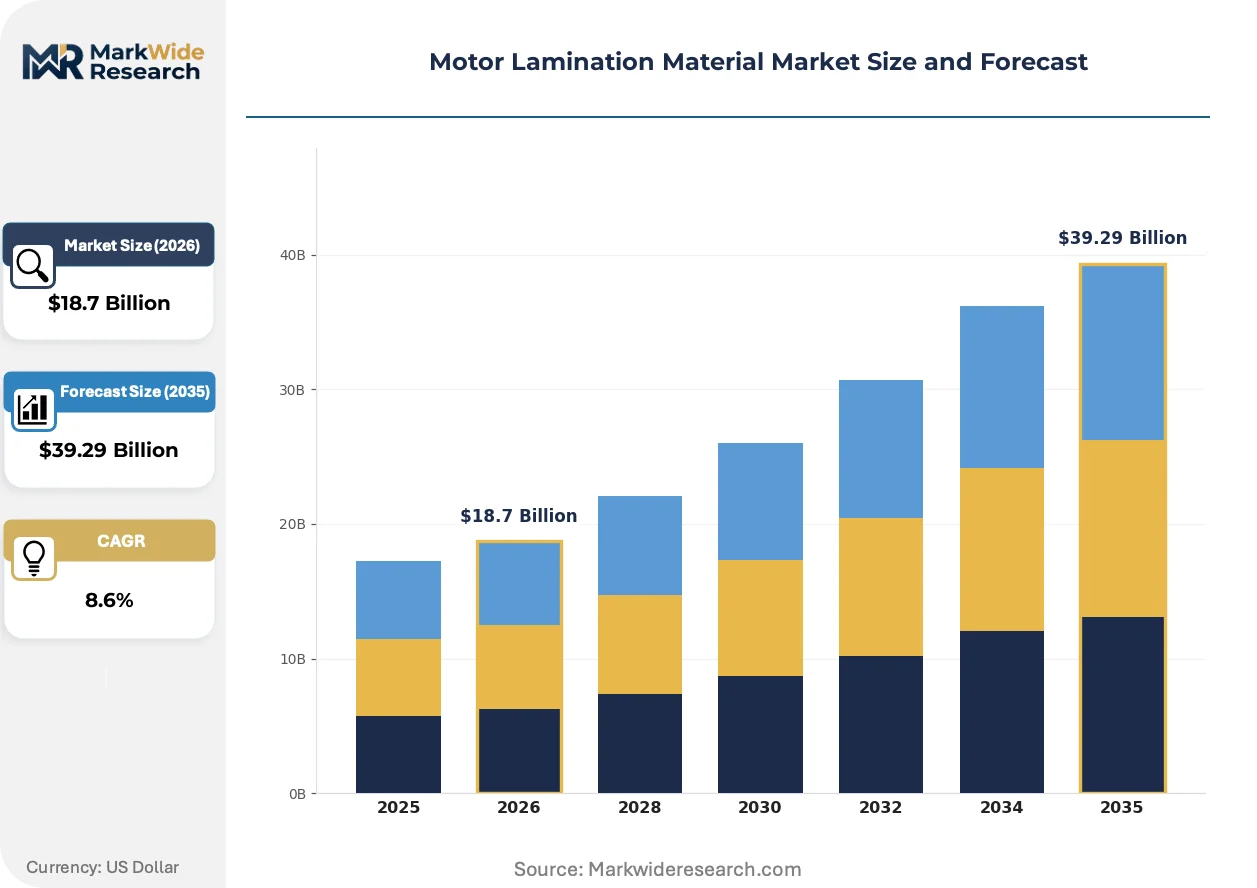
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Electrical Steel, Silicon Steel, Cold Rolled Steel, Amorphous Steel End User: Automotive, Industrial Machinery, Aerospace, Consumer Electronics Form Factor: Sheet, Stampings, Coils, Ferrites Application: Electric Motors, Transformers, Alternators, Generators |
| Companies Covered | ArcelorMittal, Baosteel, JFE Steel, POSCO, Nidec Corporation, Mitsubishi Electric Corporation, Tempel, EuroGroup Laminations, Metglas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Lamination Material Market Evolving Landscape
Laser scribing and mechanical stress relief techniques are redefining core loss performance boundaries without alloy composition changes. These process innovations are compressing the performance gap between standard and premium electrical steel grades.
Amorphous metal ribbon is integrating into high-frequency motor stators through segmented core architectures that isolate brittle amorphous layers from mechanical stress. EV inverter-driven traction motors above 10 kHz switching frequencies are adopting this hybrid construction fastest. The technology is integrating cost-competitive core loss performance into mass-production motor platforms previously limited to silicon steel.
Japan's METI Top Runner program is tightening industrial motor efficiency benchmarks through fiscal 2030, mandating IE4-equivalent performance for designated equipment categories. Japanese motor manufacturers are responding with accelerated thin-gauge silicon steel adoption and amorphous core pilot programs. This regulatory compression is propagating through supply chains into South Korean and Taiwanese motor export specifications.
Consolidated procurement by automotive OEMs is displacing fragmented industrial distributor networks for electrical steel sourcing. Tier-one drivetrain suppliers now negotiate multi-year volume commitments directly with ArcelorMittal, Baosteel, and JFE Steel production divisions. This channel restructuring is most visible in Germany's industrial motor corridor and South Korea's battery-motor integrated manufacturing zones.
Motor Lamination Material Market Segmentation
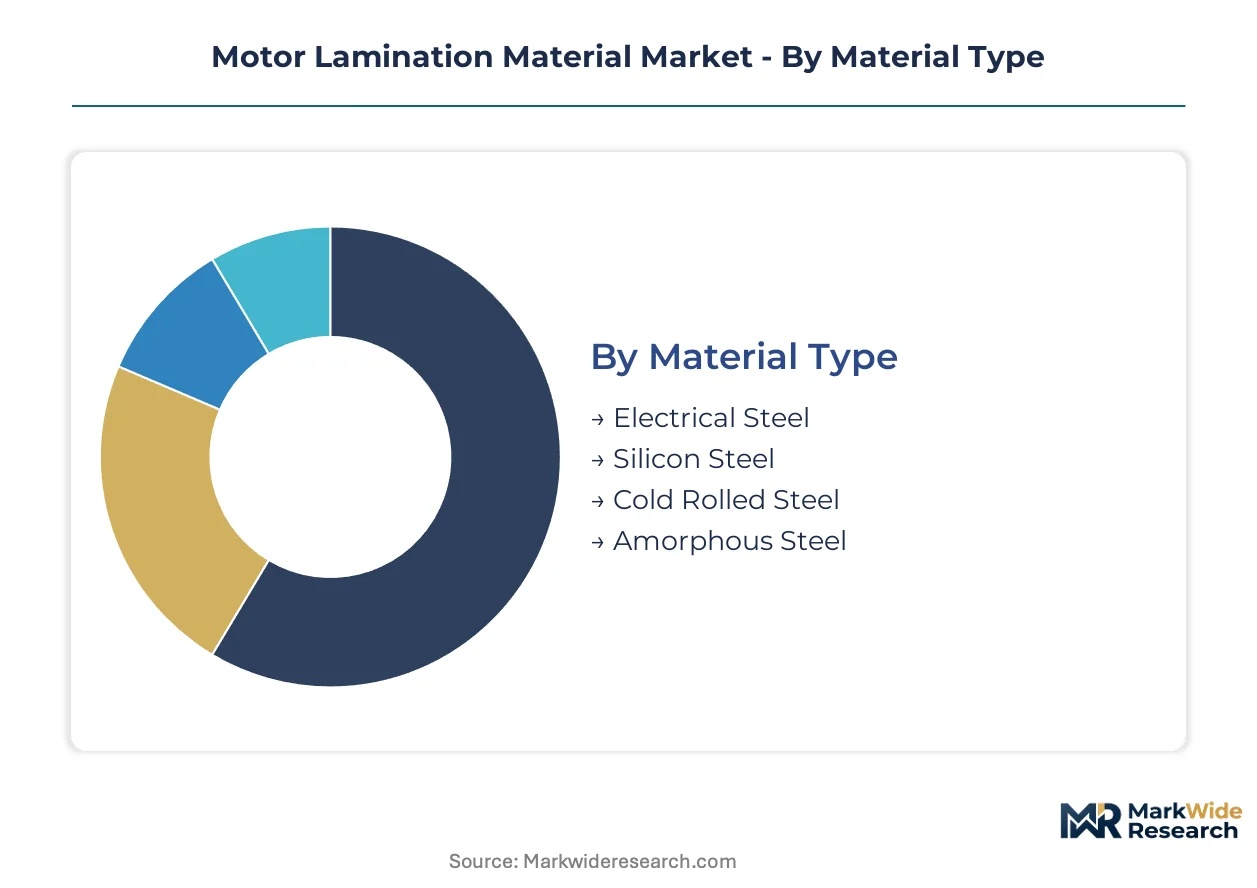
Motor lamination segmentation governs procurement strategy across fundamentally incompatible performance tiers. Material chemistry, end-use thermal requirements, and form factor constraints create distinct supply chains that rarely overlap in practice.
Material Type:
Customization intensity spans from commodity-grade cold-rolled steel to precision-tuned amorphous alloys requiring rapid-solidification manufacturing.
- Electrical Steel:Non-oriented silicon-alloyed grades between 0.35 mm and 0.65 mm thickness dominate industrial motor cores. Demand concentrates in Germany's Ruhr industrial corridor where EPA NEMA MG-1 efficiency mandates force substitution from standard to premium grades with higher silicon content and tighter core loss tolerances.
- Amorphous Steel:Iron-boron-silicon alloys produced through melt-spinning deliver core losses 70-80% below conventional electrical steel. Procurement clusters among South Korean EV battery-motor integrated manufacturers seeking high-frequency inverter compatibility, though Metglas supply concentration creates single-source vulnerability for transformer and traction motor designers.
- Silicon Steel:Oriented and non-oriented grades with 1.0% to 4.5% silicon content balance permeability against mechanical formability.
- Cold Rolled Steel:Low-carbon unalloyed grades serve cost-sensitive fractional horsepower motors where efficiency regulations permit higher core losses.
Most installed capacity flows through Electrical Steel. Expansion is steepest in Amorphous Steel.
End User:
Volume concentration versus margin capture splits sharply across customer categories, with automotive procurement power reshaping supplier relationships.
- Automotive:Traction motor laminations for battery electric and hybrid powertrains specify ultra-thin gauge silicon steel and amorphous hybrids. China's MIIT motor efficiency roadmaps and Japan's METI Top Runner program are converging on IE4-equivalent performance requirements that favor high-silicon grades in domestic and export manufacturing.
- Industrial Machinery:Pump, compressor, and conveyor motor cores consume standardized non-oriented electrical steel in high tonnages. India's BIS efficiency labeling expansion and CEA mandatory standards are opening substitution windows for grades previously underutilized in domestic manufacturing.
- Aerospace:High-reliability motor and generator cores demand specialized thin-gauge materials with extreme temperature stability.
- Consumer Electronics:Small motor laminations for appliances and power tools prioritize stamping yield over core loss minimization.
Automotive commands the steepest price premiums. Industrial Machinery moves the highest absolute tonnage.
Form Factor:
Processing stage at delivery determines logistics economics and tier-one supplier value-add capture.
- Sheet:Raw coil or cut-length electrical steel delivered to independent stampers and motor manufacturers. Automotive OEMs in South Korea and Germany are bypassing traditional steel service centers, negotiating direct mill procurement that stabilizes capacity planning for integrated producers.
- Stampings:Precision-cut laminations ready for core stacking eliminate downstream tooling investment. Stamping die precision engineering scarcity concentrates in Germany and Japan, creating capability bottlenecks for sub-0.25 mm gauge production.
- Coils:Continuous wound ribbon enables automated high-speed stamping lines at large motor manufacturers.
- Ferrites:Ceramic magnetic materials serve specialized high-frequency applications outside mainstream lamination supply chains.
Sheet dominates raw material flows. Stampings are climbing the fastest as OEMs internalize core manufacturing.
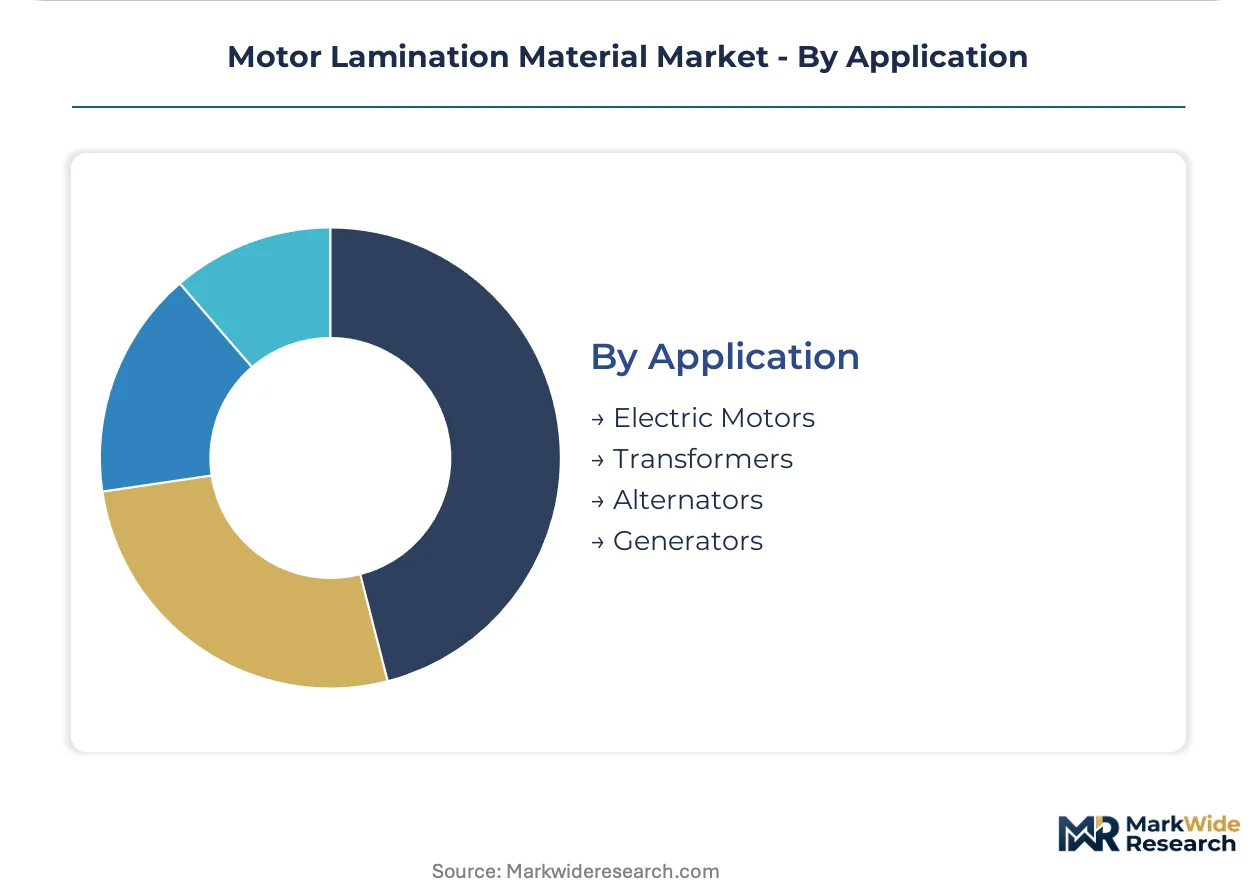
Application:
Magnetic circuit design requirements create irreconcilable material specifications across rotating and static equipment.
- Electric Motors:Rotating machinery laminations face mechanical stress and centrifugal loading that disqualifies brittle amorphous materials in conventional designs. Hybrid segmented stator architectures are emerging in Japan's METI-directed efficiency programs, isolating amorphous layers from mechanical stress while capturing core loss reduction.
- Transformers:Static core applications tolerate brittle amorphous ribbon without mechanical reliability concerns. Distribution transformer procurement in China and India is accelerating amorphous adoption where no-load loss regulations justify material cost premiums.
- Alternators:Automotive charging system laminations balance high-speed mechanical durability against efficiency.
- Generators:Utility-scale and industrial generation equipment specifications favor proven electrical steel grades with established IEC 60404-8-3 certification pathways.
Electric Motors absorb the widest material diversity. Transformers are gaining share fastest for amorphous steel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial motor corridor commands premium-grade procurement volumes while South Korea's EV battery-motor integrated zones drive amorphous steel qualification cycles, revealing how regulatory compression and powertrain electrification split geographic demand patterns.
United States
Industrial motor efficiency mandates from EPA NEMA MG-1 force manufacturers toward lower-loss electrical steel grades. The Department of Energy coordinates with NEMA on test protocol harmonization for multi-regional platforms. Manufacturing clusters in Ohio and Wisconsin concentrate stamping capacity for IE3 and IE4 motor tiers serving domestic industrial automation.
Germany
Ruhr industrial corridor demand centers on high-silicon non-oriented electrical steel for pump and compressor motor cores. EU Ecodesign Directive implementation tightens minimum efficiency tiers through 2027, accelerating material substitution from standard to premium grades. Stuttgart and Munich automotive engineering hubs anchor traction motor lamination procurement for export-oriented drivetrain suppliers.
China
MIIT motor efficiency roadmaps systematically retire IE2 classifications, creating sustained demand pull for thin-gauge silicon steel. Dual carbon goals compress industrial upgrade timelines across state-owned manufacturing enterprises. Yangtze River Delta and Pearl River Delta clusters integrate battery-motor production lines requiring high-frequency compatible lamination grades.
Japan
METI Top Runner program mandates IE4-equivalent performance for designated industrial equipment categories through fiscal 2030. Nagoya and Osaka manufacturing belts pilot amorphous-steel hybrid stator architectures for high-frequency inverter applications. JIS standard alignment with IEC 60404-8-3 accelerates material qualification for export motor platforms.
India
BIS efficiency labeling expansion and CEA mandatory standards open substitution windows for electrical steel grades previously underutilized in domestic manufacturing. Gujarat and Maharashtra industrial corridors absorb upgraded lamination materials for pump and fan motor applications. Domestic steel producers expand cold-rolled electrical steel capacity to capture import substitution opportunities.
Motor Lamination Material Market Competitive Landscape
European producers anchor premium-grade supply through integrated mill networks; East Asian specialists hold process expertise in ultra-thin gauge rolling and rapid-solidification metallurgy. The vendor base stratifies across three tiers: integrated steelmakers with captive hot-rolled feedstock, precision rolling specialists serving automotive qualification programs, and amorphous ribbon producers controlling liquid metal rapid-solidification capacity. Dominant competitive moves include direct mill-to-tier procurement channel establishment and hybrid material architecture development combining amorphous and crystalline steel segments.
Within the integrated steelmaker tier, ArcelorMittal and Baosteel occupy positions reflecting European and Chinese production gravity respectively. JFE Steel exemplifies the precision specialist archetype through its concentration on ultra-thin gauge products. These three entities represent the procurement focal points where automotive OEMs and industrial motor manufacturers concentrate multi-year volume commitments, displacing traditional steel service center intermediation.
| Leading Market Players |
|---|
| ArcelorMittal |
| Baosteel |
| JFE Steel |
| POSCO |
| Nidec Corporation |
| Mitsubishi Electric Corporation |
| Tempel |
| EuroGroup Laminations |
| Metglas |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement concentration is compressing pricing power toward integrated steelmakers capable of multi-year volume commitments. Tier-one drivetrain suppliers negotiate directly with ArcelorMittal, Baosteel, and JFE Steel production divisions, displacing traditional service center intermediation and flattening margin capture across distribution layers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard-grade electrical steel while premium thin-gauge products retain pricing power. Contract-based long-term offtake dominates automotive procurement, with price differentiation driven by silicon content certification and gauge thickness tolerances. Cost compression in industrial motor tiers is intensifying because Chinese smelter output curbs on ferrosilicon alloy inputs create margin unpredictability. Industrial machinery buyers exhibit highest price sensitivity; automotive traction motor programs show lowest sensitivity due to efficiency mandate compliance requirements.
Supply Chain Analysis
Remanufacturing flows for legacy industrial motor cores create secondary material loops that compete with virgin electrical steel demand in cost-sensitive segments. Primary supply concentrates in China, Japan, and Germany, with raw material dependencies on Australian iron ore, Chinese ferrosilicon alloy, and Japanese rolling mill equipment. Single-source vulnerability runs through Metglas liquid metal rapid-solidification capacity for amorphous ribbon. Distribution runs through direct mill-to-tier channels for automotive qualification programs and steel service centers for fragmented industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA NEMA MG-1 efficiency mandates and China's MIIT motor efficiency roadmaps create sustained demand pull for premium lamination grades. Compliance fragmentation across jurisdictions forces multi-regional qualification investments that favor capitalized incumbents.
For Market Incumbents: Extend thin-gauge rolling capability through equipment upgrades at European and East Asian production assets. ArcelorMittal and Baosteel should deepen backward integration into ferrosilicon alloy supply to defend margin position against Chinese smelter output volatility. JFE Steel's precision specialist positioning requires accelerated amorphous-steel hybrid architecture R&D to preempt emerging rapid-solidification entrants. For New Entrants and Emerging Players: Capture India's industrial motor upgrade cycle through BIS efficiency labeling alignment and localized cold-rolled electrical steel capacity partnerships. The most penetrable white space sits in sub-0.25 mm gauge stamping die engineering services, where German and Japanese capability scarcity creates bottlenecks. A go-to-market angle anchored in IEC 60404-8-3 test protocol consulting accelerates material qualification timelines for multi-regional motor platforms. For Investors and Strategic Acquirers: Integrated automotive drivetrain suppliers are the most active acquirer in this space, seeking captive lamination supply for battery-motor integrated manufacturing zones. Long-term viability hinges on regulatory compression sustaining IE4-equivalent performance requirements across major automotive export markets. Acquisition target archetypes include precision rolling specialists with automotive qualification credentials and rapid-solidification metallurgy firms outside Metglas supply concentration. The signal to watch is hybrid amorphous-silicon steel stator architecture adoption rates in Japanese METI-directed efficiency programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrosilicon Supply | Mitigates Chinese smelter output volatility compressing cold-rolled electrical steel margins. |
| Thin-Gauge Rolling Capacity Expansion | Addresses sub-0.20 mm gauge yield degradation constraining high-frequency inverter motor supply. |
| Amorphous-Steel Hybrid Architecture Development | Enables core loss reduction without full material cost premiums in EV traction motors. |
| Direct Mill-to-Tier Procurement Channel Establishment | Stabilizes capacity planning for integrated steelmakers serving South Korean and German automotive clusters. |
| IEC 60404-8-3 Certification Investment | Accelerates material qualification cycles delayed by ASTM protocol alignment gaps. |
Research Methodology
Bottom-up automotive and industrial machinery modeling reconciled against top-down steel mill capacity tracking forms the analytical core. Primary interviews with electrical steel procurement managers at Tier 1 drivetrain suppliers, motor manufacturer plant engineers, rolling mill technical directors, and amorphous ribbon application specialists combined with secondary validation from SEC steel producer filings, MIIT motor efficiency roadmaps, EPA NEMA MG-1 regulatory updates, and IEC 60404-8-3 test protocol documentation. Triangulation across these sources isolates volume and pricing assumptions.
Historical trendline analysis of electrical steel shipment patterns and motor efficiency regulation implementation timelines informed projection modeling. Segmentation dimensions include material chemistry tier, end-use vertical, gauge thickness specification, and regional regulatory cluster. CAGRs were derived from regression analysis of installed motor stock replacement cycles and EV powertrain penetration assumptions. Industry-specific forecast inputs incorporate ferrosilicon alloy price volatility indices and stamping die precision engineering capacity constraints.
Underlying measurement precision varies by segment; automotive traction motor demand carries tighter precision than fragmented industrial machinery replacement due to concentrated OEM procurement visibility. Forecasts reflect assumptions around EPA and MIIT efficiency mandate enforcement consistency, with revision triggers including amorphous ribbon supply disruption, sub-0.20 mm gauge rolling yield breakthroughs, or regional test protocol harmonization delays. Practitioners should monitor Japanese METI Top Runner program implementation pace and South Korean EV battery-motor integrated zone capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Powder Metallurgy Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Global Hot Rolled Coil Steel Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Colloidal Metal Particles Market
Metals
Galvanized Steel Market
Metals
Europe Aluminium Powder Market
Metals
Beryllium Copper Billet Market
Metals
South America Metal Finishing Market
Metals
Lithium Foil Market
Metals
Heat-Treated Steel Plates Market
Metals
Electrolytic Iron Market
Metals
Metallurgical Silicon Market
Metals
GCC Aluminium Powder Market
Metals
Copper Clad Aluminum Wire Market
Metals
Medium Carbon Steel Market