
 Tantalum and Niobium Material Market | 2026-2036
Tantalum and Niobium Material Market Size, Share, and Industry Trends Forecast 2026-2036
Tantalum and Niobium Material Market Insights
Capital-intensity divergence between integrated miners and downstream processors is redrawing competitive boundaries in tantalum and niobium supply. CBMM leverages captive pyrochlore reserves in Brazil to sustain low-cost ferroniobium output. Global Advanced Metals anchors premium capacitor-grade tantalum supply through Western Australian ore streams and in-house metallurgical refining.
Tantalum and niobium materials comprise refractory transition metals extracted primarily from tantalite-columbite ores and pyrochlore deposits, with tantalum exhibiting a melting point exceeding 3,000°C and niobium serving as a critical micro-alloying element in high-strength low-alloy steels. Powder forms command dominant volume share in electronics capacitor feedstock, while superalloy applications in aerospace represent the fastest-growing grade segment as jet engine manufacturers specify niobium-bearing nickel alloys for turbine blade thermal tolerance. Recycled grade supply is expanding as closed-loop recovery systems at aerospace machine shops reclaim tantalum from cutting waste.
REACH registration requirements in Europe mandate full supply chain disclosure for tantalum conflict minerals, while China's MEE enforces wastewater discharge limits on niobium separation facilities that elevate capital costs for non-integrated producers. The US SEC's conflict minerals rule and Dodd-Frank Section 1502 disclosure obligations shape sourcing transparency for defense contractors purchasing tantalum for missile guidance systems. Stakeholders must monitor evolving traceability mandates and carbon border adjustment mechanisms that will differentiate compliant from non-compliant material streams.
Market Dynamics
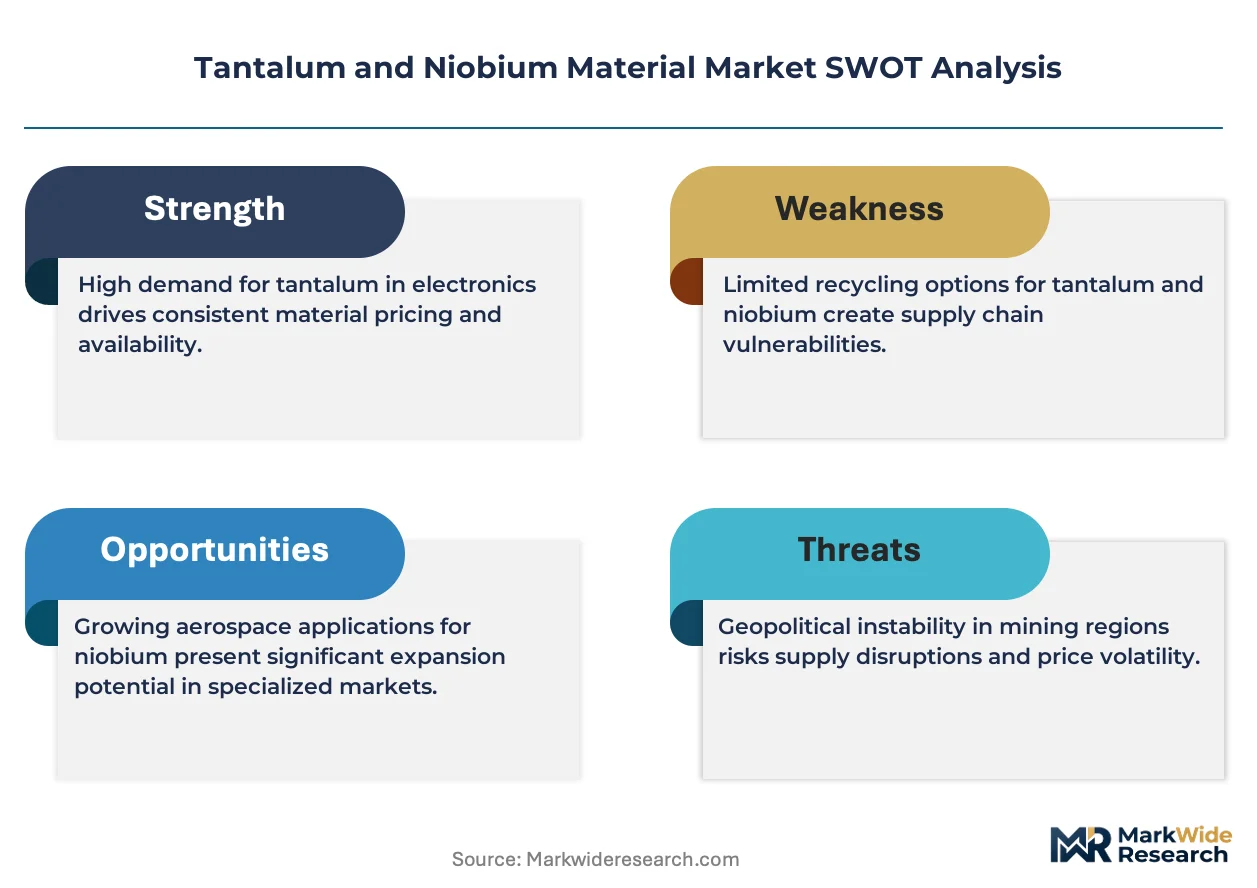
Environmental compliance costs at Chinese niobium separation facilities are compressing margins for non-integrated processors while consolidating supply around captive ore holders. This structural pressure is redrawing competitive boundaries between integrated miners and downstream metallurgical refiners.
Growth Catalysts
- Dual carbon goals:China's MEE wastewater discharge mandates are accelerating capital deployment into closed-loop niobium recovery systems. Integrated producers with captive pyrochlore reserves capture cost advantages over toll processors.
- Capacitor-grade tantalum powder:Electronics assemblers in Japan and South Korea are scaling long-term supply agreements for high-purity feedstock. Precision electronics and semiconductor supply chains anchor demand concentration.
- Superalloy specification shifts:Jet engine manufacturers are specifying niobium-bearing nickel alloys for turbine blade thermal tolerance. Aerospace machine shops are expanding closed-loop tantalum recovery from cutting waste.
Market Restraints
- Input cost volatility:Energy-intensive tantalum reduction processes expose processors to electricity price swings in hydro-dependent regions. Smelters without captive power face margin compression.
- Supply concentration risk:Ferroniobium output concentrates around Brazilian pyrochlore deposits. Disruption to rail or port infrastructure at single-source ore streams threatens alloy supply chains.
- Substitution pressure:Ceramic capacitors are capturing share in consumer electronics below 10V applications. Tantalum polymer capacitors defend position in high-reliability military and medical devices.
Strategic Opportunities
- Underpenetrated recycling infrastructure:Aerospace machining clusters in the United States and Germany lack standardized tantalum scrap aggregation networks. Closed-loop toll refining contracts could capture stranded waste streams.
- Regulatory tailwind from conflict minerals rules:The US SEC's Dodd-Frank Section 1502 disclosure obligations and EU REACH registration requirements are creating preference premiums for fully traceable tantalum supply. Compliant material streams command sourcing priority from defense contractors.
- Technology convergence:Additive manufacturing of niobium superalloy components is intersecting with powder atomization advances. Medical implant and satellite propulsion applications are emerging as qualification targets.
Industry Challenges
- Metallurgical talent scarcity:Refractory metal reduction and electron-beam melting require specialized pyrometallurgical expertise. Workforce pipelines from mining engineering programs are thinning.
- Certification timeline compression:Aerospace material qualification cycles for new niobium superalloy grades extend 18-36 months. Suppliers must fund qualification campaigns before revenue realization.
- Supply chain reconfiguration friction:Shifting from Chinese-processed niobium oxide to alternative separation facilities requires customer requalification. Defense prime contractors resist supplier changes mid-program.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tantalum and Niobium Material Market |
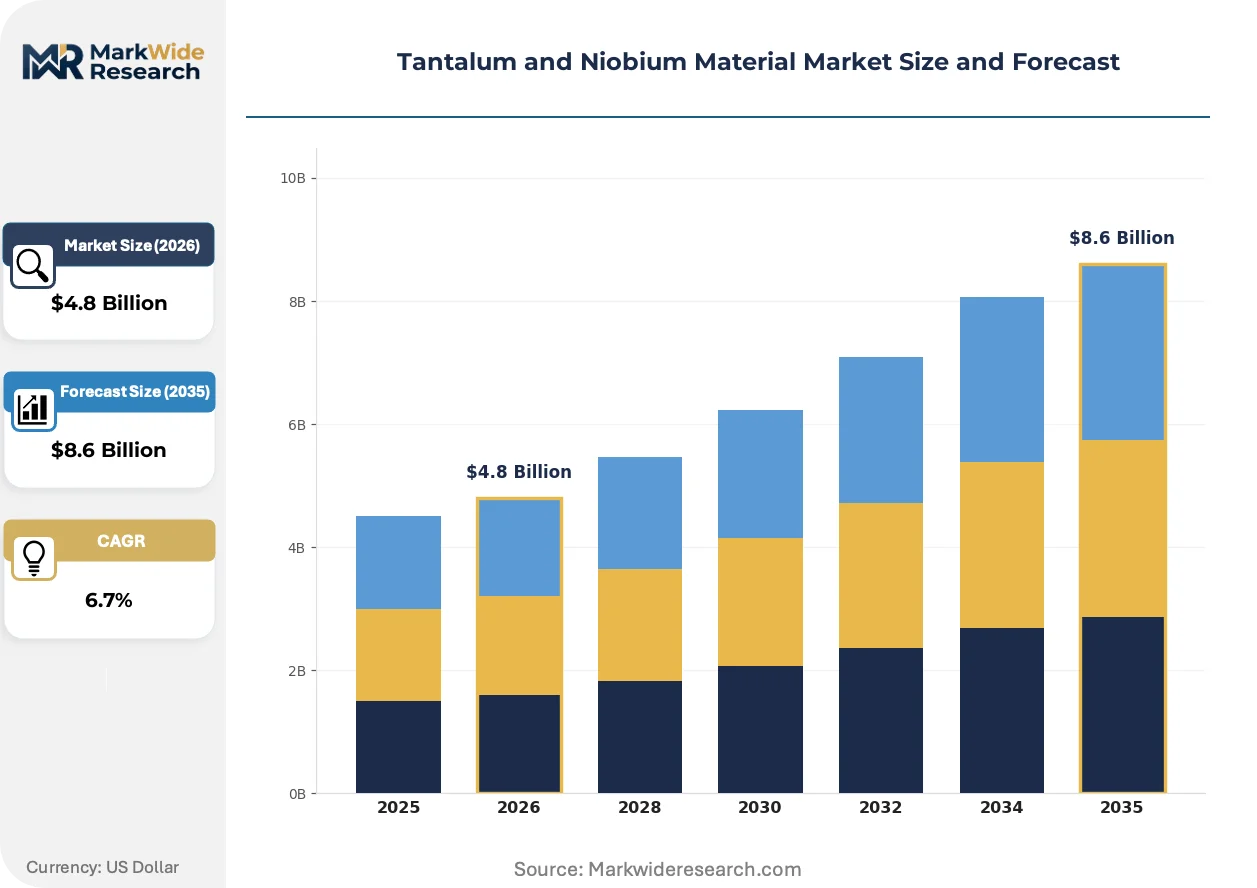
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Wire, Plate, Sheet, Foil Grade: High Purity, Standard Purity, Electrolytic, Recycled Application: Aerospace Components, Chemical Processing, Electronics, Carbide Tools, Superalloys End User: Manufacturers, Research Laboratories, Defense Contractors, Electronics Assemblers, Toolmakers |
| Companies Covered | Global Advanced Metals, JX Advanced Metals, CBMM, CMOC Group, Metallurgical Products, Niobec, ULBA Metallurgical Plant, Advanced Metallurgical Group, Mitsubishi Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tantalum and Niobium Material Market Trends and Innovations
Tantalum and niobium supply chains are restructuring around traceability mandates and powder metallurgy advances. Three converging developments are compressing traditional processing economics and rewiring procurement relationships.
Electrolytic tantalum capacitor manufacturing is displacing sintered anode production in high-frequency applications. Japanese electronics assemblers are adopting advanced powder morphology control for volumetric efficiency gains. This powder-grade specification shift is compressing demand for traditional wire and ingot forms in consumer electronics.
REACH registration requirements in Europe are mandating full supply chain disclosure for tantalum conflict minerals. ECHA's substance evaluation protocols are elevating documentation burdens for non-integrated traders. Defense contractors purchasing tantalum for missile guidance systems are consolidating sourcing around vertically integrated Western Australian ore streams to satisfy audit requirements.
Long-term offtake contracting is replacing spot market purchasing among capacitor-grade tantalum buyers. Electronics manufacturers in South Korea and Japan are negotiating multi-year supply agreements directly with metallurgical refiners. This disintermediation is visible most acutely in precision electronics supply chains where qualification timelines deter supplier switching.
Tantalum and Niobium Material Market Segmentation
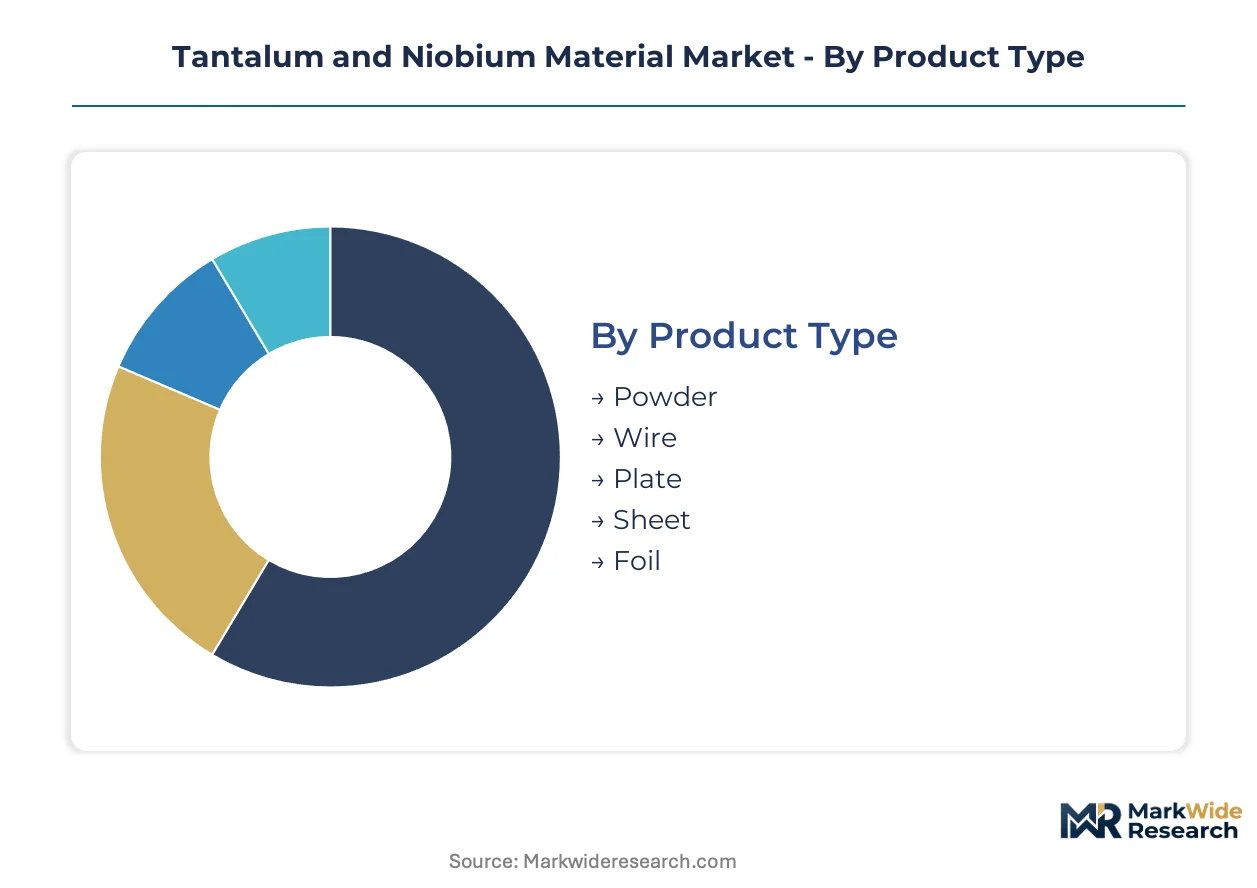
Segmentation in tantalum and niobium materials reflects divergent processing economics and end-use qualification requirements. Powder specifications for capacitor anodes command fundamentally different metallurgical workflows than superalloy-grade niobium additions. Understanding these segment boundaries reveals where captive ore holders extract margin premiums versus where toll processors face commoditization pressure.
Product Type:
Geographic demand spread varies sharply across product forms, with powder and wire anchored in Japanese and South Korean electronics clusters while plate and sheet serve domestic aerospace fabricators in the United States and Germany.
- Powder:Capacitor-grade tantalum powder requires controlled particle morphology for volumetric efficiency in surface-mount components. Japanese electronics assemblers in Osaka and Nagoya prefectures dominate procurement of high-purity feedstock, driven by multi-year supply agreements that lock in metallurgical qualification. South Korean semiconductor packaging houses are scaling parallel offtake contracts.
- Wire:Electron-beam melted tantalum wire serves surgical implant and chemical processing applications demanding corrosion resistance. German precision wire drawers in North Rhine-Westphalia and Connecticut-based medical device suppliers represent concentrated demand pockets.
- Plate:Hot-rolled niobium plate targets chemical processing equipment for sulfuric acid service. Fabricators in Texas and Louisiana anchor North American consumption.
- Sheet:Cold-rolled tantalum sheet supplies aerospace heat shields and vacuum furnace components. California and Washington state machine shops drive qualification requirements.
- Foil:Ultra-thin tantalum foil serves explosive bonding and medical radiation shielding. Niche volumes concentrate in Massachusetts and Swiss research corridors.
Powder commands the established base. The steepest expansion runs through wire as medical implant specifications proliferate.
Grade:
Cost tier differentiation separates captive-refined material from toll-processed alternatives, with integrated miners capturing margin premiums in high-purity segments while recyclers undercut standard grades.
- High Purity:3N5 and 4N tantalum grades demand electron-beam melting and multiple vacuum arc remelts to achieve semiconductor-grade cleanliness. Western Australian ore streams processed through in-house metallurgical refiners satisfy Japanese capacitor manufacturers' traceability mandates.
- Standard Purity:2N5 tantalum and technical-grade niobium serve carbide tool and structural steel applications. Brazilian pyrochlore-based ferroniobium dominates this tier through CBMM's captive reserve economics.
- Electrolytic:Electrolytic capacitor-grade tantalum requires specific oxide thickness control for voltage rating stability. This grade sits at the intersection of powder metallurgy and anodization process control.
- Recycled:Aerospace machining scrap recovery yields tantalum suitable for non-aerospace applications. German and American machine shops lack standardized aggregation networks.
Standard purity commands the established base. The steepest expansion runs through recycled grades as closed-loop recovery systems mature.
Application:
Volume concentration in electronics capacitors contrasts with margin concentration in aerospace superalloys, where qualification timelines deter supplier switching.
- Electronics:Surface-mount tantalum capacitors for smartphones and automotive control modules represent the dominant volume sink. Japanese and South Korean assemblers specify powder morphology for volumetric efficiency gains.
- Superalloys:Niobium-bearing nickel alloys for turbine blade thermal tolerance command premium pricing through aerospace material qualification cycles. GE Aerospace and Rolls-Royce specifications drive grade requirements.
- Aerospace Components:Tantalum fasteners and heat shields serve hypersonic vehicle programs. Defense prime contractors in California and Virginia consolidate sourcing around qualified Western suppliers.
- Chemical Processing:Tantalum-lined reactors and heat exchangers handle corrosive media in sulfuric acid production. Gulf Coast petrochemical complexes anchor North American demand.
- Carbide Tools:Niobium carbide additions improve cemented carbide toughness for metal cutting. Toolmakers in Ohio and Illinois specify consistent grain size distribution.
Electronics commands the established base. The steepest expansion runs through superalloys as jet engine manufacturers specify higher thermal tolerance alloys.
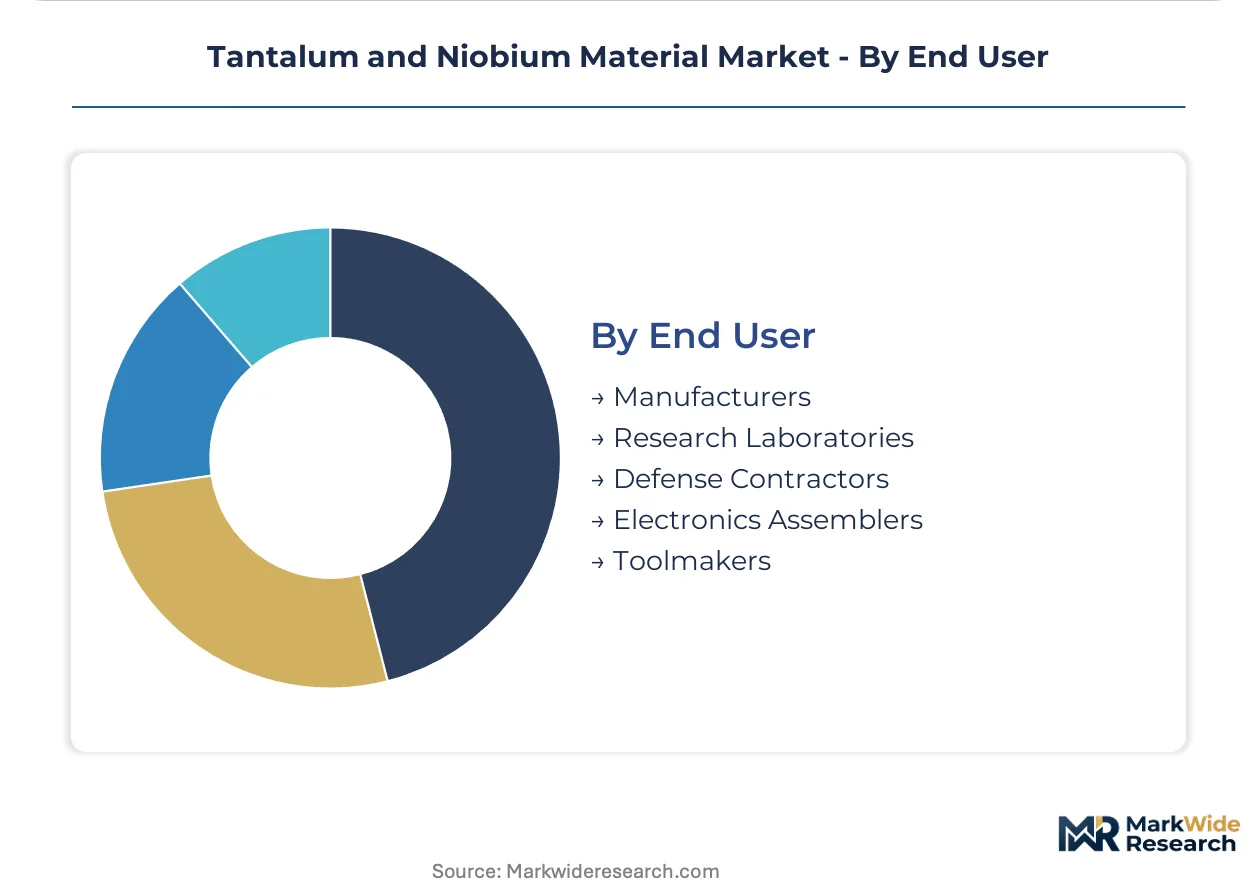
End User:
Customer type determines procurement modality, with defense contractors demanding full supply chain disclosure while toolmakers prioritize spot price minimization.
- Electronics Assemblers:Murata, TDK, and Samsung Electro-Mechanics negotiate multi-year tantalum powder offtake agreements directly with metallurgical refiners. Disintermediation eliminates trader margins.
- Defense Contractors:Lockheed Martin and Raytheon face US SEC conflict minerals disclosure obligations for tantalum in missile guidance systems. Sourcing concentrates on Western Australian ore streams with audit documentation.
- Manufacturers:Steel mills and chemical equipment fabricators purchase ferroniobium and tantalum mill products through distributor networks. Price sensitivity dominates procurement criteria.
- Research Laboratories:CERN, MIT, and Max Planck Institutes require small-batch high-purity material for superconducting applications. Custom specifications justify premium pricing.
- Toolmakers:Kennametal and Sandvik Coromant source niobium carbide through carbide powder suppliers. Volume scale enables long-term contract pricing.
Manufacturers command the established base. The steepest expansion runs through defense contractors as traceability mandates tighten procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in tantalum and niobium materials tilt heavily toward ore-exporting nations supplying refined product to Asian electronics clusters. Brazil's pyrochlore dominance and Australia's tantalite streams anchor primary supply, while Japan and South Korea concentrate downstream demand.
Brazil
CBMM's captive pyrochlore reserves in Minas Gerais sustain the world's lowest-cost ferroniobium output. ANVISA environmental licensing and state-level mining codes govern extraction expansion. São Paulo-based metallurgical clusters process ore into alloy feedstock for export.
Australia
Western Australian tantalite deposits supply capacitor-grade feedstock to Japanese and South Korean electronics assemblers. The country's national mining regulator enforces rehabilitation bonds for greenfield projects. Perth-Greenbushes processing corridors anchor Western supply chain documentation.
China
Niobium separation facilities in Jiangxi and Hunan provinces face tightening MEE wastewater discharge mandates under dual carbon goals. GB standards for rare earth processing elevate capital costs for non-integrated toll processors. Yangtze River Delta capacitor manufacturers scale high-purity tantalum powder purchases.
Japan
Osaka and Nagoya prefectures concentrate precision electronics demand for 3N5 and 4N tantalum grades. METI supply chain security initiatives promote long-term offtake contracting with Western Australian ore streams. Kansai-based assemblers specify powder morphology for volumetric efficiency.
South Korea
Samsung Electro-Mechanics and affiliated packaging houses negotiate multi-year tantalum powder agreements directly with metallurgical refiners. MFDS traceability requirements intersect with US SEC conflict minerals disclosure for defense-adjacent supply chains. Seoul-Incheon semiconductor corridors anchor procurement concentration.
Tantalum and Niobium Material Market Competitive Landscape
Concentration sits with integrated miners controlling captive ore reserves. CBMM's pyrochlore dominance and Global Advanced Metals' Western Australian ore streams define the upstream tier, while toll processors face margin compression from environmental compliance costs. Three archetypes populate the landscape: captive reserve holders, in-house metallurgical refiners, and non-integrated toll processors. Strategic moves center on backward integration into ore control and disintermediation of trader networks through direct offtake contracting.
Among integrated reserve-based producers, CBMM exemplifies the captive pyrochlore archetype with Brazilian ore economics. Global Advanced Metals occupies a position as a Western Australian ore holder with in-house refining capability. JX Advanced Metals sits within the Asian downstream tier, representing metallurgical processing concentration near demand clusters.
| Leading Market Players |
|---|
| Global Advanced Metals |
| JX Advanced Metals |
| CBMM |
| CMOC Group |
| Metallurgical Products |
| Niobec |
| ULBA Metallurgical Plant |
| Advanced Metallurgical Group |
| Mitsubishi Materials |
| Others |
Pricing and Supply Chain Analysis
CBMM's 85% capacity utilization at Araxá pyrochlore complexes anchors global ferroniobium price floors through ore-grade economies unavailable to toll processors. This scale concentration compresses margins for non-integrated Chinese separation facilities while elevating premiums for Western Australian tantalite streams with audit-ready traceability documentation.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for capacitor-grade tantalum powder, with Japanese electronics assemblers locking in multi-year supply agreements to secure metallurgical qualification. Price differentiation hinges on certification grade — REACH-registered 4N tantalum commands sourcing priority from defense contractors — and volume scale, where Murata and TDK leverage procurement concentration for preferential terms. Cost compression in standard-purity ferroniobium is intensifying because Brazilian captive-reserve economics undercut Chinese toll processors facing MEE wastewater compliance upgrades. Steel mills and chemical equipment fabricators exhibit highest price sensitivity, prioritizing spot price minimization over supply chain disclosure.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for Brazilian ferroniobium shipments to European steel mills, compressing delivered margins against rail-dependent domestic Chinese alloy supply. Geographic supply concentrates in Brazil, Australia, and China — CBMM's pyrochlore reserves, Western Australian tantalite deposits, and Jiangxi niobium separation facilities respectively. Raw material dependencies rest on pyrochlore ore grades, tantalite-columbite concentrate specifications, and sodium hydroxide reagent availability. Single-source vulnerability threatens alloy supply chains, as disruption to Minas Gerais rail infrastructure would cascade through global ferroniobium availability. Distribution runs through metallurgical refiner direct contracting with capacitor manufacturers, disintermediating trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat, where REACH conflict-minerals documentation and aerospace qualification timelines create switching costs that deter supplier substitution mid-program.
For Market Incumbents: Consolidate backward integration into captive ore reserves to defend margin position against environmental compliance cost inflation at Chinese toll processors. CBMM's pyrochlore economics and Global Advanced Metals' Western Australian ore streams exemplify the leverage available from upstream control. Capacity addition in low-carbon hydropower regions — Quebec, Norway, New Zealand — addresses electricity price volatility exposure in tantalum reduction. Certification investment in closed-loop scrap recovery systems captures aerospace machining waste streams before recyclers aggregate standardized networks. For New Entrants and Emerging Players: Anchor in underpenetrated tantalum scrap aggregation infrastructure across German and American aerospace machining clusters, where closed-loop toll refining contracts could capture stranded waste streams lacking standardized collection networks. The most penetrable segment sits at recycled-grade supply for non-aerospace applications, where qualification timelines compress versus virgin material pathways. Go-to-market execution should emphasize direct offtake contracting with capacitor manufacturers seeking dual-source diversification beyond Japanese and South Korean incumbent relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated miners with captive pyrochlore reserves and in-house metallurgical refining capability, where long-term offtake agreements with defense contractors and electronics assemblers generate contracted visibility. Acquisition targets should screen for Western Australian ore streams with established traceability documentation and electron-beam melting infrastructure. The signal to watch is qualification timeline compression for new niobium superalloy grades, where suppliers funding 18-36 month aerospace campaigns before revenue realization face working capital intensity that may force asset sales.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Ore Reserves | CBMM's pyrochlore economics demonstrate margin capture unavailable to toll processors facing MEE compliance costs. |
| Long-term Supply Agreement with Electronics Assemblers | Murata and Samsung Electro-Mechanics negotiate multi-year offtake contracts that disintermediate trader margins. |
| Closed-loop Scrap Recovery System Deployment | Aerospace machine shops in Connecticut and Bavaria lack standardized tantalum waste aggregation networks. |
| Certification Investment for REACH Traceability | Defense contractors consolidate sourcing around Western Australian ore streams with audit-ready documentation. |
| Capacity Expansion in Low-carbon Power Regions | Quebec hydropower addresses electricity price volatility exposure in energy-intensive tantalum reduction processes. |
Research Methodology
The analysis maps capacitor-grade powder, superalloy-grade niobium, and recycled material streams, each validated through primary interviews with tantalum reduction plant managers, aerospace procurement officers at GE Aerospace and Rolls-Royce, capacitor manufacturer supply chain directors, and rare earth separation facility engineers. Secondary sources include SEC conflict minerals filings under Dodd-Frank Section 1502, ECHA REACH registration databases, Brazilian ANVISA environmental licensing records, and Chinese MEE wastewater discharge compliance reports. Bottom-up capacity and consumption estimates triangulate against top-down trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product form, purity grade, application, and end-user procurement modality, with CAGRs derived from elasticity-adjusted demand modeling and supply-side capacity constraints. Industry-specific forecast inputs include jet engine superalloy specification shifts and electronics capacitor volumetric efficiency requirements.
Material uncertainties — regulatory timeline acceleration for carbon border adjustments, pyrochlore reserve depletion rates, and aerospace qualification cycle extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions about environmental compliance cost trajectories and traceability mandate enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Extrusion Market
Metals
Silver Sulphate Market
Metals
North America Iron Casting Market
Metals
Rhodium Market
Metals
Metallurgical Coal Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Global Aluminum Extruded Products Market
Metals
Metal Forging Parts Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Aluminum Tubes Market
Metals
Tinplate Market
Metals
Platinum Group Metals Market
Metals
Rare Earth Metals Market
Metals
Aluminium Conductors Market
Metals
Iron Casting Market
Metals
Middle-East and Africa Metal Finishing Market