
 High Purity Pig Iron Market | 2026-2036
High Purity Pig Iron Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Pig Iron Market Intelligence
The ISO 945-1 standard for microstructural classification of cast irons is reorganizing the competitive landscape for suppliers. Kobe Steel Ltd. leverages its extensive metallurgical expertise to produce specialized grades for demanding automotive and industrial applications. Eramet Group differentiates through its focus on high-performance materials required by the aerospace and energy sectors. Concurrently, High Purity Iron Inc. positions itself on technology leadership, developing novel processing techniques to achieve ultra-low impurity levels.
High purity pig iron is a primary ferrous material with exceptionally low levels of sulfur, phosphorus, and other tramp elements. Its main purpose is to act as a clean iron unit in the production of high-quality ductile iron castings and specialty steels. The Electronics Grade, though a niche volume segment, commands the highest margins, while Metallurgical Grade material supports the bulk of industrial applications. Applications in automotive components are expanding faster than those in the more traditional construction materials sector.
Regulatory frameworks including the EU’s REACH directive and China's GB standards for material composition govern market access and product specifications. In parallel, US Environmental Protection Agency (EPA) rules on smelter emissions influence production costs and technology adoption. Producers face a strategic choice between investing in costly refining upgrades for global markets or serving regional niches with standard grades.
Market Dynamics
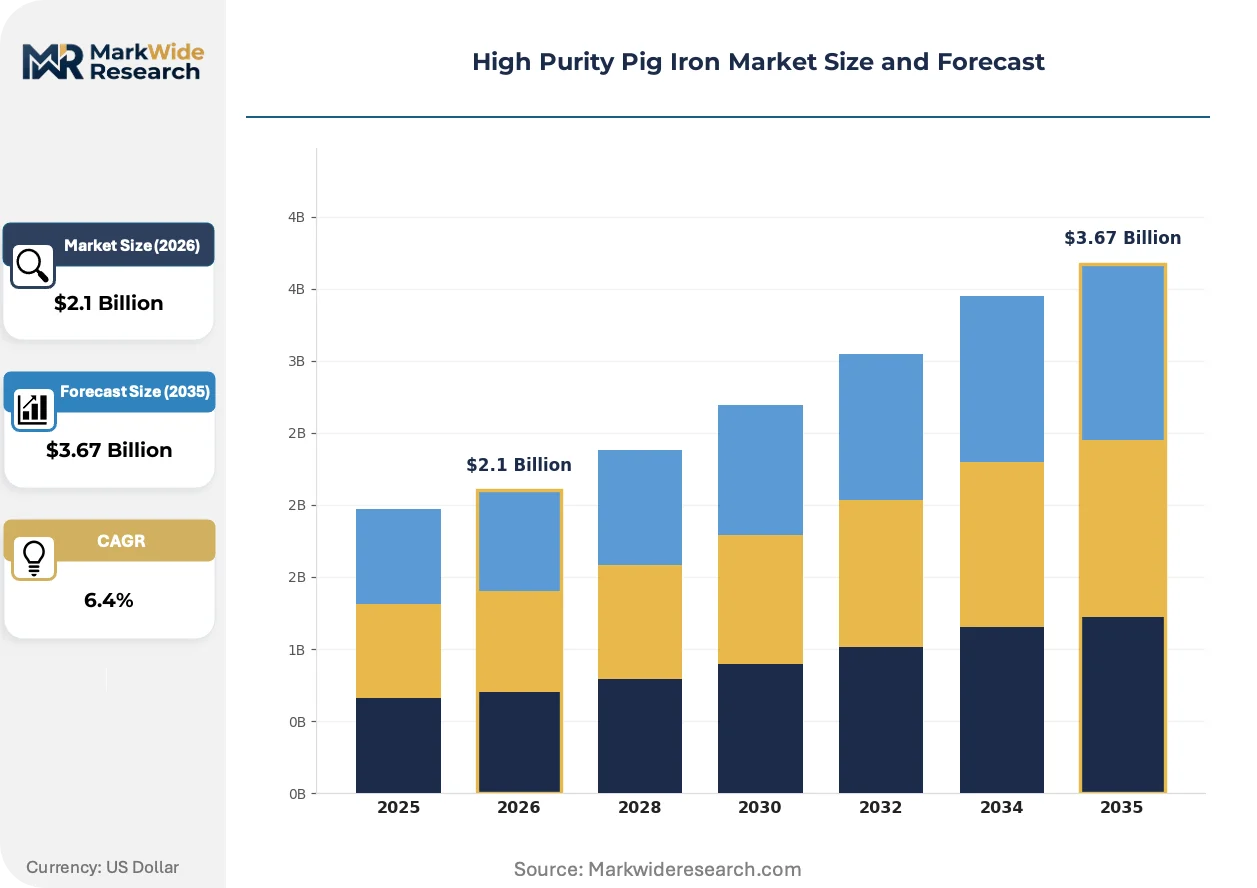
The convergence of advanced electric arc furnace technologies and stringent material specifications from the electric vehicle sector is the central force. This dual pressure accelerates the market's shift from standard grades toward specialized, high-purity formulations for demanding applications.
Growth Catalysts
- Electric Vehicle Production:The automotive sector's demand for high-strength, lightweight castings for EVs propels consumption of HPPI to produce superior ductile iron.
- Foundry Emissions Compliance:US EPA rules on smelter emissions incentivize using HPPI, as its low impurity profile helps foundries meet stringent air quality standards.
- Advanced EAF Technology:The adoption of modern electric arc furnaces allows steelmakers to leverage HPPI for producing higher quality steel with fewer refining steps.
Market Restraints
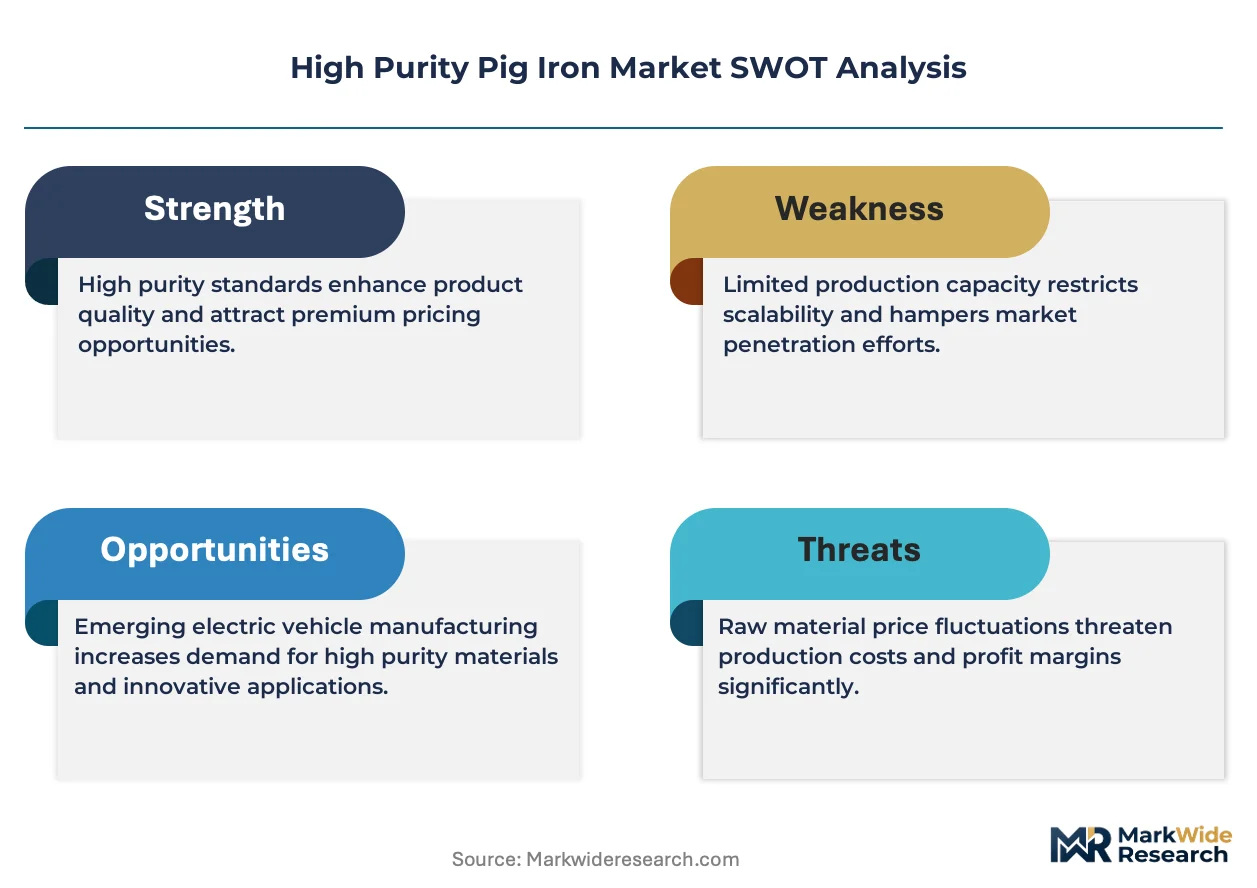
- Energy-Intensive Refining:High energy consumption and complex refining processes create a significant cost premium for HPPI over standard ferrous inputs like scrap metal.
- Limited Producer Base:Supply of top-tier grades is concentrated among a few producers, exposing consumers to price volatility and potential supply chain disruptions.
- Scrap Metal Competition:Advanced scrap sorting offers a lower-cost substitute for less demanding applications, capping HPPI adoption in non-specialty steel and iron grades.
Strategic Opportunities
- Aerospace and Energy Alloys:Developing HPPI grades for high-performance alloys in aerospace and energy sectors opens new, high-margin markets beyond automotive.
- Foundry Hubs in India:Targeting India's growing specialized foundry industry with grades for its automotive and industrial sectors represents a key geographic opportunity.
- Electronics Grade Materials:Expanding production of ultra-pure electronics grade iron for magnetic components offers a path to higher value capture despite its niche volume.
Industry Challenges
- Capital-Intensive Upgrades:Upgrading smelters to produce higher purity grades while complying with environmental rules from the EPA and EU REACH demands significant capital expenditure.
- Metallurgical Talent Gap:A scarcity of metallurgists with expertise in ultra-pure refining and ductile iron casting constrains production expansion and innovation in new grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Pig Iron Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foundry Pig Iron, SG Iron, Ductile Iron, Grey Iron Grade: Electronics Grade, Metallurgical Grade, Industrial Grade, Commercial Grade Application: Automotive Components, Construction Materials, Machinery Manufacturing, Electronics Production End User: Manufacturers, Industrial End Users, Construction Firms, Automotive OEMs |
| Companies Covered | QIT-Fer et Titane, Tronox Holdings plc, High Purity Iron Inc., Saraf Group, Mineral-Loy, Ironveld Plc, Richards Bay Minerals, Kobe Steel Ltd., Eramet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Pig Iron Market Strategic Shifts & Innovations
A focus on material science innovation to meet precise performance criteria in end-use applications is reshaping the market. This shift prioritizes custom-grade development over bulk commodity production, linking supplier success to deep metallurgical expertise.
Advanced electric arc furnace (EAF) technology enables precise control over melting, maximizing the benefit of clean iron units. Specialty steelmakers and high-end iron foundries, particularly in Germany's automotive supply chain, are rapidly adopting these systems. This technological shift is bifurcating the market, separating premium, EAF-optimized HPPI grades from standard materials used in less advanced production environments.
The European Union’s REACH directive, alongside China's GB standards for material composition, imposes stringent controls on tramp elements. This forces foundries to meticulously document and manage the chemical makeup of their products to maintain market access. Consequently, Metallurgical Grade HPPI is increasingly used as a strategic input to ensure compliance and simplify the certification process for finished goods.
Specification-driven procurement is displacing traditional volume-based purchasing, especially within the automotive components sector. Foundries now source specific HPPI grades that guarantee final casting properties like ductility and tensile strength, aligning with ISO 945-1 microstructural requirements. This behavior is most visible within Germany’s specialized foundry industry, which supplies Europe’s leading automotive manufacturers.
High Purity Pig Iron Market Segmentation
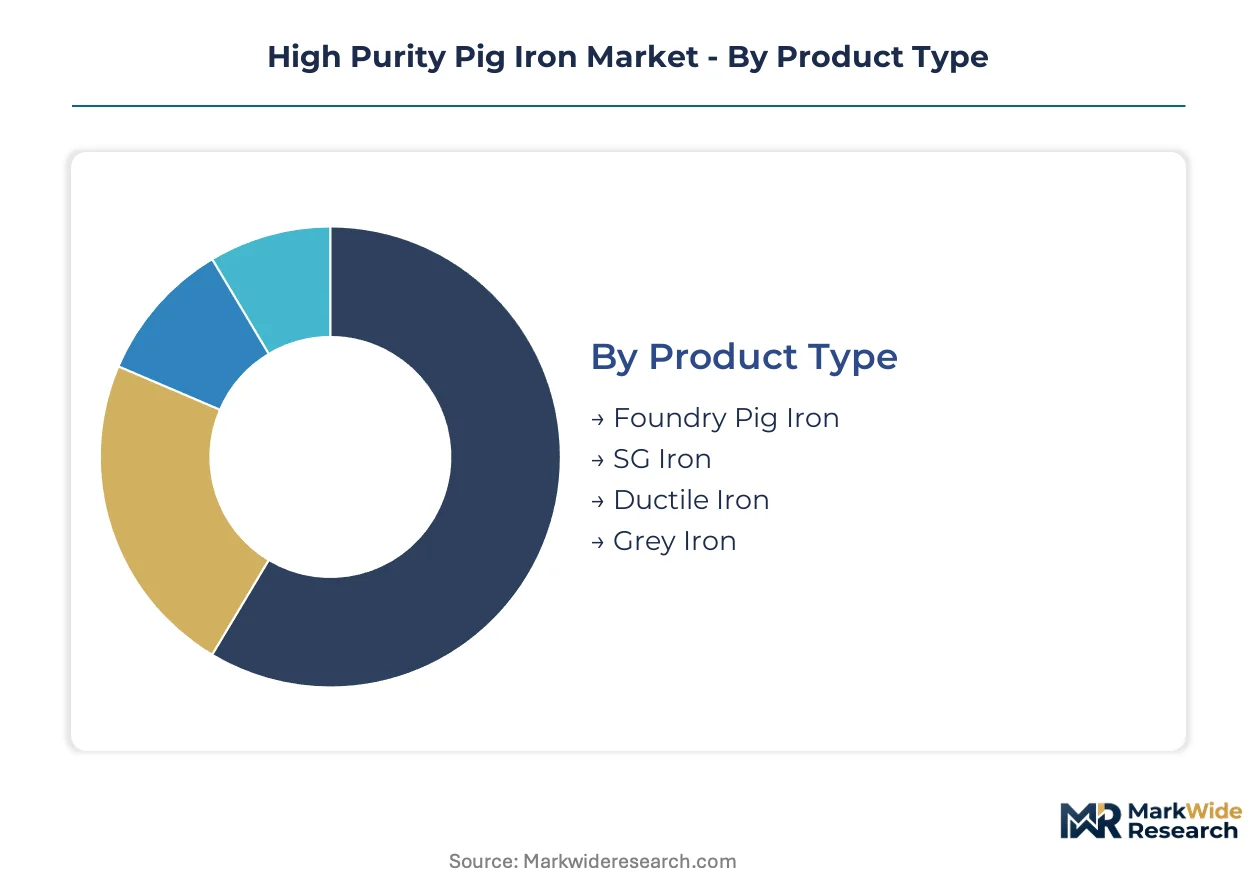
This market's segmentation highlights the diverse requirements for high purity pig iron, from specialized metallurgical properties to specific end-use applications. Understanding these distinct categories allows producers to align their refining processes and product offerings with precise customer needs. Each segment reflects unique performance demands and market dynamics.
Product Type:
The product type segmentation reveals how different high purity pig iron formulations are tailored for either domestic consumption within specialized foundries or for export to specific industrial hubs.
- Foundry Pig Iron:This material features specific carbon and silicon content with ultra-low tramp elements, optimized for remelting in foundry operations. Demand concentrates within Germany's specialized foundry industry, driven by the need for superior ductile iron castings in automotive applications.
- SG Iron:This refers to spheroidal graphite iron, a high-strength cast iron produced using HPPI as a clean iron unit.
- Ductile Iron:Characterized by its nodular graphite structure, ductile iron offers high tensile strength, elongation, and impact resistance for critical components. US heavy machinery manufacturing drives demand, requiring durable and reliable materials for robust equipment parts.
- Grey Iron:This traditional cast iron contains flake graphite, providing good machinability and damping properties for various industrial uses.
Foundry Pig Iron holds the largest share; momentum sits with Ductile Iron.
Grade:
Different grades of high purity pig iron reflect a tiered cost structure, with refining intensity directly influencing pricing and market accessibility.
- Electronics Grade:This grade boasts ultra-low levels of all impurities, achieving exceptional magnetic permeability and electrical conductivity. Japan's specialized electronics sector drives demand, requiring materials for miniaturized and high-performance magnetic components.
- Metallurgical Grade:Designed for high-quality steel and ductile iron production, this grade offers controlled impurity levels suitable for advanced casting and steelmaking processes. China's specialty steel mills drive demand, ensuring compliance with stringent GB standards for material composition.
- Industrial Grade:This grade provides a balanced purity profile, suitable for a broad range of general industrial casting and metalworking applications.
- Commercial Grade:Representing the baseline purity, this material serves less demanding applications where cost-effectiveness is a primary consideration.
The level of purity directly correlates with the value proposition, with ultra-low impurity grades commanding premium pricing.
Application:
Application segments highlight the contrasting dynamics between high-volume, traditional uses and high-value, performance-driven sectors.
- Automotive Components:This application utilizes HPPI for high-strength, lightweight ductile iron castings in chassis, braking systems, and powertrain components. Germany's automotive supply chain drives demand, particularly for electric vehicle light-weighting initiatives.
- Construction Materials:This segment encompasses cast iron pipes, fittings, and structural elements requiring durable and long-lasting materials.
- Machinery Manufacturing:HPPI forms critical components for wear-resistant parts, heavy equipment, and precision machinery requiring robust and reliable materials. US industrial equipment producers drive demand, seeking superior performance for their heavy-duty products.
- Electronics Production:This niche application leverages ultra-pure iron for magnetic cores, specialized sensors, and other high-performance electronic components.
Innovation in material science is propelling growth in advanced applications, while traditional uses maintain stable demand.
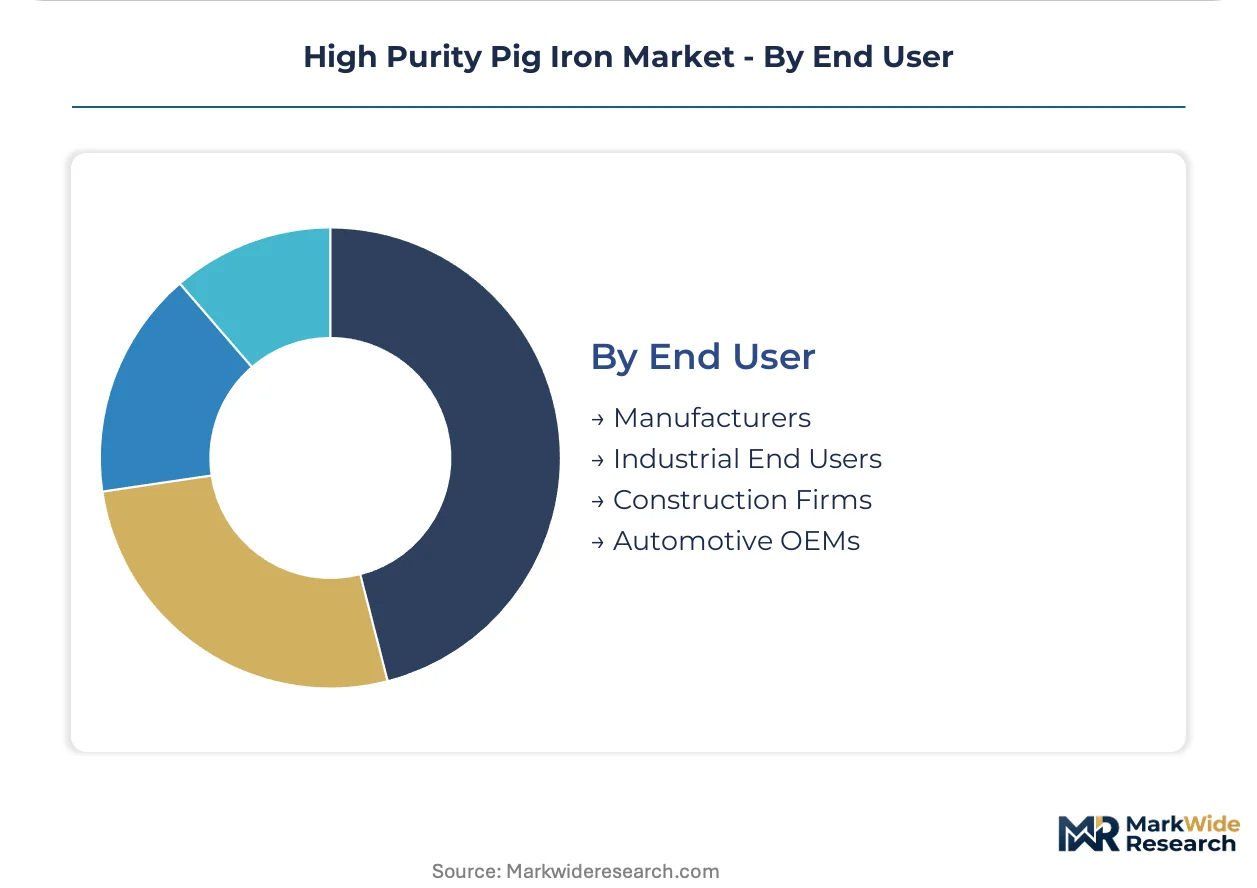
End User:
End-user categories delineate the distinct roles within the industrial supply chain, from primary material processors to final product assemblers.
- Manufacturers:This group includes foundries and specialty steel producers who convert HPPI into finished or semi-finished goods for various industries. European foundries adopting advanced EAF technologies drive demand, meeting stringent material specifications for end products.
- Industrial End Users:These companies integrate HPPI-derived components into their own production processes across diverse industrial sectors.
- Construction Firms:These entities procure ductile iron pipes, cast iron fittings, and other HPPI-based materials for infrastructure development and building projects. India's urban development projects drive demand, fueled by expanding infrastructure needs.
- Automotive OEMs:These original equipment manufacturers directly purchase HPPI-based components for integration into vehicle assembly lines.
The value chain sees varied engagement, from raw material conversion by manufacturers to direct component integration by automotive OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity pig iron demand concentrates among specialized foundries and advanced steelmakers globally, driven by stringent material specifications. This material is crucial for producing high-quality ductile iron castings and specialty steels across various industries. Regional dynamics reflect distinct regulatory environments and end-use application priorities.
Germany
High-purity pig iron demand in Germany is driven by its specialized foundry industry and electric vehicle manufacturing. The EU’s REACH directive imposes stringent material composition controls, influencing procurement patterns for ferrous inputs. Foundries in Baden-Württemberg are rapidly adopting advanced EAF technologies for premium ductile iron castings and components.
China
China's specialty steel mills drive high-purity pig iron demand for high-quality steel and ductile iron production. Stringent GB standards for material composition dictate purity requirements for local producers. The Yangtze River Delta region sees significant investment in advanced casting and steelmaking processes, leveraging cleaner iron units.
Japan
Japan's specialized electronics sector demands ultra-low impurity high-purity pig iron for miniaturized magnetic components. METI initiatives support advanced material research to meet precise performance criteria in high-tech industries. Tokyo's high-tech manufacturing hubs focus on innovation in electronic grade iron production and application development.
United States
US heavy machinery manufacturing requires durable high-purity pig iron-based components for robust equipment parts. EPA rules on smelter emissions incentivize foundries to use cleaner inputs like high-purity pig iron to meet air quality standards. Industrial equipment producers in the Midwest are a key demand center for high-performance ductile iron.
India
India's growing specialized foundry industry, particularly for automotive and industrial sectors, consumes high-purity pig iron. The PLI scheme encourages domestic manufacturing and material quality improvements in key sectors. Urban development projects in Maharashtra are driving demand for high-purity pig iron in durable construction materials.
High Purity Pig Iron Market Key Industry Players
Player mix skews toward specialized metallurgical firms and integrated materials producers, reflecting the technical demands of high-purity pig iron. The market structure features a tiered landscape, separating niche ultra-purity suppliers from bulk industrial providers. Strategic archetypes include technology innovators focusing on novel processing techniques, raw material specialists leveraging captive resources, and regional market leaders serving localized demand. Dominant competitive moves involve capital-intensive refining upgrades to meet stringent purity standards and strategic partnerships for end-use application development in sectors like electric vehicles.
Specialists in advanced metallurgical solutions, such as Kobe Steel Ltd., exemplify a focus on extensive metallurgical expertise for demanding automotive and industrial applications. Eramet Group anchors the high-performance materials segment, particularly serving the aerospace and energy sectors with differentiated offerings that meet stringent material specifications. High Purity Iron Inc. occupies a position as a technology leader, developing novel processing techniques to achieve ultra-low impurity levels required by advanced industries. These companies collectively represent the market's drive towards specialized, high-value material solutions.
| Leading Market Players |
|---|
| QIT-Fer et Titane |
| Tronox Holdings plc |
| High Purity Iron Inc. |
| Saraf Group |
| Mineral-Loy |
| Ironveld Plc |
| Richards Bay Minerals |
| Kobe Steel Ltd. |
| Eramet Group |
| Others |
Cost & Logistics Intelligence
The extended lead times for specialized high purity pig iron grades, often exceeding six months, directly reflect a concentrated supply chain and grant producers significant pricing power. This dynamic underscores the critical role of material availability in determining market value for advanced ferrous inputs.
Pricing Analysis
Cost-plus contract patterns, frequently indexed to energy and raw material prices, govern pricing for high purity pig iron. Price differentiation stems from the stringent purity levels required for Electronics Grade material and specific ISO 945-1 certification for automotive applications. Pricing softness runs through Commercial Grade material due to competition from less demanding substitutes. Japan's specialized electronics sector exhibits the least price sensitivity for ultra-pure grades.
Supply Chain Analysis
Inbound logistics costs, particularly for intercontinental shipping of bulk materials, influence the landed price of high purity pig iron. Geographic supply concentrates among a few producers in China, Germany, and South Africa. The market relies on consistent access to high-quality iron ore and stable energy inputs for electric arc furnaces. Limited producer base represents a structural supply chain risk. Direct contracts with specialized foundries and steel mills form the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits within a cyclical recovery, driven by renewed investment in the automotive sector and the accelerating transition to electric vehicles.
For Market Incumbents:Fortify core market share by investing in advanced EAF technology upgrades to achieve ultra-low impurity levels, countering scrap metal competition. Strategic partnerships with automotive OEMs for next-generation EV components can mitigate margin pressure. Focus R&D efforts on material science innovations for high-performance alloys. Invest in capacity additions for specialized grades within key European foundry hubs.
For New Entrants and Emerging Players:Lead with novel processing techniques to target white-space opportunities in aerospace and energy alloys, where material specifications are exceptionally stringent. India's growing specialized foundry industry, particularly for its automotive and industrial sectors, represents a highly penetrable geographic segment. A go-to-market angle emphasizing technology leadership and custom-grade development can differentiate offerings.
For Investors and Strategic Acquirers:Long-term, this sits as a specialized materials play because demand is driven by non-substitutable performance requirements in high-tech sectors. Technology innovators with proprietary refining processes and strong intellectual property represent attractive acquisition archetypes. The signal to watch is the expansion of advanced EAF technology adoption beyond Germany's automotive supply chain.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses growing demand for specialized HPPI grades in Germany's automotive sector. |
| Green Manufacturing Transition | Ensures compliance with US EPA and EU REACH environmental regulations for smelter emissions. |
| Technology Licensing | Accelerates adoption of novel processing techniques for ultra-low impurity iron production. |
| Joint Venture | Secures long-term supply relationships with automotive OEMs for critical EV components. |
| Long-term Supply Agreement | Provides stability for electronics manufacturers requiring ultra-pure magnetic components. |
Research Approach
A spread of perspectives from metallurgical engineers, foundry managers, automotive component designers, and regulatory compliance officers converged on the working assumptions for this analysis. Primary interviews were combined with secondary validation using industry association reports, government material standards (GB, ISO), corporate financial filings, and patent databases. This approach enabled comprehensive bottom-up and top-down triangulation.
The analysis modeled segmentation dimensions including product type, grade, application, end-user, and regional automotive production trends. CAGRs were derived from historical growth rates and projected demand drivers over the projection horizon. Electric vehicle production forecasts and global steel production volumes served as key industry-specific forecast inputs across the modeling period.
Forecasts assume regulatory continuity in EU REACH, US EPA, and China GB standards; material policy shifts would require re-modeling. Energy price volatility and raw material supply disruptions represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Colloidal Metal Particles Market
Metals
Copper Wire Market
Metals
Global Aluminum Extruded Products Market
Metals
North America Electrical Steel Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Metal Powder Market
Metals
Global Duplex Stainless Steel Market
Metals
Global Brass Rods Market
Metals
Brazil Aluminum Market
Metals
Global Chromium Market
Metals
Ore Metals Market
Metals
Magnesium Metal Market
Metals
Vietnam Aluminum Market
Metals
Steel Long Products Market
Metals
Global Oxygen-Free Copper Market
Metals
Global Copper Market