
 Polysiloxane Market | 2026-2036
Polysiloxane Market Size, Share, and Industry Trends Forecast 2026-2036
Polysiloxane Market Outlook
Aftermarket service revenue in silicone formulation technical support is narrowing as producers bundle application engineering with bulk material contracts. Wacker Chemie AG anchors its position through backward integration into silicon metal production. Dow leverages integrated siloxane capacity across North American and European manufacturing sites. Momentive Performance Materials Inc. specializes in medical-grade and electronics-grade silicone portfolios that command specification-driven procurement.
Polysiloxanes are polymeric organosilicon compounds with repeating siloxane (Si-O-Si) backbones, typically synthesized via hydrolysis and condensation of chlorosilanes, valued for thermal stability from -60°C to 250°C and dielectric properties. Silicone rubber dominates volume consumption in automotive gaskets and wire insulation where heat resistance is non-negotiable. Silicone oil carries margin concentration in personal care and pharmaceutical formulations requiring low surface tension and biocompatibility. Silane applications in adhesion promotion and surface modification represent the fastest-expanding chemistry segment as composite manufacturing intensifies across transportation sectors.
EPA oversight of volatile organic compound emissions from silicone coatings and sealants shapes product reformulation priorities in the United States. REACH registration requirements and the EU F-Gas Regulation constrain fluorinated silicone alternatives while redirecting investment toward non-fluorinated high-performance grades. China's GB standards and MEE environmental compliance protocols are tightening effluent controls at siloxane monomer plants. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets and maintain cross-border product registrations.
Market Dynamics
Automotive electrification is compressing thermal management material specifications, forcing silicone rubber suppliers to co-develop battery pack solutions with OEM engineering teams rather than selling commodity formulations.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases are redirecting HVAC and refrigeration manufacturers toward non-fluorinated silicone elastomers for sealing and gasket applications.
- China:Dual carbon goals and NEV production mandates are accelerating silicone adoption in electric vehicle battery modules and power electronics thermal interface materials.
- Silane chemistry:Advanced adhesion promoters for carbon fiber composites are penetrating aerospace and wind turbine manufacturing as lightweighting intensifies across transportation sectors.
Market Restraints
- Silicon metal price volatility:Energy-intensive carbothermic reduction of quartz concentrates feedstock costs in regions with unstable electricity pricing.
- Supply concentration:High-purity siloxane monomer production clusters in China's Jiangsu and Zhejiang provinces, creating geographic risk exposure for European and North American compounders.
- REACH registration costs:ECHA data requirements for low-volume specialty silanes impose disproportionate compliance burdens on mid-tier European formulators.
Strategic Opportunities
- India:PLI scheme incentives for electronics manufacturing are attracting silicone thermal pad and encapsulant suppliers to establish local compounding operations.
- Medical-grade liquid silicone rubber:ISO 13485-certified cleanroom production for implantable devices remains undersupplied relative to diagnostic equipment demand growth.
- Digital distribution platforms:Technical data sheet repositories and formulation calculators are compressing traditional distributor technical service roles in North American industrial procurement.
Industry Challenges
- Process engineering talent:Siloxane polymerization reactor operation requires specialized expertise that aging workforces in German and US manufacturing hubs struggle to replenish.
- Cleanroom certification timelines:USP Class VI and ISO 10993 biocompatibility testing protocols extend medical silicone qualification cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysiloxane Market |
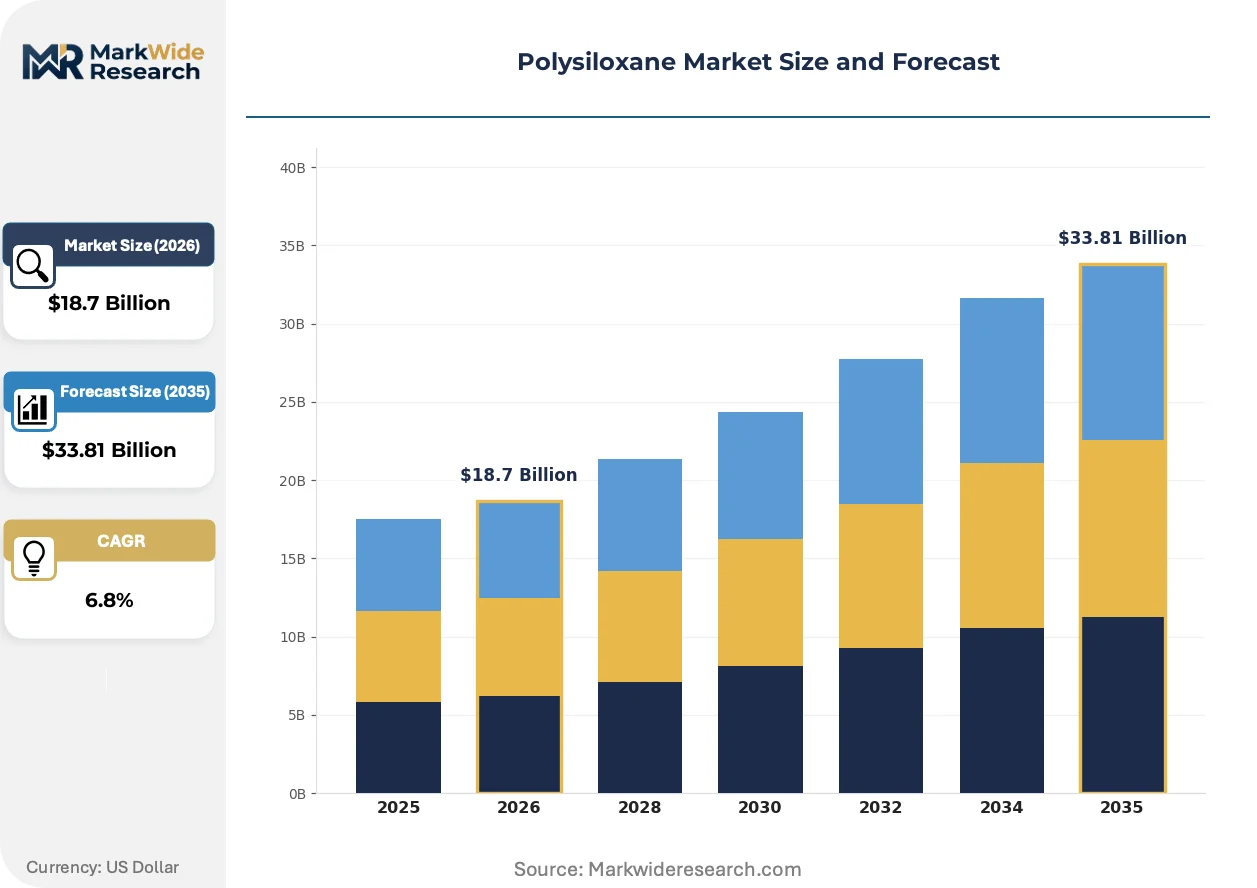
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Rubber, Silicone Oil, Silicone Resin, Silane End Use Industry: Aerospace, Automotive, Electronics, Textiles Application: Coatings, Sealants, Adhesives, Personal Care Form: Liquid, Solid, Gel, Powder |
| Companies Covered | Evonik Industries AG, Akzo Nobel N.V., Wacker Chemie AG, The Sherwin-Williams Company, PPG Industries, Inc., Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials Inc., 3M, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysiloxane Market Strategic Shifts
Material science convergence with digital manufacturing is redefining how silicone formulations are specified, tested, and supplied across industrial value chains.
Self-healing silicone elastomers incorporating dynamic covalent bond chemistry are hybridizing conventional thermal management materials with autonomous repair functionality. Automotive battery pack engineers at European OEMs are piloting these formulations for module-to-module gap fillers. The technology is hybridizing product lifecycle expectations by extending service intervals and reducing warranty exposure for thermal interface materials.
REACH authorization procedures for cyclic siloxanes (D4, D5, D6) are forcing reformulation of personal care and household products across European supply chains. Downstream brand owners are accelerating substitution timelines ahead of regulatory deadlines. Cosmetics and cleaning product manufacturers are most affected, with several major formulators advancing non-cyclic silicone alternatives through safety assessments.
Specification-driven procurement is consolidating buying power among tier-one automotive and electronics OEMs, compressing margins for standard-grade silicone rubber suppliers. Technical service bundling with material contracts is displacing standalone formulation consulting revenue streams. This consolidation is most visible in German automotive supply chains, where platform standardization across EV architectures reduces approved vendor lists for thermal management materials.
Polysiloxane Market Segmentation
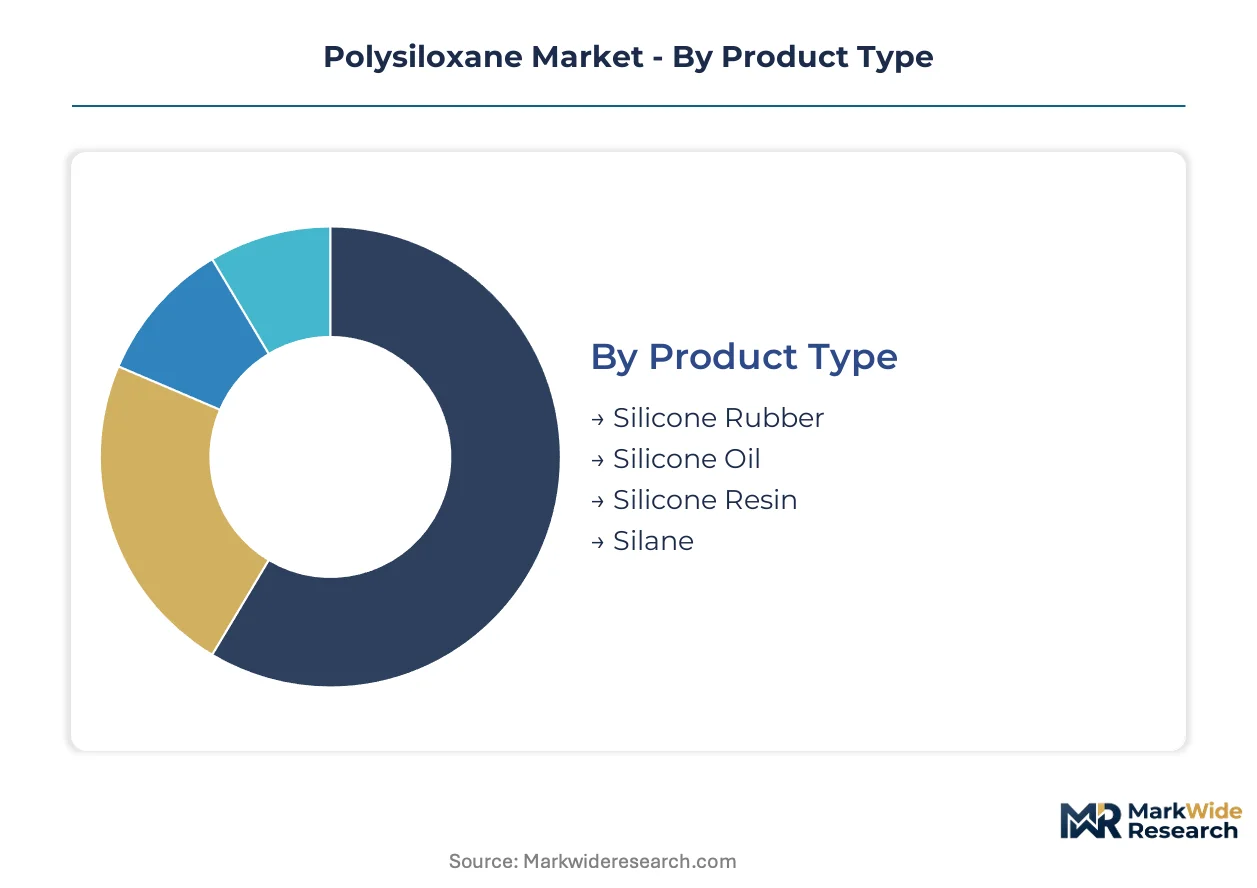
Segmentation in polysiloxanes reveals divergent margin profiles across chemistry families and end-use specifications. Formulation complexity and certification requirements create distinct competitive arenas that reward specialization over commodity scale.
Product Type:
Cycle times vary dramatically across silicone chemistries, with silane intermediates turning inventory fastest while medical-grade silicone rubber compounds age through extended qualification protocols.
- Silicone Rubber:High-viscosity elastomers vulcanized through peroxide or platinum-catalyzed crosslinking dominate automotive gaskets and wire insulation. Automotive electrification in Germany and China is compressing thermal management specifications and forcing co-development partnerships with OEM engineering teams.
- Silane:Organofunctional silicones serve as adhesion promoters and surface modifiers for carbon fiber composites. Wind turbine manufacturing in Denmark and aerospace production in France are driving specification intensity for advanced coupling agents.
- Silicone Oil:Low-viscosity fluids valued for thermal stability and dielectric properties concentrate in personal care and pharmaceutical formulations.
- Silicone Resin:Three-dimensional crosslinked polymers provide weather resistance in architectural coatings and high-temperature electrical insulation.
Silicone rubber anchors the volume base while silane chemistry gains share at the steepest rate.
End Use Industry:
Margin tiers separate specification-driven sectors from price-sensitive commodity applications, with medical and aerospace commanding certification premiums over industrial segments.
- Automotive:Battery thermal interface materials and high-voltage wire insulation represent the fastest-expanding demand cluster. NEV production mandates under China's dual carbon goals are accelerating silicone adoption in power electronics encapsulation and module gap fillers.
- Electronics:Thermal pads, conformal coatings, and encapsulants for semiconductor packaging require ultra-low ionic purity. India's PLI scheme incentives are attracting local compounding operations for smartphone and server component supply chains.
- Aerospace:Fire-resistant sealants and composite adhesion systems for airframe lightweighting carry extended qualification cycles and limited qualified supplier pools.
- Textiles:Softening agents and water-repellent finishes for technical fabrics compete on cost efficiency in high-volume garment processing.
Electronics commands the steepest pricing premiums while automotive delivers the fastest volume expansion trajectory.
Application:
Customer procurement patterns bifurcate between specification-locked industrial contracts and formulation-flexible consumer product channels.
- Sealants:Elastomeric joint fillers for construction and transportation infrastructure require weathering resistance certification. EU F-Gas Regulation restrictions are redirecting HVAC manufacturers toward non-fluorinated silicone elastomers for refrigeration system gaskets.
- Adhesives:Structural bonding systems for transportation composites and electronics assembly demand precise rheology control and thermal conductivity tuning.
- Coatings:Protective layers for industrial equipment and architectural surfaces balance durability against volatile organic compound compliance under EPA oversight.
- Personal Care:Hair conditioning agents and skin emollients face REACH authorization pressure on cyclic siloxanes D4, D5, and D6, forcing accelerated substitution timelines.
Sealants provide the stable volume foundation while adhesives climb fastest on composite manufacturing intensity.
Form:
Processing equipment requirements and shelf-life constraints shape regional supply chain configuration for each physical state.
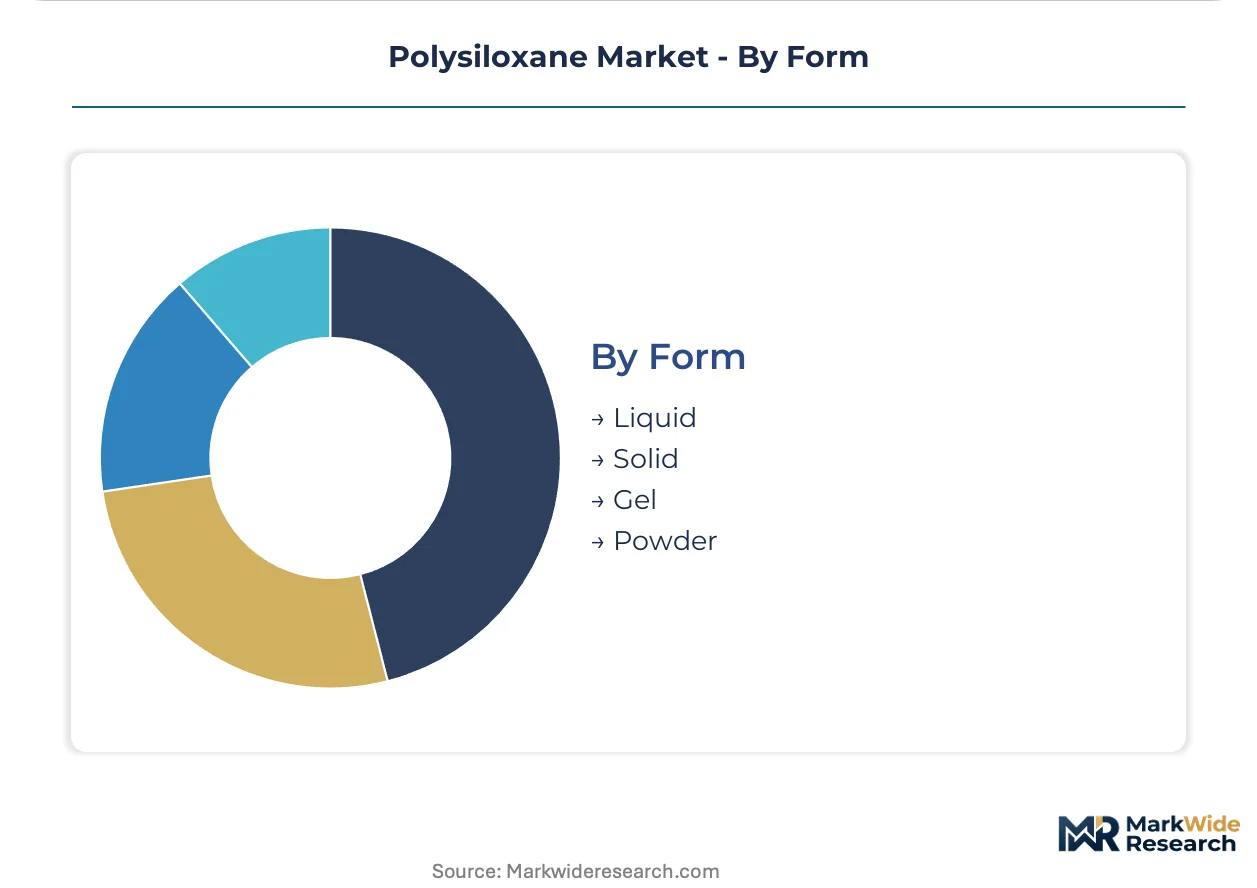
- Liquid:Pumpable dispersions and two-part systems enable automated metering in high-throughput automotive and electronics assembly. Cleanroom-certified liquid silicone rubber for implantable devices remains undersupplied relative to diagnostic equipment demand growth.
- Solid:Millable gums and preformed profiles serve compression molding operations in automotive sealing and industrial gasket fabrication.
- Gel:Soft, conformable materials for medical cushioning and electronics potting require precise durometer control and biocompatibility validation.
- Powder:Free-flowing additives for plastics modification and dry blending applications concentrate in polymer compounding operations.
Liquid forms dominate value concentration while gel formulations expand most quickly on medical device specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity siloxane monomer production clusters in China's Jiangsu and Zhejiang provinces, creating geographic risk exposure for European and North American compounders. This concentration shapes procurement strategies across automotive, electronics, and medical supply chains.
China
NEV production mandates under dual carbon goals are accelerating silicone adoption in electric vehicle battery modules and power electronics thermal interface materials. GB standards and MEE environmental compliance protocols are tightening effluent controls at siloxane monomer plants in Jiangsu province. The Yangtze River Delta region hosts the densest concentration of high-purity siloxane production capacity serving domestic and export markets.
Germany
Platform standardization across EV architectures is reducing approved vendor lists for thermal management materials in automotive supply chains. REACH registration requirements and the EU F-Gas Regulation constrain fluorinated silicone alternatives while redirecting investment toward non-fluorinated high-performance grades. The Ruhr industrial corridor and Bavarian manufacturing hubs concentrate formulation technical service capabilities for OEM co-development partnerships.
United States
EPA oversight of volatile organic compound emissions from silicone coatings and sealants shapes product reformulation priorities in industrial applications. The Inflation Reduction Act incentives for domestic battery manufacturing are expanding demand for thermal interface materials in gigafactory construction. Texas and Louisiana host integrated siloxane production complexes serving North American automotive and electronics supply chains.
India
PLI scheme incentives for electronics manufacturing are attracting silicone thermal pad and encapsulant suppliers to establish local compounding operations. BIS certification requirements for industrial chemicals are extending qualification timelines for imported formulations. Karnataka and Tamil Nadu are emerging as primary locations for smartphone and server component supply chain localization.
Japan
METI industrial policy is supporting advanced material development for semiconductor packaging and automotive electrification applications. JIS standards for silicone rubber in transportation applications maintain specification barriers for non-domestic suppliers. The Kansai region around Osaka retains specialized capabilities in medical-grade and electronics-grade silicone purification.
Polysiloxane Market Competitive Environment
Integrated chemical conglomerates and specialized silicone producers split the market between scale-driven commodity supply and specification-locked premium segments. The competitive structure rewards backward integration into silicon metal production and captive siloxane monomer capacity. Three archetypes dominate: diversified chemical majors with integrated siloxane chains, pure-play silicone specialists with medical and electronics certifications, and regional compounders serving construction and industrial maintenance channels. Capacity expansion in high-purity grades and strategic partnerships for battery thermal management co-development represent the dominant competitive moves.
Within the integrated chemical major tier, Dow and Wacker Chemie AG exemplify archetypes built on captive siloxane production and multi-regional manufacturing footprints. Momentive Performance Materials Inc. occupies a position emphasizing medical-grade and electronics-grade portfolios that command specification-driven procurement. Shin-Etsu Chemical Co., Ltd. anchors the Asia-Pacific supply base with integrated production capabilities. These three companies represent distinct strategic positions: continental manufacturing scale, premium specification focus, and regional supply security.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Akzo Nobel N.V. |
| Wacker Chemie AG |
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials Inc. |
| 3M |
| Dow |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion premiums amplify cost differentials between Jiangsu-sourced siloxane monomers and European compounder alternatives, concentrating pricing power among integrated producers while forcing specification-locked buyers into long-term offtake commitments.
Pricing Analysis
REACH authorization procedures for cyclic siloxanes dictate the pricing tier structure across European supply chains. Three-tier pricing structure across medical-grade, industrial-grade, and commodity-grade silicone separates implantable device certifications from automotive thermal management specifications. Cost compression in standard-grade silicone rubber intensifies because automotive platform standardization reduces approved vendor lists. Electronics OEMs exhibit the least price sensitivity due to ultra-low ionic purity requirements, while construction sealant distributors face acute margin pressure from spot-market silane intermediates.
Supply Chain Analysis
Integrated siloxane production complexes in China, Germany, and the United States hold captive capacity that insulates against raw material volatility. Silicon metal from carbothermic reduction of quartz concentrates, methyl chloride from methanol-chlorine processes, and platinum catalysts for hydrosilylation anchor input dependencies. Single-source vulnerability concentrates in Jiangsu and Zhejiang province monomer plants subject to MEE environmental compliance shutdowns. Distribution runs through regional compounding facilities serving automotive OEMs, electronics EMS providers, and medical device contract manufacturers with divergent qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorinated elastomer substitutes threaten silicone gasket applications under EU F-Gas Regulation compliance timelines, demanding that incumbents fortify non-fluorinated high-performance grade positions before regulatory deadlines accelerate substitution.
For Market Incumbents:Pre-empt fluorinated silicone displacement by accelerating non-fluorinated elastomer R&D partnerships with HVAC OEM engineering teams. Backward integration into silicon metal production anchors margin defense against electricity price volatility in carbothermic reduction. Medical-grade ISO 13485 certification investments create switching costs that emerging Asian compounders cannot replicate within qualification cycles.
For New Entrants and Emerging Players:Establish a beachhead in India's PLI scheme electronics manufacturing corridors where local compounding operations remain undersupplied for thermal pad and encapsulant demand. Target medical-grade liquid silicone rubber for diagnostic equipment as the most penetrable premium segment relative to implantable device qualification barriers. Pursue digital distribution platforms with technical data sheet repositories to compress traditional distributor technical service roles in North American industrial procurement.
For Investors and Strategic Acquirers:Pure-play silicone specialists with captive medical and electronics certifications offer acquisition exposure to specification-driven procurement consolidation. Long-term viability hinges on co-development partnership depth with battery thermal management engineering teams at European and Chinese OEMs. Monitor REACH authorization timeline acceleration for D4, D5, D6 cyclic siloxanes as the inflection signal for personal care formulation substitution demand. Quarterly review of Jiangsu province environmental compliance enforcement and NEV production mandate revisions is advised to detect supply and demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive silicon metal production insulates Wacker Chemie AG from electricity price volatility in German manufacturing. |
| Capacity Expansion | Dow's integrated siloxane complexes in Texas and Louisiana serve Inflation Reduction Act battery gigafactory thermal interface demand. |
| Joint Venture | OEM co-development partnerships for automotive battery pack gap fillers lock in specification-driven procurement at Momentive. |
| Long-term Supply Agreement | Medical-grade cleanroom production commitments extend qualification cycles to 18-24 months under USP Class VI protocols. |
| Green Manufacturing Transition | Non-fluorinated high-performance grade investment redirects capital from constrained fluorinated silicone alternatives under EU F-Gas Regulation. |
Study Parameters
Cross-validation between procurement leads at automotive OEMs and technical R&D directors at silicone compounders anchors the qualitative findings in operational reality. Primary interviews with plant managers at Jiangsu siloxane monomer facilities, distribution channel partners serving construction sealant markets, and regulatory affairs specialists navigating REACH authorization procedures combined with secondary validation from SEC 10-K filings, Cefic chemical industry reports, and customs trade data. Bottom-up segment sizing across silicone rubber, silane, silicone oil, and silicone resin chemistries triangulated against top-down end-use industry demand models.
Calibration against historical capacity utilization rates and patent filing trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include chemistry family, end-use industry specification tier, physical form factor, and regional regulatory compliance cluster. CAGRs derived from elasticity-adjusted demand curves incorporating automotive electrification content-per-vehicle coefficients and medical device implantable versus diagnostic equipment growth differentials. Silane chemistry penetration rates in carbon fiber composite manufacturing and cyclic siloxane substitution timelines under REACH authorization procedures served as industry-specific forecast inputs.
Stress conditions across silicon metal price volatility, Jiangsu province environmental enforcement intensity, and EU F-Gas Regulation compliance acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NEV production mandate adherence and medical-grade cleanroom certification timeline stability. Quarterly review of MEE effluent control protocol revisions and ECHA authorization procedure updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
PEG 3500 Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Polyimides Market
Polymers & Resins
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Wood Coating Resins Market
Polymers & Resins
Polyethylene Naphthalate Market