
 Tip Location Devices Market | 2026-2036
Tip Location Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Tip Location Devices Market Outlook
Hospital purchasing coalitions is reorganizing procurement priorities around real-time catheter tip verification, displacing traditional blind insertion protocols in favor of electromagnetic guidance. Becton, Dickinson and Company leverages its vascular access portfolio breadth to anchor institutional contracts across integrated delivery networks. Teleflex Incorporated competes through specialized navigation platforms that dominate interventional radiology suites. AngioDynamics sustains technology leadership in tip confirmation subsystems through concentrated R&D allocation.
Tip location devices are instruments that detect and confirm the terminal position of central venous catheters, peripherally inserted central catheters, and other vascular access devices using magnetic field detection, impedance sensing, or ultrasound guidance, typically achieving positional accuracy within millimeters to prevent malposition complications. Electromagnetic devices lead installed base volumes due to mature reimbursement coding, while magnetically-activated systems represent the fastest-expanding segment as ambulatory surgical centers adopt lower-cost verification workflows. Bluetooth-enabled wireless technology segments capture premium pricing through seamless electronic health record integration, whereas RFID technology occupies niche applications in asset-tracked catheter inventory management.
FDA premarket notification requirements under 510(k) pathways mandate electromagnetic compatibility and biocompatibility testing for tip location systems, directly shaping product development timelines and clinical evidence burdens. The EU Medical Device Regulation imposes enhanced post-market surveillance and unique device identification obligations on manufacturers distributing electromagnetic and optical tip verification equipment across European member states. Stakeholders must monitor evolving interoperability standards between tip location hardware and hospital information systems as connectivity becomes a decisive procurement criterion.
Market Dynamics
Hospital procurement coalitions are reorganizing catheter insertion protocols around real-time electromagnetic verification, displacing traditional blind insertion methods as catheter-related complication reduction programs expand across integrated delivery networks.
Growth Catalysts
- CMS Hospital-Acquired Condition Reduction Program:Medicare reimbursement penalties for preventable catheter complications accelerate electromagnetic tip verification adoption in US acute care facilities.
- Peripherally inserted central catheter volume expansion:Ambulatory surgical centers in Germany and Japan deploy magnetically-activated verification workflows for same-day vascular access procedures.
- Bluetooth-enabled EHR integration:Seamless electronic health record connectivity captures premium pricing and anchors institutional purchasing decisions.
Market Restraints
- Copper and ferrite magnet cost volatility:Electromagnetic sensor component prices fluctuate with rare earth mineral supply disruptions concentrated in Chinese processing facilities.
- FDA 510(k) electromagnetic compatibility testing:Premarket notification timelines extend 8-14 months for novel tip location architectures, compressing effective patent windows.
- Ultrasound-guided catheter insertion:Point-of-care ultrasound systems substitute for electromagnetic verification in resource-constrained settings, limiting addressable market expansion.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract tip location device assembly for price-sensitive South Asian markets.
- EU MDR unique device identification mandates:Post-market surveillance obligations create demand for integrated RFID tip confirmation subsystems in European member states.
- Home infusion therapy expansion:Portable electromagnetic verification units address the shift of parenteral antibiotic and chemotherapy administration to residential settings in Japan and the United States.
Industry Challenges
- Interoperability certification delays:Hospital information system integration testing with proprietary electromagnetic tip location protocols extends sales cycles 4-6 months.
- Biocompatibility validation complexity:ISO 10993 cytotoxicity and sensitization testing for catheter-integrated magnetic sensors requires parallel clinical evidence generation.
- Electromagnetic field safety training gaps:Vascular access teams lack standardized competency frameworks for magnetically-activated device operation in interventional radiology suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tip Location Devices Market |
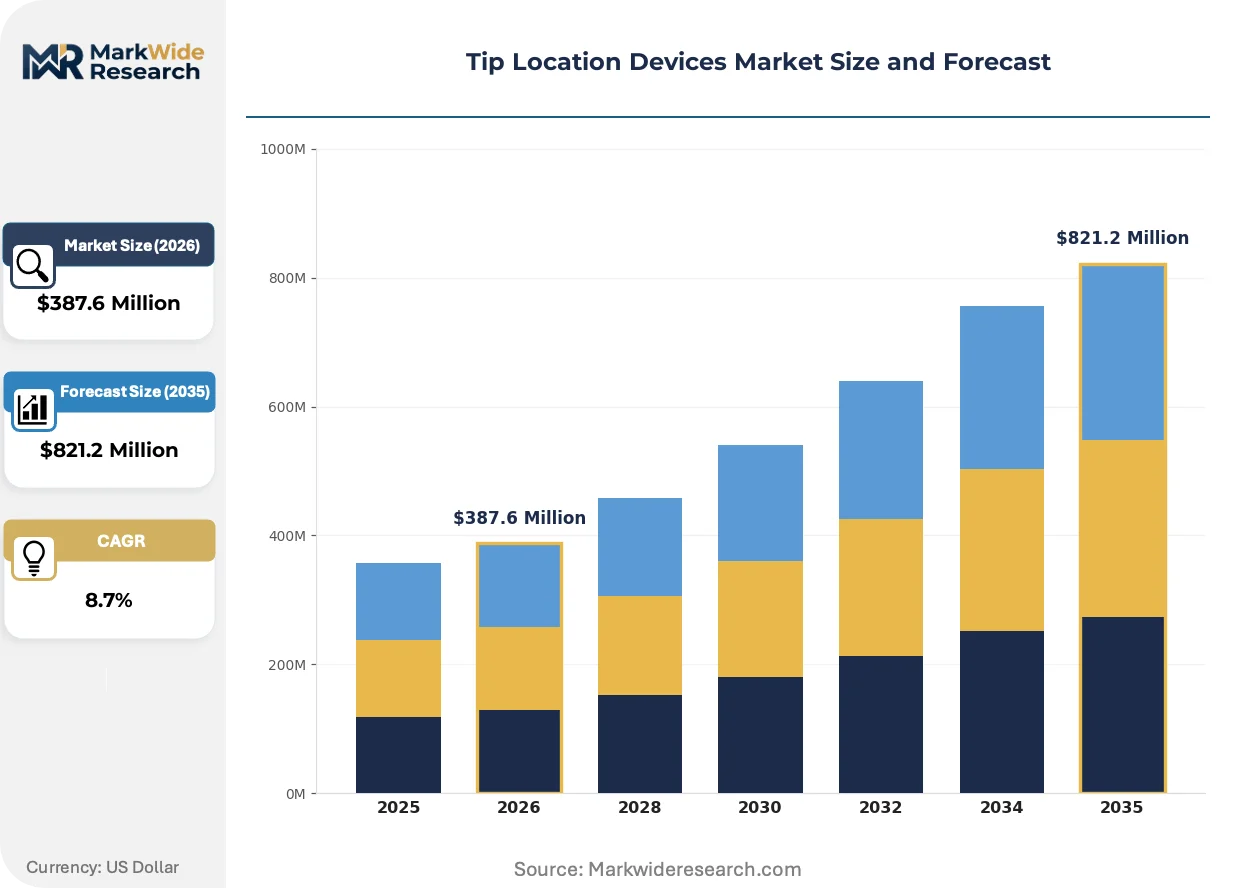
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
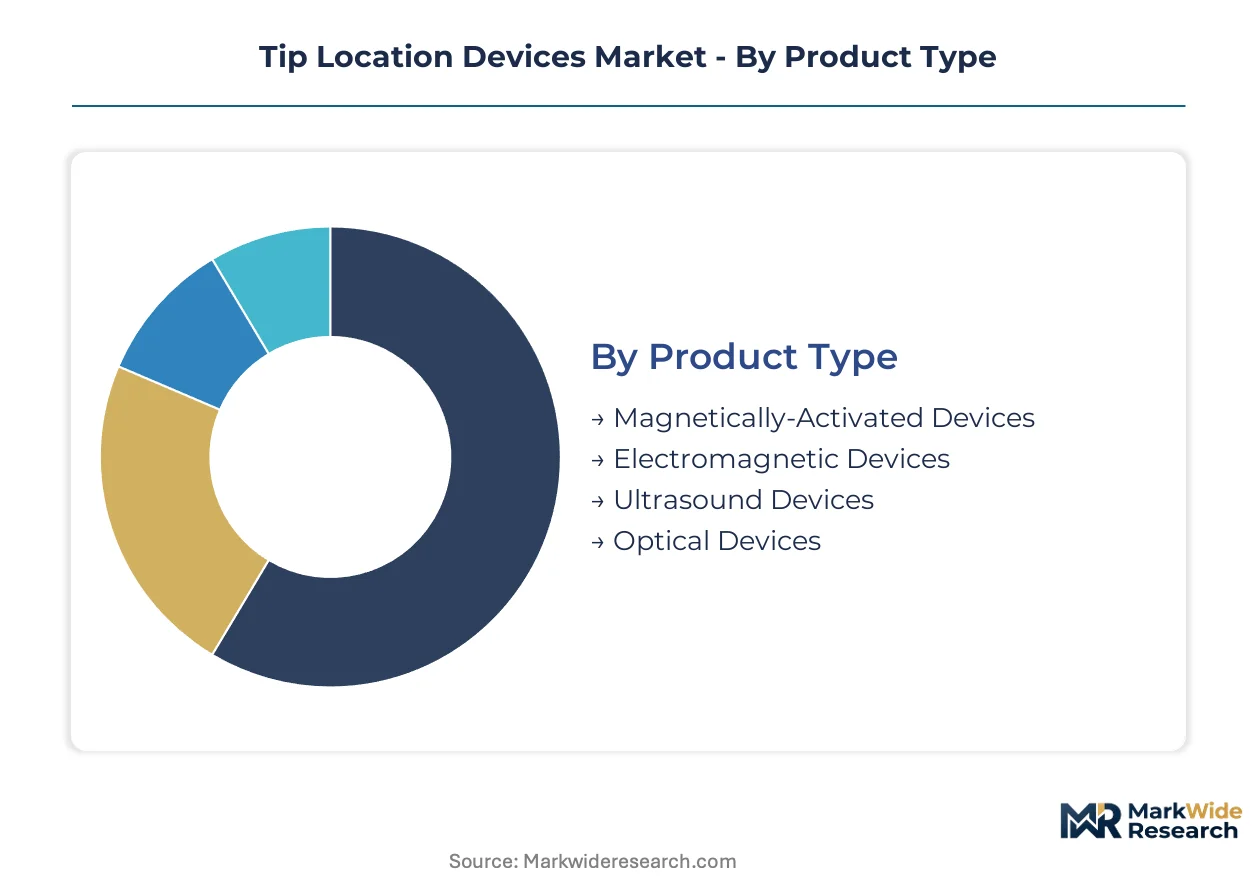
| Segmentation | Product Type: Magnetically-Activated Devices, Electromagnetic Devices, Ultrasound Devices, Optical Devices End User: Clinics, Hospitals, Home Care, Surgical Centers Technology: Wireless Technology, Bluetooth Technology, GPS Technology, RFID Technology Application: Emergency Medical Services, Surgical Procedures, Diagnostic Imaging, Patient Monitoring |
| Companies Covered | Becton, Dickinson and Company, Teleflex Incorporated, AngioDynamics, Vygon, CORPAK MedSystems, GE Healthcare, B. Braun Melsungen AG, Avanos Medical, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tip Location Devices Market Strategic Shifts
Catheter tip verification technology is fragmenting across multiple detection modalities as procurement teams demand flexible, interoperable platforms rather than single-technology dependencies. Three distinct trajectories are reshaping product development priorities and competitive positioning.
Magnetically-activated tip detection is fragmenting the installed base of electromagnetic systems by enabling lower-cost verification workflows without dedicated console hardware. Ambulatory surgical centers in Germany and Japan adopt these stripped-down platforms for high-volume peripherally inserted central catheter procedures. The structural consequence compresses average selling prices while expanding unit volumes into outpatient settings previously excluded from electromagnetic verification economics.
The EU Medical Device Regulation imposes enhanced post-market surveillance and unique device identification obligations on electromagnetic and optical tip verification equipment distributed across European member states. Manufacturers must maintain clinical evidence registries and implement traceability systems for every deployed sensor. Interventional radiology suites in France and Germany face the steepest compliance burdens, driving consolidation toward vendors with established European notified body relationships.
Integrated delivery networks now bundle catheter tip verification with comprehensive vascular access service contracts rather than purchasing capital equipment outright. Device manufacturers compete on total cost-per-procedure metrics, displacing traditional capital lease arrangements. This purchasing pattern shift concentrates most visibly in United States hospital systems participating in CMS accountable care organization models, where complication reduction directly impacts shared savings calculations.
Tip Location Devices Market Segmentation
Tip location device procurement varies sharply across clinical settings and connectivity requirements. Electromagnetic and magnetically-activated systems compete directly for catheter verification workflows, while end-user economics and technology integration demands reshape competitive boundaries.
Product Type:
Ultrasound-guided catheter insertion poses the strongest substitution threat to hardware-dependent verification systems, pressuring electromagnetic device margins in cost-sensitive procurement environments.
- Magnetically-Activated Devices:These systems detect catheter tip position through passive magnetic field sensors embedded in specialized stylets, eliminating the need for external console hardware. Ambulatory surgical centers in Germany and Japan deploy these platforms for high-volume peripherally inserted central catheter procedures where capital equipment economics exclude full electromagnetic suites.
- Electromagnetic Devices:Console-based systems generate low-frequency electromagnetic fields detected by catheter-mounted sensors, achieving positional accuracy within millimeters. United States hospital systems participating in CMS accountable care organization models anchor procurement around these platforms due to mature reimbursement coding and established clinical evidence bases.
- Ultrasound Devices:Point-of-care imaging substitutes for dedicated tip verification in resource-constrained settings.
- Optical Devices:Fiber-optic stylet systems serve niche applications requiring electromagnetic interference avoidance.
Electromagnetic devices retain volume leadership; magnetically-activated platforms hold the steepest expansion curve.
End User:
Procurement authority concentrates differently across settings, with integrated delivery networks driving hospital purchasing while surgical centers optimize for per-procedure economics.
- Hospitals:Acute care facilities command the largest installed base through vascular access service contracts that bundle tip verification with comprehensive catheter management programs. FDA electromagnetic compatibility mandates and Joint Commission catheter-related bloodstream infection reduction targets shape purchasing timelines and technical specifications.
- Surgical Centers:Outpatient facilities prioritize portable, lower-cost verification workflows for same-day vascular access procedures.
- Clinics:Physician office laboratories adopt stripped-down electromagnetic or magnetically-activated systems for limited procedure volumes.
- Home Care:Residential infusion therapy expansion in Japan and the United States creates demand for portable electromagnetic verification units.
Hospitals dominate absolute spending; surgical centers capture the fastest volume gains.
Technology:
Connectivity premiums separate electronic health record-integrated platforms from standalone verification hardware.
- Bluetooth Technology:Wireless protocols enable seamless data transmission to hospital information systems, capturing premium pricing through automated documentation and traceability compliance. United States procurement teams prioritize Bluetooth-enabled systems as interoperability becomes a decisive vendor selection criterion.
- RFID Technology:Radio-frequency identification supports unique device identification mandates under EU Medical Device Regulation, creating integrated tip confirmation subsystems for European post-market surveillance obligations.
- Wireless Technology:Generic wireless protocols serve cost-optimized deployments without EHR integration requirements.
- GPS Technology:Satellite positioning occupies negligible share, limited to specialized asset tracking rather than real-time tip verification.
Bluetooth-enabled systems command pricing premiums; RFID segments expand most quickly on regulatory compliance demand.
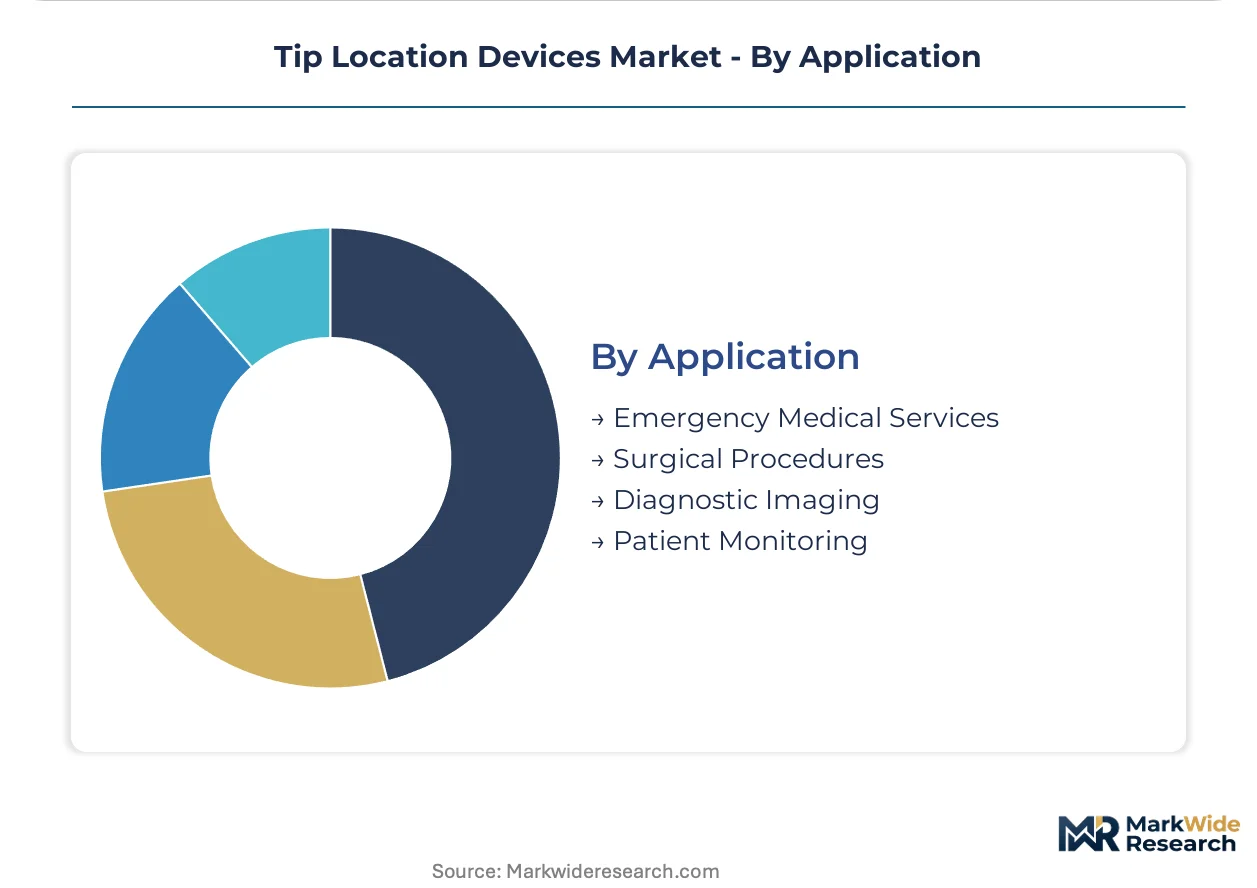
Application:
Procedure urgency and complication risk profiles determine verification technology selection across clinical workflows.
- Surgical Procedures:Operating room and interventional radiology suites demand highest positional accuracy, anchoring electromagnetic system adoption. Teleflex navigation platforms dominate these settings through specialized hardware-software integration.
- Patient Monitoring:Intensive care unit catheter maintenance requires ongoing tip position verification, sustaining recurring revenue for disposable sensor components.
- Emergency Medical Services:Pre-hospital vascular access prioritizes speed over precision, limiting dedicated tip verification adoption.
- Diagnostic Imaging:Radiology departments integrate tip confirmation with contrast injection protocols for computed tomography and magnetic resonance procedures.
Surgical procedures anchor technology investment; patient monitoring applications expand through disposable sensor recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics infrastructure underwrites European distribution efficiency for electromagnetic tip verification systems, while the Trans-Pacific submarine cable network enables real-time EHR data synchronization for Bluetooth-enabled devices across East Asian and North American hospital systems.
United States
CMS Hospital-Acquired Condition Reduction Program penalties drive electromagnetic tip verification adoption across acute care facilities. FDA 510(k) premarket notification pathways mandate electromagnetic compatibility testing that extends product development timelines. Integrated delivery networks in Texas and California anchor institutional purchasing through bundled vascular access service contracts.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia deploy magnetically-activated verification workflows for high-volume peripherally inserted central catheter procedures. EU Medical Device Regulation unique device identification obligations reshape post-market surveillance requirements for electromagnetic equipment. The Frankfurt-Rhine-Main medical technology cluster concentrates notified body relationships and regulatory expertise.
Japan
Residential infusion therapy expansion creates demand for portable electromagnetic verification units in Tokyo and Osaka metropolitan areas. METI reimbursement frameworks incentivize catheter-related complication reduction programs in acute care settings. The Kansai region's interventional radiology suites anchor specialized navigation platform adoption.
India
Production-Linked Incentive schemes for medical devices attract tip location device assembly for price-sensitive South Asian markets. CDSCO regulatory harmonization with international standards accelerates import substitution for electromagnetic sensor components. Manufacturing investments concentrate in Maharashtra and Gujarat medical device parks.
Tip Location Devices Market Competitive Environment
Concentration sits with diversified vascular access portfolios and specialized navigation platforms that anchor distinct procurement channels. The vendor base stratifies across integrated delivery network contract holders, interventional radiology suite specialists, and component subsystem suppliers. Strategic archetypes include electromagnetic console manufacturers, magnetically-activated platform developers, and disposable sensor component suppliers. Competitive moves center on institutional contract bundling and interoperability certification acceleration.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Siemens Healthineers occupy positions spanning vascular access portfolios and imaging integration. Teleflex Incorporated represents the specialized navigation platform archetype within interventional radiology procurement channels. These three entities exemplify distinct competitive positioning vectors without overlapping core technology dependencies.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| AngioDynamics |
| Vygon |
| CORPAK MedSystems |
| GE Healthcare |
| B. Braun Melsungen AG |
| Avanos Medical |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
FDA electromagnetic compatibility testing under 510(k) pathways gates both supplier qualification and price tiering simultaneously, creating a dual barrier where certification investment separates premium console manufacturers from stripped-down magnetically-activated competitors. This regulatory filtering concentrates pricing power among established vendors while forcing new entrants into lower-margin hardware-eliminated segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with Bluetooth-enabled EHR-integrated systems commanding the highest tier through interoperability certification, magnetically-activated platforms occupying the mid-tier via elimination of console hardware, and basic ultrasound-guided verification anchoring the economy tier. Price differentiation rests on electromagnetic sensor precision grades and FDA 510(k) clearance tier. Cost compression in the economy tier is intensifying because ambulatory surgical centers in Germany and Japan prioritize per-procedure economics over capital investment. Surgical centers exhibit the highest price sensitivity; integrated delivery networks in the United States demonstrate the lowest.
Supply Chain Analysis
Rare earth mineral processing concentration in Chinese facilities creates a chokepoint for ferrite magnet and copper sensor component supply, exposing electromagnetic device manufacturers to single-source vulnerability for critical magnetic field generators. Component sourcing draws from China for rare earth processing, Japan for precision sensor fabrication, and Germany for optical subsystem assembly. Raw material dependencies center on neodymium, copper coil windings, and biocompatible catheter polymers. Distribution runs through specialized medical device distributors serving hospital procurement coalitions and direct institutional contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA 510(k) electromagnetic compatibility testing creates multi-year certification barriers that protect incumbent revenue streams from rapid competitive displacement.
For Market Incumbents: Compound institutional contract density through bundled vascular access service agreements that embed tip verification within comprehensive catheter management programs, displacing standalone capital equipment purchases. Deepen backward integration into electromagnetic sensor component production to offset rare earth mineral price volatility from Chinese processing concentration. Prioritize Bluetooth interoperability certification acceleration to defend against ultrasound-guided substitution threats in cost-sensitive procurement channels.
For New Entrants and Emerging Players: Anchor in India's Production-Linked Incentive medical device parks to exploit domestic manufacturing cost advantages for price-sensitive South Asian market penetration. Target ambulatory surgical centers in Germany and Japan with magnetically-activated platforms that eliminate console hardware economics. Pursue CDSCO regulatory harmonization pathways to accelerate import substitution for electromagnetic sensor components in Indian hospital procurement.
For Investors and Strategic Acquirers: EU MDR unique device identification mandates reshape the acquisition landscape by elevating vendors with established European notified body relationships above compliance-lagged competitors. Five-to-ten year viability favors electromagnetic console manufacturers with installed base lock-in through disposable sensor recurring revenue. Target acquisition archetypes include magnetically-activated platform developers with ambulatory surgical center channel penetration. Monitor FDA 510(k) clearance backlogs as the inflection signal indicating regulatory capacity constraints that favor incumbents with established submission expertise.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Electromagnetic Compatibility Submission | Clearance timelines of 8-14 months protect incumbent patent windows from rapid competitive entry. |
| Bluetooth EHR Integration Certification | Interoperability with Epic and Cerner systems anchors premium pricing in United States hospital procurement. |
| EU MDR Unique Device Identification Compliance | Traceability systems satisfy post-market surveillance obligations for French and German interventional radiology suites. |
| Magnetically-Activated Platform Development | Hardware elimination captures ambulatory surgical center volume in Germany and Japan outpatient settings. |
| India PLI Scheme Manufacturing Localization | Domestic assembly reduces landed cost for price-sensitive South Asian catheter verification markets. |
Study Parameters
Operator-level perspectives from vascular access specialists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview intelligence combined with secondary validation from FDA 510(k) premarket notification databases, CMS Medicare reimbursement coding records, hospital procurement contract registries, and EU Medical Device Regulation implementation guidance. Bottom-up installed base modeling and top-down spending pattern triangulation converged on segment-level estimates.
Sensitivity analysis across pricing tier adoption rates, regulatory clearance timeline scenarios, and raw material cost volatility assumptions shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user setting, connectivity technology, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to reimbursement incentive structures and catheter-related complication reduction program expansion. Forecast inputs incorporated electromagnetic sensor component cost curves and Bluetooth interoperability certification penetration rates.
Material uncertainties — rare earth mineral supply disruptions, FDA electromagnetic compatibility testing backlog fluctuations, and EU MDR notified body capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable reimbursement coding for electromagnetic verification and continued CMS penalty structures for preventable catheter complications. Revision becomes warranted when FDA 510(k) average review duration crosses 18-month thresholds or when Chinese rare earth export restrictions disrupt ferrite magnet supply continuity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Russia Non-Contact Infrared Thermometer Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Torque Transducer Market