
 Global Refrigeration Leak Detector Market | 2026-2036
Global Refrigeration Leak Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refrigeration Leak Detector Market Outlook
Semiconductor-based infrared sensor miniaturization is rewriting the cost-performance frontier for portable detection equipment. Inficon leverages its vacuum technology heritage to dominate high-sensitivity benchtop systems for industrial process control. Bacharach specializes in refrigerant-specific infrared bench units that anchor its position among HVAC service contractors. Fieldpiece Instruments competes aggressively on wireless connectivity and smartphone integration for residential and light commercial technicians.
Refrigeration leak detectors are instruments designed to identify and locate unintended escapes of refrigerant gases from sealed systems, typically achieving detection thresholds below one part per million depending on sensor technology and calibration protocol. Their primary purpose is to ensure environmental compliance, preserve system efficiency, and prevent occupational exposure to asphyxiant or toxic compounds. Portable units command the broadest installed base across service fleets, while fixed systems embedded in large industrial ammonia installations capture disproportionate margin pools through integration contracts and recurring calibration services. Infrared technology leads on accuracy for low-global-warming-potential blends, though ultrasonic methods retain cost advantages in noisy environments where electronic interference complicates semiconductor operation.
The US EPA enforces refrigerant management regulations under Section 608 of the Clean Air Act, mandating leak repair thresholds and inspection frequencies that directly sustain replacement demand for certified detection equipment. The EU F-Gas Regulation and ECHA REACH restrictions on fluorinated gases are forcing European operators toward more sensitive detection protocols to minimize venting during maintenance cycles. China's MEE implements national hydrofluorocarbon consumption quotas aligned with Kigali Amendment commitments, tightening compliance verification requirements for commercial cold storage operators. Stakeholders must weigh sensor technology bets against evolving refrigerant chemistries and regional enforcement intensities.
Market Dynamics
The Kigali Amendment's hydrofluorocarbon phase-down schedules are compressing replacement cycles across commercial refrigeration fleets, forcing operators to upgrade detection sensitivity thresholds faster than historical equipment depreciation schedules allowed.
Growth Catalysts
- Cold chain logistics expansion:Asia-Pacific fleet operators are retrofitting monitoring programs across refrigerated transport corridors. This generates replacement demand for portable detection units calibrated to new refrigerant blends.
- F-Gas Regulation enforcement:The EU's tightening venting thresholds during maintenance cycles mandates more frequent inspection protocols. Service contractors must maintain certified equipment inventories that meet evolving sensitivity standards.
- Infrared sensor miniaturization:Semiconductor fabrication advances are collapsing cost curves for benchtop accuracy in handheld form factors. This opens residential and light commercial segments previously served by lower-precision ultrasonic alternatives.
Market Restraints
- Helium supply concentration:Mass spectrometer leak detectors depend on helium as a tracer gas, with extraction concentrated in Qatar and the US. Price volatility in this input directly squeezes margins for high-sensitivity industrial systems.
- Calibration service fragmentation:Fixed ammonia detection installations require recurring certification by accredited technicians. The geographic dispersion of qualified service providers extends downtime risks for food processing facilities in remote locations.
- Refrigerant chemistry turbulence:Rapid transitions from R-404A to R-448A/R-449A blends and emerging A2L mildly flammable alternatives force sensor recalibration or hardware replacement before full depreciation.
Strategic Opportunities
- Wireless connectivity integration:Bluetooth-enabled detectors streaming to smartphone apps are penetrating residential HVAC contractor segments. Fieldpiece Instruments has established early positioning here.
- India cold storage buildout:The country's PLI scheme for food processing infrastructure is accelerating commercial refrigeration deployment. Detection equipment demand trails capital expenditure by twelve to eighteen months.
- Cloud-based fleet monitoring:Large supermarket chains in Germany and France are centralizing leak detection data across distributed store networks. This creates recurring software subscription revenue atop hardware sales.
Industry Challenges
- Certified technician scarcity:EPA Section 608 certification requirements in the US and equivalent credentials in the EU constrain service fleet expansion. Training pipelines have not kept pace with enforcement intensity.
- Legacy system integration:Industrial ammonia refrigeration installations from the 1980s and 1990s use proprietary control architectures. Retrofitting modern digital detectors requires custom engineering that extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refrigeration Leak Detector Market |
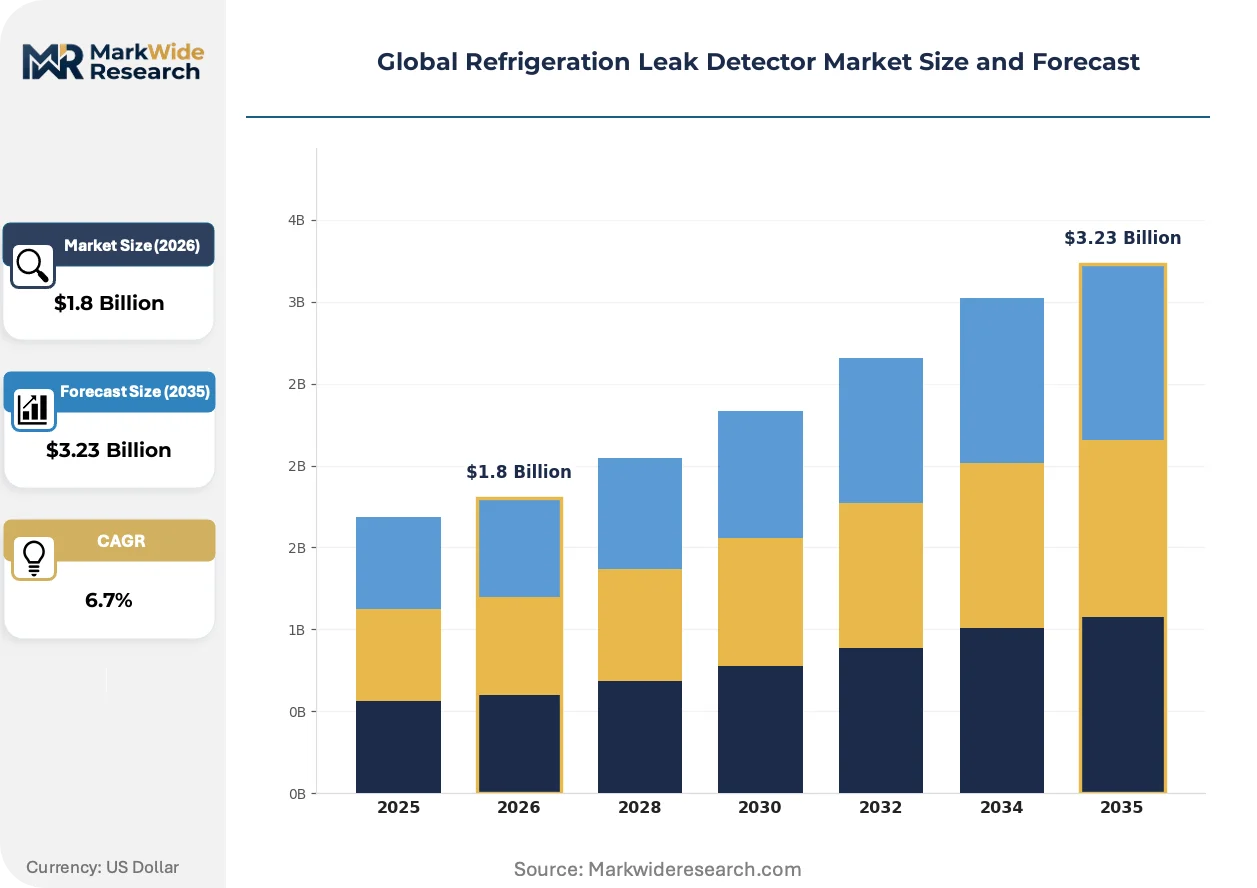
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Handheld, Wireless Technology: Ultrasonic, Infrared, Electronic, Chemical End User: Commercial, Industrial, Residential, Automotive Application: HVAC Systems, Refrigeration, Leak Detection, Maintenance |
| Companies Covered | Testo SE & Co. KGaA, CPS Products, Inficon, Honeywell International, Ritchie Engineering, Bacharach, Robinair, Danfoss Group, Fieldpiece Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refrigeration Leak Detector Market Strategic Shifts
Detection technology is converging with industrial IoT architectures and predictive maintenance platforms, shifting value capture from hardware transactions toward data-enabled service relationships.
Photonic integrated circuits are digitizing refrigerant identification workflows by embedding broadband infrared spectroscopy into chip-scale packages. Cold storage operators in the Netherlands and Denmark are piloting these units for continuous perimeter monitoring. The technology is digitizing how facilities distinguish between R-134a, R-410A, and emerging hydrofluoroolefin blends without laboratory-grade benchtop equipment.
REACH restrictions on fluorinated gases are forcing European OEMs to redesign leak detection protocols around lower-global-warming-potential alternatives. The regulation compresses acceptable venting thresholds during compressor changeouts and coil repairs. Commercial service fleets in France and Germany are responding by standardizing on multi-refrigerant infrared units rather than single-gas detectors.
Supermarket operators are unbundling after-sales service contracts from original equipment manufacturers, instead procuring detection and maintenance through specialized regional contractors. This procurement fragmentation concentrates buying power among multi-site facility managers in the UK and Australia. The shift pressures detector vendors to simplify calibration procedures and extend sensor lifespans to match third-party service economics.
Global Refrigeration Leak Detector Market Segmentation
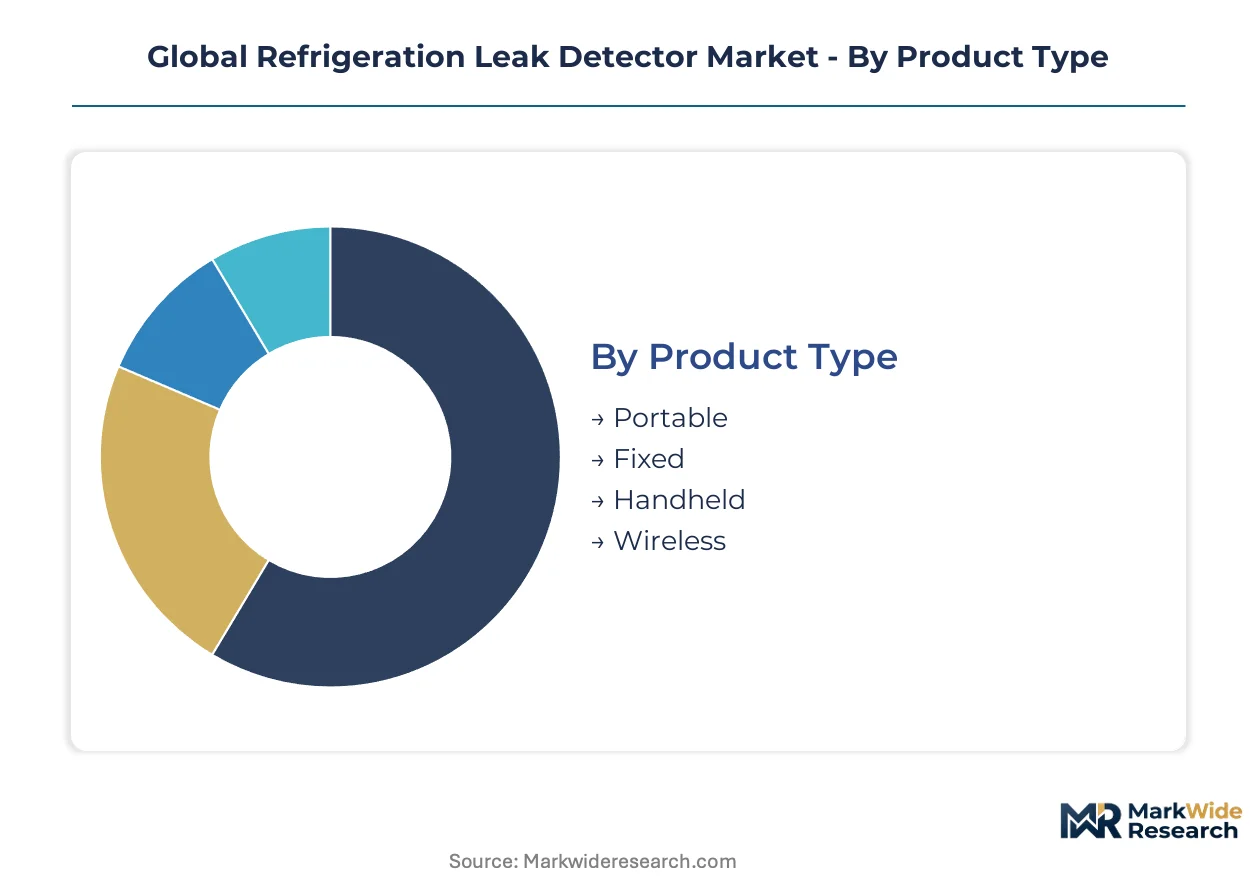
Refrigeration leak detector procurement splits across four distinct category hierarchies. Product form factor determines service fleet mobility requirements. Technology choice governs sensitivity thresholds against evolving refrigerant chemistries.
Product Type:
Mature benchtop systems anchor industrial process control, while emerging wireless form factors are penetrating residential contractor segments.
- Portable:Battery-powered units weighing under two kilograms dominate HVAC service truck inventories. Fleet operators across Germany and Japan are replacing ultrasonic legacy stock with infrared-enabled portables as R-448A and R-449A blends displace R-404A.
- Fixed:Permanently installed sensor arrays monitor large ammonia refrigeration installations in food processing plants. Integration contracts with cold storage operators in the Netherlands bundle hardware with recurring calibration services, capturing disproportionate margin pools.
- Handheld:Compact pistol-grip designs serve residential technicians requiring single-hand operation during coil inspections.
- Wireless:Bluetooth-enabled detectors streaming to smartphone apps are gaining share among light commercial contractors. Fieldpiece Instruments has established positioning here through aggressive smartphone integration.
Portable units retain volume leadership across service fleets; wireless configurations hold the steepest expansion curve as contractor digitization accelerates.
Technology:
Cost tier stratification separates premium infrared accuracy from economy ultrasonic alternatives, with electronic and chemical methods occupying intermediate positions.
- Ultrasonic:Detects refrigerant escape through high-frequency sound signature analysis without gas-specific calibration. Noisy compressor environments and electronic interference limit accuracy, constraining deployment to budget-conscious residential segments in India and Brazil.
- Infrared:Non-dispersive infrared spectroscopy achieves sub-ppm detection thresholds required for hydrofluoroolefin blends and A2L mildly flammable refrigerants. Semiconductor fabrication advances are collapsing cost curves, enabling benchtop accuracy in handheld form factors.
- Electronic:Heated diode and metal oxide semiconductor sensors offer mid-range sensitivity at moderate price points for general commercial maintenance.
- Chemical:Color-change indicator tubes and halide torches persist in legacy ammonia applications where intrinsic safety requirements prohibit powered electronics.
Infrared technology commands premium positioning; ultrasonic methods defend economy volume through durability and calibration simplicity.
End User:
Application scale separates industrial capital expenditure cycles from residential replacement demand, with commercial and automotive occupying distinct procurement rhythms.
- Commercial:Supermarket chains and cold storage operators in France and Germany drive multi-unit procurement through centralized facility management. Unbundling of after-sales contracts from OEMs concentrates buying power among specialized regional contractors.
- Industrial:Ammonia refrigeration installations in meat processing and dairy facilities require fixed detection arrays with SIL-rated safety integration. China's food processing infrastructure buildout under MEE hydrofluorocarbon quotas is accelerating demand.
- Residential:HVAC service technicians in the US face EPA Section 608 certification requirements that constrain fleet expansion and equipment turnover rates.
- Automotive:Mobile air conditioning service bays require compact portables calibrated to R-1234yf and emerging ultra-low-GWP alternatives.
Commercial end users generate the largest revenue concentration; industrial applications are expanding most quickly on cold chain infrastructure investment.
Application:
Customer type bifurcation separates continuous monitoring requirements from episodic maintenance workflows.
- HVAC Systems:Split-system and packaged unit service drives recurring portable detector demand. US residential contractors perform leak inspections during seasonal maintenance visits under EPA leak repair threshold mandates.
- Refrigeration:Commercial cold storage and transport refrigeration require both fixed perimeter monitoring and portable spot-checking capabilities. REACH restrictions on fluorinated gases are compressing acceptable venting thresholds during compressor changeouts.
- Leak Detection:Standalone detection services represent a growing procurement category as facility managers separate monitoring from maintenance execution.
- Maintenance:Scheduled inspection protocols sustain replacement demand as sensitivity standards tighten and refrigerant chemistries evolve.
Refrigeration applications anchor installed base value; HVAC systems are gaining share fastest on residential contractor fleet upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision infrared benchtop systems to cold storage operators across France and the Netherlands. Japanese sensor fabricators supply semiconductor-based detectors to HVAC service fleets in Australia and Southeast Asia.
United States
EPA Section 608 enforcement sustains replacement demand across residential HVAC contractor fleets. The agency mandates certified leak detection equipment for technicians servicing systems containing fifty pounds or more of refrigerant. Service truck inventories in Texas and Florida are upgrading to infrared-enabled portables as R-454B blends displace legacy chemistries.
China
MEE hydrofluorocarbon consumption quotas are accelerating commercial refrigeration retrofit activity. The ministry's compliance verification requirements tighten inspection protocols for cold storage operators in Shanghai and Guangdong. Yangtze River Delta processing clusters are deploying fixed ammonia detection arrays under food safety integration mandates.
Germany
EU F-Gas Regulation venting thresholds are compressing maintenance cycle tolerances for supermarket chains. ECHA REACH restrictions on fluorinated gases force multi-refrigerant infrared standardization across service fleets. Industrial refrigeration in North Rhine-Westphalia is unbundling detection procurement from OEM after-sales contracts.
Japan
METI energy efficiency standards are driving supermarket refrigeration system replacements. The ministry's refrigerant management guidelines require sensitive detection protocols for ultra-low-GWP alternatives. Kanto region cold chain operators are piloting photonic integrated circuit detectors for continuous perimeter monitoring.
India
PLI scheme incentives for food processing infrastructure are accelerating commercial cold storage deployment. BIS certification requirements for refrigeration safety equipment lag capital expenditure by twelve to eighteen months. Gujarat and Maharashtra processing clusters are importing portable infrared units calibrated to R-32 and R-410A service protocols.
Global Refrigeration Leak Detector Market Competitive Environment
On the supply side, the industry is consolidating around three capability tiers. Vacuum technology heritage distinguishes high-sensitivity benchtop specialists from portable-focused service equipment vendors. Strategic archetypes include infrared spectroscopy purists, wireless connectivity integrators, and diversified industrial controls conglomerates. Competitive moves concentrate on sensor miniaturization partnerships and cloud-based fleet monitoring platform launches.
Among Swiss precision instrumentation specialists, Inficon anchors the high-sensitivity industrial process control tier. Fieldpiece Instruments and Bacharach exemplify divergent positioning vectors within the North American service equipment segment. These three names represent the spectrum from vacuum technology heritage through wireless contractor integration to refrigerant-specific infrared specialization.
| Leading Market Players |
|---|
| Testo SE & Co. KGaA |
| CPS Products |
| Inficon |
| Honeywell International |
| Ritchie Engineering |
| Bacharach |
| Robinair |
| Danfoss Group |
| Fieldpiece Instruments |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japanese semiconductor fabs producing infrared sensor arrays is tightening component availability for portable detector manufacturers. This utilization squeeze simultaneously elevates input costs for mid-tier vendors and accelerates pricing power consolidation among integrated producers with captive sensor supply.
Pricing Analysis
Prior-generation ultrasonic detectors trade at substantial discounts to current infrared-enabled portables, while next-generation photonic integrated circuit units command laboratory-grade premiums. Three-tier pricing structure across premium, standard, and economy levels separates benchtop industrial systems from wireless contractor units and legacy chemical indicators. Price differentiation hinges on certification grade—EPA Section 608 and EU F-Gas compliance tiers—and after-sales service bundling. Cost compression in the economy tier is intensifying because Indian and Brazilian buyers prioritize calibration simplicity over sensitivity. Residential HVAC contractors in Florida and Texas exhibit highest price sensitivity; cold storage operators in the Netherlands and Denmark show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for detector manufacturers sourcing packaged sensors. Component assembly concentrates in China, Japan, and Germany, with semiconductor fabrication feeding from Taiwanese foundries and specialized glass suppliers in Schott AG's German operations. Raw material dependencies include indium antimonide for infrared detectors, helium for mass spectrometer calibration, and rare earth elements for sensor packaging. Single-source vulnerability in Qatari helium extraction threatens high-sensitivity industrial system margins. Distribution runs through authorized service distributors in North America and direct OEM relationships with supermarket chains in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based fleet monitoring subscriptions are expanding faster than hardware transactions among German and French supermarket operators. This service-attach layer recalibrates vendor economics toward recurring revenue retention.
For Market Incumbents: Harden calibration service networks against geographic fragmentation by accrediting third-party technicians in India's Gujarat and Maharashtra processing clusters. Vertical integration into semiconductor sensor fabrication—exemplified by Japanese fabricators—defends margin position against component cost volatility from Taiwanese foundry concentration. Inficon's vacuum technology heritage and Bacharach's refrigerant-specific specialization represent defensible moats against portable-focused wireless entrants. For New Entrants and Emerging Players: Establish a beachhead in India's commercial cold storage buildout where BIS certification lags capital expenditure by twelve to eighteen months. Wireless connectivity integration for residential HVAC contractors in Texas and Florida offers the most penetrable segment; Fieldpiece Instruments has validated smartphone-enabled demand. A calibration-as-a-service go-to-market angle bypasses incumbent hardware replacement cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fixed ammonia detection integrators with multi-year calibration contracts in Dutch and Danish food processing facilities. Long-term viability over a five-to-ten-year window favors vendors with sensor miniaturization partnerships and cloud platform deployments. Acquisition targets should display photonic integrated circuit pilot programs or EPA Section 608 certification infrastructure. The signal to watch is MEE enforcement intensity in China's Yangtze River Delta processing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Miniaturization Partnership | Semiconductor fabrication advances collapse cost curves for infrared accuracy in handheld units. |
| Cloud-Based Fleet Monitoring Platform | German supermarket chains centralize leak data across distributed store networks. |
| Calibration Service Network Expansion | Accredited technician scarcity in India extends downtime risks for food processing facilities. |
| Multi-Refrigerant Infrared Standardization | EU F-Gas Regulation forces service fleets away from single-gas detector inventories. |
| Photonic Integrated Circuit Pilot Deployment | Dutch cold storage operators digitize refrigerant identification without laboratory equipment. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with equipment procurement managers at supermarket chains, EPA-certified service contractors, cold storage facility engineers, and infrared sensor R&D directors; and secondary validation through customs trade records, EPA Section 608 enforcement disclosures, EU F-Gas Regulation implementation reports, and MEE hydrofluorocarbon quota filings. Bottom-up unit demand modeling across portable, fixed, handheld, and wireless form factors triangulated against top-down market sizing from semiconductor sensor shipment data.
Forecast inputs span technology substitution curves for ultrasonic-to-infrared transitions, refrigerant chemistry evolution from R-404A to R-448A/R-449A and A2L alternatives, and regional enforcement intensity variations under Kigali Amendment schedules. Segmentation dimensions modeled include product form factor, detection technology, end-user scale, and application workflow type. CAGRs derive from equipment replacement cycle compression against historical depreciation schedules and sensitivity threshold upgrades mandated by tightening venting regulations.
Sensitivities concentrate around helium supply disruptions, rapid A2L refrigerant transitions forcing premature hardware obsolescence, and MEE enforcement acceleration in China. Forecasts reflect documented assumptions on sensor cost curves and regional regulatory implementation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Wearable Temperature Sensors Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market