
 Global Accelerometers Market | 2026-2036
Global Accelerometers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Accelerometers Market Analysis
China is tilting the supply map eastward as domestic MEMS fabrication expands around Shanghai and Suzhou. Robert Bosch GmbH leverages its automotive heritage to anchor European demand for high-g accelerometers. STMicroelectronics sustains R&D intensity across analog and digital product lines. Murata Manufacturing Co. Ltd. specializes in miniaturized capacitive designs for consumer electronics.
Accelerometers are electromechanical devices that measure proper acceleration along one or more axes, typically using piezoelectric crystals, capacitive plates, or micromachined silicon structures to detect inertial forces with sensitivities ranging from micro-g to thousands of g. Their primary commercial purpose spans vibration monitoring, tilt sensing, shock detection, and inertial navigation across industrial, automotive, and aerospace systems. MEMS technology dominates unit economics through semiconductor-scale manufacturing, while piezoelectric variants retain premium positioning in high-temperature aerospace environments. Digital output interfaces are displacing analog signal chains in new automotive safety designs, and wireless connectivity is emerging in predictive maintenance networks.
FDA oversight shapes medical-grade accelerometer specifications for patient monitoring devices in the United States, while REACH and RoHS compliance in Europe restricts hazardous substances in sensor packaging and solder materials. China's GB standards and MIIT directives govern domestic MEMS certification for automotive integration. Stakeholders must monitor how divergent electromagnetic compatibility requirements across FDA, EMA, and NMPA jurisdictions fragment test-and-certification budgets.
Market Dynamics
Automotive electrification and advanced driver-assistance mandates are compressing design cycles for high-g MEMS sensors, forcing suppliers to reconcile functional safety certification with semiconductor-scale cost structures.
Growth Catalysts
- EU Green Deal vehicle safety mandates:Tightened emissions protocols require precise motion sensing for regenerative braking optimization and battery thermal management across European OEM platforms.
- China domestic EV production scaling:Shanghai and Suzhou fabrication clusters are absorbing demand previously served by imported MEMS, redirecting supply chain gravity eastward.
- Digital output interface standardization:SPI and I2C protocols are replacing analog signal chains in new automotive safety designs, simplifying ECU integration and reducing wiring harness complexity.
Market Restraints
- Silicon wafer input volatility:MEMS fabrication depends on 200mm and 300mm silicon-on-insulator substrates subject to foundry allocation constraints and price swings.
- Automotive qualification timelines:AEC-Q100 stress testing and ISO 26262 functional safety certification extend product development cycles to 24-36 months, freezing design wins.
- Piezoelectric substitution in aerospace:High-temperature environments above 175°C still require quartz and ceramic accelerometers, fragmenting R&D investment across incompatible material platforms.
Strategic Opportunities
- India industrial automation penetration:PLI scheme incentives for electronics manufacturing are creating captive demand for vibration monitoring in precision tooling and robotics.
- Wireless predictive maintenance networks:LoRaWAN and Bluetooth Low Energy integration enables battery-free sensor nodes for rotating equipment monitoring in oil and gas infrastructure.
- FDA Class II device expansion:Remote patient monitoring reimbursement codes are accelerating design-ins for accelerometer-based fall detection and activity tracking in home healthcare.
Industry Challenges
- MEMS process engineer scarcity:Specialized expertise in deep reactive ion etching and wafer-level packaging concentrates in Grenoble, Dresden, and Hsinchu, constraining foundry expansion.
- Multi-jurisdiction EMC testing:Divergent electromagnetic compatibility requirements across FDA, EMA, and NMPA jurisdictions fragment certification budgets and delay product launches.
- Legacy analog system integration:Industrial retrofit projects require signal conditioning hardware to bridge digital MEMS outputs with existing 4-20mA control loops, adding BOM cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Accelerometers Market |
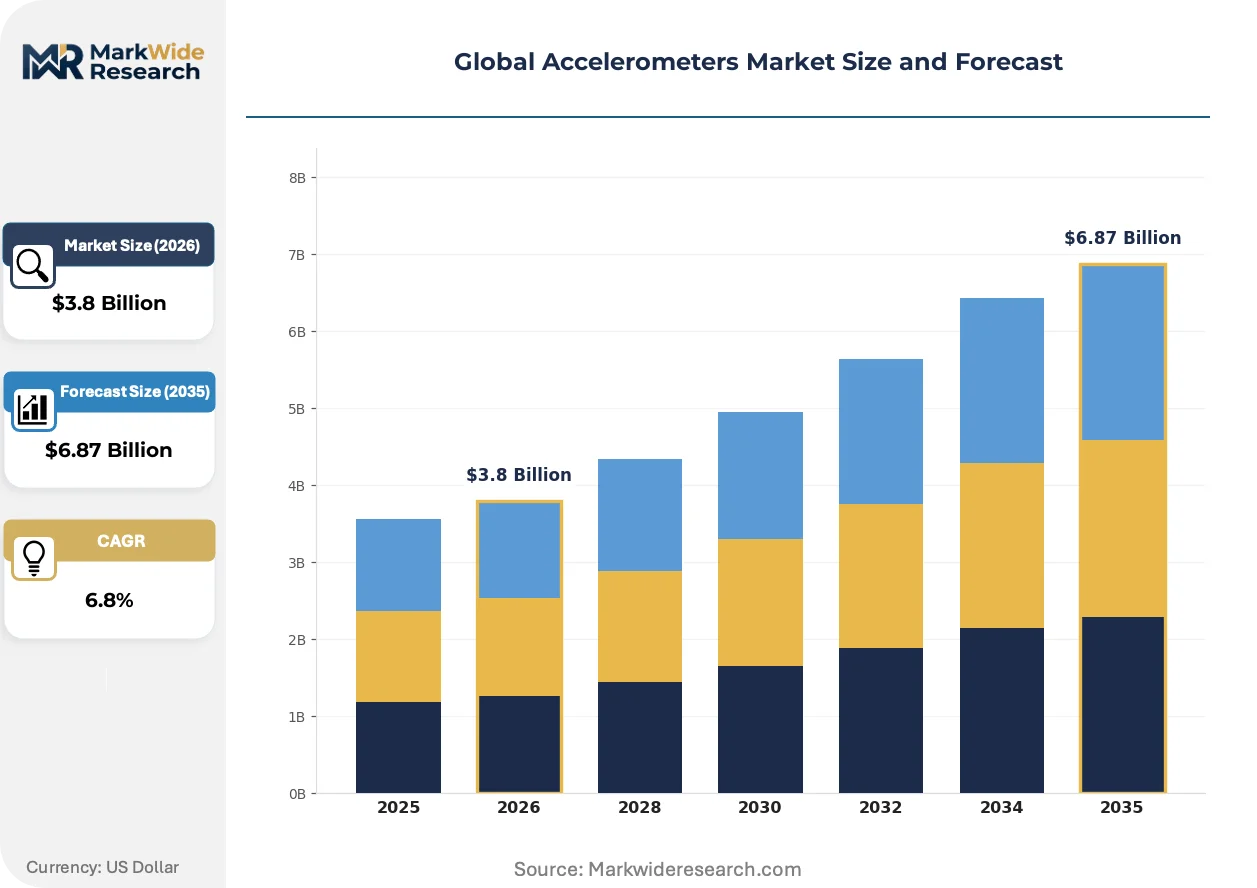
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: MEMS, Piezoelectric, Capacitive, Magnetic Application: Consumer Electronics, Automotive Safety, Aerospace, Industrial Automation End User: Manufacturers, Designers, Researchers, Automotive OEMs Technology: Analog, Digital, Wireless, Hybrid |
| Companies Covered | Analog Devices Inc., Robert Bosch GmbH, Honeywell International Inc., STMicroelectronics, TE Connectivity, Murata Manufacturing Co. Ltd., NXP Semiconductor, Safran SA, Meggitt PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Accelerometers Market Emerging Trajectories
Capacitive sensing architectures are displacing piezoresistive alternatives across temperature-sensitive applications, while regulatory pressure on functional safety and material transparency is rewriting procurement specifications.
Capacitive MEMS accelerometers detect inertial forces through electrostatic sensing of proof-mass displacement between fixed electrodes, offering superior temperature stability and self-test capability compared to piezoresistive variants. Automotive Tier-1 suppliers are adopting these designs for rollover detection and electronic stability control modules. The technology is migrating from consumer-grade tilt sensing into safety-critical automotive and medical applications where zero-g offset drift specifications below 1 mg are mandatory.
REACH substance restrictions and RoHS hazardous material limits are tightening compliance requirements for sensor packaging alloys and solder compositions in European-bound products. Manufacturers must reformulate lead-free interconnect materials and document full material declarations through SCIP database submissions. Medical device OEMs face the steepest adaptation burden, as biocompatibility requirements overlap with environmental substance restrictions.
Buying committees at automotive OEMs are consolidating accelerometer qualification under centralized sensor platform teams, displacing decentralized purchasing by individual vehicle line engineers. Tier-1 suppliers now engage directly with platform architects rather than component buyers, compressing the vendor selection window and elevating technical specification authority over price negotiation. This pattern is most visible in Germany and Japan, where platform standardization across multiple nameplates accelerates design-in consolidation.
Global Accelerometers Market Segmentation
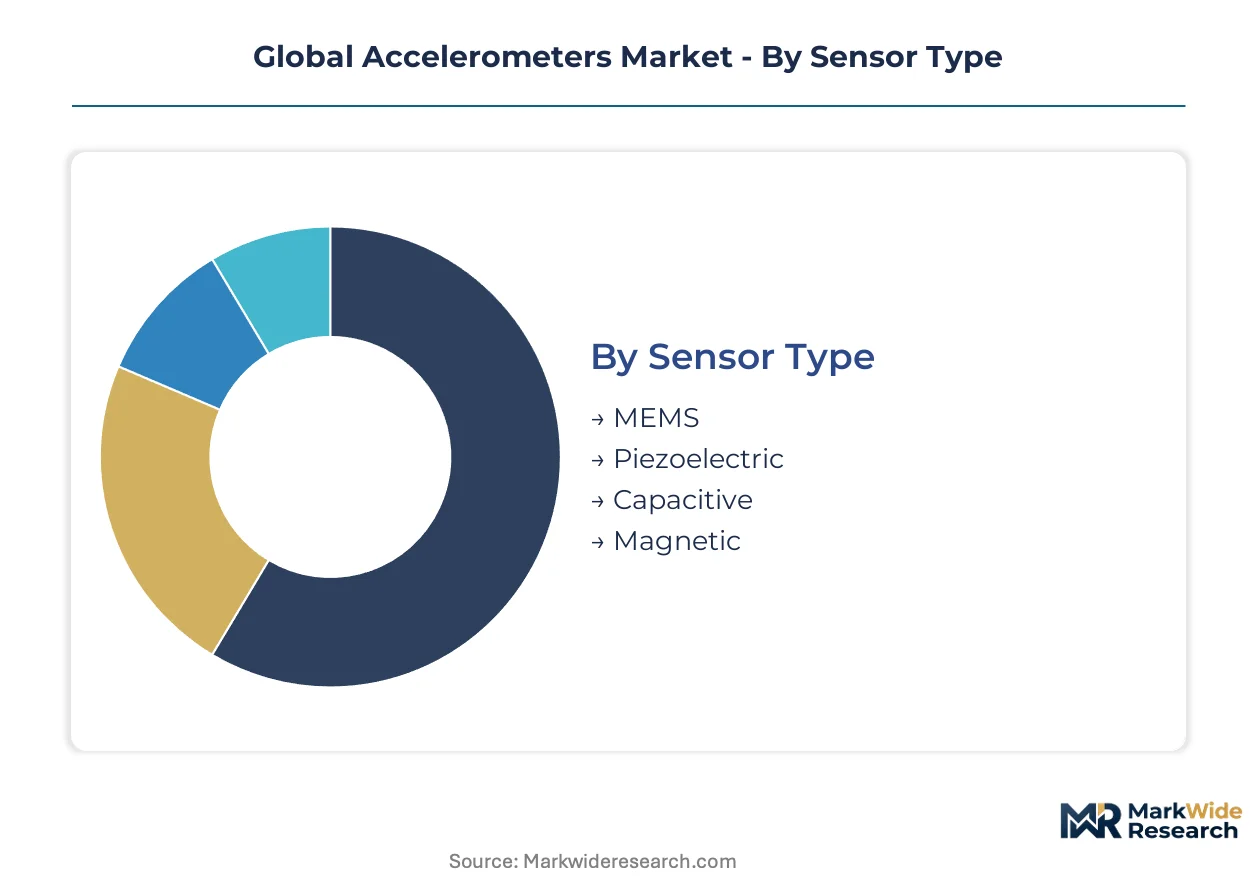
Accelerometer procurement decisions split across four distinct dimensions: underlying sensing physics, target use environment, buyer organizational type, and signal processing architecture. Each dimension carries different margin profiles, qualification timelines, and supplier concentration patterns that reshape competitive positioning.
Sensor Type:
Cost tier and performance ceiling separate the four sensing modalities, with semiconductor-scale manufacturing at the low end and precision-crafted crystals at the premium extreme.
- MEMS:Micromachined silicon structures fabricated on 200mm and 300mm wafers deliver micro-g to thousand-g sensitivity ranges at unit costs compatible with consumer electronics scale. Demand concentrates in China where Shanghai and Suzhou fabrication clusters absorb volume previously served by imported die, driven by domestic EV production scaling and MIIT-directed automotive certification requirements.
- Piezoelectric:Quartz and ceramic crystals generate charge output proportional to mechanical stress, maintaining signal integrity above 175°C where silicon degrades. Aerospace applications in the US and Europe still mandate these designs despite their four- to six-fold cost premium over MEMS alternatives, constrained by FAA and EASA thermal qualification standards.
- Capacitive:Electrostatic sensing of proof-mass displacement between fixed electrodes offers superior temperature stability for rollover detection modules.
- Magnetic:Hall-effect and magnetoresistive variants serve niche applications requiring immunity to electrostatic discharge events.
MEMS commands the established base. The steepest expansion runs through capacitive architectures migrating from consumer tilt sensing into automotive safety modules.
Application:
End-use environment dictates reliability grade, with automotive and aerospace imposing functional safety certification barriers that consumer electronics bypass entirely.
- Consumer Electronics:Miniaturized three-axis packages enable smartphone screen rotation, gaming motion control, and wearable activity tracking at sub-dollar price points. Designers prioritize footprint and power draw over absolute accuracy, sourcing predominantly from Taiwan and South Korea supply chains.
- Automotive Safety:Electronic stability control, airbag deployment, and advanced driver-assistance systems require AEC-Q100 qualification and ISO 26262 ASIL ratings. European OEMs under EU Green Deal mandates are compressing design cycles for regenerative braking optimization sensors.
- Aerospace:Navigation-grade and tactical-grade specifications demand bias stability below 1 mg and temperature operation to 200°C.
- Industrial Automation:Vibration monitoring for predictive maintenance networks is adopting wireless connectivity.
Automotive Safety generates the highest revenue per unit. Consumer Electronics delivers the steepest volume trajectory.
End User:
Procurement authority concentrates differently across organizational types, with platform consolidation at automotive OEMs displacing decentralized component purchasing.
- Automotive OEMs:Centralized sensor platform teams in Germany and Japan now control accelerometer qualification across multiple nameplates, compressing vendor selection windows and elevating technical specification authority over price negotiation.
- Manufacturers:Tier-1 and Tier-2 suppliers integrate accelerometers into subsystems for airbag modules, transmission controllers, and chassis electronics, managing AEC-Q100 stress testing and ISO 26262 certification on behalf of OEM customers.
- Designers:Engineering services firms and independent design houses specify accelerometers for custom industrial and medical devices.
- Researchers:Academic and government laboratories source specialty high-g and ultra-low-noise variants for experimental applications.
Automotive OEMs anchor premium-tier procurement. Manufacturers represent the broadest addressable base.
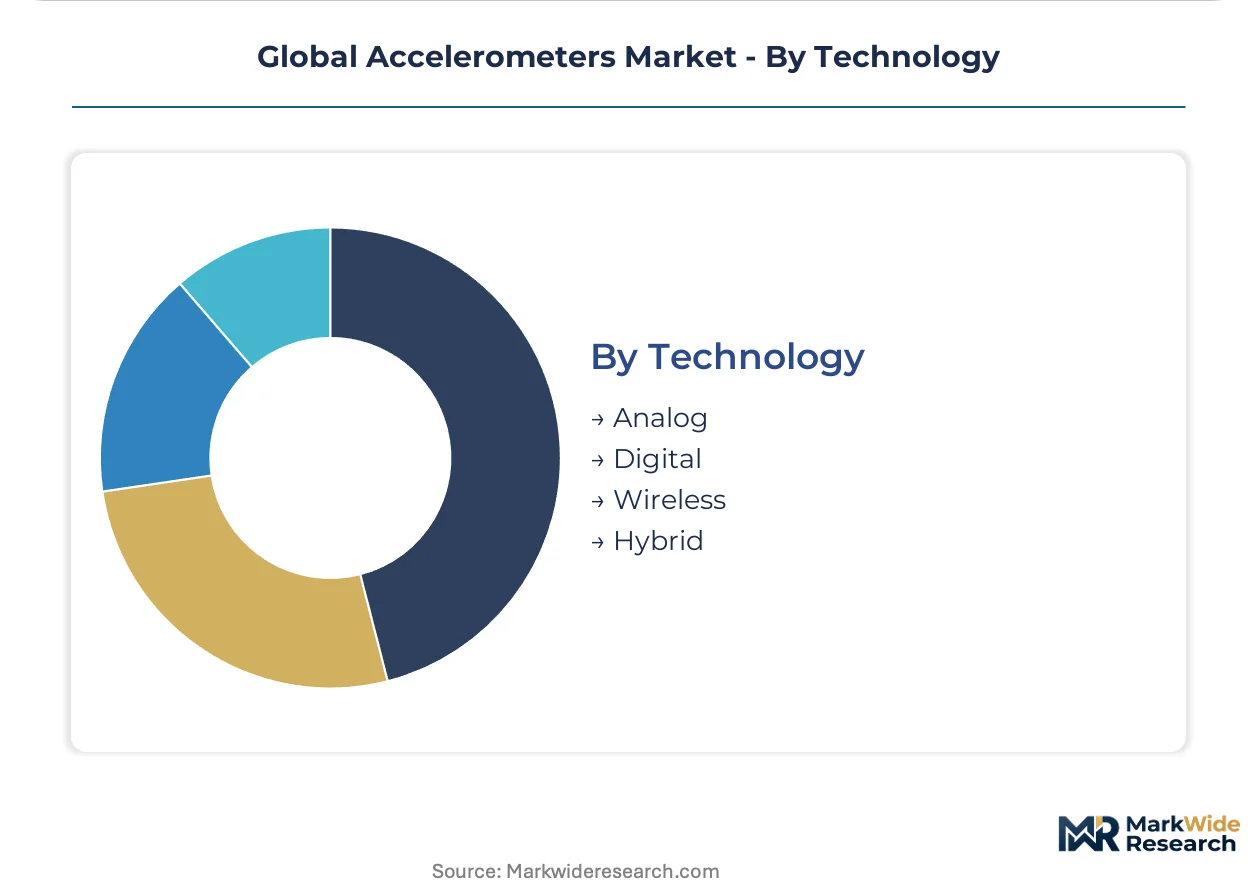
Technology:
Signal interface architecture determines system integration complexity, with digital protocols displacing analog signal chains in new automotive designs.
- Digital:SPI and I2C protocols simplify ECU integration and reduce wiring harness complexity. Automotive Tier-1 suppliers are adopting digital outputs exclusively for new electronic stability control and rollover detection modules.
- Analog:Voltage-output designs persist in industrial retrofit applications requiring compatibility with existing 4-20mA control loops.
- Wireless:LoRaWAN and Bluetooth Low Energy integration enables battery-free sensor nodes for rotating equipment monitoring in oil and gas infrastructure.
- Hybrid:Configurable devices offering both analog and digital outputs bridge legacy system upgrades.
Analog retains the installed base. Digital captures the steepest design-in momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys accelerometers predominantly for automotive safety and domestic EV production, while the United States concentrates demand in aerospace navigation and FDA-regulated medical devices. Germany anchors European procurement through centralized OEM platform teams. Japan sustains precision industrial applications. India generates emerging demand through industrial automation incentives.
China
Domestic EV production scaling and MIIT-directed automotive certification requirements absorb volume previously served by imported MEMS die. GB standards govern domestic MEMS certification for automotive integration. Shanghai and Suzhou fabrication clusters redirect supply chain gravity eastward as domestic production expands.
United States
FAA-mandated thermal qualification standards sustain demand for quartz and ceramic accelerometers in aerospace navigation systems. FDA oversight shapes medical-grade specifications for patient monitoring devices. Precision manufacturing concentrates in aerospace corridors serving defense and commercial aviation programs.
Germany
EU Green Deal vehicle safety mandates compress design cycles for regenerative braking optimization sensors. REACH and RoHS compliance restricts hazardous substances in sensor packaging for European-bound products. Centralized sensor platform teams in Stuttgart and Munich consolidate qualification across multiple OEM nameplates.
Japan
METI industrial policy supports precision MEMS fabrication for robotics and factory automation applications. JIS standards govern quality specifications for industrial-grade motion sensing. Nagoya and Osaka manufacturing belts maintain specialized expertise in high-reliability automotive and industrial sensors.
India
PLI scheme incentives for electronics manufacturing create captive demand for vibration monitoring in precision tooling. CEA regulations shape industrial equipment safety standards. Bangalore and Pune industrial corridors attract MEMS packaging investments serving domestic automation markets.
Global Accelerometers Market Vendor Landscape
Capability concentration sits with automotive heritage specialists; scale advantage sits with semiconductor fabricators serving consumer electronics. The market structures around three tiers: diversified industrial conglomerates with aerospace certification, automotive-focused MEMS specialists with AEC-Q100 portfolios, and consumer electronics scale players with miniaturization expertise. Dominant competitive moves include strategic partnerships for foundry capacity allocation and portfolio diversification into wireless connectivity modules.
Within the automotive heritage tier, Robert Bosch GmbH exemplifies European demand anchoring through functional safety certification depth. STMicroelectronics occupies a position bridging analog and digital product line breadth. Murata Manufacturing Co. Ltd. represents miniaturization specialization for consumer electronics scale. These three archetypes illustrate how geographic origin and corporate structure shape competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Robert Bosch GmbH |
| Honeywell International Inc. |
| STMicroelectronics |
| TE Connectivity |
| Murata Manufacturing Co. Ltd. |
| NXP Semiconductor |
| Safran SA |
| Meggitt PLC |
| Others |
Supply Flow & Price Mechanics
Shanghai and Suzhou fabrication clusters concentrate MEMS foundry capacity and compress pricing power for automotive-grade accelerometers, as domestic Chinese supply absorbs volume previously served by imported die and forces tier-1 suppliers to renegotiate long-term offtake terms.
Pricing Analysis
Long-term offtake agreements dominate procurement between automotive OEMs and MEMS foundries, with spot purchasing limited to consumer electronics tier. Price differentiation hinges on AEC-Q100 certification grade and volume scale, with ASIL-rated sensors commanding substantial premiums over industrial-grade alternatives. Pricing pressure stems from silicon-on-insulator substrate allocation constraints at 200mm and 300mm foundries. Consumer electronics buyers exhibit highest price sensitivity, while aerospace navigation systems demonstrate lowest sensitivity due to FAA-mandated thermal qualification requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard between Tier-1 automotive suppliers and MEMS foundries, reflecting capital intensity of AEC-Q100 qualification. Supply concentrates in China, Taiwan, and Germany. Raw material dependencies include silicon wafers, ceramic packaging substrates, and lead-free solder alloys. Single-source vulnerability persists for deep reactive ion etching equipment concentrated in Grenoble, Dresden, and Hsinchu. Distribution runs through Tier-1 subsystem integrators rather than direct OEM supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The accelerometer market represents high-growth disruption as EU Green Deal mandates and MIIT-directed automotive certification compress design cycles and recalibrate procurement authority toward centralized platform teams.
For Market Incumbents: Build certification moats by deepening AEC-Q100 and ISO 26262 ASIL portfolios before emerging Chinese foundries achieve comparable functional safety depth. Prioritize foundry capacity allocation in Shanghai and Suzhou clusters to defend against domestic substitution. Accelerate digital output interface standardization to lock in ECU integration relationships with German and Japanese OEM platform architects. For New Entrants and Emerging Players: Build out wireless predictive maintenance networks for industrial automation in India, where PLI scheme incentives create captive demand without entrenched supplier relationships. Target vibration monitoring applications in precision tooling and robotics as the most penetrable segment. Pursue LoRaWAN and Bluetooth Low Energy integration as the primary go-to-market angle, bypassing automotive qualification timelines entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive-focused MEMS specialists with AEC-Q100 portfolios over consumer electronics scale players facing margin compression. Long-term viability rests on functional safety certification depth rather than unit cost minimization. Watch for FDA Class II device reimbursement code expansions as the inflection indicator for medical-grade accelerometer demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Shanghai and Suzhou clusters absorb volume previously served by imported MEMS die. |
| Functional Safety Certification Investment | AEC-Q100 and ISO 26262 ASIL ratings lock in automotive OEM platform relationships. |
| Digital Interface Standardization | SPI and I2C protocols simplify ECU integration and reduce wiring harness complexity. |
| Wireless Connectivity Integration | LoRaWAN and Bluetooth Low Energy enable battery-free predictive maintenance networks. |
| Backward Integration into Packaging | In-house ceramic substrate production mitigates REACH and RoHS compliance risks. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across automotive OEM platform teams, Tier-1 subsystem integrators, MEMS foundry engineers, and industrial automation procurement leads. Primary interview insights were validated against secondary sources including MIIT certification databases, FDA 510(k) filings, ECHA SCIP material declarations, and AEC-Q100 test reports. Bottom-up unit demand estimates triangulated with top-down semiconductor fabrication capacity data.
Calibration against historical automotive production volumes and MEMS die shipments anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include sensing physics, application environment, end-user organizational type, and signal processing architecture. CAGRs were derived from regression analysis of adoption curves for digital output interfaces and wireless connectivity modules. Industry-specific inputs incorporated EU Green Deal implementation timelines and MIIT-directed certification requirements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic foundries or accelerated FDA reimbursement code expansions would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Conveyor Belt Tracking Devices Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Electric Pipette Controllers Market