
 Global Sensors and Actuators Market | 2026-2036
Global Sensors and Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sensors and Actuators Market Foresight
Edge-native AI inference is reshaping how sensor arrays process data before cloud transmission, compressing latency budgets for real-time industrial control. Infineon Technologies leverages its SiC and GaN power portfolio to anchor high-temperature actuator designs for automotive traction systems. Honeywell competes through aerospace-grade pressure sensing architectures that sustain certification advantages in commercial aviation. Bosch Sensortec specializes in consumer MEMS inertial units, dominating smartphone and wearable motion tracking with integrated sensor fusion algorithms.
Sensors and actuators are electromechanical devices that transduce physical quantities—temperature, pressure, displacement, acceleration, or optical intensity—into measurable electrical signals, or conversely convert electrical commands into mechanical motion, force, or position control, typically operating across millivolt-to-volt output ranges or nanometer-to-millimeter positioning resolutions. Their primary industrial purpose is closed-loop automation: enabling machines to perceive environmental states and execute corrective physical responses without human intervention. Temperature and pressure sensors lead installed bases across process industries where mature calibration standards protect margin pools, while MEMS technology represents the fastest-expanding fabrication platform as wafer-level batch processing collapses unit costs for motion and proximity functions. Optical sensing captures premium positioning in medical and aerospace applications where electromagnetic immunity and sub-micron accuracy justify higher price tiers.
The FDA digital health pre-certification pathway and EU AI Act conformity requirements are forcing sensor manufacturers to document algorithmic transparency and clinical validation for diagnostic-adjacent devices, raising barriers to market entry. ECHA REACH substance restrictions and RoHS substance thresholds constrain piezoelectric material selections and solder compositions in European-bound actuator assemblies. China's GB standards and NMPA medical device classifications impose parallel testing regimes for products entering clinical or industrial automation channels. Stakeholders must monitor divergence between FDA software-as-medical-device guidance and EU AI Act risk-classification thresholds to avoid redundant compliance architectures that fragment product development roadmaps.
Market Dynamics
Edge-native AI inference is compressing latency budgets for real-time industrial control, forcing sensor manufacturers to embed processing power directly at the sensing node rather than relying on cloud architectures. This architectural shift is reshaping R&D allocation, certification requirements, and supplier qualification criteria across precision manufacturing clusters.
Growth Catalysts
- EU AI Act conformity requirements:Risk-classification mandates for diagnostic-adjacent devices are accelerating documentation standards that favor established sensor suppliers with validation infrastructure.
- Silicon carbide power modules:High-temperature tolerance in automotive traction systems is expanding addressable markets for actuators previously limited by thermal derating curves.
- German precision manufacturing clusters:Factory automation buyers in Baden-Württemberg and Bavaria are expanding sensor deployments across assembly lines with integrated quality feedback loops.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependency on Chinese processing facilities creates price volatility and strategic vulnerability for rotary actuator manufacturers.
- ECHA REACH substance restrictions:Piezoelectric material selections and solder compositions face constrained formulation options for European-bound actuator assemblies.
- MEMS fabrication yield floors:Wafer-level batch processing limits unit cost compression below current thresholds for motion sensing functions in consumer electronics.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Component localization mandates are creating greenfield demand for sensor packaging and testing facilities serving smartphone and automotive export channels.
- Digital health pre-certification pathways:FDA's streamlined software-as-medical-device validation is opening diagnostic-adjacent applications for biometric sensors in remote patient monitoring.
- Photonic-MEMS convergence:Integrated optical interferometry with microelectromechanical positioning is enabling sub-nanometer metrology for semiconductor lithography equipment.
Industry Challenges
- Embedded firmware security certification:IEC 62443 compliance for industrial cybersecurity is extending product development timelines by 8-14 months for connected sensing devices.
- Multi-physics simulation talent scarcity:Electromechanical-acoustic-thermal co-design expertise remains concentrated among aging specialist engineers in automotive and aerospace supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sensors and Actuators Market |
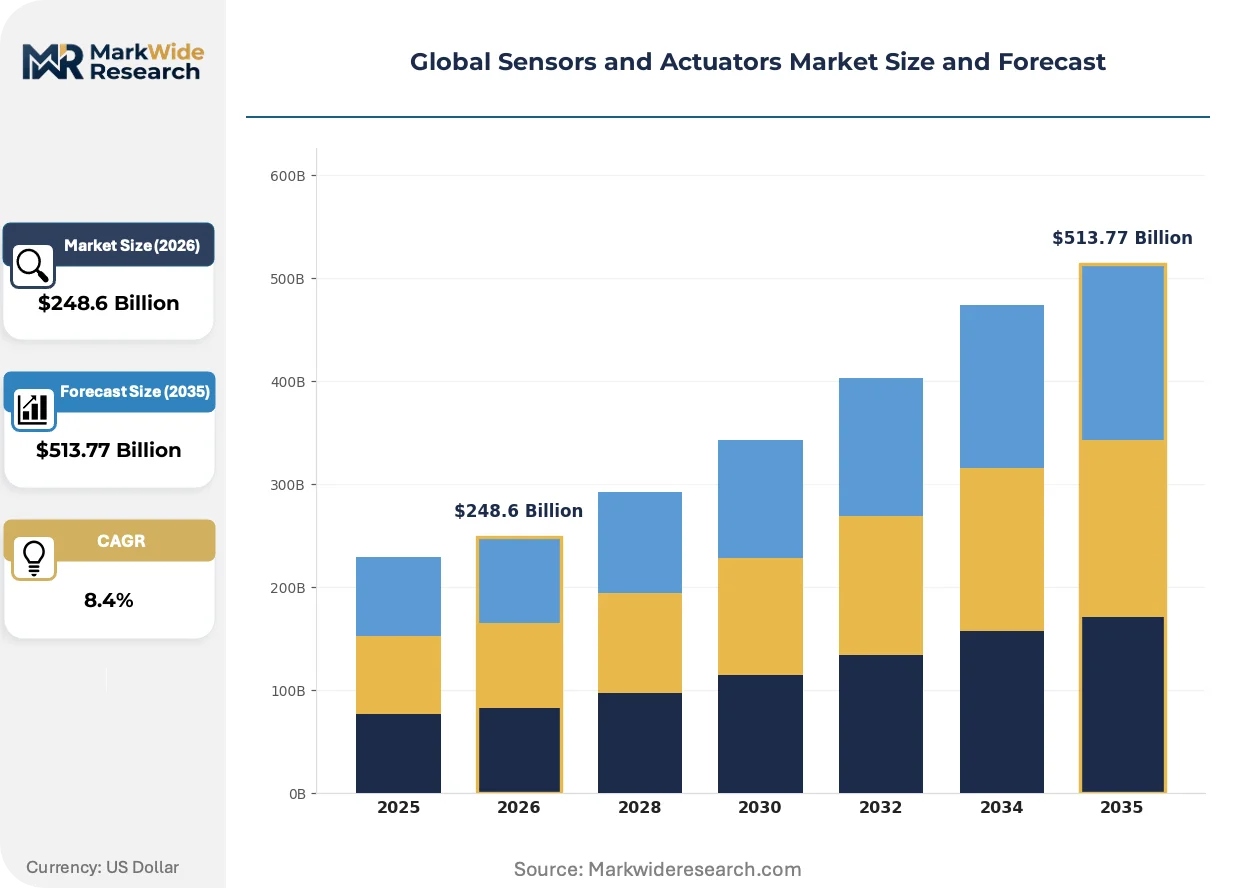
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $513.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Motion Sensors, Position Sensors Technology: MEMS, Optical Sensors, Ultrasonic Sensors, Capacitive Sensors, Inductive Sensors Application: Consumer Electronics, Aerospace Systems, Factory Automation, Agriculture Monitoring, Smart Energy Management End User: Automotive Suppliers, Telecommunications Providers, Manufacturing Plants, Renewable Energy Firms, Defense Contractors |
| Companies Covered | Infineon Technologies, Honeywell, Bosch Sensortec, Festo, Schneider Electric, Analog Devices, Siemens, Emerson Electric, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sensors and Actuators Market Shifts & Advancements
Sensor architectures are bifurcating between ultra-low-power edge inference nodes and high-fidelity measurement chains for safety-critical applications. This divergence is fragmenting semiconductor process roadmaps and qualification protocols.
Time-of-flight optical arrays are digitizing proximity sensing in warehouse robotics and autonomous mobile platforms. Logistics operators in the United States are deploying these modules at scale for pallet dimensioning and obstacle avoidance. The technology is digitizing spatial awareness workflows that previously required structured-light or stereoscopic camera systems with higher compute overhead.
Japan's METI carbon-neutrality technology roadmap is mandating efficiency thresholds for industrial motor systems that cascade into actuator specification requirements. PMDA medical device software guidance is paralleling FDA digital health frameworks, creating dual-track validation obligations for diagnostic sensor suppliers. Automotive and medical device segments are responding with unified quality management systems spanning both regulatory jurisdictions.
Japanese automotive OEMs are consolidating sensor procurement through tier-one system integrators rather than direct component sourcing. This channel compression is displacing traditional distributor relationships and favoring suppliers with subsystem design capabilities. The pattern is most visible in hybrid vehicle powertrain sensor suites where Denso and Aisin dominate specification authority.
Global Sensors and Actuators Market Segmentation
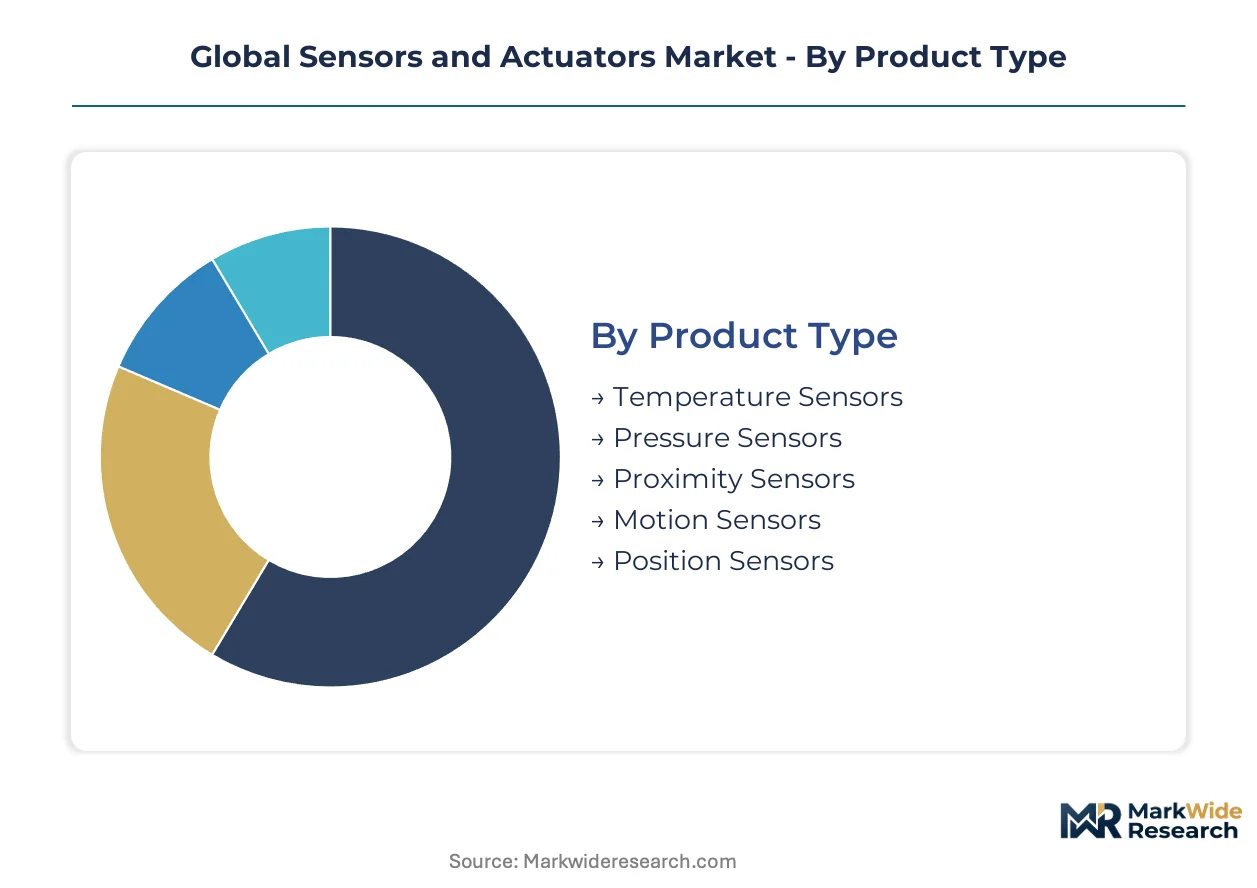
Sensor and actuator architectures fragment across competing performance priorities: cost-sensitive consumer applications demand wafer-scale integration, while safety-critical aerospace and medical installations require traceable calibration chains and redundant sensing paths. The segmentation below maps how these divergent requirements reshape supplier capabilities and procurement patterns.
Product Type:
Mature sensing modalities anchor high-volume industrial bases, while emerging proximity and motion variants capture deployment momentum in robotics and autonomous platforms.
- Temperature Sensors:Thermocouple, RTD, and thermistor architectures span -200°C to 1700°C measurement ranges with established IEC 60584 calibration protocols. Process industries in Germany and the United States maintain dense installed bases where sensor replacement cycles protect aftermarket revenue pools.
- Pressure Sensors:Piezoresistive MEMS and thin-film strain gauge designs transduce absolute, gauge, and differential pressures across 0.1 mbar to 10,000 bar spans. Automotive brake-by-wire and HVAC refrigerant monitoring in Japan concentrate procurement for high-reliability variants.
- Proximity Sensors:Eddy-current, capacitive, and magnetic proximity devices detect object presence without mechanical contact. Warehouse robotics deployments in the United States are accelerating inductive and photoelectric proximity module procurement.
- Motion Sensors:Accelerometer, gyroscope, and IMU packages combine multi-axis inertial measurement for navigation and vibration monitoring. Wearable device manufacturers source compact MEMS motion sensing from Taiwanese packaging facilities.
- Position Sensors:LVDT, potentiometric, and magnetostrictive technologies deliver sub-micron displacement feedback for CNC machine tools and hydraulic cylinders. Machine tool builders in Baden-Württemberg specify ruggedized position sensing for metal-cutting applications.
Temperature sensors retain volume leadership; motion sensors hold the steepest expansion curve.
Technology:
Cost tier stratification separates commodity wafer-scale fabrication from precision optical and ultrasonic architectures requiring specialized assembly and calibration infrastructure.
- MEMS:Bulk and surface micromachining processes etch mechanical structures into silicon substrates for pressure, inertial, and acoustic sensing. Smartphone and automotive safety system volumes in South Korea and China drive foundry capacity expansion for consumer-grade MEMS.
- Optical Sensors:Photodiode arrays, fiber Bragg gratings, and interferometric encoders convert light intensity or wavelength shifts into electrical signals. Semiconductor lithography equipment manufacturers in the Netherlands specify sub-nanometer optical position feedback for wafer stage positioning.
- Ultrasonic Sensors:Piezoelectric transducers emit and receive acoustic pulses for distance measurement and flow metering. Automotive parking assist and industrial level sensing applications in Mexico and Thailand concentrate mid-range ultrasonic module demand.
- Capacitive Sensors:Variable capacitance architectures detect proximity, humidity, and touch input with low power consumption. White goods and touch interface manufacturers in Poland and Vietnam integrate capacitive sensing for appliance control panels.
- Inductive Sensors:Coil-based proximity detection resists contamination in metalworking and welding environments. Automotive powertrain plants in Stuttgart and Detroit specify inductive position sensing for camshaft and crankshaft timing.
MEMS dominates unit economics; optical sensing commands the premium tier.
Application:
Customer type divergence separates high-volume consumer electronics procurement from project-based aerospace and agricultural sensing deployments.
- Consumer Electronics:Smartphone, tablet, and wearable devices integrate motion, environmental, and optical sensing for user interface and health monitoring. Assembly plants in India and Vietnam under PLI localization mandates are expanding sensor packaging capacity for export markets.
- Aerospace Systems:Flight-critical pressure, temperature, and position sensing must satisfy DO-160G environmental qualification and DO-178C software assurance. Honeywell and Collins Aerospace specification authority in Wichita and Phoenix shapes supplier qualification requirements.
- Factory Automation:PLC-integrated sensing arrays enable closed-loop control of robotic arms, conveyor systems, and quality inspection stations. Bavarian automotive assembly lines are deploying sensor networks with edge-native AI inference for predictive maintenance.
- Agriculture Monitoring:Soil moisture, weather station, and livestock tracking sensors support precision irrigation and yield optimization. Large-scale farming operations in Brazil's Mato Grosso and Australia's Murray-Darling basin are digitizing input management.
- Smart Energy Management:Grid-tied voltage, current, and power quality sensors enable demand response and distributed generation integration. German Energiewende policy is accelerating smart meter and transformer monitoring deployments.
Factory automation captures the largest revenue pool; agriculture monitoring is climbing the fastest.
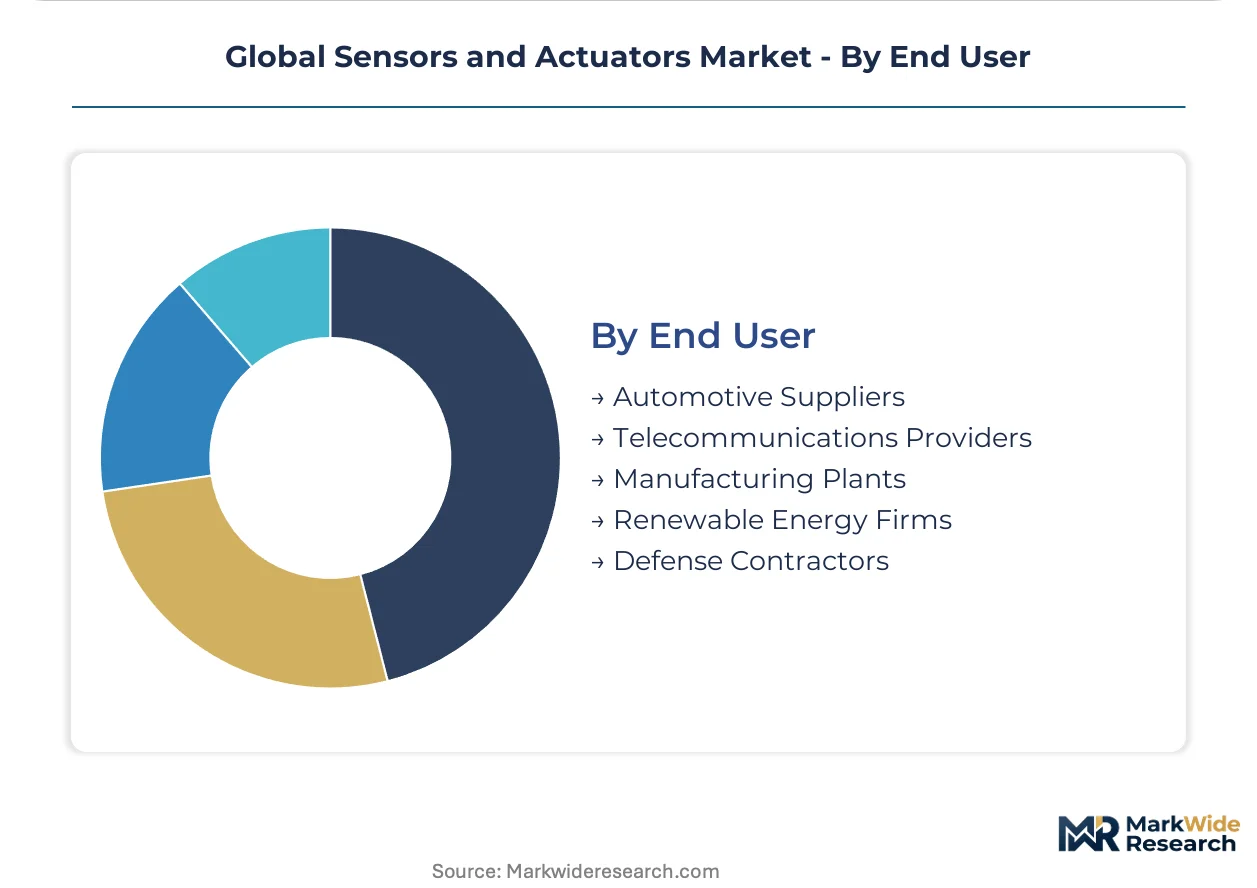
End User:
Supply concentration patterns align with geographic clustering of precision manufacturing, telecommunications infrastructure, and defense industrial bases.
- Automotive Suppliers:Tier-one system integrators consolidate sensor procurement for powertrain, chassis, and ADAS subsystems. Denso and Aisin specification authority is displacing direct OEM-component relationships in Japanese hybrid vehicle programs.
- Telecommunications Providers:Base station environmental monitoring and fiber optic network sensing support infrastructure reliability. 5G rollout schedules in Saudi Arabia and South Africa are driving demand for ruggedized outdoor sensor modules.
- Manufacturing Plants:Discrete and process automation buyers deploy sensing arrays for quality feedback, safety interlocks, and energy optimization. Baden-Württemberg machine tool builders specify integrated sensor-actuator packages with predictive analytics.
- Renewable Energy Firms:Wind turbine vibration monitoring and solar array tracking systems depend on position and environmental sensing. Offshore wind developers in the North Sea are specifying corrosion-resistant sensor architectures.
- Defense Contractors:MIL-STD-810H environmental qualification and TEMPEST electromagnetic security constrain supplier selection. US Department of Defense supply chain security directives are reshaping sourcing for navigation and targeting sensors.
Automotive suppliers command the deepest specification authority; renewable energy firms are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Germany and Japan running structural surpluses in precision sensor assemblies, while the United States and China balance substantial cross-border component flows. India's electronics manufacturing incentives are redrawing sourcing patterns for consumer-grade MEMS packaging.
Germany
Automotive electrification and Industrie 4.0 deployments drive sensor procurement from Baden-Württemberg machine tool builders and Bavarian assembly lines. ECHA REACH substance restrictions constrain piezoelectric formulations for European-bound actuator exports. Stuttgart's precision manufacturing clusters specify integrated sensor-actuator packages with edge-native AI inference for predictive maintenance workflows.
United States
Warehouse robotics operators and commercial aviation suppliers anchor demand for time-of-flight optical arrays and aerospace-grade pressure sensing. FDA digital health pre-certification pathways open diagnostic-adjacent applications for biometric sensors in remote patient monitoring. Wichita and Phoenix aerospace hubs sustain qualification requirements that shape supplier selection for flight-critical sensing architectures.
Japan
Hybrid vehicle powertrain sensor suites and consumer electronics MEMS inertial units concentrate procurement through tier-one system integrators. METI carbon-neutrality technology roadmaps mandate efficiency thresholds for industrial motor systems that cascade into actuator specifications. Nagoya's automotive supplier ecosystem consolidates sourcing through Denso and Aisin specification authority, displacing direct OEM-component relationships.
China
Smartphone assembly plants and automotive safety system volumes drive foundry capacity expansion for consumer-grade MEMS. GB standards and NMPA medical device classifications impose parallel testing regimes for products entering clinical or industrial automation channels. Yangtze River Delta electronics manufacturing clusters integrate sensor packaging for export markets under localization mandates.
India
Smartphone and wearable device assembly under PLI scheme localization incentives creates greenfield demand for sensor packaging and testing facilities. BIS certification requirements and electronics manufacturing subsidies reshape component sourcing for export channels. Tamil Nadu and Karnataka smartphone assembly hubs expand MEMS motion sensing procurement from Taiwanese packaging partners.
Global Sensors and Actuators Market Competitive Landscape
On the supply side, the industry is tiered between diversified industrial conglomerates with subsystem integration capabilities and specialized semiconductor fabricators focused on discrete sensing elements. Strategic archetypes include MEMS foundry operators, aerospace-grade certification specialists, and power electronics-anchored actuator designers. Competitive moves center on tier-one system integrator partnerships and backward integration into wafer-level fabrication capacity.
Among diversified industrial technology groups, Siemens and Schneider Electric exemplify subsystem integration capabilities spanning factory automation and energy management applications. Infineon Technologies anchors the power electronics-anchored archetype through its SiC and GaN portfolio. Bosch Sensortec occupies a specialist position in consumer MEMS inertial units. STMicroelectronics and Analog Devices represent semiconductor fabricators with broad sensing element portfolios. Honeywell exemplifies the aerospace-grade certification specialist archetype.
| Leading Market Players |
|---|
| Infineon Technologies |
| Honeywell |
| Bosch Sensortec |
| Festo |
| Schneider Electric |
| Analog Devices |
| Siemens |
| Emerson Electric |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Rare earth magnet processing concentration in Chinese facilities anchors cost volatility for rotary actuator manufacturers, with neodymium and dysprosium price swings cascading into margin compression for automotive and industrial motor suppliers downstream. This upstream dependency concentrates pricing power among magnet processors while forcing actuator OEMs to absorb input cost spikes or pass through to tier-one automotive integrators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with aerospace-grade pressure sensing commanding certification premiums against commoditized consumer MEMS. Price differentiation rests on FDA pre-certification status and ISO 26262 automotive safety integrity levels. Cost compression in standard-tier proximity sensing is intensifying because wafer-level MEMS yield floors limit further unit cost reductions. Automotive tier-one integrators exhibit lowest price sensitivity due to specification lock-in, while white goods manufacturers in Vietnam and Poland drive hardest volume negotiations.
Supply Chain Analysis
TSMC and GlobalFoundries MEMS foundry capacity in Taiwan, South Korea, and the United States anchors wafer supply for motion and pressure sensing die. Raw material flows draw from Malaysian packaging substrates, Japanese piezoelectric ceramics, and Chinese rare earth magnet feedstocks. Single-source vulnerability concentrates in Taiwanese foundry capacity for automotive safety-grade MEMS. Distribution runs through tier-one system integrators like Denso and Aisin in Japan, displacing traditional distributor relationships for hybrid powertrain sensor suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions. FDA and EU AI Act validation infrastructure creates switching costs that emerging suppliers cannot replicate without 18-24 month compliance timelines.
For Market Incumbents: Insulate specification authority by deepening backward integration into SiC power module production for high-temperature actuator designs. Lock in tier-one automotive partnerships through subsystem co-development agreements that embed sensors within Denso and Aisin powertrain platforms. Threats from Chinese MEMS foundries with government subsidized capacity additions in Yangtze River Delta clusters demand preemptive capacity reservations at TSMC and GlobalFoundries. For New Entrants and Emerging Players: Build out photonic-MEMS convergence capabilities for semiconductor lithography metrology, where sub-nanometer positioning requirements sustain premium pricing and limited supplier bases. India's PLI scheme for electronics manufacturing offers the most penetrable geography, with Tamil Nadu and Karnataka smartphone assembly hubs creating greenfield demand for packaging and testing facilities. Go-to-market positioning should emphasize BIS certification readiness for export channel access under localization mandates. For Investors and Strategic Acquirers: Capital is best deployed toward aerospace-grade certification specialists with DO-160G and DO-178C qualification infrastructure, given decade-long commercial aviation product lifecycles and limited supplier bases. Long-term viability over the analysis window favors targets with embedded firmware security certification for IEC 62443 compliance. Signal to watch: PMDA harmonization with FDA digital health frameworks, which would consolidate dual-track validation obligations and favor suppliers with unified quality management systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Wafer Production | Infineon Technologies leverages captive supply to anchor high-temperature automotive actuator designs. |
| FDA Digital Health Pre-Certification Pathway | Streamlined validation opens diagnostic-adjacent biometric sensor applications for remote patient monitoring. |
| Tier-One System Integrator Partnership | Denso and Aisin specification authority in Japan displaces direct OEM relationships for hybrid powertrain suites. |
| Photonic-MEMS Convergence R&D | Integrated optical interferometry enables sub-nanometer metrology for Netherlands-based lithography equipment. |
| India PLI Localization Compliance | BIS certification and Tamil Nadu assembly hub proximity secure smartphone export channel access. |
Research Methodology
Initial hypotheses were tested against primary input from automotive tier-one procurement directors, MEMS foundry operations managers, aerospace certification engineers, and industrial automation plant engineers, then refined through secondary validation. Primary fieldwork encompassed FDA regulatory affairs specialists and EU notified body representatives for AI Act conformity assessment. Secondary sources included SEC 10-K filings from diversified industrial technology groups, ECHA REACH substance restriction databases, and IHS Markit automotive production data. Bottom-up sensor unit shipment estimates were triangulated against top-down factory automation capex forecasts.
Demand-supply balance modeling across the projection horizon segmented volume by product type, technology platform, application vertical, and end-user concentration. Modeled dimensions included MEMS versus optical versus ultrasonic technology tiers, consumer electronics versus aerospace versus factory automation applications, and automotive supplier versus telecommunications provider versus renewable energy firm end-user categories. CAGRs were derived from regression analysis of historical shipment data against industrial production indices and semiconductor capital equipment spending. Industry-specific inputs incorporated METI carbon-neutrality efficiency thresholds and German Industrie 4.0 deployment schedules.
Stress conditions across rare earth magnet price volatility, Taiwanese foundry capacity utilization, and EU AI Act implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding continued automotive electrification capex and sustained precision manufacturing cluster expansion in Baden-Württemberg and Bavaria. Quarterly review of BIS certification processing times, TSMC MEMS foundry utilization rates, and PMDA-FDA harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Calibrator Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Global Signal Conditioning Modules Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market