
 Global Continuous Peripheral Nerve Block Catheter Market | 2026-2036
Global Continuous Peripheral Nerve Block Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Continuous Peripheral Nerve Block Catheter Market Intelligence
Anesthesiologist workforce shortages in perioperative pain management is collapsing access to conventional nerve block services in community hospitals across the United States, Australia, and Brazil. Teleflex Incorporated leverages its broad critical care portfolio to sustain catheter placement technology leadership in acute care settings. B. Braun Melsungen AG anchors European manufacturing scale for regional anesthesia delivery systems. Pajunk GmbH specializes in precision-engineered stimulation-guided catheter designs that dominate German-speaking clinical markets.
A continuous peripheral nerve block catheter is a flexible, multi-lumen medical device inserted adjacent to peripheral nerves to deliver local anesthetic solutions for prolonged postoperative or chronic pain control, typically featuring radiopaque markers and closed-tip designs with side port configurations. The device enables targeted neural blockade lasting 48–96 hours, reducing systemic opioid exposure and supporting early mobilization protocols in orthopedic and trauma surgery. Ultrasound compatible catheters now lead product type demand as image-guided placement becomes standard of care in surgical centers and pain clinics across deployment settings. Postoperative analgesia remains the largest application segment, though chronic pain management represents the fastest-growing margin pool as ambulatory care units expand interventional services beyond hospital settings.
The FDA 510(k) pathway governs catheter material biocompatibility and sterility assurance in the United States, while the EU Medical Device Regulation mandates clinical evidence standards for extended-duration indwelling devices in European markets. Japan's PMDA enforces JIS-compliant polymer validation for catheter tensile strength and kink resistance under METI oversight. Stakeholders must monitor evolving notified body capacity in Europe and FDA guidance on antimicrobial-coated surfaces to anticipate compliance costs and competitive differentiation timelines.
Market Dynamics
Ultrasound-guided catheter placement is collapsing the learning curve for regional anesthesia, expanding deployment beyond academic medical centers into community hospitals and ambulatory surgical centers where anesthesiologist density previously blocked adoption.
Growth Catalysts
- Enhanced Recovery After Surgery protocols:ERAS mandates in orthopedic and colorectal surgery are institutionalizing multimodal analgesia, embedding continuous nerve block catheters as standard perioperative infrastructure in United States health systems.
- FDA 510(k) streamlining:The FDA's evolving premarket notification pathways for pain management devices are compressing clearance timelines for catheter material innovations and antimicrobial surface coatings.
- Ambulatory surgical center expansion:Outpatient orthopedic procedure volume in Germany and Japan is concentrating demand for disposable catheter systems designed for 48–72 hour postoperative analgesia protocols.
Market Restraints
- Polymer supply concentration:Medical-grade polyurethane and silicone raw material production concentrates among a limited supplier base in Germany and Switzerland, exposing catheter manufacturers to input cost volatility and allocation risk.
- EU MDR clinical evidence requirements:The EU Medical Device Regulation mandates extended-duration biocompatibility studies for indwelling catheters, extending compliance timelines and elevating notified body review costs for European market entry.
- Opioid-sparing substitution:Liposomal bupivacaine and other long-acting local anesthetic formulations are capturing select orthopedic procedures that previously required indwelling catheter systems.
Strategic Opportunities
- Brazilian market underpenetration:Regional anesthesia training program expansion in São Paulo and Rio de Janeiro clinical networks is creating first-mover advantage for catheter manufacturers establishing distributor relationships ahead of infrastructure maturation.
- Chronic pain ambulatory pivot:Interventional pain clinics in the United States are extending catheter-based neural blockade beyond postoperative applications into complex regional pain syndrome and cancer pain management.
- Telehealth-integrated remote monitoring:Convergence of disposable infusion pumps with cellular connectivity platforms is enabling home-based catheter management, opening reimbursement pathways for 72-hour ambulatory discharge protocols.
Industry Challenges
- Regional anesthesia skill scarcity:Fellowship-trained acute pain specialists remain concentrated in academic medical centers, constraining catheter placement quality assurance and complication management in community hospital settings.
- Antimicrobial coating validation timelines:FDA and PMDA evidentiary requirements for silver-ion or antibiotic-impregnated catheter surfaces are extending development cycles and elevating clinical trial costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Continuous Peripheral Nerve Block Catheter Market |
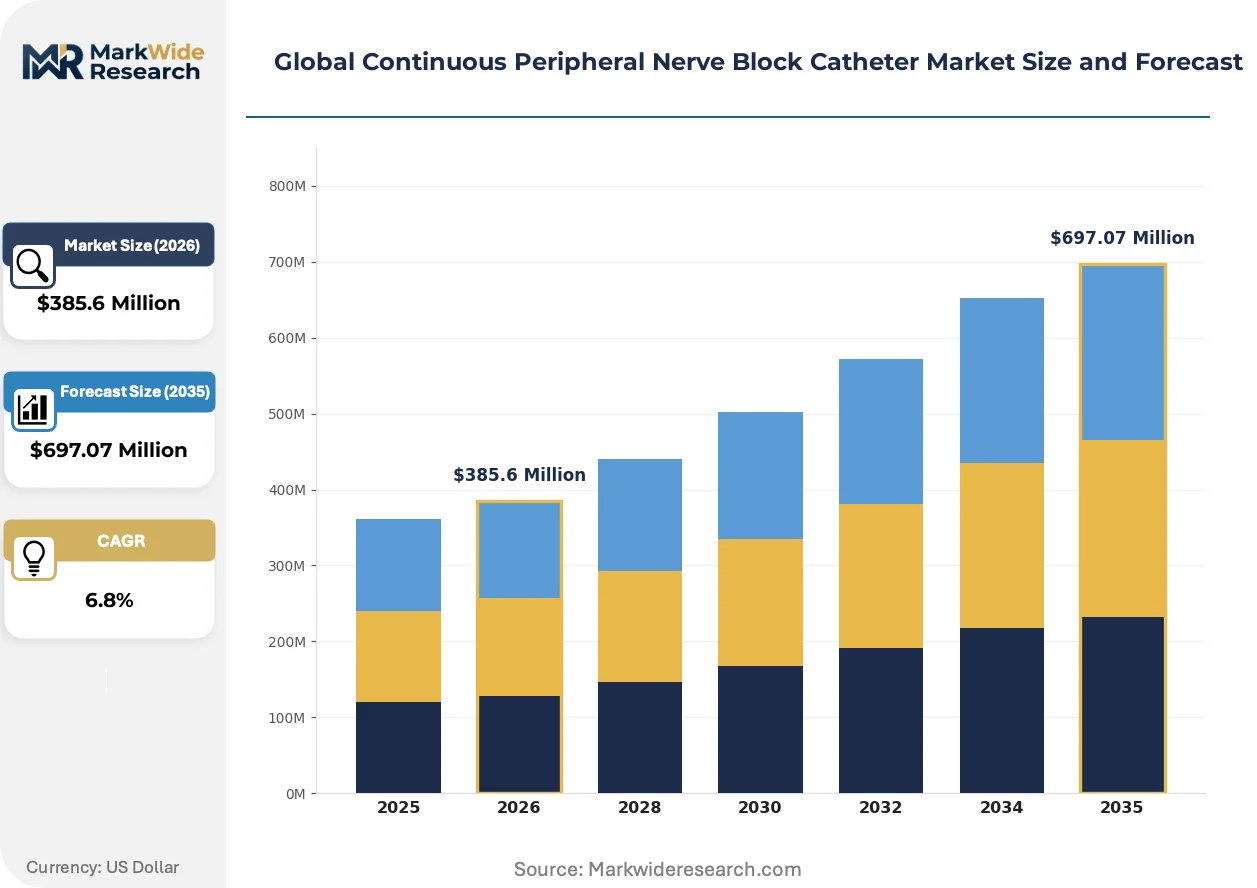
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peripheral Nerve Stimulator Catheters, Non-Stimulator Catheters, Ultrasound Compatible Catheters, Multi-orifice Catheters Application: Postoperative Analgesia, Chronic Pain Management, Labor Analgesia, Trauma Anesthesia End User: Surgical Centers, Pain Clinics, Ambulatory Care Units, Rehabilitation Facilities Deployment: Hospital Settings, Outpatient Clinics, Home Care, Specialty Pain Management Centers |
| Companies Covered | Teleflex Incorporated, B. Braun Melsungen AG, Pajunk GmbH, Halyard Health, Inc., Epimed International Inc., Ambu A/S, ICU Medical, Inc., Avanos Medical, Inc., Vygon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Continuous Peripheral Nerve Block Catheter Market Strategic Shifts & Innovations
Catheter engineering is converging with digital health infrastructure, reshaping how placement accuracy, infusion compliance, and complication surveillance are managed across decentralized care settings.
Multi-orifice catheter tip designs incorporating echogenic materials are miniaturizing while maintaining flow characteristics, enabling 18–20 gauge systems that reduce insertion trauma without compromising local anesthetic distribution. Ambulatory surgery centers in the United States are adopting these profiles for same-day discharge protocols. The technology is miniaturizing access requirements, allowing non-specialist anesthesiologists to achieve comparable block success rates with reduced procedure time.
The EU Medical Device Regulation's clinical evidence standards for extended-duration indwelling devices are elevating post-market surveillance obligations for catheter manufacturers serving European markets. Notified body capacity constraints in Germany and France are extending conformity assessment timelines. Premium catheter suppliers are responding by consolidating clinical data packages across multiple member states to streamline recertification cycles.
Hospital procurement committees are unbundling catheter-pump combinations that were previously sourced as integrated kits, creating direct purchasing relationships with disposable infusion device specialists. This pattern disrupts traditional critical care distribution channels in the United States and concentrates price negotiation leverage among integrated delivery networks. The shift is most visible in orthopedic service lines where standardized ERAS protocols enable specification of single-source catheter components independent of pump hardware.
Global Continuous Peripheral Nerve Block Catheter Market Segmentation
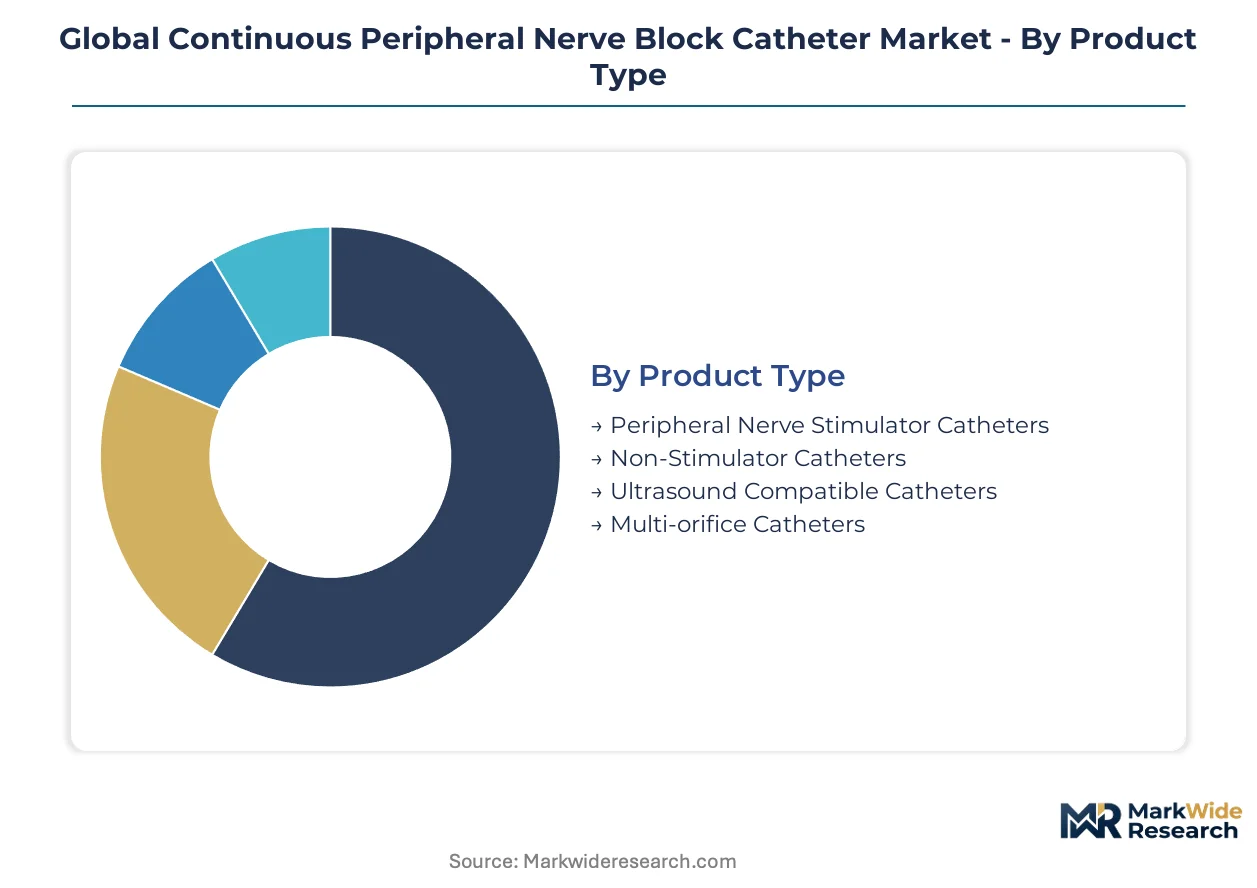
Catheter manufacturers navigate divergent technical requirements across placement modalities and care settings. Substitution threats from long-acting local anesthetics and infusion pumps reshape which segment configurations retain pricing power.
Product Type:
Non-stimulator designs face the most acute substitution pressure as ultrasound guidance collapses demand for electrophysiological confirmation in routine orthopedic cases.
- Peripheral Nerve Stimulator Catheters:These devices incorporate conductive elements for electrophysiological nerve localization during placement. Demand concentrates in German-speaking European markets where anesthesiology training programs retain stimulation-guided protocols as competency benchmarks.
- Ultrasound Compatible Catheters:Echogenic materials and optimized acoustic interfaces enable real-time visualization during image-guided placement. United States academic medical centers drive volume as residency programs standardize ultrasound-first curricula for regional anesthesia certification.
- Non-Stimulator Catheters:Simplified polymer constructions without conductive elements serve cost-sensitive procurement in high-volume ambulatory settings. Japanese surgical centers specify these for standardized knee arthroscopy protocols.
- Multi-orifice Catheters:Distributed side-port configurations improve local anesthetic spread patterns. Australian trauma networks specify these for continuous interscalene blockade in shoulder reconstruction cases.
Ultrasound compatible catheters retain volume leadership; multi-orifice configurations hold the steepest expansion curve.
Application:
Cost tier stratification separates acute postoperative protocols from chronic pain interventions requiring extended reimbursement navigation.
- Postoperative Analgesia:Standardized 48–72 hour infusion protocols dominate orthopedic and colorectal service lines. United States integrated delivery networks embed these in ERAS pathways for total joint replacement.
- Chronic Pain Management:Complex regional pain syndrome and cancer-related neuralgia applications require specialized pump integration. Interventional pain clinics in São Paulo and Rio de Janeiro are expanding catheter-based neural blockade beyond surgical indications.
- Labor Analgesia:Continuous epidural alternatives for obstetric anesthesia utilize modified catheter geometries. Maternity hospitals in Tokyo specify these for ambulatory labor protocols.
- Trauma Anesthesia:Battlefield-expedient and emergency department placements prioritize rapid insertion characteristics. German trauma networks specify kink-resistant constructions for prehospital deployment.
Postoperative analgesia retains volume leadership; chronic pain management commands the steepest expansion curve.
End User:
Customer type determines procurement sophistication, with integrated delivery networks unbundling catheter-pump combinations that ambulatory sites still source as kits.
- Surgical Centers:High-volume orthopedic facilities standardize on single-source catheter specifications matched to ERAS protocols. United States same-day discharge mandates concentrate demand for 48-hour disposable systems.
- Pain Clinics:Interventional specialists require programmable infusion compatibility for titrated chronic pain management. German private pain networks specify these for outpatient cancer pain protocols.
- Ambulatory Care Units:Mixed-service facilities balance cost constraints across procedure types. Japanese day-surgery centers prioritize compact packaging for limited storage footprints.
- Rehabilitation Facilities:Post-acute settings utilize simplified catheter management for extended mobilization protocols. Brazilian physical medicine departments are piloting these for complex regional pain syndrome recovery.
Surgical centers retain volume leadership; pain clinics command the steepest expansion curve.
Deployment:
Supply concentration in polymer raw materials shapes which deployment settings can absorb cost volatility without specification downgrades.
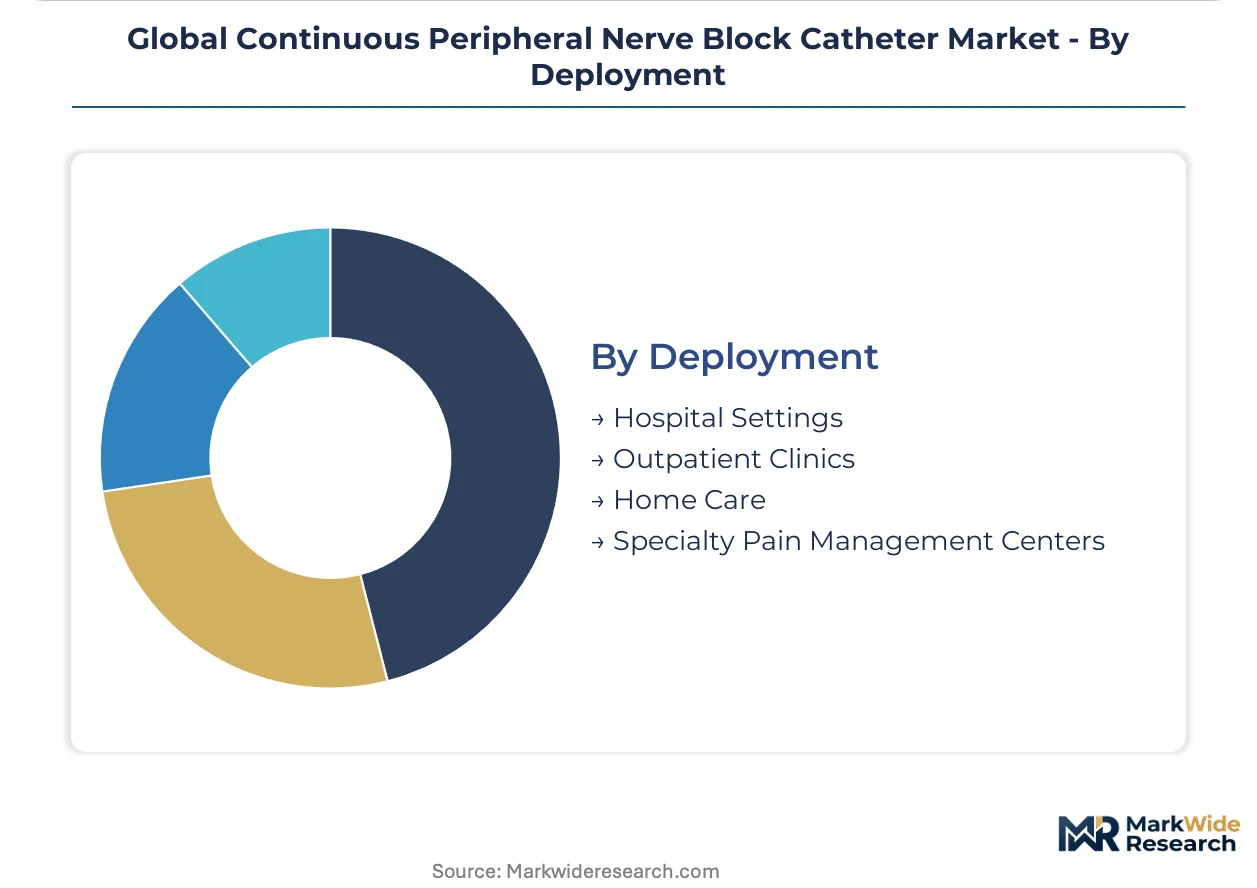
- Hospital Settings:Inpatient surgical floors utilize integrated pump systems with centralized pharmacy oversight. United States health systems specify antimicrobial-coated surfaces for extended indwelling duration.
- Outpatient Clinics:Limited-procedure facilities prioritize pre-assembled kits reducing preparation time. German orthopedic day clinics specify these for standardized shoulder arthroscopy volumes.
- Home Care:Discharge protocols require patient-managed infusion with remote monitoring capability. Australian home health networks are piloting cellular-connected pumps for 72-hour ambulatory protocols.
- Specialty Pain Management Centers:Dedicated facilities combine advanced imaging with programmable delivery systems. Japanese interventional pain specialists specify these for complex neuralgia cases.
Hospital settings retain volume leadership; home care commands the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathways anchor the United States as the dominant geography, while EU MDR compliance costs and Japan's PMDA polymer standards shape competitive entry across developed markets. Demand concentrates where ERAS protocols and regional anesthesia training programs have achieved institutional penetration.
United States
Integrated delivery networks unbundle catheter-pump combinations, creating direct purchasing leverage for standardized orthopedic protocols. FDA antimicrobial coating guidance extends validation timelines for silver-ion surfaces. Academic medical centers in Boston and Philadelphia drive ultrasound-first residency curricula that expand placement competency beyond specialist concentrations.
Germany
Anesthesiology training programs retain stimulation-guided protocols as competency benchmarks, sustaining demand for precision-engineered catheter designs. EU MDR clinical evidence requirements elevate notified body review costs for extended-duration indwelling devices. Manufacturing clusters in North Rhine-Westphalia and Baden-Württemberg anchor European supply chain scale for regional anesthesia delivery systems.
Japan
METI oversight enforces JIS-compliant polymer validation for catheter tensile strength and kink resistance specifications. PMDA sterility assurance standards govern material biocompatibility for extended postoperative protocols. Tokyo maternity hospitals specify modified catheter geometries for ambulatory labor analgesia applications.
Australia
Home health networks pilot cellular-connected infusion pumps for 72-hour ambulatory discharge protocols. TGA regulatory frameworks align with ISO standards for extended-duration neural blockade devices. Trauma networks in New South Wales specify multi-orifice configurations for continuous interscalene blockade in shoulder reconstruction cases.
Brazil
Regional anesthesia training program expansion in São Paulo and Rio de Janeiro clinical networks creates first-mover advantage for distributor relationships. ANVISA premarket pathways for pain management devices remain less streamlined than FDA equivalents. Physical medicine departments pilot catheter-based neural blockade for complex regional pain syndrome recovery protocols.
Global Continuous Peripheral Nerve Block Catheter Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with catheter-pump unbundling reshaping procurement leverage across health systems. The vendor base separates into three strategic archetypes: diversified critical care portfolios, precision-engineered regional anesthesia specialists, and disposable-focused ambulatory suppliers. Competitive moves concentrate on M&A for technology access and geographic distributor consolidation ahead of infrastructure maturation in underpenetrated markets.
Among diversified critical care portfolios, Teleflex Incorporated occupies a position exemplifying integrated acute care technology breadth. B. Braun Melsungen AG anchors European manufacturing scale within the regional anesthesia delivery systems tier. Pajunk GmbH represents the precision-engineered specialist archetype, with German-speaking clinical market concentration reflecting stimulation-guided design heritage.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Pajunk GmbH |
| Halyard Health, Inc. |
| Epimed International Inc. |
| Ambu A/S |
| ICU Medical, Inc. |
| Avanos Medical, Inc. |
| Vygon |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day polymer inventory cycles in catheter manufacturing tether pricing power to German and Swiss resin allocation decisions, concentrating margin pressure on manufacturers lacking backward integration into medical-grade polyurethane supply. This lead-time exposure amplifies cost pass-through volatility for antimicrobial-coated catheter variants facing extended FDA validation timelines.
Pricing Analysis
United States hospital systems command 15-25% price discounts versus Japanese procurement committees for identical ultrasound-compatible catheter specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and antimicrobial surface certification. Cost compression in economy-tier non-stimulator catheters is intensifying because Brazilian distributor consolidation concentrates volume leverage. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with GPO contracts show lowest.
Supply Chain Analysis
Germany and Switzerland anchor medical-grade polyurethane and silicone raw material production for catheter construction, with North Rhine-Westphalia housing specialized extrusion capabilities. Manufacturing draws from thermoplastic elastomer, radiopaque filler, and antimicrobial additive feedstocks. Single-source vulnerability concentrates in Swiss polymer compounders serving extended-duration indwelling device specifications. Distribution runs through critical care distributors in developed markets and specialized medical device distributors in Brazil and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated delivery networks as hospital procurement committees unbundle catheter-pump combinations, fragmenting traditional vendor relationships and compressing margin capture for non-differentiated suppliers.
For Market Incumbents: Fortify antimicrobial coating validation pipelines to preempt FDA guidance shifts on silver-ion surfaces. Deepen backward integration into German polymer supply through captive compounding arrangements or long-term offtake agreements with North Rhine-Westphalia resin specialists. Defend against liposomal bupivacaine substitution by embedding catheter protocols in ERAS pathway standardization. For New Entrants and Emerging Players: Lead with ultrasound-first catheter designs targeting Brazilian regional anesthesia training program expansion in São Paulo clinical networks. Prioritize distributor relationships ahead of infrastructure maturation. Capture white-space in Australian home care cellular-connected pump integration for 72-hour ambulatory discharge protocols. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified critical care portfolios seeking to monetize non-core regional anesthesia assets. Five-to-ten-year viability hinges on catheter-pump ecosystem control and reimbursement pathway navigation. Signal to watch: FDA antimicrobial coating guidance finalization as inflection indicator for coating-investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Streamlining Engagement | Accelerates clearance timelines for antimicrobial surface innovations in United States markets. |
| EU MDR Clinical Evidence Consolidation | Reduces notified body review costs through multi-state data package standardization. |
| Backward Integration into Polymer Supply | Captures margin compression from German and Swiss resin allocation volatility. |
| Telehealth-Integrated Pump Development | Opens reimbursement pathways for Australian and United States home-based catheter management. |
| Brazilian Distributor Network Establishment | Secures first-mover positioning ahead of São Paulo regional anesthesia infrastructure maturation. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with anesthesiologists, hospital procurement managers, biomedical engineers, and GPO contracts directors; and secondary validation against FDA 510(k) filings, EU MDR notified body guidance, hospital procurement databases, and catheter manufacturer SEC disclosures. Bottom-up volume modeling triangulated with top-down market sizing across placement modality, application setting, and end-user type.
Across the analysis window, forecast outputs reflect segmented modeling by product type, application, end user, and deployment setting, with regional regulatory cluster overlays for United States, Germany, Japan, and Brazil. CAGRs derived from procedure volume elasticity to ERAS protocol penetration and regional anesthesia training program expansion. Industry-specific inputs incorporated ultrasound guidance adoption curves and antimicrobial coating validation timeline assumptions.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR clinical evidence standards, and Japan PMDA polymer specifications; material policy shifts would require re-modeling. Specific risks include polymer supply disruption, liposomal bupivacaine substitution acceleration, and anesthesiologist workforce scarcity constraining placement volume realization. Recalibration cycles align with material shifts in ERAS protocol mandates and reimbursement pathway rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Global Bone Screw System Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Electronic Pill Market
Medical Devices
Global Prosthetics Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Europe Spinal Surgery Devices Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Allografts Market