
 Disposable Thermometer Market | 2026-2036
Disposable Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Thermometer Market Analysis
Subscription-based calibration and fleet-management software for digital disposable thermometers is broadening what healthcare systems purchase alongside hardware. 3M (Solventum) leverages its extensive hospital supply contracts to bundle disposable probes with monitoring platforms. MEDICAL INDICATORS anchors its position through proprietary liquid-crystal chemistry that eliminates battery dependency. tempagenix differentiates via flexible manufacturing lines that serve both clinical and consumer channels.
A disposable thermometer is a single-use temperature-sensing device, typically employing thermochromic liquid crystals, bimetallic strips, or digital infrared sensors with factory-sealed housings, designed to provide one-time clinical-grade readings between 35°C and 42°C before discard. Its primary commercial purpose is eliminating sterilization overhead and cross-infection vectors in patient-care settings. Digital formats now lead hospital procurement due to precision requirements, while chemical strip variants sustain share in home-care and school settings where cost sensitivity dominates. Infrared disposables represent the fastest-growing product type as ambulatory clinics adopt non-contact screening protocols. Oral and axillary usage modes capture the bulk of volume, though rectal applications retain premium positioning in neonatal intensive care.
The FDA's medical device classification system governs 510(k) clearance pathways for clinical-grade disposable thermometers, while the EPA regulates mercury-free manufacturing claims through its toxic substances framework. The EU Medical Device Regulation imposes stricter post-market surveillance and unique device identification requirements on manufacturers exporting to European healthcare systems. Stakeholders must monitor evolving cross-border harmonization between FDA and EMA standards as dual-registered products become the norm for multinational suppliers.
Market Dynamics
Hospital infection control protocols are mandating single-use temperature monitoring, forcing procurement teams to abandon reusable probe systems and absorb higher per-patient supply costs.
Growth Catalysts
- FDA Device Classification Updates:Streamlined 510(k) pathways for digital disposable thermometers accelerate product registration timelines for manufacturers targeting acute-care facilities.
- Neonatal Intensive Care Demand:Rectal disposable thermometers command premium positioning in NICU settings where sterilization failure risks are unacceptable.
- Mercury-Free Manufacturing Mandates:EPA toxic substances frameworks ban mercury-based alternatives, eliminating legacy competition and redirecting procurement budgets toward compliant single-use formats.
Market Restraints
- Liquid Crystal Raw Material Concentration:Proprietary thermochromic chemistry suppliers in East Asia control critical feedstock for chemical strip variants, creating single-source vulnerability.
- Digital Sensor Cost Volatility:Infrared sensor components face price instability from semiconductor foundry allocation constraints.
- Battery-Free Design Limitations:Liquid-crystal formats cannot support continuous monitoring or data logging, restricting functionality in telemetry-integrated wards.
Strategic Opportunities
- Subscription Calibration Services:Fleet-management software bundled with disposable probe purchases creates recurring revenue streams beyond hardware margins.
- Ambulatory Clinic Expansion:Non-contact infrared disposables penetrate urgent-care networks adopting rapid screening protocols.
- EU Medical Device Regulation Tailwinds:Stricter post-market surveillance requirements favor manufacturers with established quality systems, disadvantaging commodity suppliers.
Industry Challenges
- Dual-Registration Complexity:Harmonizing FDA 510(k) and EMA MDR compliance timelines strains regulatory affairs capacity at mid-scale manufacturers.
- Legacy System Integration:Digital disposable thermometers must interface with proprietary hospital information systems, requiring bespoke software development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Thermometer Market |
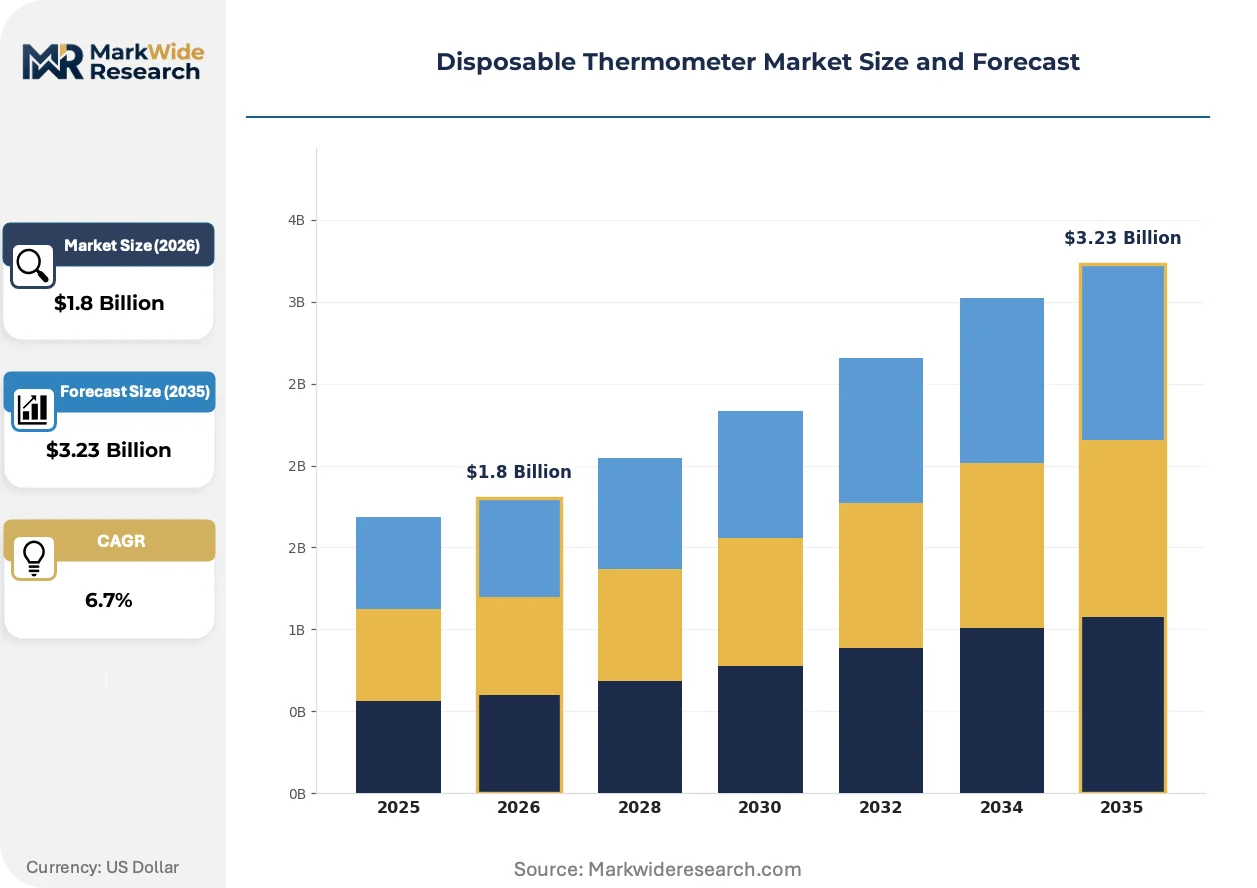
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Infrared, Chemical Strip, Disposable Probe End User: Hospitals, Home Care, Clinics, Schools Usage Mode: Oral, Rectal, Axillary, Surface Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | 3M (Solventum), Hopkins Medical Products, MEDICAL INDICATORS, tempagenix, Zeal, Acme United Corporation, American Diagnostics Corporation, Advanced Meditech Internationals, LCRHallcrest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Thermometer Market Emerging Trajectories
Disposable thermometer technology is converging with connected health infrastructure, transforming standalone temperature readings into integrated data points within electronic medical records.
Bluetooth-enabled disposable thermometers is automating temperature data capture at the point of care. Hospital systems adopting these devices eliminate manual transcription errors and reduce nursing documentation burden. The technology is compressing the gap between measurement and EMR entry, enabling real-time fever surveillance dashboards.
EU Medical Device Regulation post-market surveillance mandates are intensifying documentation requirements for manufacturers exporting to European healthcare systems. Clinical-grade disposable thermometers now require unique device identification and traceability systems. German and French hospital procurement consortiums are prioritizing suppliers with established EUDAMED registration.
Direct contracting between thermometer manufacturers and integrated delivery networks is displacing traditional distributor relationships. Large health systems negotiate multi-year supply agreements bundling probes with calibration software. This pattern is most visible in United States acute-care chains consolidating purchasing through centralized supply chain offices.
Disposable Thermometer Market Segmentation
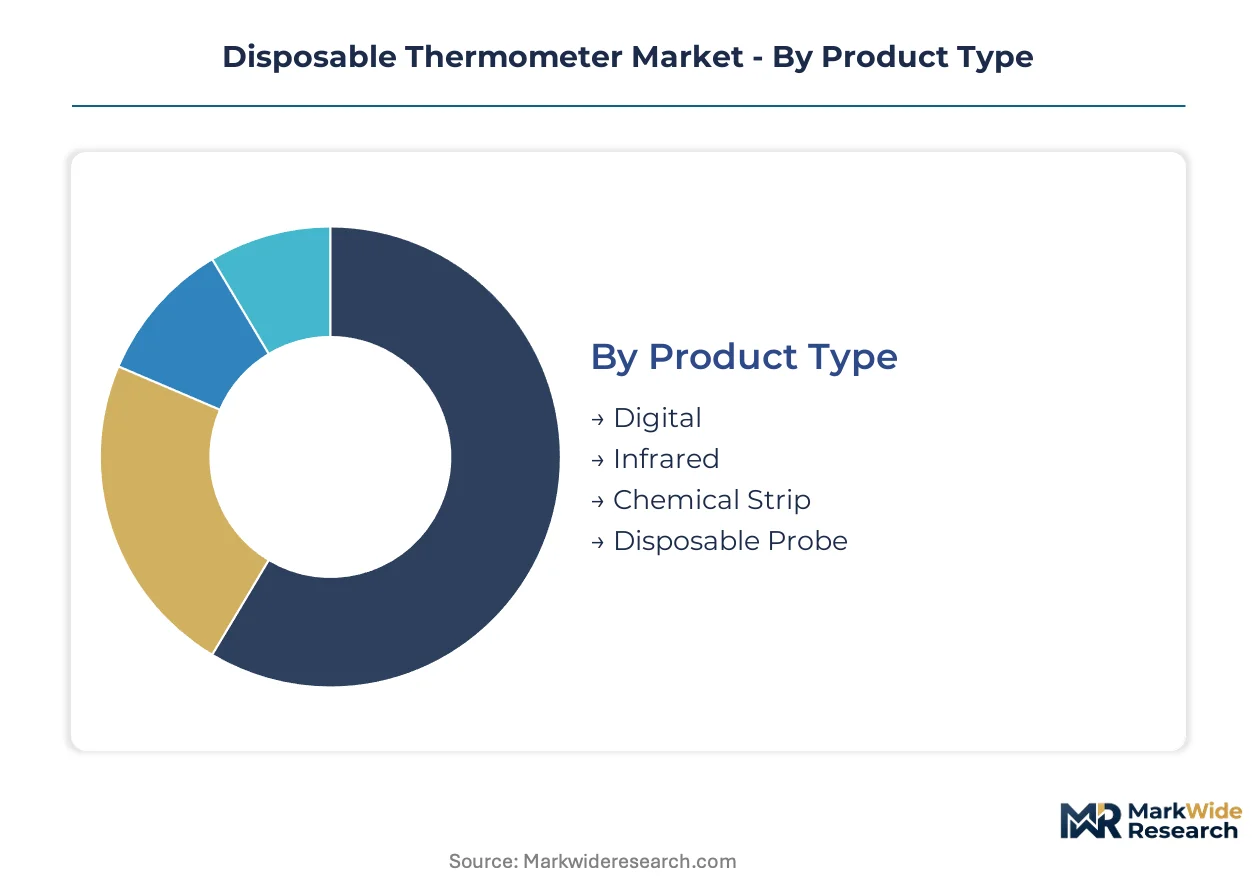
Disposable thermometer segmentation reveals divergent procurement logic across clinical and non-clinical environments. Product format selection hinges on precision requirements, sterilization protocols, and integration with hospital information systems.
Product Type:
Cost tier separates hospital procurement from consumer purchases, with precision specifications and connectivity features commanding premium positioning.
- Digital:Battery-powered units with LCD displays and factory-calibrated sensors deliver clinical-grade accuracy to acute-care wards. United States hospital procurement teams prioritize these for EMR integration and telemetry compatibility, absorbing higher per-patient costs to eliminate sterilization overhead.
- Infrared:Non-contact sensors with sealed optical housings enable rapid screening without patient contact. Ambulatory clinics in urgent-care networks drive fastest expansion here, adopting these for throughput efficiency in high-volume intake settings.
- Chemical Strip:Thermochromic liquid crystals bonded to flexible substrates provide passive temperature indication without power. Home-care and school settings dominate procurement due to minimal unit economics and disposal simplicity.
- Disposable Probe:Single-use sheaths paired with reusable digital handles bridge cost and infection control priorities. NICU departments specify these for rectal applications where sterilization failure risks are unacceptable.
Volume sits with Digital formats in hospital systems; growth tilts toward Infrared as non-contact protocols expand.
End User:
Application environment dictates specification requirements, from telemetry integration in acute care to cost minimization in institutional screening.
- Hospitals:Infection control mandates and EMR connectivity requirements dominate procurement criteria. United States acute-care facilities consolidate purchasing through centralized supply chain offices, negotiating multi-year agreements bundling probes with calibration services.
- Home Care:Patient-directed purchasing prioritizes simplicity and disposal convenience. Retail and online channels capture this volume, with chemical strip formats sustaining share due to minimal training requirements.
- Clinics:Throughput pressure and space constraints shape product selection. Urgent-care networks favor infrared disposables for rapid intake screening, while primary care balances cost against accuracy needs.
- Schools:Mass screening protocols and budget limitations drive bulk procurement of chemical strip variants. Institutional buyers prioritize lowest unit cost over precision, accepting wider accuracy tolerances for fever detection.
Revenue concentrates in Hospitals; expansion accelerates fastest in Clinics as ambulatory networks proliferate.
Usage Mode:
Clinical risk tolerance and patient population characteristics determine site selection, with neonatal applications commanding strictest specifications.
- Oral:Standard placement under the tongue with 60-second equilibration time suits conscious cooperative patients. General medical-surgical floors in United States hospitals default to this mode for routine monitoring.
- Rectal:Core temperature measurement via sealed flexible probes delivers highest accuracy for critical patients. NICU settings mandate single-use formats here, where immunocompromised infants face unacceptable cross-contamination exposure.
- Axillary:Armpit placement offers non-invasive alternative for patients with oral trauma or altered consciousness. Pediatric wards specify these when rectal application is contraindicated.
- Surface:Skin-contact or non-contact measurement of forehead or temporal artery serves screening and triage functions. Emergency departments deploy these for rapid fever detection during intake.
Procedure volume favors Oral measurement; premium positioning concentrates in Rectal applications.
Distribution Channel:
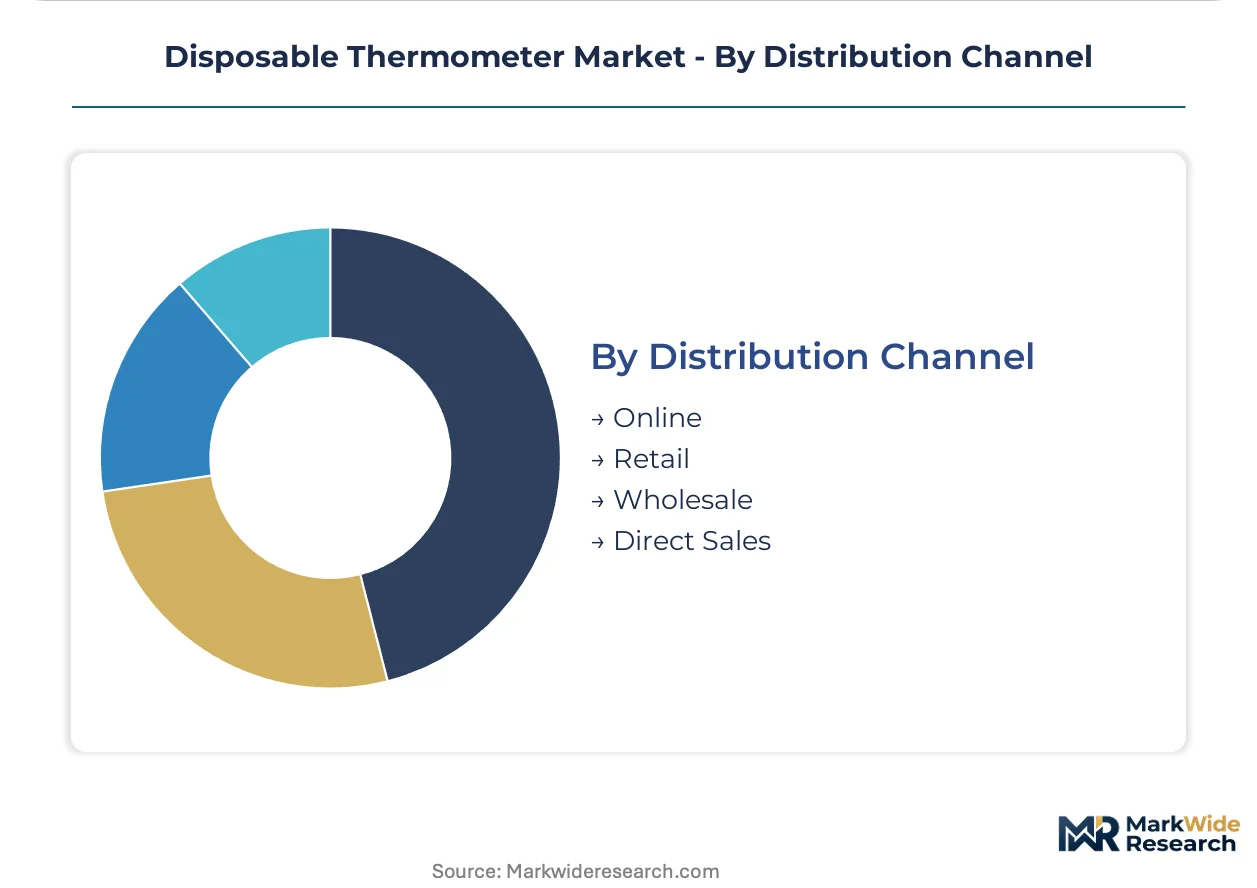
Customer scale and procurement sophistication determine channel selection, with large health systems bypassing traditional intermediaries.
- Online:E-commerce platforms capture home-care and small institutional buyers seeking transparent pricing and rapid fulfillment. Amazon Business and specialized medical supply marketplaces aggregate fragmented demand.
- Retail:Pharmacy chains and big-box stores serve consumer and school procurement with immediate availability. CVS Health and Walgreens dominate United States over-the-counter placement.
- Wholesale:Medical supply distributors maintain inventory for mid-scale clinics and nursing facilities. Cardinal Health and McKesson leverage logistics networks for just-in-time delivery.
- Direct Sales:Manufacturer relationships with integrated delivery networks displace distributor margins. Large United States health systems negotiate enterprise contracts bundling hardware with fleet-management software.
Transaction volume flows through Wholesale; margin expansion concentrates in Direct Sales as health systems consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of thermochromic liquid crystals concentrates in East Asian chemical clusters, while consumption tilts toward North American and European hospital systems with stringent infection control mandates. Procurement budgets in acute-care facilities are diverging sharply by regulatory environment.
United States
Hospital infection control budgets at acute-care facilities continue climbing, with centralized supply chain offices consolidating multi-year probe contracts. FDA 510(k) clearance pathways for digital disposable thermometers streamline product registration for manufacturers targeting clinical settings. The Boston-Cambridge medical device corridor hosts development activity for Bluetooth-enabled disposable formats integrating with Epic and Cerner EMR systems.
Germany
Hospital procurement consortiums in Bavaria and North Rhine-Westphalia prioritize suppliers with established EUDAMED registration under EU Medical Device Regulation post-market surveillance mandates. German university hospitals drive demand for telemetry-compatible digital formats in integrated wards. The Rhine-Main cluster around Frankfurt anchors distribution logistics for disposable probe supply across Central Europe.
China
Domestic production of thermochromic liquid crystal feedstock supplies global chemical strip manufacturers, with NMPA medical device classification rules governing export-quality production lines. Provincial hospital networks in Guangdong and Jiangsu are upgrading from reusable to single-use protocols. The Yangtze River Delta chemical corridor controls critical raw material output for passive temperature indication formats.
Japan
PMDA quality system requirements favor manufacturers with established post-market surveillance infrastructure, disadvantaging commodity suppliers in hospital procurement. METI industrial standards for mercury-free manufacturing align with domestic EPA-equivalent toxic substances frameworks. The Kansai region around Osaka maintains specialized production of high-precision liquid-crystal formulations for neonatal applications.
United Kingdom
NHS supply chain consolidation is displacing traditional distributor relationships in favor of direct manufacturer contracting for integrated delivery networks. MHRA alignment with EU MDR traceability requirements shapes procurement specifications for clinical-grade disposables. The Cambridge-London corridor hosts development of calibration software bundling with disposable probe purchases.
Disposable Thermometer Market Vendor Landscape
Top-tier vendors anchor hospital supply contracts, while mid-scale specialists compete on flexible manufacturing and proprietary chemistry. The vendor base stratifies across three tiers: diversified medical device conglomerates with extensive distribution networks, specialized temperature monitoring firms with proprietary liquid-crystal or digital sensor technology, and regional fabricators serving cost-sensitive consumer channels. Dominant competitive moves include bundling disposable hardware with subscription calibration services and pursuing dual FDA-EMA registration to capture multinational health system contracts.
Within the diversified medical device tier, 3M (Solventum) and Hopkins Medical Products exemplify scale-driven positioning through extensive hospital supply relationships. MEDICAL INDICATORS and tempagenix occupy specialist positions, with the former representing proprietary chemistry-based differentiation and the latter illustrating flexible manufacturing architectures serving dual clinical-consumer channels. These four entities collectively demonstrate the competitive archetypes reshaping procurement negotiations with integrated delivery networks.
| Leading Market Players |
|---|
| 3M (Solventum) |
| Hopkins Medical Products |
| MEDICAL INDICATORS |
| tempagenix |
| Zeal |
| Acme United Corporation |
| American Diagnostics Corporation |
| Advanced Meditech Internationals |
| LCRHallcrest |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap chemical manufacturers in East Asia anchor thermochromic liquid-crystal feedstock production, translating concentrated ownership into disciplined pricing power over Western disposable thermometer assemblers facing procurement cost compression.
Pricing Analysis
Cost-down pressure on hospital-grade digital units accelerates because semiconductor foundry allocation constraints inflate infrared sensor component costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared formats with EMR integration from uncertified chemical strips. Price differentiation hinges on certification tier and volume scale, with integrated delivery networks extracting steepest discounts through multi-year offtake commitments. Home-care channels exhibit highest price sensitivity, while NICU procurement teams absorb premium positioning for rectal single-use formats.
Supply Chain Analysis
Workforce availability constraints in Guangdong and Jiangsu provincial manufacturing zones limit expansion of thermochromic liquid-crystal output. Supply concentrates in China for passive temperature indication substrates, South Korea for precision infrared sensor packaging, and Germany for telemetry-compatible digital assemblies. Raw material dependencies span liquid-crystal polymers, semiconductor wafers, and medical-grade flexible substrates. Single-source vulnerability in East Asian thermochromic chemistry creates supply chain risk. Distribution runs through wholesale medical supply networks for mid-scale clinics, with direct manufacturer contracting displacing intermediaries for large health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU MDR compliance burdens and dual-registration complexity force commodity suppliers toward exit or acquisition.
For Market Incumbents: Deploy subscription calibration software bundling to deepen hospital system lock-in and defend against emerging Bluetooth-enabled entrants. Pursue backward integration into thermochromic liquid-crystal chemistry to neutralize East Asian feedstock pricing power. Anchor positioning through exclusive GPO contracts with Cardinal Health and McKesson distribution networks. For New Entrants and Emerging Players: Launch via Amazon Business and specialized medical supply marketplaces to bypass entrenched wholesale relationships. Target urgent-care clinic networks adopting non-contact infrared screening protocols as the most penetrable segment. Lead with unbundled per-unit pricing against incumbent subscription bundles to exploit price sensitivity in ambulatory settings. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale manufacturers with established FDA 510(k) portfolios but strained EMA MDR registration capacity in Germany and France. Long-term viability centers on dual-registered asset bases serving multinational integrated delivery networks. Watch EUDAMED registration completion rates as the signal for regulatory-driven consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual FDA-EMA Registration Pursuit | Captures multinational health system contracts requiring harmonized compliance across United States and European acute-care networks. |
| Bluetooth-Enabled Format Development | Enables Epic and Cerner EMR integration demanded by United States hospital procurement committees. |
| Thermochromic Chemistry Backward Integration | Neutralizes East Asian single-source vulnerability for liquid-crystal feedstock in chemical strip production. |
| Subscription Fleet-Management Software Launch | Transforms transactional probe sales into recurring revenue streams with hospital supply chain offices. |
| Urgent-Care Direct Contracting Expansion | Penetrates fastest-growing ambulatory clinic segment adopting non-contact infrared screening protocols. |
Methodological Framework
Independent corroboration across hospital procurement committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads underwrites the qualitative findings in this study. Primary interviews with supply chain directors at integrated delivery networks and temperature monitoring specialists at NICU departments combined with secondary validation from FDA 510(k) filings, EUDAMED registration databases, hospital procurement contracts, and customs trade data. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition across the analysis window segments expansion by product format, end-user environment, usage mode, and distribution channel. The analytical framework models digital, infrared, chemical strip, and disposable probe categories against hospital, home-care, clinic, and school procurement patterns. CAGRs derive from weighted average of segment growth trajectories incorporating infection control budget trends, regulatory pathway timelines, and EMR integration adoption curves.
Mercury-free manufacturing mandate enforcement, semiconductor foundry capacity allocation, and EU MDR post-market surveillance documentation requirements are the dominant revision risks. Forecasts reflect assumptions about regulatory harmonization progress and health system consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurotech Devices Market
Medical Devices
Knee Walkers Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Transient Elastography Device Market
Medical Devices
US Biomedical Sensors Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Chest Drainage System Market
Medical Devices
Microdebrider Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Ambulatory X-Ray Devices Market