
 Sentinel Node Biopsy Market | 2026-2036
Sentinel Node Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Sentinel Node Biopsy Market Outlook
Blue dye is repositioning methylene blue formulations in sentinel node biopsy kits as cost pressures reshape procurement economics. Stryker leverages its orthopedic and surgical ecosystem to sustain integrated instrument-tracer offerings across hospital networks. Devicor Medical Products specializes in breast biopsy systems that extend into lymphatic mapping workflows. Navidea Biopharmaceuticals anchors its position through proprietary radiopharmaceutical development for lymphatic imaging.
Sentinel node biopsy is a surgical staging procedure that identifies the first lymph node draining a tumor site using radioactive colloids, blue dyes, or fluorescent tracers with gamma detection probes; the technique typically employs technetium-99m sulfur colloid with intraoperative gamma counting to localize nodes for histopathological examination. Fluorescence imaging using indocyanine green now competes with traditional lymphoscintigraphy for real-time nodal visualization, particularly in melanoma and breast cancer applications. Breast cancer dominates procedural volumes as the most established indication, while head and neck cancer represents the fastest-expanding application segment driven by rising oropharyngeal case volumes and refined neck dissection protocols.
The FDA oversees radiopharmaceutical tracer approvals and device clearances through its Center for Devices and Radiological Health, while the EMA's Committee for Medicinal Products for Human Use evaluates radioactive agent marketing authorizations across European Union member states. ISO 14155 governs clinical investigation standards for surgical device trials, directly shaping study design requirements for novel detection technologies. Stakeholders must monitor evolving reimbursement pathways for fluorescence-guided procedures against established gamma probe billing codes.
Market Dynamics
Fluorescence-guided sentinel node biopsy is compressing procedural timelines and displacing dual-tracer protocols across academic medical centers, forcing manufacturers to recalibrate instrument-tracer bundling strategies around real-time imaging workflows rather than gamma detection hardware.
Growth Catalysts
- EMA MDR compliance deadlines:European hospitals are accelerating validation of single-use lymphatic mapping kits to meet reclassification requirements for Class III surgical devices.
- Indocyanine green fluorescence:Real-time nodal visualization is eliminating preoperative lymphoscintigraphy in melanoma staging, cutting same-day surgery logistics.
- German oncology center density:Concentrated specialist infrastructure in Munich, Heidelberg, and Berlin generates protocol standardization spillover into neighboring EU markets.
Market Restraints
- Technetium-99m supply fragility:Aging reactor infrastructure in Canada and Europe creates radiopharmaceutical shortage risk that disrupts dual-tracer dependency.
- Blue dye manufacturing concentration:Three specialized chemical producers control methylene blue pharmaceutical-grade supply, exposing procurement to batch variability.
- Fluorescence depth limitation:Tissue penetration constraints below 10 millimeters restrict indocyanine green utility in obese patient populations.
Strategic Opportunities
- Indian tier-2 city expansion:Underpenetrated oncology infrastructure in Lucknow, Jaipur, and Kochi offers first-mover positioning for portable gamma probe systems.
- Head and neck cancer protocols:Rising oropharyngeal case volumes are creating dedicated lymphatic mapping service lines outside traditional breast centers.
- ISO 14155 harmonization:Streamlined multi-site clinical investigation standards reduce trial costs for novel tracer-device combinations.
Industry Challenges
- Nuclear medicine technologist scarcity:Specialized radiopharmaceutical handling certification bottlenecks constrain same-day surgery scheduling capacity.
- Dual-modality integration complexity:Synchronous fluorescence and gamma signal processing requires retraining of surgical staff accustomed to sequential detection methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sentinel Node Biopsy Market |
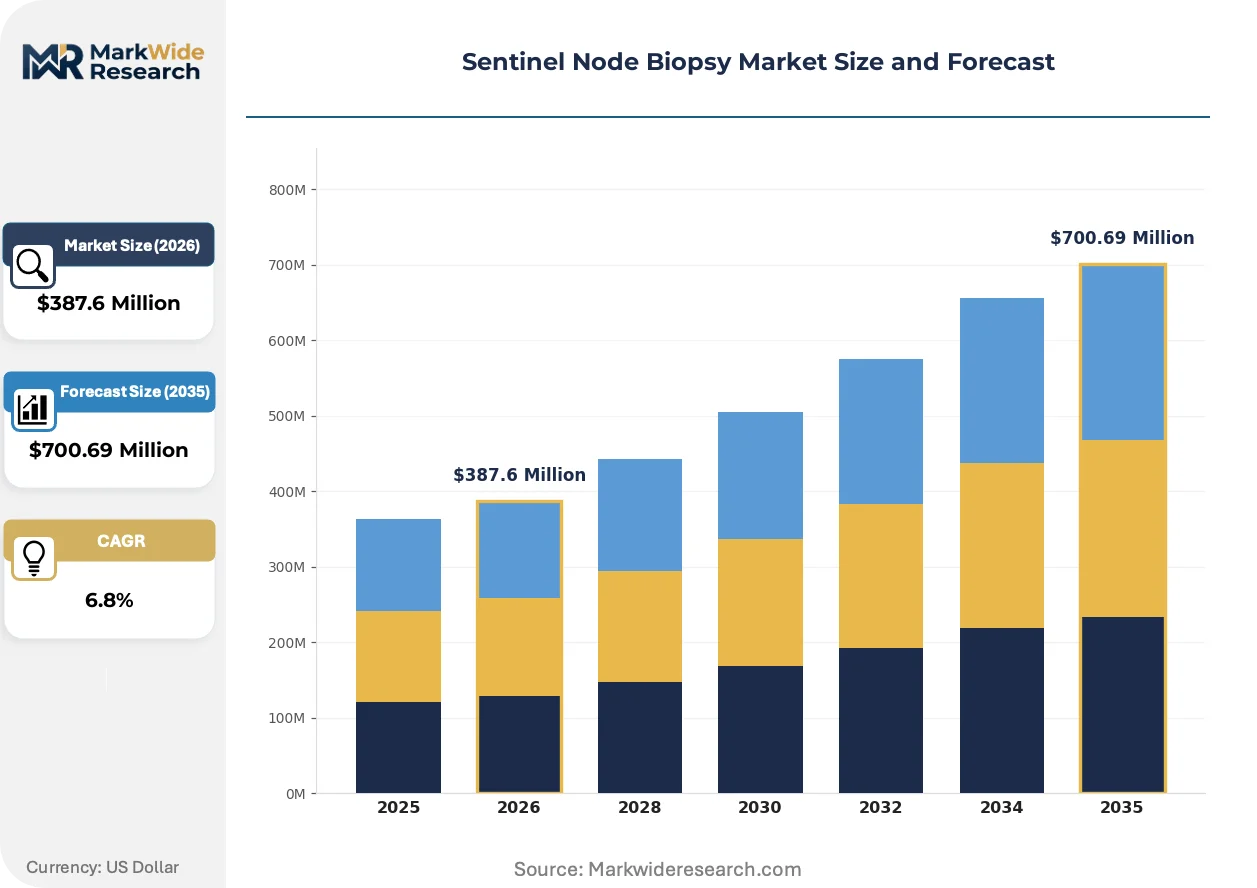
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle, Radioactive Tracers, Imaging Agents, Surgical Instruments End User: Hospitals, Surgical Clinics, Research Laboratories, Oncology Centers Application: Breast Cancer, Melanoma, Colorectal Cancer, Head and Neck Cancer Technology: Fluorescence Imaging, PET, MRI, Lymphoscintigraphy |
| Companies Covered | SurgicEye GmbH, INTRAMEDICAL IMAGING LLC, Devicor Medical Products, Inc., Stryker, Navidea Biopharmaceuticals, Inc., C. R. Bard, Inc., KUB Technologies Inc., LabLogic Systems Ltd, Hologic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sentinel Node Biopsy Market Strategic Shifts
Near-infrared fluorescence imaging is restructuring competitive positioning around intraoperative decision speed rather than detection sensitivity, compressing the value proposition of established gamma probe manufacturers.
Indocyanine green near-infrared fluorescence is expanding into breast cancer sentinel node biopsy as the primary mapping modality. Academic medical centers in the United States are adopting single-tracer protocols within 18-month validation cycles. This technology is expanding into outpatient surgery settings previously restricted by nuclear medicine licensing requirements, enabling procedure migration from hospital-based suites to ambulatory surgical centers.
REACH Annex XIV authorization processes for novel dye formulations are extending development timelines for European market entry. Manufacturers are reformulating tracer stability profiles to satisfy substance restriction thresholds. Breast biopsy kit suppliers serving EU markets are diversifying dye sourcing to reduce dependency on legacy coal-tar derived intermediates.
Hospital procurement committees are consolidating sentinel node biopsy supply contracts under integrated operating room vendor agreements. Independent distributor networks serving community oncology practices are losing access to bundled instrument-tracer offerings. This concentration is most visible in United States health system purchasing, where IDN-level standardization is displacing physician preference item autonomy.
Sentinel Node Biopsy Market Segmentation
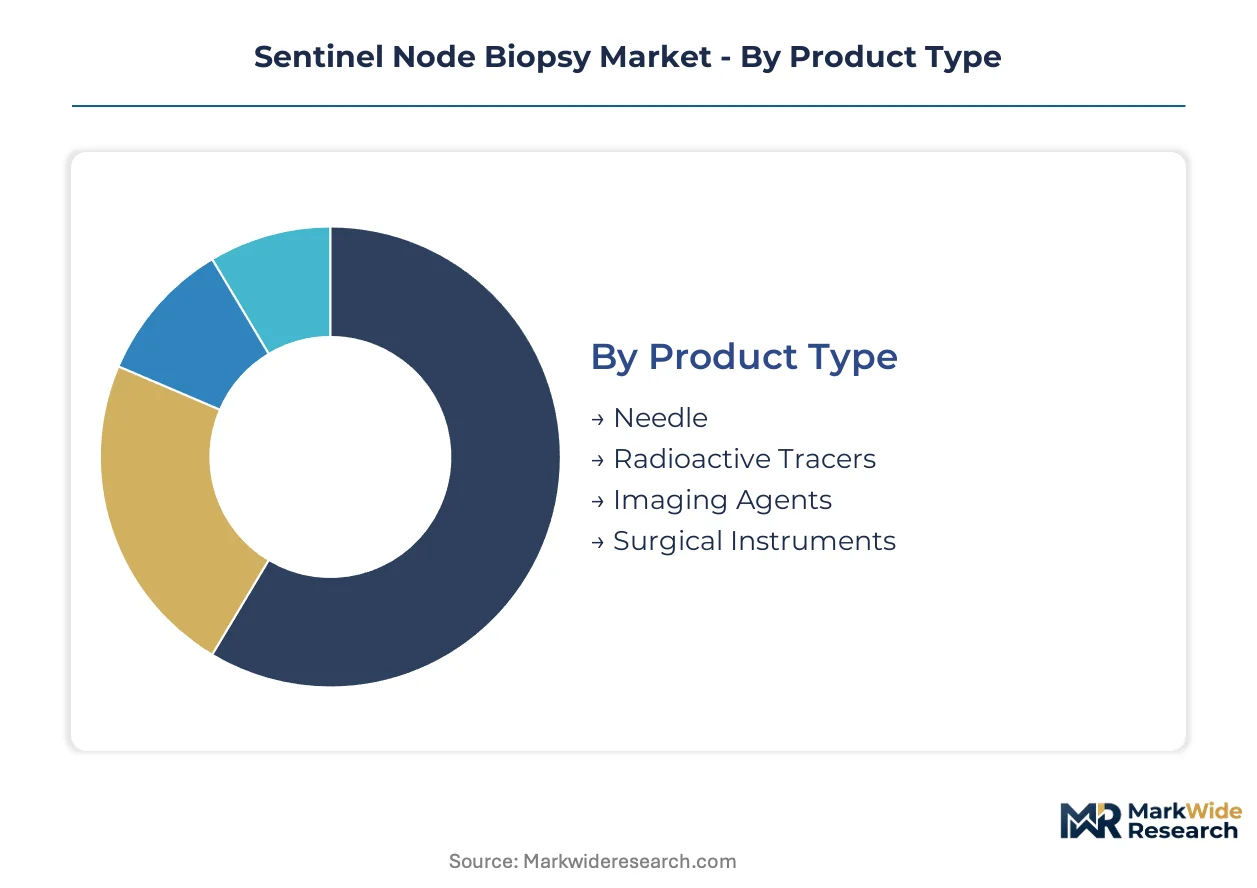
Segmentation in sentinel node biopsy reveals how tracer modality, clinical setting, and cancer type reshape procurement patterns. Each axis carries distinct regulatory burdens and reimbursement logic that manufacturers must navigate separately.
Product Type:
Technical specification determines sterility requirements, shelf stability, and handling protocols across the product spectrum.
- Radioactive Tracers:Technetium-99m sulfur colloid remains the reference standard for gamma-guided detection, with compounding pharmacies in the United States and Germany controlling regional supply chains. Hospital nuclear medicine licensing requirements constrain same-day surgery scheduling and create geographic access disparities.
- Imaging Agents:Indocyanine green near-infrared formulations are displacing dual-tracer protocols in academic medical centers, eliminating preoperative lymphoscintigraphy and enabling migration to ambulatory surgical centers previously restricted by radiopharmaceutical handling rules.
- Needle:Single-use lymphatic mapping kits face EMA MDR reclassification deadlines that accelerate validation cycles across European hospital networks.
- Surgical Instruments:Gamma detection probes and fluorescence camera systems compete for capital budget allocation within integrated operating room vendor agreements.
Radioactive tracers lead on scale; imaging agents lead on momentum.
End User:
Facility type dictates capital intensity, staffing requirements, and procedure volume economics.
- Hospitals:Academic medical centers in the United States drive protocol standardization and maintain dual-tracer capability for complex cases, while community hospitals consolidate purchasing under IDN-level contracts that displace physician preference autonomy.
- Oncology Centers:Concentrated specialist infrastructure in Munich, Heidelberg, and Berlin generates protocol spillover into neighboring EU markets, with German oncology center density supporting fluorescence adoption at scale.
- Surgical Clinics:Ambulatory settings gain access as near-infrared fluorescence eliminates nuclear medicine licensing barriers.
- Research Laboratories:ISO 14155 harmonization reduces multi-site trial costs for novel tracer-device combinations under investigation.
Hospitals dominate current volume; oncology centers are climbing the fastest.
Application:
Cancer type determines anatomical complexity, nodal basin location, and surgical specialty involvement.
- Breast Cancer:Established indication with the highest procedural volumes, where single-tracer indocyanine green protocols are completing 18-month validation cycles at major academic centers.
- Head and Neck Cancer:Rising oropharyngeal case volumes are creating dedicated lymphatic mapping service lines outside traditional breast centers, with refined neck dissection protocols expanding addressable procedures.
- Melanoma:Axillary and inguinal basin mapping standardization supports fluorescence-guided technique adoption.
- Colorectal Cancer:Mesenteric nodal evaluation applications remain under development with limited commercial penetration.
Breast cancer anchors current revenue; head and neck cancer shows steepest expansion trajectory.
Technology:
Detection modality determines real-time decision capability, capital equipment requirements, and reimbursement coding.
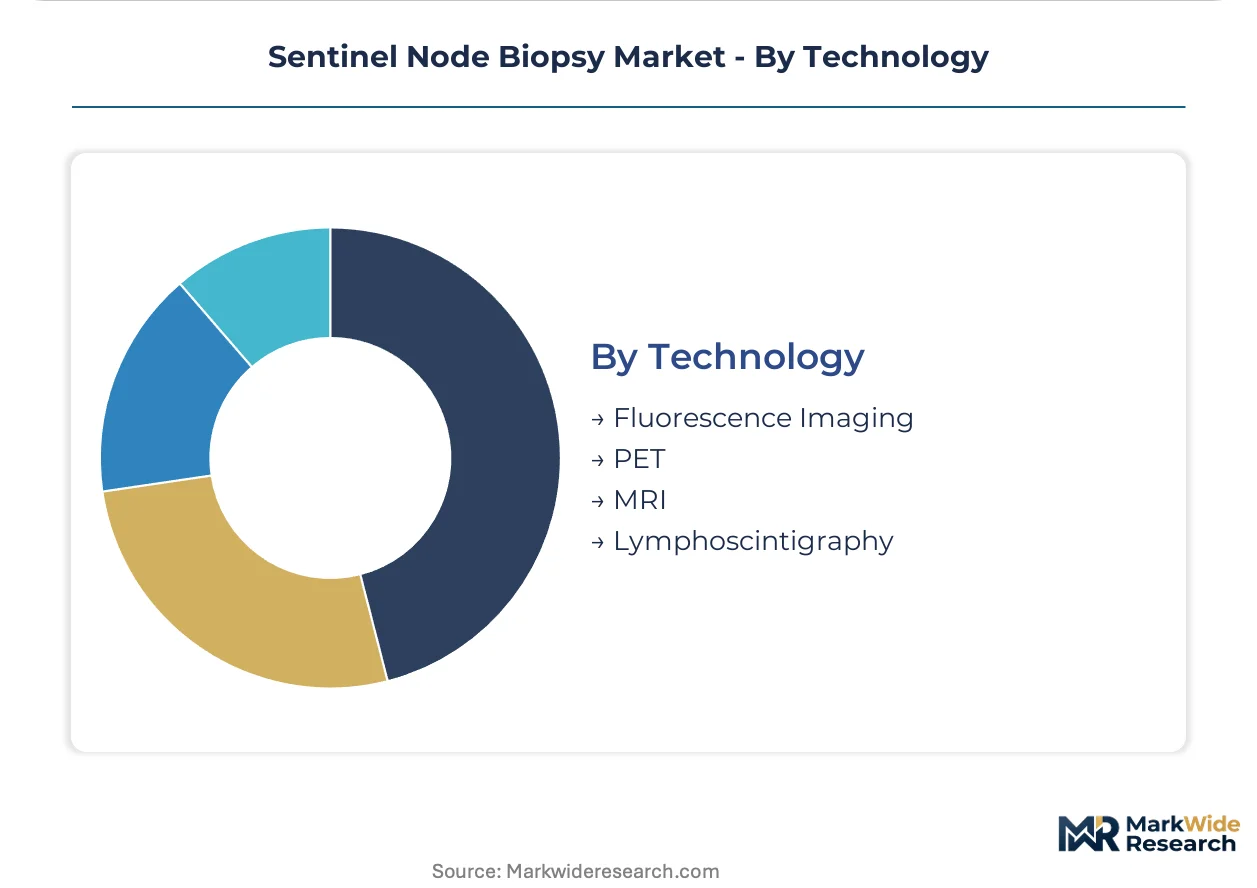
- Fluorescence Imaging:Near-infrared systems compress procedural timelines and enable real-time nodal visualization, restructuring competitive positioning around intraoperative decision speed rather than detection sensitivity alone.
- Lymphoscintigraphy:Preoperative gamma camera imaging faces displacement as fluorescence protocols eliminate same-day surgery logistics, though technetium-99m supply fragility from aging Canadian and European reactor infrastructure accelerates this transition.
- PET:Positron emission tomography serves staging applications rather than intraoperative guidance, with limited direct competition to sentinel node biopsy workflows.
- MRI:Magnetic resonance lymphography remains investigational for nodal mapping with no established clinical adoption.
Lymphoscintigraphy retains installed base dominance; fluorescence imaging is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German oncology center density in Munich, Heidelberg, and Berlin generates protocol standardization spillover into neighboring EU markets. Academic medical centers in the United States drive global adoption of fluorescence-guided techniques. Japanese precision manufacturing clusters supply gamma detection hardware components.
United States
FDA Center for Devices and Radiological Health oversees radiopharmaceutical tracer approvals and device clearances. Academic medical centers in Boston, Houston, and New York complete 18-month validation cycles for single-tracer indocyanine green protocols. Integrated delivery networks consolidate procurement contracts under vendor agreements that displace physician preference autonomy.
Germany
EMA MDR compliance deadlines accelerate validation of single-use lymphatic mapping kits across hospital networks. REACH Annex XIV authorization processes extend development timelines for novel dye formulations entering European markets. Concentrated specialist infrastructure in Munich and Heidelberg generates fluorescence adoption at scale with protocol spillover into Austria and Switzerland.
Japan
PMDA marketing authorization requirements shape radiopharmaceutical development pathways for lymphatic imaging agents. METI industrial policy supports precision manufacturing of gamma detection probe components. Osaka-based surgical instrument clusters supply detection hardware to Asia-Pacific oncology centers.
India
CDSCO regulatory pathways for medical devices create entry barriers for novel tracer-device combinations. PLI scheme incentives for domestic manufacturing attract portable gamma probe assembly operations. Tier-2 city oncology infrastructure in Lucknow, Jaipur, and Kochi offers first-mover positioning for detection system distributors.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for fluorescence imaging systems. NHS England procurement frameworks consolidate sentinel node biopsy supply contracts under integrated vendor agreements. London and Manchester academic centers drive head and neck cancer protocol development for lymphatic mapping service lines.
Sentinel Node Biopsy Market Competitive Environment
Global majors compete with regional champions across instrument-tracer bundling strategies and fluorescence imaging workflows. The vendor base spans diversified surgical conglomerates, specialized radiopharmaceutical developers, and dedicated biopsy system manufacturers. Three archetypes dominate: integrated operating room suppliers, proprietary tracer specialists, and detection hardware fabricators. Capacity expansion and strategic partnerships constitute the primary competitive moves reshaping supply relationships.
Within the integrated surgical solutions tier, Stryker anchors multinational hospital network agreements. Devicor Medical Products, Inc. exemplifies the specialized biopsy system archetype with breast-focused platform extensions. Navidea Biopharmaceuticals, Inc. occupies the proprietary radiopharmaceutical development position for lymphatic imaging applications.
| Leading Market Players |
|---|
| SurgicEye GmbH |
| INTRAMEDICAL IMAGING LLC |
| Devicor Medical Products, Inc. |
| Stryker |
| Navidea Biopharmaceuticals, Inc. |
| C. R. Bard, Inc. |
| KUB Technologies Inc. |
| LabLogic Systems Ltd |
| Hologic, Inc. |
| Others |
Value Chain & Pricing Dynamics
IDN-level procurement consolidation in the United States is compressing vendor margins and forcing tracer manufacturers to restructure kit bundling around fluorescence-only workflows that eliminate nuclear medicine licensing costs.
Pricing Analysis
Input-cost pass-through from technetium-99m reactor maintenance cycles and pharmaceutical-grade methylene blue batch variability sustains premium pricing for radioactive tracer kits against fluorescence alternatives. Pricing stratifies across premium gamma-guided systems, standard dual-tracer protocols, and economy single-dye configurations based on detection modality and sterility certification tier. Cost compression in the standard tier intensifies as hospital procurement committees consolidate contracts under integrated operating room vendor agreements. Community oncology practices exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize clinical validation timelines over unit economics.
Supply Chain Analysis
India's PLI scheme incentives for domestic medical device manufacturing are reshaping sourcing patterns for portable gamma probe assembly operations previously concentrated in Japanese precision manufacturing clusters. Component supply draws from German optical sensor fabricators, Chinese circuit board suppliers, and United States radiopharmaceutical compounding pharmacies. Single-source vulnerability in technetium-99m production from aging Canadian and European reactor infrastructure poses disruption risk to dual-tracer dependent workflows. Distribution runs through integrated delivery network procurement offices in the United States, specialized oncology distributor networks in Germany, and direct hospital contracts in underpenetrated Indian tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sentinel node biopsy market offers geographic arbitrage between established United States reimbursement pathways and emerging Indian procurement infrastructure, where PLI incentives offset capital equipment import costs.
For Market Incumbents: Extend fluorescence imaging platform compatibility to capture ambulatory surgical center migration as nuclear medicine licensing requirements relax. Defend against specialized radiopharmaceutical developers by anchoring integrated instrument-tracer bundling within IDN procurement frameworks. Prioritize backward integration into indocyanine green formulation supply to secure margin control as blue dye manufacturing concentration creates procurement bottlenecks. For New Entrants and Emerging Players: Capture head and neck cancer protocol development at academic medical centers establishing dedicated lymphatic mapping service lines outside traditional breast centers. Target underpenetrated Indian tier-2 city oncology infrastructure with portable gamma probe systems designed for minimal nuclear medicine technician staffing. Deploy direct clinical specialist education programs to bypass entrenched distributor relationships controlling United States community hospital access. For Investors and Strategic Acquirers: Asymmetric upside sits with proprietary radiopharmaceutical developers possessing REACH Annex XIV authorization progress for novel dye formulations. Long-term viability hinges on fluorescence-guided technique standardization displacing gamma detection hardware across the projection horizon. Monitor EMA MDR compliance deadline acceleration as inflection indicator for single-use lymphatic mapping kit validation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS coding alignment for fluorescence-guided procedures unlocks ambulatory surgical center expansion. |
| Hospital System Partnership | IDN-level standardization contracts displace physician preference autonomy in United States procurement. |
| CE Marking Pathway | EMA MDR Class III reclassification deadlines accelerate validation investment cycles across European networks. |
| Software Companion Development | Real-time nodal visualization algorithms compress intraoperative decision timelines for melanoma staging. |
| Backward Integration | In-house indocyanine green formulation secures margin control against methylene blue supply concentration. |
Study Parameters
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market informing demand-side validation. The research combines structured interviews with oncology surgeons, hospital procurement committee members, nuclear medicine technologists, and biomedical engineering directors with secondary triangulation against FDA 510(k) clearances, EMA marketing authorization databases, CMS reimbursement coding updates, and ISO 14155 clinical investigation registries. Bottom-up procedure volume modeling and top-down equipment installed base estimates converge through iterative stakeholder feedback.
Granularity extends to tracer modality, cancer application, end-user facility type, and detection technology across the projection horizon. CAGRs derive from logistic diffusion modeling of fluorescence adoption curves against gamma probe replacement cycles. Technetium-99m supply fragility scenarios and EMA MDR compliance deadline acceleration serve as industry-specific sensitivity inputs.
Reactor infrastructure decommissioning, REACH authorization delays, and nuclear medicine technologist certification bottlenecks are the dominant revision risks to procedure volume assumptions. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement coding stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
US C-Arms Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Europe Smart Bed Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Conduction Vaporizers Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Laparoscopic Electrodes Market