
 Hairy Cell Leukemia Treatment Market | 2026-2036
Hairy Cell Leukemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hairy Cell Leukemia Treatment Market Foresight
The EU Orphan Drug Regulation is consolidating market access incentives for rare hematologic malignancies, reshaping how manufacturers prioritize pipeline assets. AstraZeneca PLC leverages its immuno-oncology infrastructure to sustain development programs in B-cell malignancies. F. Hoffmann-La Roche Ltd anchors its position through diagnostic-therapeutic integration in hematology. Pfizer Inc. competes via broad portfolio scale across oncology therapeutic classes.
Hairy cell leukemia treatment encompasses therapeutic interventions targeting the CD22-positive B-cell malignancy characterized by splenomegaly and pancytopenia, with cladribine and pentostatin serving as purine analog backbone agents alongside rituximab combination protocols. These treatments function to achieve durable complete remission through induction of apoptosis in malignant lymphocytes. Monoclonal antibodies occupy the premium tier within product type segmentation due to rituximab's established efficacy profile and biosimilar entry dynamics. Intravenous delivery mode dominates clinical practice, though subcutaneous formulations are gaining traction in outpatient settings. Oncology clinics represent the fastest-growing end user segment as care decentralizes from academic medical centers.
The FDA's orphan drug designation framework and EMA's parallel pathway for rare disease therapies shape clinical development economics and exclusivity timelines for manufacturers. BIS and CDSCO in India enforce import and quality standards for biologic therapies entering their respective jurisdictions. Stakeholders must monitor evolving reimbursement policies for combination regimens and the competitive entry of biosimilar monoclonal antibodies.
Market Dynamics
The FDA's accelerated approval pathways for rare disease therapeutics are compressing development timelines for purine analog-based regimens while reshaping how manufacturers prioritize pipeline assets in B-cell malignancies.
Growth Catalysts
- EMA Orphan Drug Incentives:The EU Orphan Drug Regulation consolidates market access benefits for rare hematologic malignancies, incentivizing manufacturers to advance novel therapeutic candidates.
- Oncology Clinic Expansion:Community-based oncology clinics in the United States and Germany are decentralizing care delivery, expanding patient access to cladribine and rituximab combination protocols.
- Subcutaneous Formulation Development:Subcutaneous delivery modes are gaining traction in outpatient settings, reducing infusion center burden and enabling same-day treatment administration.
Market Restraints
- Biologics Manufacturing Concentration:Monoclonal antibody production concentrates among a limited supplier base, creating vulnerability to capacity constraints and quality deviations.
- Reimbursement Complexity:Combination regimen pricing faces scrutiny from CMS and private payers in the United States, complicating access for multi-agent protocols.
- Biosimilar Substitution Pressure:Rituximab biosimilar entry is compressing margins for originator products while introducing therapeutic equivalence questions among hematologists.
Strategic Opportunities
- Japan's Aging Demographics:Japan's expanding elderly population and specialized hematology center network create concentrated demand for durable remission therapies.
- Diagnostic-Therapeutic Integration:CD22 biomarker testing convergence with treatment selection protocols enables precision medicine approaches in academic medical centers.
- CDSCO Pathway Expansion:India's Central Drugs Standard Control Organization is streamlining biologic import approvals, opening access for multinational manufacturers.
Industry Challenges
- Hematology Specialist Scarcity:Fellowship-trained hematologists remain concentrated in tertiary centers, limiting protocol expertise in community oncology settings.
- Cold Chain Integrity Requirements:Biologic therapy distribution demands continuous temperature monitoring from manufacturing through infusion, elevating logistics complexity.
- Legacy System Interoperability:Electronic health record fragmentation between academic centers and community clinics impedes real-time treatment response tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hairy Cell Leukemia Treatment Market |
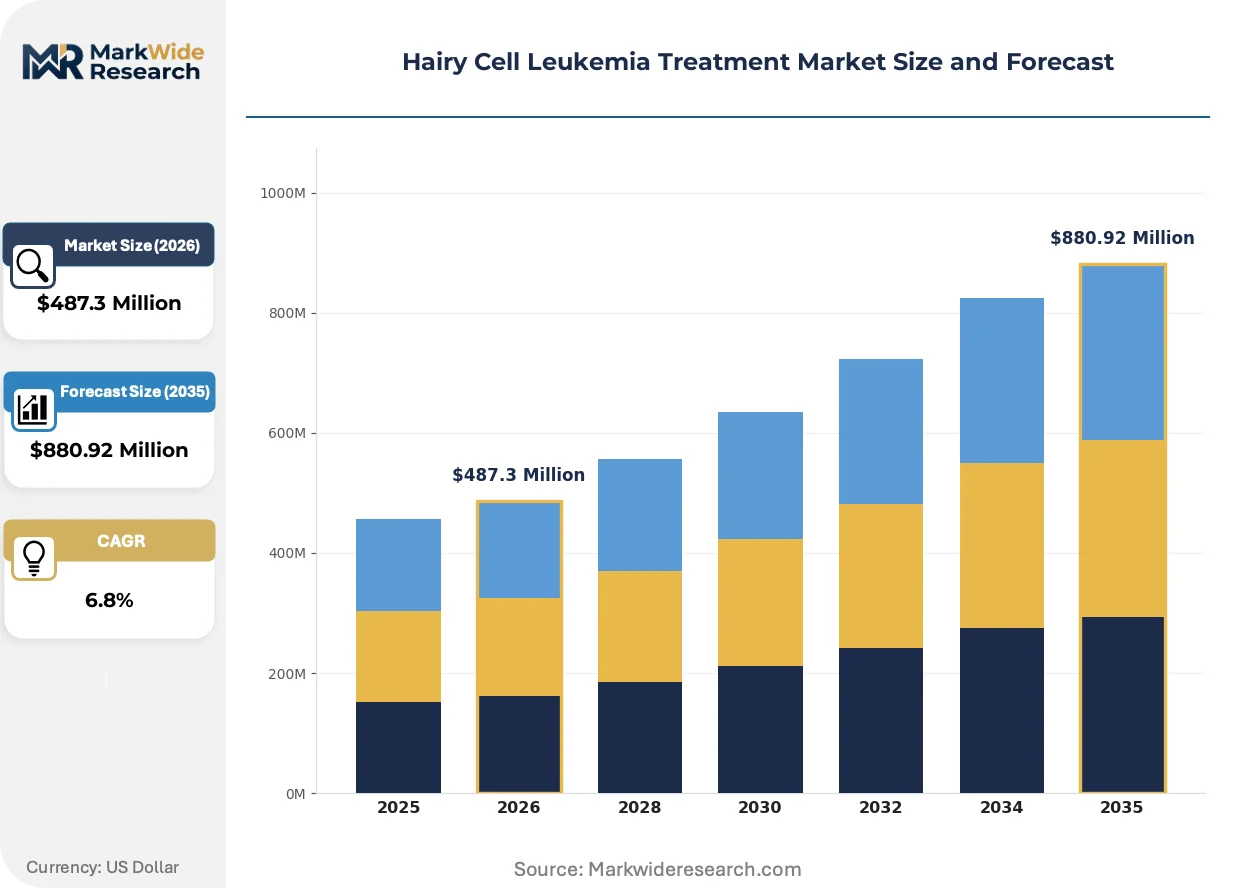
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy, Targeted Therapy, Immunotherapy Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Oncology Clinics, Research Institutions, Home Care Indication: Relapsed Disease, Newly Diagnosed, Resistant Disease, Maintenance Therapy |
| Companies Covered | AstraZeneca PLC, F. Hoffmann-La Roche Ltd, Pfizer Inc., Gilead Sciences, Amgen Inc., AbbVie Inc., Novartis AG, Teva Pharmaceutical Industries Ltd, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hairy Cell Leukemia Treatment Market Shifts & Advancements
Targeted therapy protocols are displacing empirical treatment selection in hairy cell leukemia, with molecular profiling and biomarker-driven regimens compressing the gap between diagnosis and optimal therapeutic intervention.
Next-generation sequencing panels are rewriting how clinicians identify BRAF V600E mutations and other actionable alterations in hairy cell leukemia. Academic medical centers in Germany and the United States are adopting these platforms at accelerating pace. The technology is rewriting the competitive landscape by enabling patient stratification that favors targeted agents over conventional chemotherapy backbones.
The FDA's orphan drug designation framework is extending exclusivity timelines and tax credit provisions for rare disease developers. Manufacturers are restructuring clinical trial designs to leverage accelerated approval pathways, reducing time-to-market for novel agents. Oncology clinics in the United States are responding by building specialized infrastructure to administer these premium-tier therapies.
Site-of-care migration is shifting infusion delivery from inpatient wards to ambulatory oncology clinics. Community-based providers in Germany and Japan are investing in outpatient capacity to capture this volume. This behavioral shift is most pronounced in the United States, where payer pressure and patient convenience preferences are driving same-day treatment administration models.
Hairy Cell Leukemia Treatment Market Segmentation
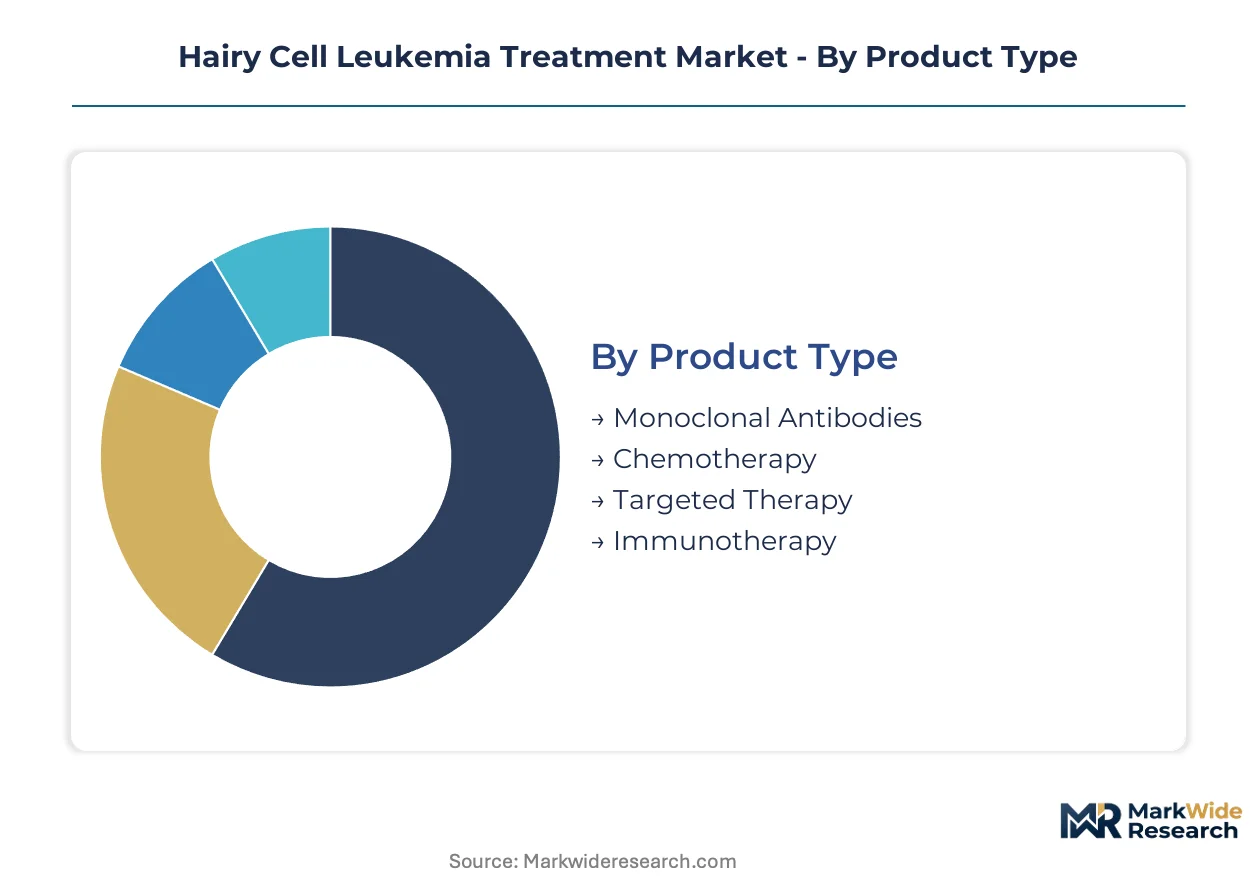
Segmentation in the hairy cell leukemia treatment market reveals how therapeutic modalities, administration routes, and care settings intersect to shape patient access and commercial opportunity. Understanding these divisions enables stakeholders to align development priorities with where clinical demand and reimbursement leverage concentrate.
Product Type:
Integration depth varies sharply across therapeutic categories, with some agents functioning as standalone protocols while others require combination frameworks to achieve efficacy.
- Monoclonal Antibodies:Rituximab and its biosimilar variants target CD20-positive malignant B-cells through antibody-dependent cellular cytotoxicity. Demand concentrates in academic medical centers in Germany and the United States where combination protocols with purine analogs dominate first-line care.
- Chemotherapy:Cladribine and pentostatin function as purine analog backbone agents inducing apoptosis in hairy cells. These agents see concentrated utilization in Japan's specialized hematology centers where durable remission rates drive protocol adherence.
- Targeted Therapy:BRAF inhibitors address V600E-mutant disease variants through selective kinase inhibition.
- Immunotherapy:Investigational checkpoint inhibitors and CAR-T approaches remain in clinical development pipelines.
Monoclonal antibodies lead volumes today; targeted therapy is gaining share fastest as biomarker testing expands.
Delivery Mode:
Cost tier stratification separates hospital-based infusion services from lower-acuity outpatient administration models.
- Intravenous:Hospital and oncology clinic infusion centers administer rituximab and cladribine through controlled intravenous delivery. This mode captures the majority of current treatment volume in the United States where CMS reimbursement structures favor facility-based administration.
- Subcutaneous:Formulation advances enable rituximab subcutaneous delivery reducing infusion center burden. Germany's community oncology clinics are adopting these protocols most aggressively as same-day administration models expand.
- Oral:BRAF inhibitor tablets enable home-based administration for relapsed or resistant disease.
- Intramuscular:Limited application for supportive care agents in treatment protocols.
Intravenous delivery dominates revenue today; subcutaneous formulations are climbing the fastest as site-of-care migration accelerates.
End User:
Customer type fragmentation reflects the tension between centralized academic expertise and decentralized community access.
- Oncology Clinics:Community-based infusion centers in the United States and Germany are expanding capacity to capture hairy cell leukemia volume. These settings prioritize subcutaneous protocols and same-day administration to compete with hospital outpatient departments.
- Hospitals:Tertiary academic centers retain complex case referrals including resistant disease and combination protocol management. Japan's national hospital network concentrates specialized hematology expertise in designated cancer centers.
- Research Institutions:Academic medical centers conduct investigator-initiated trials for novel targeted agents and immunotherapy combinations.
- Home Care:Limited to oral targeted therapy administration with remote monitoring protocols.
Hospitals retain the highest acuity cases today; oncology clinics are expanding most quickly as care decentralizes.
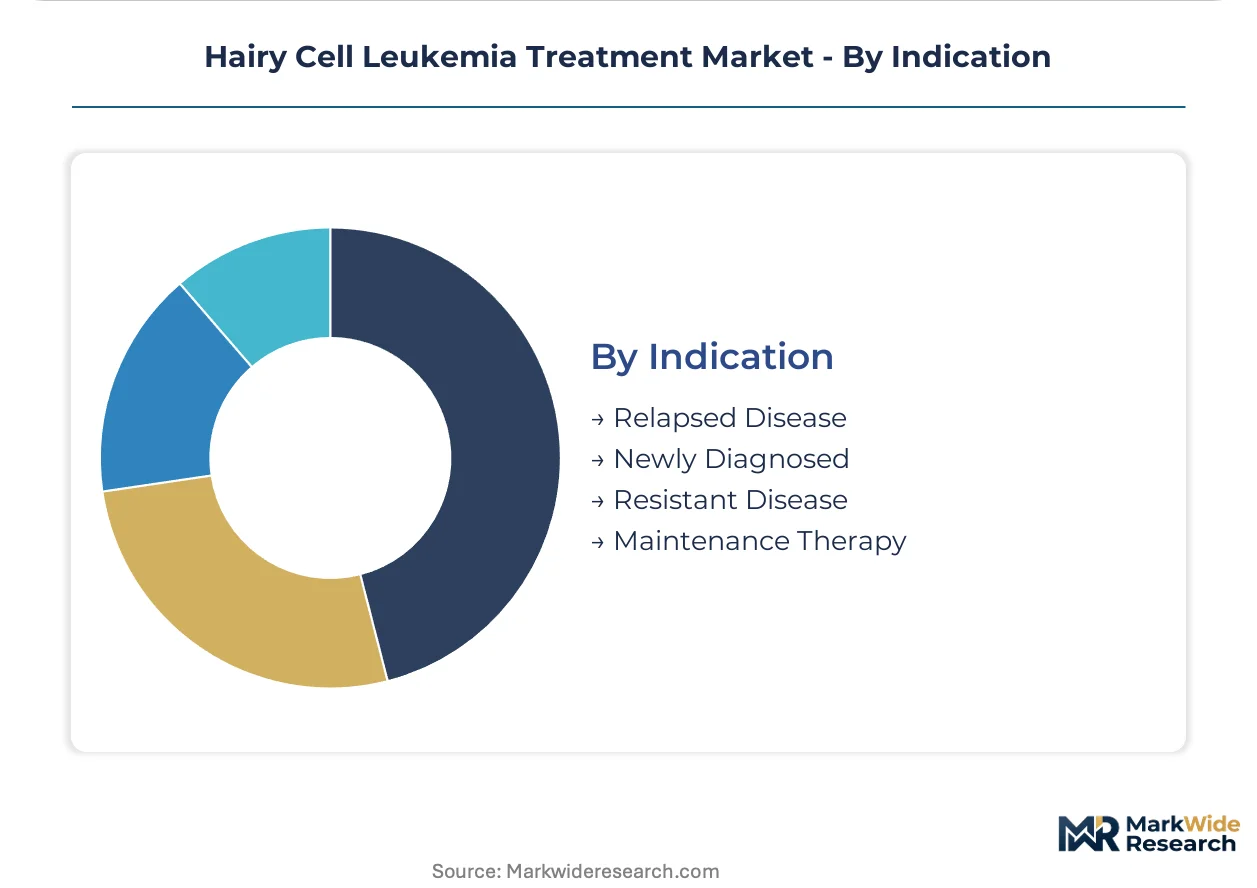
Indication:
Application urgency separates curative-intent first-line protocols from chronic management of relapsed or resistant disease.
- Newly Diagnosed:First-line cladribine or pentostatin protocols with or without rituximab consolidation represent the largest addressable population. Treatment centers in the United States and Germany emphasize complete remission as the primary endpoint.
- Relapsed Disease:Second-line rituximab monotherapy or re-treatment with purine analogs targets patients with disease recurrence. Japan's aging demographics generate concentrated demand for salvage protocols in elderly populations.
- Resistant Disease:BRAF inhibitor therapy and investigational agents address refractory cases with actionable mutations.
- Maintenance Therapy:Extended rituximab schedules for high-risk remission maintenance remain controversial in clinical practice.
Newly diagnosed cases dominate treatment initiations today; relapsed disease protocols are gaining share fastest as long-term follow-up cohorts expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hairy cell leukemia treatment protocols originated in academic medical centers across the United States and Germany during the 1980s, establishing the clinical foundations that now diffuse through specialized hematology networks worldwide.
United States
Oncology clinics in Texas and Florida are expanding outpatient capacity to capture decentralized infusion volume. The FDA's orphan drug designation framework extends market exclusivity and tax incentives for rare disease developers. Memorial Sloan Kettering Cancer Center in New York anchors biomarker-driven protocol adoption, integrating CD22 testing with treatment selection.
Germany
Community-based hematology practices in Bavaria and North Rhine-Westphalia prioritize same-day administration models. EMA parallel pathways for rare disease therapies compress regulatory timelines for purine analog developers. Heidelberg University Hospital concentrates resistant disease expertise, managing complex salvage protocols through its National Center for Tumor Diseases.
Japan
Specialized hematology centers in Tokyo and Osaka face concentrated demand from an aging patient population requiring durable remission therapies. PMDA's sakigake designation system accelerates priority review for innovative oncology agents. The National Cancer Center Hospital in Tokyo coordinates investigator-initiated trials for next-generation B-cell targeting modalities.
India
CDSCO is streamlining biologic import approvals, enabling multinational manufacturers to supply rituximab and cladribine to tertiary oncology centers. Maharashtra's Tata Memorial Hospital in Mumbai serves as the referral hub for complex hematologic malignancies across South Asia. Delhi-based Apollo Hospitals are building cold chain infrastructure to support temperature-sensitive monoclonal antibody distribution.
Switzerland
Roche's diagnostic-therapeutic integration model shapes how Swissmedic regulates companion diagnostic approvals for hematology applications. Basel anchors European headquarters operations for major oncology developers, concentrating regulatory affairs and medical affairs functions. University Hospital Basel maintains reference laboratory status for BRAF mutation testing in hairy cell leukemia subtypes.
Hairy Cell Leukemia Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the therapeutic modality spectrum, with monoclonal antibody originators commanding pricing power against purine analog generics. The market structure consolidates around three strategic archetypes: large-cap pharmaceutical conglomerates with immuno-oncology infrastructure, mid-sized biotech specialists in B-cell malignancies, and emerging biosimilar manufacturers compressing originator margins. Dominant competitive moves include diagnostic-therapeutic integration partnerships and subcutaneous formulation development to capture site-of-care migration.
Within the large-cap tier, AstraZeneca PLC and F. Hoffmann-La Roche Ltd occupy positions defined by broad oncology platform scale and hematology-specific infrastructure investment. Roche exemplifies the diagnostic-therapeutic integration archetype through its Basel-centered regulatory and commercial operations. Pfizer Inc. represents portfolio diversification strategy across therapeutic classes, leveraging manufacturing scale to compete in combination regimen markets. These three anchors demonstrate how geographic concentration in Switzerland, the United Kingdom, and the United States shapes competitive positioning in rare hematologic malignancies.
| Leading Market Players |
|---|
| AstraZeneca PLC |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Gilead Sciences |
| Amgen Inc. |
| AbbVie Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Captive biologics manufacturing anchors both supply security and pricing power for monoclonal antibody originators, with Roche's Basel-centered vertical integration insulating rituximab from biosimilar cost compression while community oncology clinics in Germany and the United States absorb margin pressure through site-of-care arbitrage.
Pricing Analysis
Three-tier pricing structure across originator biologics, biosimilar alternatives, and generic purine analogs separates premium monoclonal antibodies from standard-of-care chemotherapy backbones. Price differentiation rests on FDA orphan drug exclusivity and EMA parallel pathway incentives versus post-patent commodity competition. Cost compression in the biosimilar tier is intensifying because CMS reimbursement parity and private payer formulary preference erode originator volume. Community oncology clinics exhibit highest price sensitivity; academic medical centers demonstrate lowest due to protocol adherence and research funding insulation.
Supply Chain Analysis
FDA Current Good Manufacturing Practice certification and EMA GMP compliance function as non-negotiable gating mechanisms for biologic active pharmaceutical ingredient sourcing. Manufacturing concentrates in Switzerland, the United States, and Ireland where cold chain infrastructure and sterile fill-finish capacity cluster. Raw material dependencies span recombinant cell lines, proprietary media formulations, and single-use bioreactor components. Single-source vulnerability pervades the supplier base for critical bioreactor hardware. Distribution runs through specialized pharmaceutical wholesalers with temperature-validated logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hairy cell leukemia treatment market functions as a geographic-arbitrage play where EMA orphan drug incentives in Germany and accelerated FDA pathways in the United States create divergent cost structures for clinical development and commercial launch.
For Market Incumbents: Lock in diagnostic-therapeutic integration partnerships to defend against biosimilar substitution and site-of-care migration threatening originator monoclonal antibody volume. Deepen backward integration into companion diagnostic development to capture biomarker-driven protocol selection. Prioritize subcutaneous formulation investment to retain community oncology clinic relationships as same-day administration models expand. For New Entrants and Emerging Players: Oncology clinic networks in Japan's aging demographic corridors represent the most penetrable channel partner type for novel BRAF inhibitor and investigational immunotherapy candidates. Target salvage protocol positioning in resistant disease where academic medical center concentration enables specialist prescriber access. Pursue PMDA sakigake designation to compress regulatory timelines and establish early-mover presence in Tokyo-Osaka treatment corridors. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap B-cell malignancy specialists because hematology expertise scarcity and orphan drug exclusivity timelines create durable margin structures resistant to commoditization. Platform consolidation across purine analog, monoclonal antibody, and targeted therapy modalities offers long-term viability through protocol lifecycle management. Watch FDA accelerated approval conversion rates to full approval as the critical inflection indicator for pipeline asset valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables same-day administration in German community oncology clinics competing with hospital outpatient departments. |
| Diagnostic-Therapeutic Integration Partnership | Positions Roche and AstraZeneca to capture CD22 biomarker-driven treatment selection in Memorial Sloan Kettering protocols. |
| EMA Orphan Drug Pathway Advancement | Compresses regulatory timelines for purine analog developers seeking Bavaria and North Rhine-Westphalia market entry. |
| Biosimilar Manufacturing Scale-Up | Threatens originator rituximab margins as CMS reimbursement parity drives formulary substitution in United States oncology clinics. |
| CDSCO Import Approval Streamlining | Opens access for multinational manufacturers to supply Tata Memorial Hospital and Apollo Hospitals networks across India. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded the qualitative foundation, cross-referenced with FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Secondary validation drew from SEC 10-K oncology segment disclosures, CMS Medicare reimbursement data, and GPO contract repositories. Bottom-up patient-flow modeling and top-down therapeutic class sizing enabled triangulation across independent estimation approaches.
Market size and growth trajectory outputs reflect segmentation across product type, delivery mode, end user, and indication dimensions throughout the projection horizon. CAGRs derived from treatment initiation rates, protocol duration assumptions, and pricing evolution by therapeutic tier. Forecast inputs incorporated PMDA sakigake designation velocity, biosimilar substitution elasticity, and site-of-care migration coefficients specific to ambulatory oncology expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory pathway modifications, biosimilar entry sequencing, and hematology specialist workforce expansion. The analysis reflects documented assumptions regarding orphan drug exclusivity periods, reimbursement policy stability, and cold chain infrastructure investment trajectories. A model refresh is warranted upon material change in FDA accelerated approval conversion standards or EMA parallel pathway harmonization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Febrile Neutropenia Market
Hematology
Malignant Lymphoma Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Global Bleeding Disorders Market
Hematology
Sickle Cell Anemia Market
Hematology
Single Blood Drop Analysis Market
Hematology
Hematology Analyzers Market
Hematology
Apheresis Market
Hematology
Myelodysplastic Syndrome (MDS) Treatment Market
Hematology
Pancytopenia Market