
 Portable Grinders Market | 2026-2036
Portable Grinders Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Grinders Market Outlook
A shortage of certified welding and metalworking technicians is redrawing how equipment suppliers allocate training and service resources. Makita leverages its battery-platform ecosystem to cross-sell grinders to existing cordless tool users. Bosch sustains engineering intensity through in-house motor and electronics development for its professional lines. DeWalt competes on jobsite durability ratings and fleet-management compatibility across North American construction accounts.
Portable grinders are handheld rotary power tools using abrasive discs rated by diameter, spindle thread, and rotational speed to remove material or finish surfaces. Units typically operate at 6,000–12,000 RPM with guards enclosing 180 degrees of the disc perimeter for operator protection. Angle grinders dominate volume due to versatility across grinding, cutting, and polishing applications in construction and metal fabrication. Battery-powered units represent the fastest-expanding power source segment as lithium-ion cell costs decline and runtime thresholds cross eight-hour shift requirements. Pneumatic grinders retain share in fixed-shop environments where compressed air infrastructure eliminates battery-swapping downtime.
OSHA enforces permissible exposure limits for hand-arm vibration and respirable silica that directly shape guard design and dust-collection attachment requirements for grinders sold into U.S. construction. The EU Machinery Directive and CE marking framework mandate emergency stop functionality, spindle-lock safety, and documented noise-emission declarations for market access across member states. Stakeholders must monitor how impending battery-transport regulations and right-to-repair legislation alter aftermarket service economics and replacement-part availability.
Market Dynamics
Battery energy density improvements are compressing the cost-performance gap between cordless and corded portable grinders, forcing incumbent suppliers to restructure their motor and electronics supply chains around lithium-ion platforms rather than traditional AC architectures.
Growth Catalysts
- OSHA Silica Rule Enforcement:Tightened respirable crystalline silica exposure limits in U.S. construction are mandating integrated dust-collection systems on angle grinders, accelerating replacement cycles for non-compliant legacy fleets.
- Metal Fabrication Cluster Expansion:Export-oriented workshops in China's Jiangsu and Guangdong provinces are scaling pneumatic and electric grinder procurement to match integrated supply chain demands from automotive and appliance OEMs.
- Lithium-Ion Cell Cost Curves:Declining battery pack economics are pushing runtime thresholds past eight-hour shift requirements, unlocking cordless adoption in high-duty-cycle metalworking applications previously reserved for corded units.
Market Restraints
- Neodymium Magnet Supply Concentration:Rare-earth magnet sourcing for brushless motor rotors remains concentrated among Chinese refiners, exposing motor manufacturers to export quota volatility and price spikes.
- Hand-Arm Vibration Exposure Limits:EU Machinery Directive amendments and OSHA permissible exposure limits for vibration are forcing costly redesigns of spindle assemblies and handle damping systems.
- Pneumatic Infrastructure Lock-In:Fixed-shop metal fabrication facilities with sunk compressed air investments face high switching costs to electrify grinder fleets despite cordless performance improvements.
Strategic Opportunities
- Right-to-Repair Legislation:Pending EU and U.S. state-level repair mandates are creating aftermarket service revenue streams through authorized spare-part distribution and diagnostic tool licensing.
- Robotic Weld Grinding Integration:Collaborative robot deployments in automotive stamping plants are opening demand for precision pneumatic grinders with force-feedback interfaces and standardized tool-change systems.
- Indonesian Shipbuilding Expansion:Batam and Surabaya port infrastructure investments are driving grinder procurement for hull preparation and coating removal in Southeast Asian maritime maintenance clusters.
Industry Challenges
- Certified Welding Technician Shortage:Metal fabrication employers in Germany and the United States report unfilled positions for skilled grinding and finishing specialists, forcing equipment suppliers to absorb training and technical support costs.
- CE Marking Documentation Burden:Extended technical file preparation and notified body review timelines for EU Machinery Directive compliance are delaying product launches by 6-12 months for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Grinders Market |
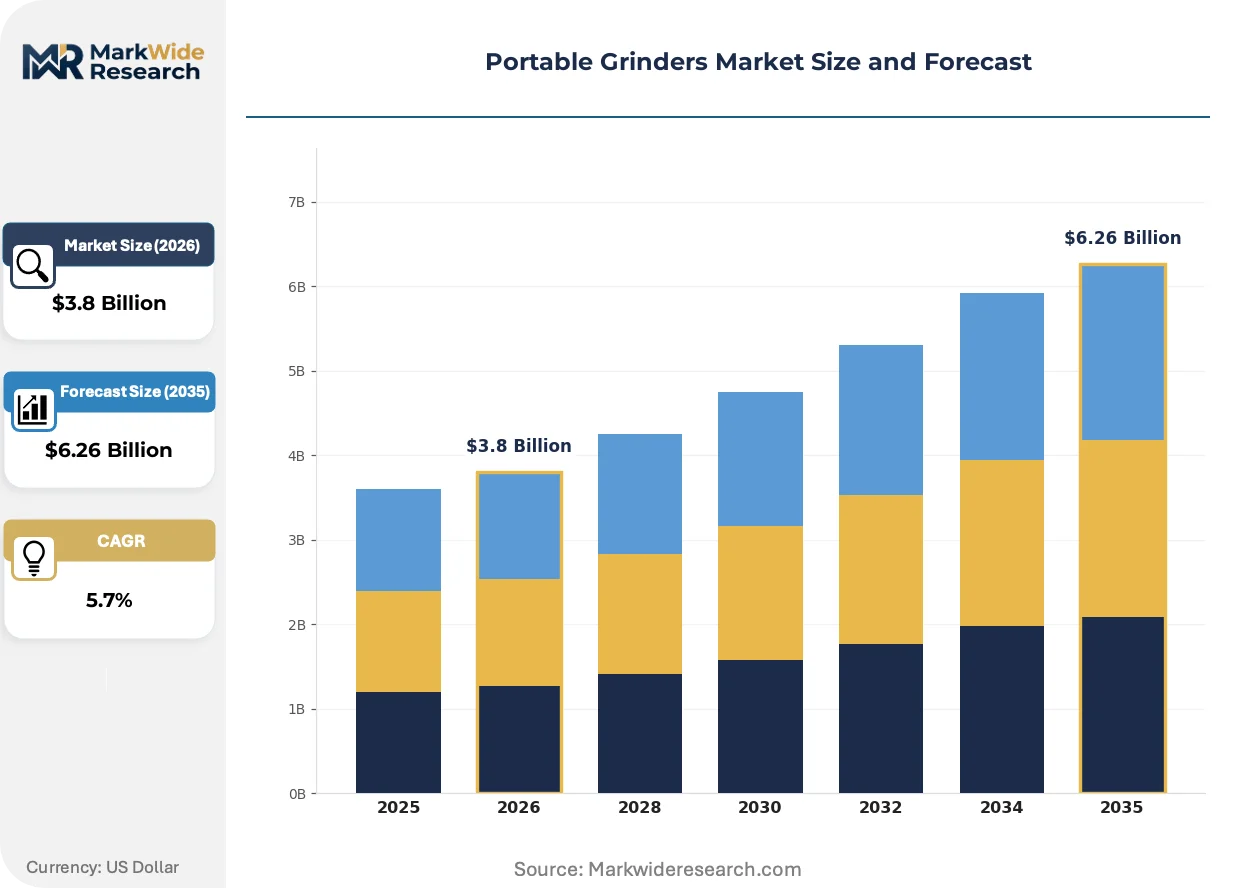
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angle Grinders, Die Grinders, Bench Grinders, Straight Grinders Power Source: Electric, Battery-Powered, Pneumatic, Hydraulic End User: Construction, Metal Fabrication, Woodworking, Automotive Repair Application: Grinding, Polishing, Cutting, Sharpening |
| Companies Covered | Bosch, Makita, DeWalt, Hilti, Metabo, Milwaukee, Festool, Stanley Black & Decker, Koki Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Grinders Market Strategic Shifts
Electrification of handheld power tools is converging with connectivity and safety mandates to redefine grinder architecture, with suppliers racing to integrate battery management, vibration sensing, and dust containment into unified platform designs.
Brushless DC motor technology is miniaturizing. Permanent-magnet rotor designs with Hall-effect commutation are replacing brushed universal motors in 4.5-inch and 5-inch angle grinder form factors. German and Japanese metal fabrication contractors are specifying brushless units for continuous-duty grinding operations where thermal management previously limited runtime. This motor architecture is miniaturizing power density thresholds, enabling 18V battery packs to deliver corded-equivalent torque in sub-2.5kg chassis weights.
EU Machinery Directive 2006/42/EC amendments are mandating emergency-stop functionality and documented noise-emission declarations for all professional-grade grinders seeking CE marking. Industrial safety auditors in French and Italian metalworking clusters are rejecting imports lacking spindle-lock safety mechanisms and 180-degree guard coverage. North American distributors are pre-emptively sourcing EU-compliant inventory to avoid parallel certification costs, compressing the specification gap between regional product lines.
Equipment-as-a-service contracting is displacing capital purchase models for high-volume metal fabrication fleets. Tier-one automotive stamping plants in Michigan and Ontario are negotiating all-inclusive per-hour grinding rates that bundle tool provision, maintenance, and consumable supply. This procurement restructuring is concentrating purchasing authority among integrated facility management providers and eroding traditional distributor relationships with individual maintenance supervisors.
Portable Grinders Market Segmentation
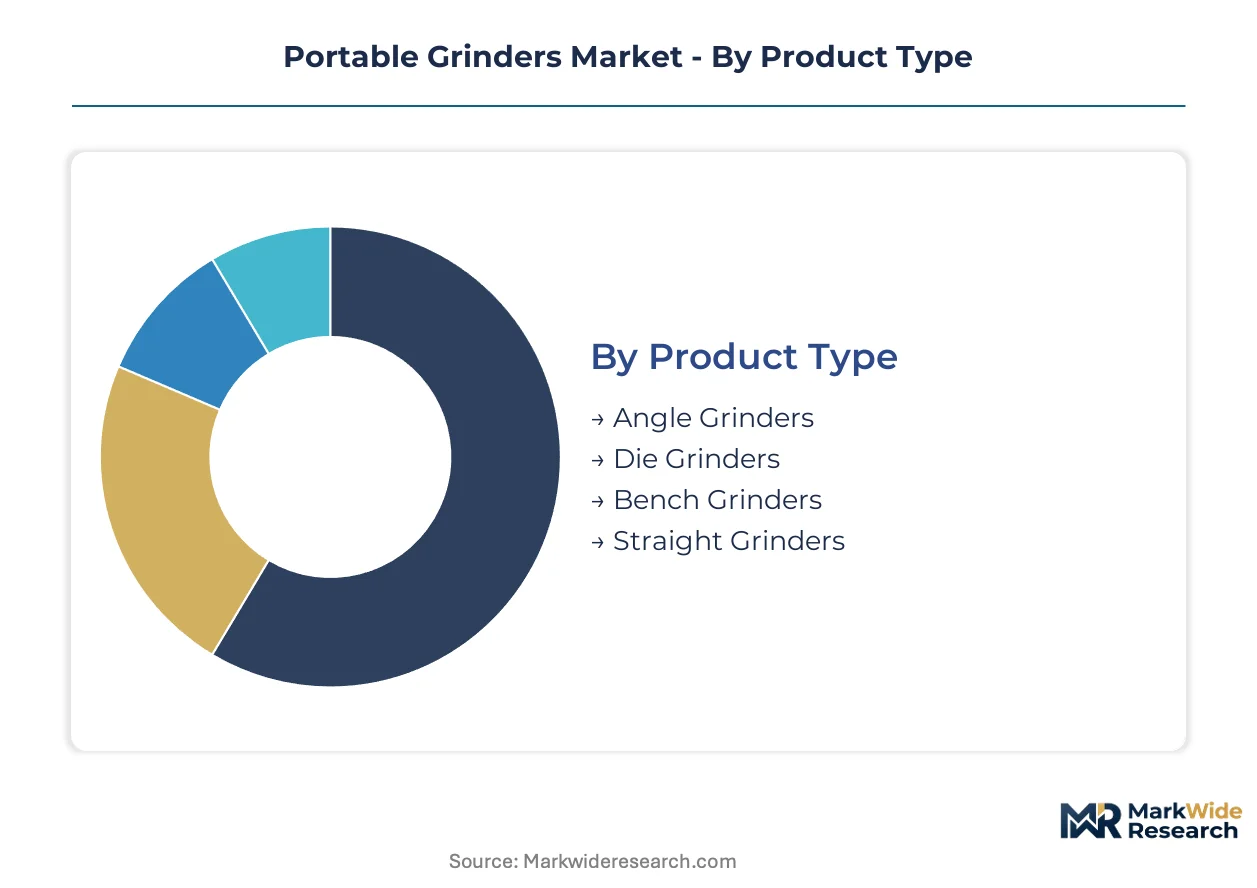
Portable grinder procurement patterns diverge sharply across power platforms and end-use environments. Regulatory mandates on vibration exposure and silica containment reshape specification requirements differently for each product configuration.
Product Type:
OSHA guard-angle specifications and EU Machinery Directive spindle-lock requirements apply unevenly across form factors, with handheld rotary designs facing stricter kinetic-energy containment rules than fixed-station units.
- Angle Grinders:Disc diameters from 4.5 to 9 inches spin at 6,000–12,000 RPM with 180-degree guard enclosures. Metal fabrication workshops in Germany specify these for weld seam removal and surface preparation where OSHA silica rules mandate integrated dust-collection shrouds.
- Die Grinders:Compact collet-driven spindles accept mounted points and carbide burrs for precision deburring in tight geometries. Automotive stamping plants in Michigan deploy pneumatic die grinders for flash removal on pressed steel components.
- Bench Grinders:Stationary dual-wheel machines with tool rests and eye shields serve sharpening and rough grinding in fixed-shop environments. These face reduced cordless substitution pressure compared to handheld categories.
- Straight Grinders:Extended spindle designs reach into deep cavities for internal grinding and porting work. Foundries in China's Jiangsu province source straight pneumatic units for casting cleanup operations.
Established volume favors angle grinders; emerging adoption favors die grinders in automated finishing cells.
Power Source:
Runtime economics and infrastructure sunk costs divide procurement between battery platforms and compressed-air networks, with lithium-ion cell cost curves compressing the cordless-corded performance gap fastest in high-duty-cycle metalworking.
- Electric:Corded AC universal motors deliver sustained torque for continuous grinding without battery-swap downtime. U.S. construction contractors specify corded angle grinders for concrete surface grinding where silica exposure limits require uninterrupted dust-collection operation.
- Battery-Powered:Brushless DC motors paired with 18V–54V lithium-ion packs now achieve corded-equivalent power density in sub-2.5kg chassis weights. German metal fabrication workshops are expanding cordless fleets as battery energy density improvements push runtime past eight-hour shift thresholds.
- Pneumatic:Vane motors powered by shop compressed air eliminate battery logistics entirely. Fixed-shop facilities in China's Guangdong export clusters retain pneumatic infrastructure to avoid charging-station capital investment.
- Hydraulic:High-torque radial piston motors operate in explosive atmospheres where electrical spark risk is prohibitive. Offshore platform maintenance contractors in Southeast Asian maritime clusters specify hydraulic grinders for coating removal in hazardous zones.
Procurement concentrates in pneumatic systems for captive-shop environments; cordless platforms gain share fastest in mobile construction and field repair applications.
End User:
Duty-cycle intensity and dust-exposure profiles shape grinder specification differently across verticals, with construction and metal fabrication driving regulatory-compliant feature adoption.
- Construction:Masonry cutting and concrete surface preparation generate respirable silica loads that trigger OSHA enforcement actions. U.S. general contractors now specify angle grinders with factory-integrated dust-collection shrouds to comply with permissible exposure limits.
- Metal Fabrication:Continuous weld grinding and finishing operations impose thermal management demands on motor architecture. Brushless DC units with Hall-effect commutation dominate new fleet specifications in German and Japanese metalworking clusters.
- Woodworking:Lower abrasive loading and reduced spark hazard permit lighter-duty motor specifications. Furniture manufacturers in China's eastern provinces source mid-tier electric units for edge profiling and shaping tasks.
- Automotive Repair:Intermittent use patterns and space constraints favor compact cordless platforms. Collision repair shops in North American markets prioritize battery-platform compatibility across multi-tool fleets.
Metal fabrication sustains premium pricing for thermal-rated brushless designs; construction drives fastest regulatory-mandated replacement cycles.
Application:
Abrasive specification and guard configuration vary by material-removal mode, with cutting applications imposing the most severe kinetic-energy containment requirements under EU Machinery Directive amendments.
- Grinding:Stock removal with depressed-center wheels demands 180-degree guard coverage and spindle-lock safety mechanisms. French industrial safety auditors reject imports lacking documented noise-emission declarations for professional grinding applications.
- Polishing:Lower-speed operation with fiber discs and flap wheels reduces guard-interference concerns. Automotive OEM paint shops in Ontario specify variable-speed grinders for clear-coat defect removal.
- Cutting:Thin abrasive discs operating at edge speed limits face catastrophic failure risks that mandate reinforced guard designs. Diamond blade cutting of concrete triggers the strictest OSHA silica rule compliance requirements.
- Sharpening:Controlled material removal at reduced speeds permits bench-mounted fixed-station configurations. Woodworking shops in U.S. Midwest markets source slow-speed wet grinders for chisel and plane iron maintenance.
Grinding commands the broadest specification range across power sources; cutting applications concentrate regulatory scrutiny and drive guard-redesign investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metal fabrication workshops favor pneumatic infrastructure for fixed-shop operations, while U.S. construction contractors prioritize cordless platforms for silica-compliant mobility. China's export-oriented clusters source mid-tier electric units for integrated automotive supply chains.
United States
OSHA silica rule enforcement drives replacement cycles for dust-collection-equipped angle grinders in commercial construction. Contractors in Texas and California specify factory-integrated shrouds to comply with permissible exposure limits. Fleet-management compatibility shapes procurement decisions across North American general contracting accounts.
Germany
Metal fabrication employers face certified welding technician shortages that force equipment suppliers to absorb training costs. The EU Machinery Directive mandates emergency-stop functionality and documented noise-emission declarations for CE marking. Workshops in Baden-Württemberg specify brushless DC units for continuous-duty thermal management.
China
Export-oriented metalworking clusters in Jiangsu and Guangdong provinces scale pneumatic and electric grinder procurement for automotive OEM supply chains. The country's national machinery safety standards align with CE marking requirements for export-bound production. Battery platform ecosystems gain traction in mobile repair applications.
Japan
Automotive stamping plants deploy collaborative robots with force-feedback pneumatic grinders for precision weld grinding. METI industrial standards shape motor efficiency and vibration exposure specifications. Manufacturing clusters in Aichi Prefecture specify Hall-effect commutation systems for high-duty-cycle finishing operations.
Indonesia
Shipbuilding expansion in Batam and Surabaya drives grinder procurement for hull preparation and coating removal. Port infrastructure investments support Southeast Asian maritime maintenance cluster formation. Compressed air infrastructure dominates fixed-yard metal fabrication facilities.
Portable Grinders Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the portable grinders market. The upper tier commands battery-platform ecosystems and in-house motor development capabilities. Specialists concentrate on pneumatic systems for captive-shop environments or hydraulic units for hazardous-zone applications. Competitive moves center on cross-selling battery-platform compatibility and restructuring supply chains around lithium-ion architectures.
Within the integrated-tool-platform tier, Bosch GmbH and Makita Corporation exemplify archetypes that anchor professional-grade positioning through captive electronics and motor development. DeWalt occupies a position representing jobsite durability specialization and fleet-management integration for North American construction accounts. These three entities represent distinct strategic vectors: German engineering-intensive vertical integration, Japanese battery-platform ecosystem breadth, and U.S.-focused contractor-grade durability specification.
| Leading Market Players |
|---|
| Bosch |
| Makita |
| DeWalt |
| Hilti |
| Metabo |
| Milwaukee |
| Festool |
| Stanley Black & Decker |
| Koki Holdings |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for brushless motor assemblies expose pricing power asymmetries between integrated platform suppliers and mid-tier assemblers dependent on Chinese rare-earth magnet sourcing. This lead-time compression concentrates margin pressure on non-captive producers while amplifying the procurement leverage of battery-platform ecosystem owners.
Pricing Analysis
Long-term fleet-service contracts now dominate high-volume metal fabrication procurement, displacing transactional spot purchasing across North American automotive stamping plants. Pricing stratifies across premium brushless platforms with Hall-effect commutation, standard AC-motor units for fixed-shop pneumatic infrastructure, and economy-tier imports lacking CE-compliant spindle-lock mechanisms. Cost compression in the economy tier is intensifying because Indonesian and Vietnamese assemblers are absorbing tariff exposure to maintain volume share. Construction contractors show the highest price sensitivity due to silica-compliance mandates that force unbudgeted dust-collection upgrades, while German metal fabrication workshops prioritize thermal-rated specifications over unit cost.
Supply Chain Analysis
China dominates rare-earth magnet refining and lithium-ion cell production, while Japan and Germany anchor precision motor manufacturing and Hall-effect sensor fabrication. Brushless DC motor production draws from neodymium-iron-boron magnet supply concentrated among Chinese refiners, copper winding stock from Chilean and Peruvian mining operations, and semiconductor-grade silicon for power electronics. Single-source vulnerability in magnet sourcing exposes motor manufacturers to export quota volatility. Distribution runs through integrated facility management providers consolidating purchasing authority for tier-one automotive accounts, alongside traditional industrial distributors serving fragmented metal fabrication shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cordless platform substitution threatens pneumatic incumbent positions as battery runtime thresholds cross continuous-duty requirements. Incumbents must navigate this technology transition while defending aftermarket service revenue against right-to-repair regulatory fragmentation.
For Market Incumbents: Secure captive battery-platform compatibility across grinder, drill, and saw product lines to lock in fleet-standardization decisions at North American construction accounts. Deepen upstream control over brushless motor controller firmware to differentiate thermal management performance against emerging Asian competitors. Defend against pneumatic-to-electric substitution by bundling charging infrastructure capital into per-hour service contracts for captive-shop metal fabrication clients. For New Entrants and Emerging Players: Aftermarket diagnostic tool licensing represents an under-served layer where EU repair mandates are creating authorized-service revenue pools without requiring full manufacturing scale. Target Indonesian shipbuilding maintenance clusters in Batam and Surabaya where compressed air infrastructure limitations favor cordless adoption but established platform ecosystems remain under-penetrated. Pursue white-label supply agreements with integrated facility management providers seeking to bypass traditional distributor markups for high-volume grinding operations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized pneumatic grinder divisions lacking battery-platform development roadmaps. Long-term viability in this market hinges on lithium-ion ecosystem participation density and right-to-repair compliance infrastructure. Monitor EU battery-transport regulation implementation timelines as an inflection indicator for aftermarket service margin compression versus spare-part revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | Cross-selling brushless grinders to existing cordless tool users locks in fleet-standardization decisions at construction accounts. |
| Backward Integration into Motor Controllers | In-house Hall-effect commutation firmware development differentiates thermal management against commodity brushless competitors. |
| Right-to-Repair Compliance Infrastructure | Authorized spare-part distribution networks capture aftermarket revenue streams from pending EU and U.S. state mandates. |
| Equipment-as-a-Service Contracting | Per-hour grinding rates bundling tools, maintenance, and consumables concentrate purchasing authority with facility management providers. |
| Collaborative Robot Integration | Force-feedback pneumatic grinders with standardized tool-change systems address precision weld grinding demand in automotive stamping plants. |
Study Parameters
Desk research of EU Machinery Directive technical file databases, OSHA enforcement action records, and customs trade data preceded structured interviews with maintenance directors at German metal fabrication workshops, procurement leads at North American construction general contractors, and aftermarket service heads at integrated tool-platform suppliers. Primary fieldwork with plant engineers in China's Jiangsu province and collision repair shop owners across the U.S. Midwest validated battery-platform adoption patterns. Secondary sources included SEC filings of listed industrial equipment manufacturers, ECHA substance restriction notifications, and production statistics from Japanese METI industrial surveys. Bottom-up unit shipment estimates triangulated against top-down value projections derived from distributor revenue disclosures.
Variance decomposition across power source segments, end-use verticals, and regional regulatory clusters shaped the analytical framework over the projection horizon. Modeled dimensions included motor architecture type, battery voltage platform, duty-cycle intensity classification, and CE marking compliance tier. CAGRs were derived from logistic diffusion curves fitted to cordless adoption rates in high-duty-cycle metalworking applications. Industry-specific forecast inputs incorporated lithium-ion cell cost curve trajectories and hand-arm vibration exposure limit amendment timelines from EU notified body consultations.
Underlying assumptions cover sustained OSHA silica rule enforcement intensity, stable rare-earth magnet export quota administration, and linear battery energy density improvement rates, with deviation risk concentrated in abrupt EU Machinery Directive guard-design amendments or disruptive solid-state battery commercialization. Recalibration cycles align with material shifts in regulatory enforcement patterns, battery chemistry transitions, and major platform ecosystem acquisition activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Drain Cleaning Equipment Market
Tools
Entrenching Tool Market
Tools
Broaching Tools Market
Tools
Hydraulic Tools Market
Tools
Blowing Torch Market
Tools
Global Construction Camera Market
Tools
Floor Polishing Machine Market
Tools
Tool Hammer Market
Tools
Total Station Market
Tools
Rotary Knife Cutters Market
Tools
Portable Tools Market
Tools
Hand Saw Market
Tools
Telescopic Tool Boxes Market
Tools
Vise-Grip Pliers Market
Tools
Digital Levels Market
Tools
Engraver Machine Market