
 Belt File Sander Market | 2026-2036
Belt File Sander Market Size, Share, and Industry Trends Forecast 2026-2036
Belt File Sander Market Insights
Single-source supply of abrasive drive systems is pivoting toward dual-source arrangements as OEMs seek resilience against component shortages. Makita leverages its vertical integration into motor manufacturing to control cost structures across cordless and electric variants. BOSCH sustains technology leadership in variable-speed electronics, while DeWalt competes through aggressive channel control in North American retail networks.
A belt file sander is a power tool combining a continuous abrasive belt with a narrow file-shaped platen, typically operating at surface speeds between 5 and 15 meters per second to grind, shape, or finish metal and wood substrates in confined areas. Portable belt sanders dominate volume sales due to flexibility across construction sites and repair workshops, though stationary belt sanders command higher margin pools in industrial fabricator settings. Cordless belt sanders represent the fastest-growing technology segment as lithium-ion battery density improvements enable runtime parity with corded units.
OSHA silica exposure limits and EPA National Emission Standards for Hazardous Air Pollutants shape product design by mandating integrated dust extraction ports and sealed bearing housings. ISO 28927 ergonomic vibration standards further constrain form-factor decisions for manufacturers targeting European and North American certification paths. Stakeholders must monitor evolving battery transport regulations and raw-material sourcing disclosures as these become gatekeeping requirements for market access.
Market Dynamics
OSHA silica exposure limits and EPA dust-collection mandates are forcing manufacturers to redesign belt file sanders with integrated extraction ports and sealed housings, while lithium-ion battery density improvements are compressing the performance gap between cordless and corded variants.
Growth Catalysts
- Workplace Safety Mandates:OSHA's crystalline silica rule compels metal fabrication shops to upgrade to dust-extraction-equipped belt file sanders, accelerating replacement cycles in the United States.
- Industrial Cluster Upgrades:Furniture manufacturers in Germany and China are expanding precision finishing capabilities, concentrating demand for high-torque belt file sanders with variable-speed control.
- Battery Chemistry Advances:Lithium-ion cell energy density improvements enable cordless belt file sanders to match corded runtime, opening mobile repair applications across construction sites.
Market Restraints
- Critical Mineral Concentration:Cobalt and lithium supply chains concentrate in the Democratic Republic of Congo and China, exposing cordless product lines to geopolitical disruption and price volatility.
- Technical Limitation:Belt file sanders cannot achieve the surface finish quality of random-orbit sanders for fine woodworking, capping penetration in high-end furniture finishing.
- Regulatory Friction:UN 38.3 lithium battery transport regulations complicate cross-border distribution of cordless units, adding compliance overhead for manufacturers.
Strategic Opportunities
- Underpenetrated Fabrication:India's ship repair yards and railway maintenance depots remain underserved by precision abrasive tools, presenting white space for portable belt file sander adoption.
- Regulatory Tailwind:The EU Green Deal's emphasis on repairability and product longevity favors durable, serviceable belt file sanders over disposable alternatives in European procurement.
- Technology Convergence:Brushless motor electronics combined with smart torque sensors enable adaptive speed control, creating premium positioning for manufacturers targeting ISO 28927 ergonomic certification.
Industry Challenges
- Certification Timeline Compression:ISO 28927 vibration testing and CE marking requirements for European market entry demand 12-18 month validation cycles, slowing product launches.
- Supply Chain Reconfiguration:Dual-sourcing abrasive drive systems requires requalification of secondary suppliers, introducing quality control complexity during transition periods.
- Skill Gap in Servicing:Brushless motor and battery management system repairs demand electronics expertise scarce in traditional power-tool service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belt File Sander Market |
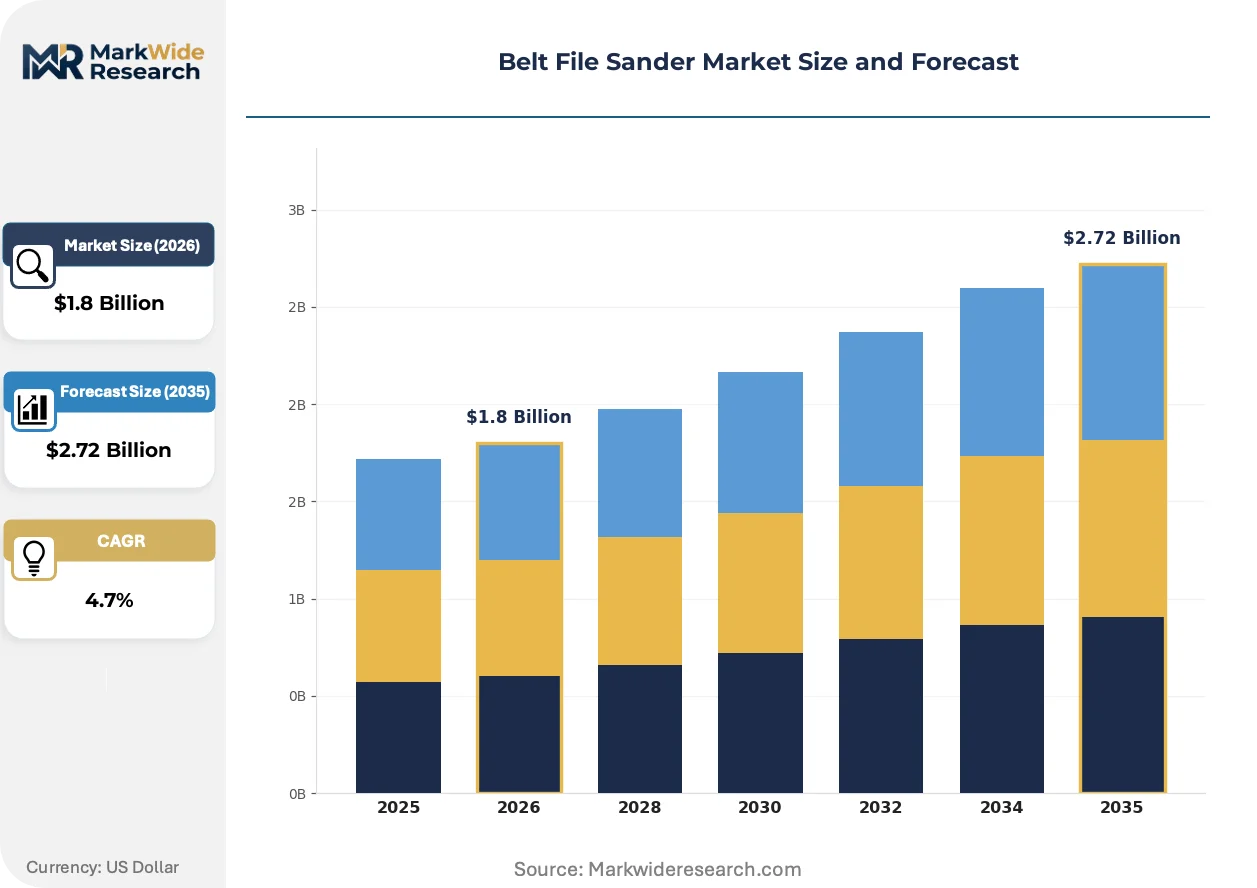
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Belt Sanders, Stationary Belt Sanders, Cordless Belt Sanders, Pneumatic Belt Sanders, Electric Belt Sanders Technology: Variable Speed, Dual-Action, Orbital, Random Orbit, Fixed Speed Application: Metalworking, Woodworking, Automotive Repair, Construction, Furniture Manufacturing End User: Manufacturers, Repair Workshops, Craftspersons, Industrial Fabricators, Construction Contractors |
| Companies Covered | Makita, BOSCH, DeWalt, Milwaukee Tool, Metabo, Festool, FLEX Tools, WEN Products, Porter-Cable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belt File Sander Market Trends and Innovations
Active sensor integration and connectivity modules are reshaping how belt file sanders monitor operator exposure and tool health, while regulatory pressure on dust emissions accelerates sealed-system designs.
Brushless DC motors with embedded Hall-effect sensors are automating torque compensation under load, maintaining constant belt speed across varying material densities. Metal fabrication shops in Germany are adopting these units for stainless steel weld grinding, where speed consistency determines surface quality. The technology is automating operator skill requirements, allowing less-experienced workers to achieve finish grades previously demanding years of hand-tool practice.
REACH restrictions on hexavalent chromium in abrasive belts are forcing European manufacturers to reformulate bonding agents and source alternative mineral compositions. The regulation compresses supplier qualification timelines, as belt producers must demonstrate compliance across extended chemical disclosure tables. Woodworking OEMs targeting CE-marked machinery integration are prioritizing belt file sanders with documented REACH-compliant abrasive supply chains.
Rental and tool-library models are displacing outright purchase in North American construction sectors, with contractors accessing belt file sanders through monthly subscription services bundled with maintenance and belt replacement. Equipment rental chains are expanding specialty abrasive tool fleets to capture this demand rotation. California and New York urban construction markets exhibit the fastest adoption, where job-site storage constraints and capital efficiency priorities favor access-over-ownership procurement.
Belt File Sander Market Segmentation
Segmentation in the belt file sander market reveals how certification requirements, power source preferences, and end-use durability demands fragment purchasing decisions across industrial and consumer tiers. Understanding these divides helps manufacturers align product development with the specific compliance burdens and performance expectations of each buyer cluster.
Product Type:
OSHA silica rules and EPA dust-collection mandates hit portable and stationary variants differently, with cordless units facing additional UN 38.3 lithium battery transport hurdles.
- Portable Belt Sanders:Compact units with integrated dust extraction ports dominate construction site workflows. Metal fabrication shops in Germany favor these for stainless steel weld grinding where mobility between workstations matters.
- Stationary Belt Sanders:Heavy-duty fixed-base machines command premium positioning in industrial fabricator settings. Furniture manufacturers in China concentrate demand here for precision dimensioning of hardwood components.
- Cordless Belt Sanders:Lithium-ion powered units eliminate trailing cables for overhead and confined-space work. UN 38.3 certification adds 8-12 weeks to distribution timelines.
- Pneumatic Belt Sanders:Compressed-air drive systems suit high-volume automotive repair bays with existing compressor infrastructure. Require CE pressure vessel compliance in European markets.
- Electric Belt Sanders:Mains-powered corded variants remain the default for craftspersons prioritizing uninterrupted runtime. ISO 28927 vibration certification drives form-factor decisions.
Portable belt sanders sit at the top of the volume ranking, with cordless belt sanders climbing the fastest.
Technology:
Cost tiers separate these segments, with premium positioning attaching to sensor-enabled adaptive systems versus commodity fixed-speed alternatives.
- Variable Speed:Electronic control modules maintain belt velocity under load variation. Metalworkers in the United States pay premiums for these units when grinding heat-sensitive alloys.
- Dual-Action:Combined belt and orbital motion reduces visible scratch patterns on automotive body panels. Repair workshops specify these for clearcoat preparation stages.
- Orbital:Fixed-pattern sanding heads suit intermediate finishing on flat wood surfaces. Furniture manufacturers standardize here for veneer preparation.
- Random Orbit:Unpredictable scratch patterns yield superior final finishes on visible woodwork. Cannot match belt file sanders for material removal rates.
- Fixed Speed:Single-speed induction motors minimize unit cost for price-sensitive craftspersons. Construction contractors in India deploy these for rough-forming tasks.
Variable speed technology captures the highest margin tier, while dual-action systems gain share fastest in automotive repair channels.
Application:
Volume concentrates in metalworking and woodworking, though regulatory exposure varies sharply by dust generation profile and substrate toxicity.
- Metalworking:Weld seam grinding and deburring operations generate respirable silica requiring OSHA-compliant extraction. Ship repair yards in India represent underpenetrated demand.
- Woodworking:Dimensioning and smoothing of timber components drives replacement cycles in furniture clusters. REACH restrictions on abrasive belt bonding agents complicate European supply.
- Automotive Repair:Panel preparation and rust removal demand dust-free operation for paint adhesion. California air quality districts enforce strictest emission thresholds.
- Construction:On-site framing and trim work favors cordless portability. Rental model adoption displaces outright purchase in New York urban markets.
- Furniture Manufacturing:Precision finishing of hardwood and engineered substrates requires ISO 28927 ergonomic compliance for operator shift protection.
Metalworking anchors volume demand, with automotive repair expanding most quickly on collision center upgrade cycles.
End User:
Procurement sophistication separates industrial fabricators with dedicated EHS staff from individual craftspersons prioritizing upfront acquisition cost.
- Manufacturers:Integrated production lines specify belt file sanders with documented REACH-compliant abrasive supply chains. German OEMs lead in smart torque sensor adoption.
- Repair Workshops:Independent automotive and metal repair operations balance capability against capital constraints. Subscription rental models penetrate fastest here.
- Craftspersons:Individual woodworkers and metal artists prioritize portability and price accessibility. Fixed-speed electric units dominate this tier.
- Industrial Fabricators:Large-scale metal and wood processing facilities demand sealed bearing housings and centralized dust extraction compatibility.
- Construction Contractors:Project-based procurement favors tool-library access over ownership. California contractors exhibit highest rental adoption rates.
Manufacturers represent the deepest pocket segment, with repair workshops showing the steepest expansion trajectory on service economy growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters anchor precision finishing equipment demand, with furniture manufacturers and metal fabricators upgrading abrasive tool capabilities across multiple continents.
United States
Metal fabrication shops and construction contractors drive replacement cycles for dust-extraction-equipped belt file sanders. OSHA crystalline silica exposure limits compel workshop upgrades in Ohio and Michigan industrial corridors. California air quality districts enforce the strictest emission thresholds, accelerating sealed-system designs in Los Angeles-area manufacturing.
Germany
Automotive suppliers and stainless steel processors concentrate demand for variable-speed belt file sanders with ISO 28927 ergonomic certification. REACH restrictions on hexavalent chromium in abrasive belts reshape supplier qualification timelines. Bavarian machine builders and Baden-Württemberg automotive clusters lead smart torque sensor adoption for weld grinding applications.
China
Furniture manufacturers in the Yangtze River Delta and Pearl River Delta expand precision finishing capabilities for hardwood component exports. GB standards for workplace dust exposure tighten compliance requirements for domestic fabricators. Shenzhen and Dongguan industrial zones concentrate cordless belt sander assembly as lithium-ion battery supply chains mature.
India
Ship repair yards in Mumbai and Visakhapatnam remain underpenetrated by precision abrasive tools, presenting white space for portable belt file sander adoption. BIS certification requirements for power tools create entry barriers for unqualified imports. Tamil Nadu railway maintenance depots and Gujarat automotive hubs show emerging demand for mobile repair equipment.
Belt File Sander Market Competitive Landscape
Global majors compete with regional champions across certification depth and channel control dimensions. The vendor base organizes around three tiers: vertically integrated motor manufacturers, electronics-focused variable-speed specialists, and price-competitive volume producers. Two strategic archetypes dominate: full-line power-tool conglomerates leveraging brand equity, and abrasive-system specialists concentrating on narrow application excellence. Competitive moves center on dual-sourcing supply chain reconfiguration and brushless motor technology licensing.
Within the premium-tier vector, Makita exemplifies vertical integration into motor manufacturing, while BOSCH occupies a position anchored in European electronics heritage. DeWalt represents North American channel dominance through retail network penetration. These three companies illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical capability bundles.
| Leading Market Players |
|---|
| Makita |
| BOSCH |
| DeWalt |
| Milwaukee Tool |
| Metabo |
| Festool |
| FLEX Tools |
| WEN Products |
| Porter-Cable |
| Others |
Pricing and Supply Chain Analysis
OSHA silica compliance mandates in the United States compel metal fabrication shops to specify dust-extraction-equipped belt file sanders, forcing suppliers to absorb certification costs and reconfigure tier boundaries between premium sensor-enabled units and economy fixed-speed alternatives.
Pricing Analysis
Input-cost pass-through from lithium-ion battery packs and REACH-compliant abrasive belts shapes tier boundaries across the market. Three-tier pricing structure across premium, standard, and economy levels separates brushless motor systems with smart torque sensors from fixed-speed induction units. Cost compression in the cordless segment intensifies because cobalt price volatility feeds directly into battery pack economics. Construction contractors in India exhibit highest price sensitivity, while German automotive suppliers accept premiums for ISO 28927-certified ergonomic systems.
Supply Chain Analysis
CE marking and UN 38.3 lithium battery certification gate European and North American market entry, extending supplier qualification timelines. Manufacturing concentrates in China, Germany, and the United States, with Shenzhen and Dongguan housing cordless assembly clusters. Abrasive belt production draws from European REACH-compliant bonding agent suppliers and Asian mineral processors. Single-source vulnerability in cobalt supply from the Democratic Republic of Congo exposes cordless product lines to geopolitical disruption. Distribution runs through industrial equipment distributors, construction rental chains, and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge from the cost differential between German precision finishing requirements and India's underpenetrated ship repair infrastructure, where identical tool specifications command divergent pricing power.
For Market Incumbents: Lock in abrasive drive system dual-sourcing arrangements before secondary supplier requalification timelines extend further. Deepen backward integration into brushless motor manufacturing to defend margin position against emerging electronics specialists. Prioritize ISO 28927 certification maintenance as European ergonomic standards tighten operator shift protection requirements. For New Entrants and Emerging Players: EU Green Deal repairability mandates in Germany and France open a window for durable, serviceable belt file sander designs against disposable alternatives. India's ship repair yards and railway maintenance depots represent the most penetrable white-space geography. Pursue subscription rental partnerships with construction equipment libraries to bypass capital-constrained buyer segments. For Investors and Strategic Acquirers: Asymmetric upside sits with brushless motor control specialists possessing embedded sensor firmware capabilities. Five-to-ten year viability favors acquisition targets with documented REACH-compliant abrasive supply chains and established UN 38.3 certification pathways. Watch lithium battery transport regulation enforcement intensity as the inflection indicator for cordless product line profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Supply Chain Reconfiguration | Reduces cobalt concentration risk from Democratic Republic of Congo exposure. |
| Brushless Motor Technology Licensing | Accelerates smart torque sensor adoption among mid-tier German fabricators. |
| REACH-Compliant Abrasive Belt Partnership | Secures European market access under tightening hexavalent chromium restrictions. |
| Rental Model Fleet Expansion | Captures California and New York construction contractor access-over-ownership preference. |
| ISO 28927 Ergonomic Certification Investment | Unlocks premium positioning in Bavarian automotive supplier procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and rental fleet managers with secondary validation from customs records, SEC filings of listed power-tool manufacturers, OSHA enforcement databases, and EU ECHA chemical restriction updates. Bottom-up demand aggregation across end-use segments triangulated against top-down macroeconomic indicators.
Historical reference periods anchored the projection horizon through documented replacement cycle lengths and regulatory implementation timelines. The analytical framework modeled power source preference, technology tier, application substrate, and regional certification cluster across the analysis window. CAGR derivation incorporated lithium-ion energy density improvement curves, silica exposure limit enforcement trajectories, and industrial cluster capital expenditure patterns.
Revisions become necessary when battery chemistry breakthroughs, cobalt supply disruptions, or ergonomic standard updates materialize. Forecasts reflect assumptions regarding regulatory enforcement consistency and raw material price stability. A model refresh is warranted upon material change in OSHA or EPA dust collection mandate implementation intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Structural Wood Screws Market
Tools
Boring-Milling Machines Market
Tools
Pneumatic Tools Market
Tools
Pliers Market
Tools
Press Machine Market
Tools
Painting Tools Market
Tools
Surface Planer Market
Tools
Gouging Torch Market
Tools
Edging Tool Market
Tools
Extensometer Market
Tools
Gear Hobbing Cutter Market
Tools
Construction Anchors Market
Tools
Drill Presses Market
Tools
Impact Wrenches Market
Tools
Cutting Equipment Market
Tools
Brushcutter Market