
 US Power Tools Market | 2026-2036
US Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
US Power Tools Market Intelligence
Multi-source component procurement is restructuring supply economics for domestic power tool manufacturers. Stanley Black & Decker leverages its captive battery cell production to insulate margins from lithium price swings. Robert Bosch Tool Corporation anchors its North American assembly footprint in South Carolina to shorten lead times for contractor distributors. Techtronic Industries Co. Ltd. competes through aggressive channel control at home improvement retail.
US power tools encompass motorized handheld and bench-mounted equipment operating via electric, pneumatic, or hydraulic energy transfer, typically generating rotational or reciprocating motion at controlled torque and speed parameters for material modification tasks. Cordless lithium-ion platforms now dominate residential and light commercial segments due to runtime improvements and interoperability across battery ecosystems. Drills and saws capture the largest volume share among product types, while grinders command premium pricing in industrial maintenance applications. The contractor end-user segment concentrates replacement demand, whereas DIY enthusiasts drive seasonal revenue spikes through retail channels.
OSHA lockout/tagout standards and EPA hazardous waste regulations govern workplace deployment and end-of-life disposal protocols for power tool batteries and pneumatic fluids. NHTSA indirectly influences cordless tool design through lithium battery transport classification rules that affect distribution logistics. Stakeholders must monitor evolving Department of Energy efficiency benchmarks and state-level right-to-repair legislation that could reshape aftermarket service revenue models.
Market Dynamics
OSHA lockout/tagout mandates and EPA battery disposal rules are compressing product design cycles while contractor fleet consolidation in Sun Belt states concentrates demand among fewer large buyers. Domestic manufacturers must now engineer for compliance-first specifications rather than retrofitting existing platforms.
Growth Catalysts
- Residential renovation intensity:Texas and Florida housing stock turnover is amplifying cordless drill replacement cycles among DIY homeowners and small contractors. Florida storm damage repair creates episodic demand spikes that favor battery-powered portability.
- OSHA workplace safety mandates:Lockout/tagout standard enforcement is driving pneumatic-to-cordless conversions in industrial maintenance settings. Compliance officers are flagging compressed air line hazards that battery platforms eliminate.
- Lithium-ion runtime improvements:Cell chemistry advances are extending duty cycles to full-shift capability, erasing the performance gap with corded tools. Interoperable battery ecosystems lock users into single-brand portfolios.
Market Restraints
- Lithium supply concentration:Cathode material processing depends on concentrated overseas refining capacity. Domestic cell assembly lacks upstream chemical feedstock security.
- EPA hazardous waste classification:End-of-life battery disposal rules impose reverse logistics costs that erode margin on entry-level price tiers. Small distributors lack compliance infrastructure.
- Pneumatic tool durability:Industrial maintenance shops cite air tool longevity in high-torque applications where cordless motor thermal limits create replacement frequency penalties.
Strategic Opportunities
- Right-to-repair legislation:State-level repair access mandates in California and New York are creating authorized service network expansion opportunities. Aftermarket parts revenue streams could offset hardware margin compression.
- Sun Belt contractor fleet electrification:Arizona and Nevada construction volume is shifting toward battery-powered equipment for indoor air quality compliance. Heat-related battery degradation challenges favor premium thermal management designs.
- Brushless motor convergence with smart torque sensing:Sensor integration is enabling predictive maintenance alerts and usage analytics. Fleet managers value downtime reduction over upfront hardware cost.
Industry Challenges
- Certification timeline compression:NHTSA lithium battery transport classification updates require recurring UN38.3 testing protocol revisions. Engineering teams must maintain parallel certification tracks for air and ground shipping.
- Legacy pneumatic infrastructure lock-in:Industrial facilities face stranded asset risk from installed compressor systems. Hybrid tool platforms that bridge air and battery power are extending transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Power Tools Market |
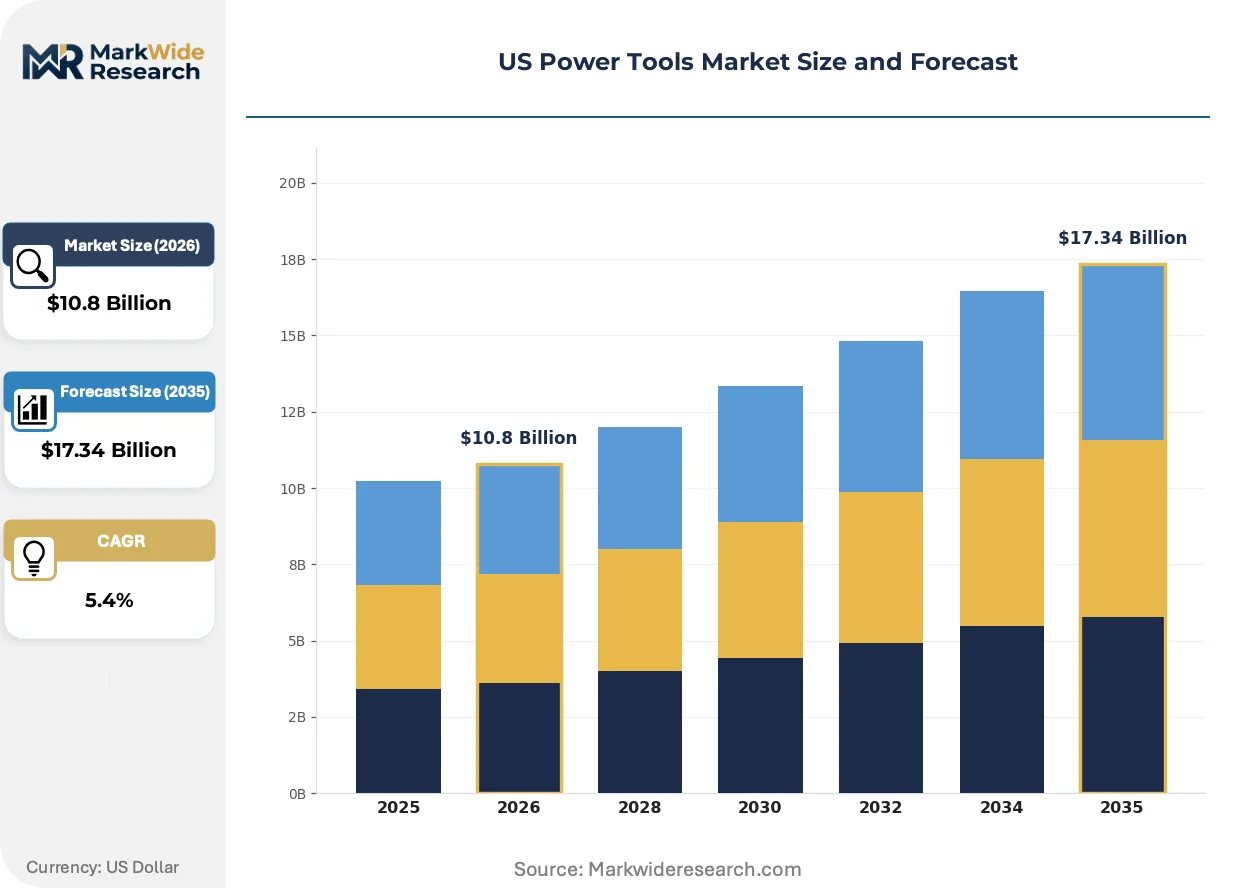
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.34 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Saws, Sanders, Grinders End User: Contractors, DIY Enthusiasts, Industrial Operators, Homeowners Technology: Corded, Cordless, Pneumatic, Hydraulics Application: Construction, Renovation, Maintenance, Demolition |
| Companies Covered | Stanley Black & Decker, Robert Bosch Tool Corporation, Techtronic Industries Co. Ltd., Makita Corporation, Hilti Corporation, Emerson Electric Co., Ingersoll Rand, Apex Tool Group, Snap-on Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Power Tools Market Strategic Shifts & Innovations
Power tool engineering is pivoting from raw performance metrics to compliance-integrated design, with connectivity layers and circular economy protocols now embedded at concept stage rather than added post-development.
Brushless motor architecture is expanding into mid-tier residential drill lines previously served by brushed commutator designs. Home improvement retailers are accelerating SKU transitions to capture efficiency-driven replacement demand. This technology is compressing the traditional three-tier product hierarchy by delivering professional-grade durability at consumer price points.
OSHA silica exposure standards for construction sites are mandating integrated dust collection on rotary hammers and grinders. Tool manufacturers must now engineer vacuum interface compatibility as a core specification rather than accessory attachment. Masonry contractors in California and Texas are prioritizing compliant integrated systems over aftermarket retrofit solutions to avoid citation exposure.
Contractor procurement teams are consolidating vendor relationships to reduce battery ecosystem fragmentation. Large fleet operators in Florida and Georgia are standardizing on single-brand platforms to simplify training and parts inventory. This concentration is shifting negotiating leverage toward volume buyers and compressing distributor margins on hardware sales.
US Power Tools Market Segmentation
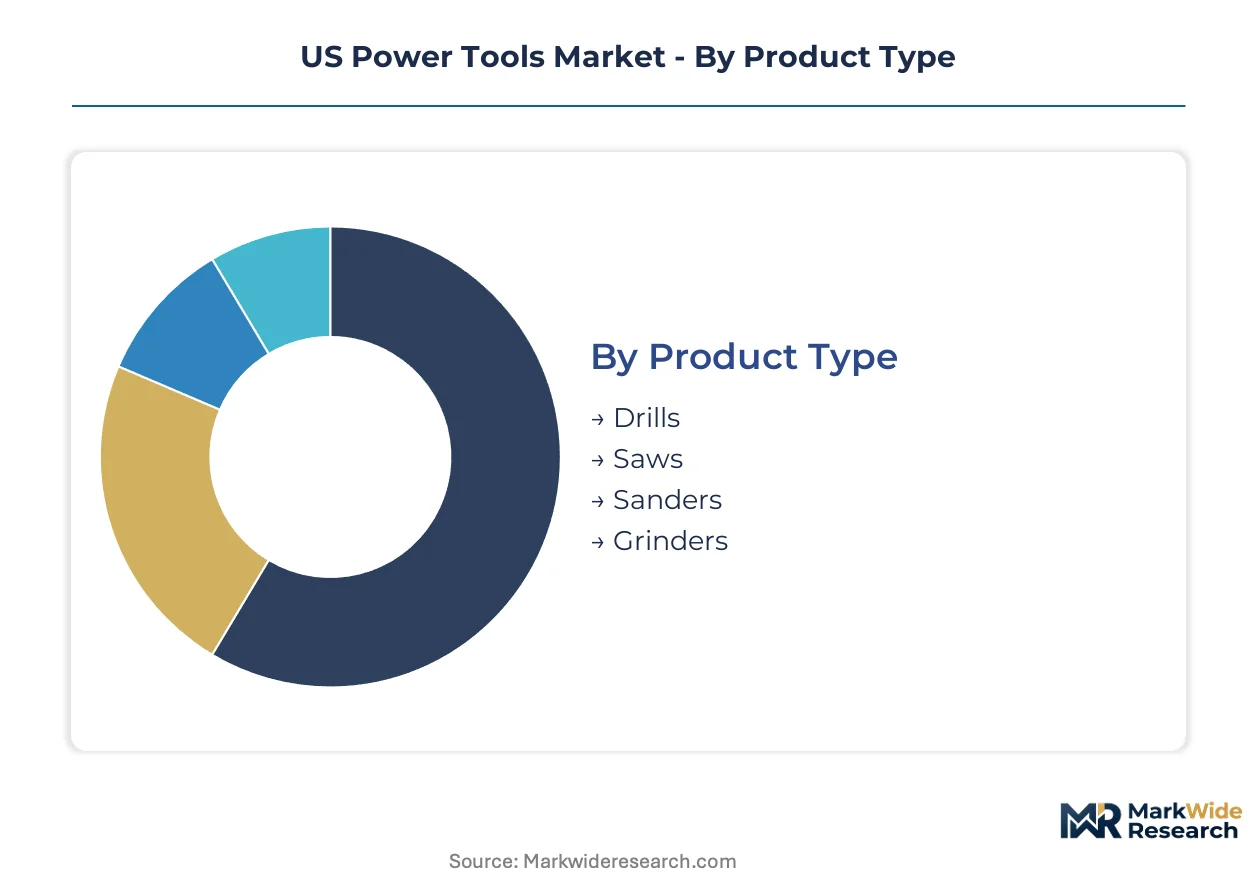
Power tool segmentation reveals how battery chemistry, torque specifications, and duty cycle ratings align with distinct procurement budgets across residential, commercial, and industrial channels. Understanding these technology-to-application mappings enables targeted platform development and inventory positioning.
Product Type:
Motor configuration and torque delivery specifications define performance ceilings and replacement frequency across professional and consumer tiers.
- Drills:Brushless motor variants now dominate contractor specifications, with lithium-ion battery platforms achieving full-shift runtime parity with corded units. Demand concentrates among renovation contractors in Texas and Florida where housing stock turnover drives replacement cycles.
- Saws:Circular and reciprocating configurations lead cordless adoption, with blade speed and cut depth metrics determining price tier placement. Florida storm damage repair crews prioritize battery-powered portability for rapid deployment to distributed job sites.
- Sanders:Orbital and belt configurations serve finishing applications with dust collection integration now mandatory under OSHA silica standards.
- Grinders:Angle and die grinder formats command premium positioning in industrial maintenance, with thermal management separating professional from consumer grades.
Mature deployment sits with Drills. Newer deployment is concentrated in Grinders as silica compliance drives integrated system upgrades.
End User:
Procurement authority and volume scale create four distinct buying behaviors with divergent price sensitivity and brand loyalty patterns.
- Contractors:Fleet operators in Sun Belt states standardize on single-brand battery ecosystems to consolidate training and parts inventory. Large buyers extract volume discounts that compress distributor margins on hardware.
- DIY Enthusiasts:Seasonal purchase patterns align with spring renovation cycles and holiday promotional windows at home improvement retail.
- Industrial Operators:Maintenance departments in manufacturing facilities face pneumatic infrastructure lock-in, with hybrid platforms extending transition timelines from compressed air systems.
- Homeowners:Infrequent use patterns favor entry-tier brushed motor designs with shorter duty cycles and lower upfront acquisition cost.
Volume leadership rests with Contractors. Steepest expansion trajectory belongs to Industrial Operators as OSHA lockout/tagout enforcement accelerates pneumatic-to-cordless conversion.
Technology:
Energy transfer mechanisms determine runtime, portability, and regulatory compliance profiles across deployment environments.
- Corded:Continuous power delivery sustains high-torque applications in stationary shop settings where mobility constraints are acceptable.
- Cordless:Lithium-ion cell chemistry advances have erased performance gaps with corded alternatives, with interoperable battery platforms locking users into single-brand portfolios. Sun Belt contractor fleets are electrifying indoor applications for air quality compliance.
- Pneumatic:Compressed air systems retain durability advantages in high-torque maintenance settings, though OSHA citation exposure for line hazards is driving displacement.
- Hydraulics:Specialized heavy-duty applications in demolition and infrastructure repair where extreme torque requirements exceed electric motor thermal limits.
Installed base dominance remains with Pneumatic. Technology transition is accelerating fastest in Cordless as cell chemistry and thermal management improve.
Application:
Worksite conditions and material modification requirements dictate tool specification, duty cycle rating, and dust collection integration.
- Construction:New build activity in Arizona and Nevada demands battery-powered equipment for indoor air quality compliance, with heat-related battery degradation favoring premium thermal management designs.
- Renovation:Residential retrofit intensity in Texas and Florida drives drill and saw replacement cycles among small contractors and DIY homeowners.
- Maintenance:Industrial facilities prioritize tool longevity and predictive maintenance alerts through smart torque sensing, with fleet managers valuing downtime reduction over upfront hardware cost.
- Demolition:Extreme duty cycles and material hardness require hydraulic or high-torque pneumatic systems with reinforced drivetrain components.
Activity concentration centers on Renovation. Regulatory pressure is intensifying fastest in Construction as state-level indoor air quality mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates among contractor fleets in Sun Belt states where residential renovation intensity and storm damage repair cycles drive cordless tool replacement. OSHA workplace safety mandates and EPA battery disposal rules are reshaping procurement patterns across state lines. Regional variation reflects climate conditions, housing stock age, and local enforcement priorities.
Texas
Housing stock turnover in Houston and Dallas-Fort Worth amplifies cordless drill demand among renovation contractors and DIY homeowners. Texas Commission on Environmental Quality administers hazardous waste rules that affect battery disposal logistics for distributors. The Austin-San Antonio corridor hosts expanding contractor fleets standardizing on single-brand battery ecosystems.
Florida
Storm damage repair creates episodic demand spikes favoring battery-powered portability for rapid deployment to distributed job sites. Florida Department of Environmental Protection enforces hazardous waste classifications that impose reverse logistics costs on entry-level price tiers. Miami and Tampa contractor concentrations are driving fleet electrification for indoor air quality compliance.
California
State-level right-to-repair legislation creates authorized service network expansion opportunities for aftermarket parts revenue. California Air Resources Board indoor air quality mandates accelerate pneumatic-to-cordless conversions in construction applications. Los Angeles and Bay Area industrial maintenance shops prioritize integrated dust collection systems to avoid silica exposure citations.
Arizona
Construction volume in Phoenix and Tucson shifts toward battery-powered equipment for indoor air quality compliance in enclosed job sites. Arizona Department of Environmental Quality administers battery recycling programs that affect distributor compliance infrastructure. Heat-related battery degradation challenges favor premium thermal management designs among desert-region contractors.
Nevada
Las Vegas commercial construction demands cordless platforms for hotel and casino renovation projects with strict indoor air standards. Nevada Division of Environmental Protection governs end-of-life battery handling protocols for contractor fleets. Reno-area industrial facilities face pneumatic infrastructure lock-in with hybrid tools extending transition timelines.
US Power Tools Market Key Industry Players
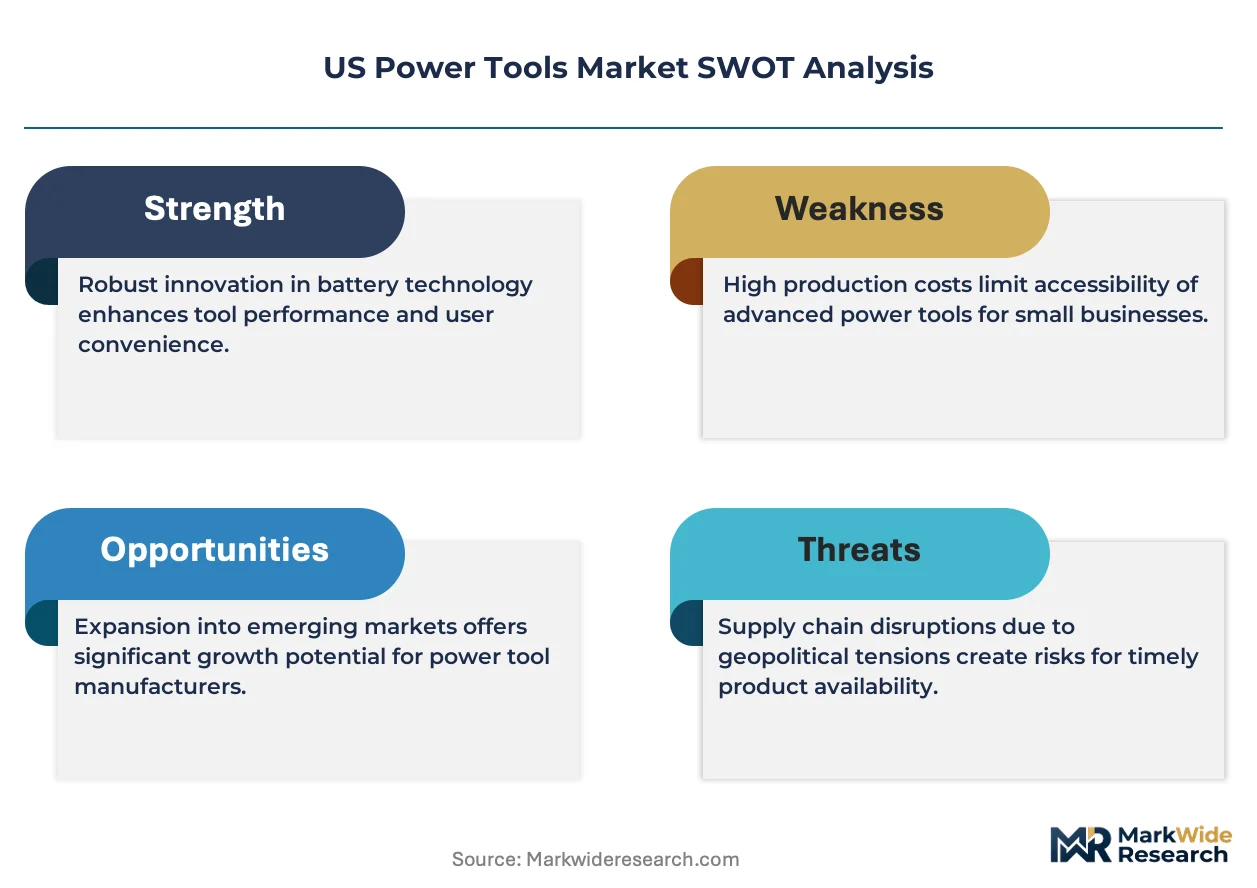
Capacity expansion dominates the current landscape as manufacturers establish regional assembly footprints to shorten lead times for contractor distributors. The vendor base concentrates among diversified industrial conglomerates with captive battery cell production and specialized professional-grade specialists. Three archetypes define competitive positioning: battery ecosystem integrators with interoperable platform strategies, pneumatic-to-cordless transition specialists, and precision maintenance tool providers for industrial fleets. M&A activity and vertical integration into upstream cell chemistry represent the dominant competitive moves reshaping supply economics.
Among diversified industrial conglomerates, Stanley Black & Decker and Robert Bosch Tool Corporation exemplify the battery ecosystem integrator archetype through captive production capabilities and North American assembly positioning. Techtronic Industries Co. Ltd. occupies a distinct channel control position at home improvement retail. These three entities anchor the competitive structure by representing divergent strategic vectors: upstream supply security, regional manufacturing proximity, and retail channel dominance.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch Tool Corporation |
| Techtronic Industries Co. Ltd. |
| Makita Corporation |
| Hilti Corporation |
| Emerson Electric Co. |
| Ingersoll Rand |
| Apex Tool Group |
| Snap-on Incorporated |
| Others |
Cost & Logistics Intelligence
Lithium carbonate and cathode precursor costs cascade through battery pack pricing tiers before reaching contractor fleet procurement budgets and DIY retail shelves. Domestic assemblers absorb cell chemistry volatility through captive production or long-term offtake agreements, while distributors face EPA reverse logistics compliance costs that compress margins on entry-level SKUs.
Pricing Analysis
Volume leadership in contractor fleet sales extracts steep hardware discounts that squeeze distributor margins, while premium thermal management designs for Sun Belt applications command price premiums. Pricing stratifies across professional-grade brushless platforms, mid-tier interoperable ecosystems, and economy brushed-motor entry points. Cost compression in the DIY tier intensifies as retailers consolidate shelf space toward house brands. Industrial maintenance buyers show lowest price sensitivity, prioritizing predictive maintenance alerts and downtime reduction over upfront acquisition cost.
Supply Chain Analysis
Regional distribution centers in South Carolina and Texas anchor hub-and-spoke patterns serving Sun Belt contractor concentrations with shortened lead times. Upstream cell production concentrates in China, South Korea, and Japan, with domestic pack assembly drawing from concentrated overseas refining capacity for cathode materials. Single-source vulnerability in lithium hydroxide processing creates tariff exposure risk for manufacturers lacking backward integration. Distribution runs through authorized dealer networks for professional tiers and big-box retail for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US power tools market functions as a vertical-integration race where captive battery cell production and regional assembly footprints determine margin defense. Players are pursuing upstream control over lithium supply chains as the decisive downstream lever.
For Market Incumbents: Anchor North American assembly capacity in battery ecosystem strongholds to shorten lead times for contractor distributors under fleet consolidation pressure. Defend against pneumatic-to-cordless displacement by accelerating brushless motor transitions in mid-tier lines. Prioritize OSHA silica compliance integration as a certification investment barrier for smaller competitors. For New Entrants and Emerging Players: Home improvement retail category managers represent the most accessible channel partner type for gaining shelf presence without legacy distributor relationships. Target the DIY enthusiast segment in Texas and Florida where housing turnover drives seasonal replacement cycles. Pursue private-label manufacturing partnerships to bypass brand ecosystem lock-in. For Investors and Strategic Acquirers: State-level right-to-repair legislation passage is the leading indicator that aftermarket parts revenue streams will offset hardware margin compression. The five-to-ten-year viability window favors targets with authorized service network infrastructure and thermal management IP for heat-stressed climates. Monitor NHTSA lithium transport classification updates as the signal for compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Battery Cell Production | Stanley Black & Decker's in-house cell manufacturing insulates margins from lithium price volatility. |
| Regional Assembly Footprint Expansion | Robert Bosch Tool Corporation's South Carolina positioning shortens lead times for contractor distributors. |
| Channel Control at Retail | Techtronic Industries Co. Ltd.'s home improvement retail dominance locks out competing brand placements. |
| Authorized Service Network Buildout | California and New York right-to-repair mandates create aftermarket parts revenue opportunities. |
| Smart Torque Sensing Integration | Predictive maintenance alerts reduce fleet downtime for industrial maintenance buyers. |
Research Approach
Independent corroboration across distributor procurement managers, contractor fleet operators, and home improvement retail category buyers underwrites the qualitative findings in this analysis. Primary fieldwork included interviews with maintenance directors at industrial facilities, OEM product development engineers, and aftermarket service heads. Secondary validation drew from SEC 10-K filings, OSHA enforcement databases, EPA hazardous waste tracking systems, and customs import records for lithium-ion cell shipments. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation produced convergent estimates.
Rate-of-change decomposition across the analysis window separates volume growth from mix-shift and pricing components. Segmentation dimensions modeled include product type, end-user archetype, energy transfer technology, and application environment, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from fitted growth curves applied to baseline shipment data. Industry-specific forecast inputs incorporated battery chemistry advancement timelines and OSHA enforcement intensity indices.
Several conditions sit outside the modeled scope, including unforeseen lithium supply disruptions, abrupt NHTSA transport rule revisions, and state-level right-to-repair legislative timing. Forecasts reflect documented assumptions about cell cost trajectories and contractor fleet consolidation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Ultra Hard Material Cutting Machines Market
Tools
Self-Clinching Fasteners Market
Tools
Drilling Tools Market
Tools
Vinyl Bending Machine Market
Tools
Electric Power Tools Market
Tools
Bandsaw Market
Tools
GCC Machine Tools Market
Tools
Leather Embossing Machine Market
Tools
Surface Levelling Equipment Market
Tools
Cordless Trim Routers Market
Tools
Tooling Market
Tools
Wood Floor Grinding Machine Market
Tools
Power Tools Market
Tools
Turning Tools Market
Tools
Handheld Engraving Machine Market
Tools
Bar Clamp Market