
 Global Standard Parts for Tool Making Market | 2026-2036
Global Standard Parts for Tool Making Market Size, Share, and Industry Trends Forecast 2026-2036
Global Standard Parts for Tool Making Market Outlook
Medical device tooling is realigning demand toward ultra-precision collets and standardized clamping systems that support micron-level repeatability in orthopedic implant machining. MISUMI Group leverages its catalog-based distribution network to dominate quick-delivery standard part procurement across Asian electronics manufacturing hubs. Barnes Group anchors its position through R&D intensity in engineered materials for high-wear tooling environments. Erwin Halder competes on geometric precision in locating components for automotive stamping dies.
Standard parts for tool making encompass interchangeable mechanical components—including collets, sockets, vises, and clamps—manufactured to dimensional tolerances typically between IT6 and IT9 grades for seamless integration into jigs, fixtures, molds, and machine tools. These components are primarily produced through CNC grinding, hard milling, and wire EDM processes to achieve the surface finishes and positional accuracy required for automated manufacturing cells. Steel material grades, particularly hardened tool steels such as 1.2379 and 1.2343, command the largest share of material demand due to their wear resistance in high-cycle stamping and injection molding applications. Composite materials represent the fastest-growing material category as lightweight fixturing gains traction in aerospace component machining and robotic end-of-arm tooling. Milling applications generate the dominant share of standard part consumption, driven by the proliferation of five-axis machining centers in job shops and production facilities.
ISO 9001 quality management systems and ISO/TS 16949 automotive quality standards shape supplier qualification requirements across European and North American procurement channels. China's SAMR enforces GB/T national standards for mold base interchangeability that directly impact export market access for component manufacturers. Japan's METI coordinates JIS standard revisions that influence precision part specifications throughout Asia-Pacific supply chains. Stakeholders must monitor evolving carbon accounting requirements under the EU Green Deal as they begin to penetrate supplier selection criteria for tooling procurement in regulated industries.
Market Dynamics
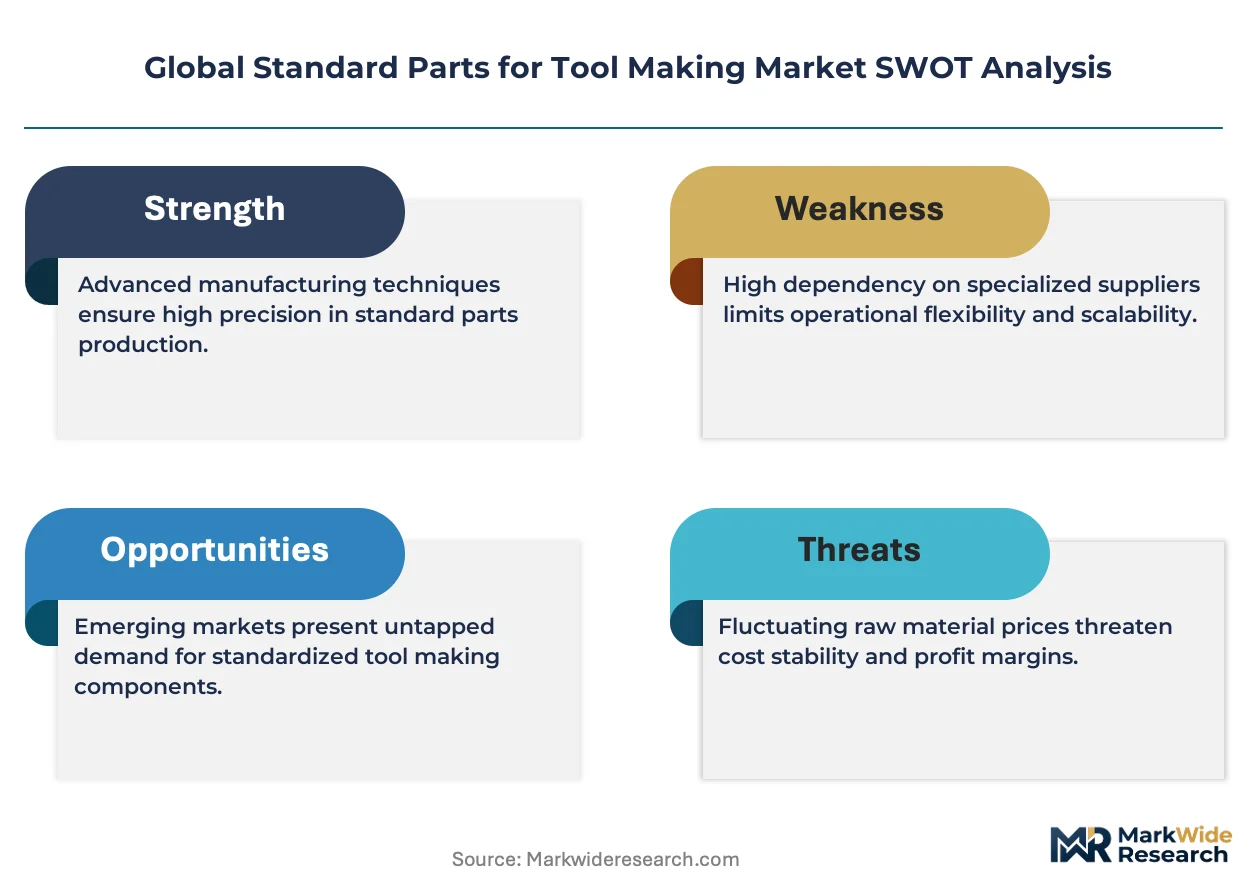
Automotive OEM retooling for electric vehicle platforms is compressing die set replacement cycles and forcing standard part suppliers to accelerate modular component development timelines.
Growth Catalysts
- EU Green Deal carbon accounting:Supplier selection criteria in regulated European tooling procurement now embed emissions disclosure requirements, favoring domestic precision manufacturers with verified supply chain data.
- Five-axis machining center proliferation:Job shops across Germany, Japan, and the United States are consuming standardized collet and vise systems at elevated rates to maximize spindle utilization in unmanned production cells.
- GB/T mold base interchangeability:China's SAMR enforcement of tightened national standards for export-bound components is upgrading specification requirements across Asian supply chains and driving replacement demand.
Market Restraints
- Hardened tool steel input volatility:Alloy surcharges on 1.2379 and 1.2343 grades fluctuate with nickel and chromium spot markets, compressing margin predictability for mid-volume precision part manufacturers.
- Baden-Württemberg supply concentration:Critical locating component and high-wear insert production clusters in southwest Germany, creating geographic vulnerability to single-region logistics disruptions or energy price shocks.
- Geometric tolerance ceiling:IT6-grade precision remains economically constrained by grinding wheel wear rates and thermal deformation in high-volume CNC sequences, limiting cost-effective entry into sub-micron medical device tooling.
Strategic Opportunities
- Composite fixturing materials:Aerospace robotic end-of-arm tooling and satellite component machining in the United States and France are absorbing carbon-fiber-reinforced clamping systems for weight-sensitive automation cells.
- Catalog-based quick delivery:Electronics manufacturing hubs in South Korea and Taiwan are migrating from custom-engineered components to standardized part numbers with 24-hour fulfillment, opening channel share for distributors with regional stocking nodes.
- Japan METI JIS revision coordination:Upcoming precision part specification harmonization across Asia-Pacific supply chains creates first-mover advantage for suppliers pre-certifying to draft standards.
Industry Challenges
- CNC grinding specialist scarcity:Hard milling and wire EDM operation certification programs in Germany and Switzerland face enrollment gaps, constraining capacity expansion for IT7-grade surface finish production.
- ISO/TS 16949 automotive recertification:Tier-2 tooling suppliers serving stamping die manufacturers encounter 18-month audit timelines and documentation burdens that delay new customer qualification.
- Legacy mold base integration:Modular die set adoption in mixed-fleet automotive plants requires adapter component engineering, adding non-recurring engineering costs and extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Standard Parts for Tool Making Market |
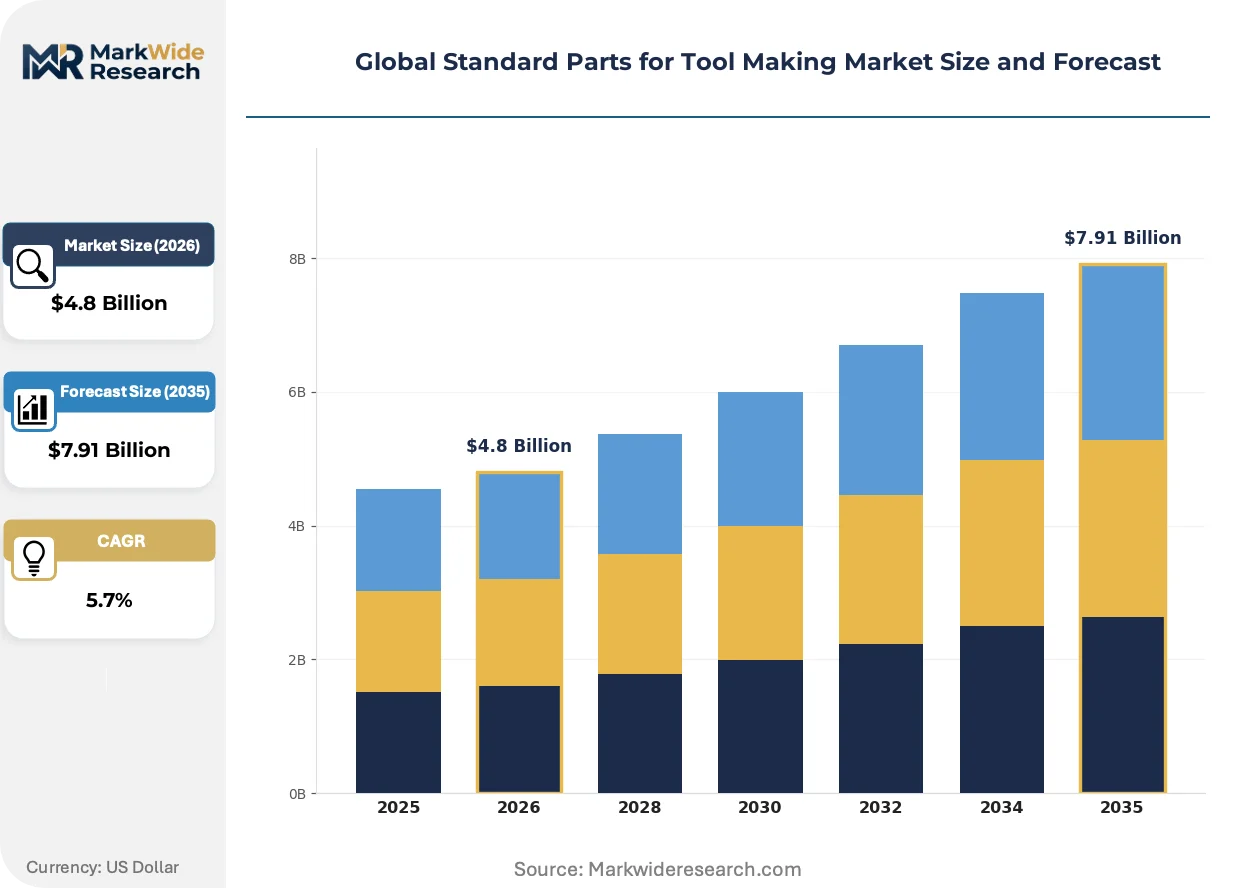
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collets, Sockets, Vises, Clamps Material: Steel, Aluminum, Plastic, Composite Application: Milling, Turning, Grinding, Drilling End User: Aerospace, Automotive, Electronics, Medical |
| Companies Covered | MISUMI Group, Barnes Group, Erwin Halder, Meusburger Georg, Lapple, Hong Yue Mold Fittings, Nitrogas, DADCO, Strack Norma GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Standard Parts for Tool Making Market Strategic Shifts
Tool making standard parts are converging around digitized specification systems, hardened material alternatives, and compressed fulfillment architectures that reward inventory positioning over custom engineering.
Additive manufacturing is absorbing fixture component production for low-volume aerospace and medical device applications. Tier-1 suppliers in France and the United States are adopting laser powder bed fusion for titanium gripper fingers and conformal cooling inserts. This technology is absorbing prototype-to-production lead times from twelve weeks to seventy-two hours in selected geometries.
REACH substance restriction expansions are forcing reformulation of surface coatings on hardened tool steel components. European mold base manufacturers are substituting hexavalent chromium plating with physical vapor deposition alternatives to maintain corrosion resistance. Medical device tooling suppliers in Germany and Switzerland face the most acute compliance deadlines and are accelerating supplier audits.
Buyer concentration among automotive stamping die OEMs is consolidating vendor panels and unbundling after-sales service from component supply. Tier-1 die manufacturers in Japan and the United States are awarding multi-year standard part contracts with penalty clauses for stockout incidents. This behavior is most visible in Baden-Württemberg and Nagoya prefecture, where just-in-time die assembly lines tolerate zero buffer inventory.
Global Standard Parts for Tool Making Market Segmentation
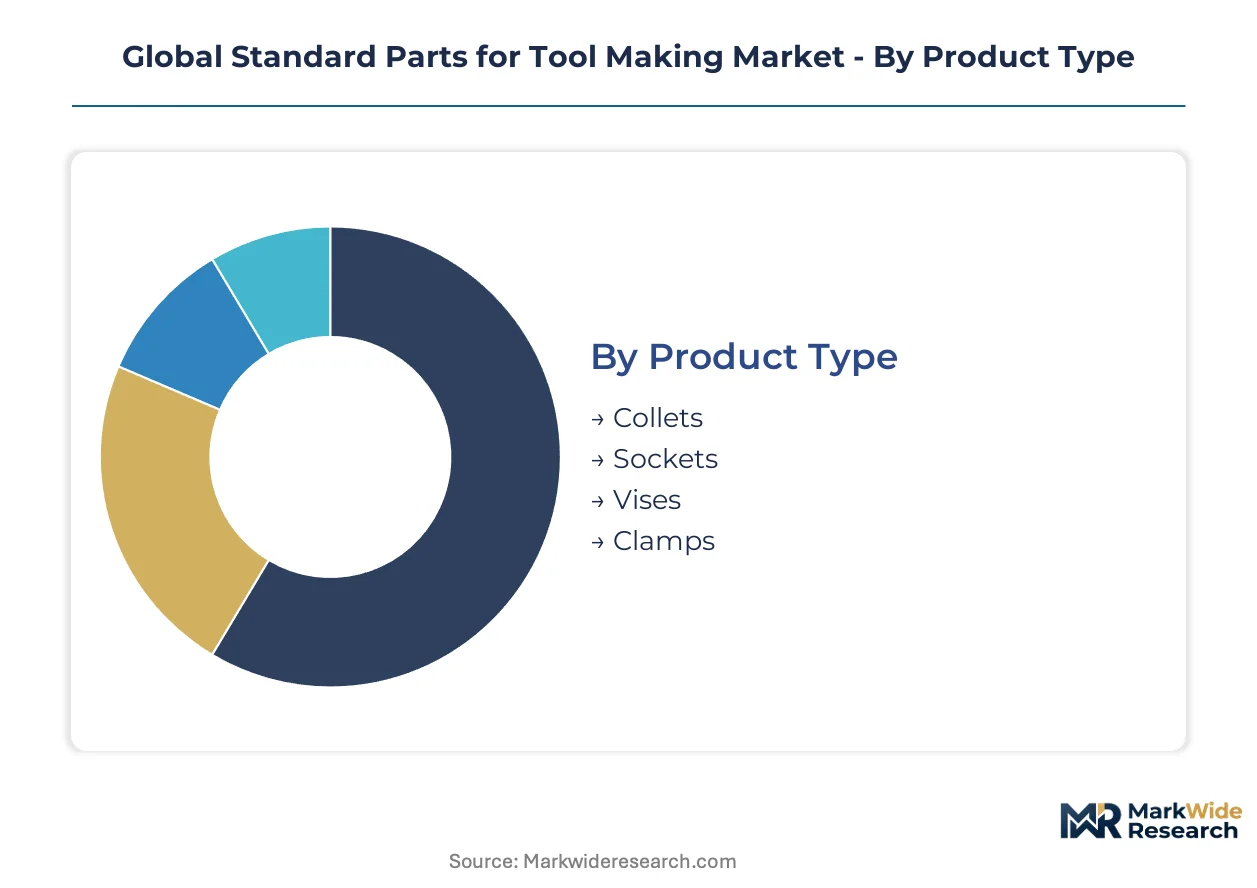
Standard parts for tool making fragment across four orthogonal dimensions that determine procurement workflows, certification burdens, and margin structures. Each segmentation axis carries distinct regulatory weight and shapes supplier qualification requirements for end users.
Product Type:
ISO/TS 16949 automotive certification dominates collet and socket procurement channels, while IT-grade geometric tolerances govern vise and clamp specifications for medical device tooling.
- Collets:Precision cylindrical clamping devices manufactured to IT6-IT7 grades for five-axis machining center spindles. Demand concentrates in Germany's Baden-Württemberg automotive tooling cluster where electric vehicle platform retooling accelerates replacement cycles.
- Sockets:Interchangeable tool holders for automated tool changers in unmanned production cells. Electronics manufacturing hubs in Taiwan and South Korea absorb standardized socket systems for 24-hour fulfillment architectures.
- Vises:Workholding fixtures for milling and grinding operations.
- Clamps:Locating and securing components for jig and fixture assembly.
Leading the category by volume: Collets. Growing fastest: Sockets.
Material:
REACH substance restrictions and carbon accounting requirements under the EU Green Deal are forcing material substitution decisions across European procurement channels.
- Steel:Hardened tool steels including 1.2379 and 1.2343 grades deliver wear resistance for high-cycle stamping dies. Alloy surcharge volatility on nickel and chromium spot markets compresses margin predictability for mid-volume manufacturers serving automotive OEMs.
- Composite:Carbon-fiber-reinforced polymers for weight-sensitive robotic end-of-arm tooling. Aerospace component machining in France and the United States drives steepest expansion trajectory as satellite manufacturers prioritize mass reduction in automation cells.
- Aluminum:Lightweight fixturing for prototype and low-volume production environments.
- Plastic:Cost-sensitive applications in electronics assembly and temporary tooling.
Steel commands the largest share. Composite materials gain share fastest.
Application:
Five-axis machining center proliferation reshapes consumption patterns across job shops and production facilities, elevating demand for standardized workholding systems.
- Milling:Dominant consumption channel driven by five-axis center deployment in Germany, Japan, and United States job shops. Unmanned production cells require standardized collet and vise systems to maximize spindle utilization.
- Grinding:Precision surface and cylindrical grinding for IT6-grade finishes. CNC grinding specialist scarcity in Germany and Switzerland constrains capacity expansion for medical device tooling suppliers.
- Turning:Lathe-based material removal for rotational components.
- Drilling:Hole-making operations in assembly and fabrication workflows.
Milling leads by installed base. Grinding expands most quickly on medical precision requirements.
End User:
Automotive stamping die OEMs consolidate vendor panels with multi-year contracts and stockout penalty clauses, while medical device manufacturers impose micron-level tolerance requirements.
- Automotive:Stamping die manufacturers in Baden-Württemberg and Nagoya prefecture operate just-in-time assembly lines with zero buffer inventory. Modular die set adoption for electric vehicle platforms compresses replacement cycles and accelerates component development timelines.
- Medical:Orthopedic implant machining demands ultra-precision collets and standardized clamping systems supporting micron-level repeatability. Germany and Switzerland suppliers face acute REACH coating reformulation deadlines.
- Aerospace:Robotic end-of-arm tooling and satellite component machining.
- Electronics:Quick-delivery procurement migrating from custom-engineered to catalog-standard parts.
Automotive dominates procurement volume. Medical tooling climbs fastest on precision premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan where precision grinding infrastructure supports IT6-grade component output, while consumption spreads across automotive stamping corridors in China and the United States where die set replacement cycles accelerate.
Germany
Baden-Württemberg tooling clusters absorb hardened tool steel collets and locating components for electric vehicle platform retooling. EU Green Deal carbon accounting requirements under ECHA enforcement now embed emissions disclosure into supplier qualification workflows. Stuttgart-based precision manufacturers face alloy surcharge volatility on 1.2379 grades while serving just-in-time die assembly lines with zero buffer inventory tolerance.
China
SAMR enforcement of tightened GB/T mold base interchangeability standards drives replacement demand across export-bound component supply chains. The country's national standards regulator mandates dimensional tolerances that directly impact market access for precision part manufacturers. Yangtze River Delta electronics manufacturing hubs migrate toward catalog-standard procurement with 24-hour fulfillment architectures.
United States
Five-axis machining center proliferation in job shops elevates consumption of standardized collet and vise systems for unmanned production cells. EPA and OSHA workplace safety frameworks shape coating reformulation timelines for hardened tool steel components. Michigan and Ohio automotive stamping corridors compress die set replacement cycles as OEMs retool for electric vehicle platforms.
Japan
METI coordinates JIS standard revisions that influence precision part specifications throughout Asia-Pacific supply chains. Nagoya prefecture die manufacturers operate just-in-time assembly lines with multi-year standard part contracts containing stockout penalty clauses. Chubu region tooling clusters specialize in IT7-grade surface finish production for automotive and electronics applications.
South Korea
Electronics manufacturing hubs in Gyeonggi-do and Incheon absorb standardized socket systems for automated tool changers in unmanned cells. The country's national industrial standards body aligns with METI-coordinated JIS revisions for regional specification harmonization. Seoul Capital Area distributors compete on regional stocking node density for quick-delivery procurement migration.
Global Standard Parts for Tool Making Market Competitive Environment
Top-tier vendors anchor precision-grade supply to automotive and medical device OEMs, while mid-tier fabricators compete on catalog breadth and regional fulfillment speed. The vendor base stratifies across three tiers: multinational specialists with captive grinding capacity, regional distributors with stocking node networks, and local job shops serving prototype-to-production workflows. Two strategic archetypes dominate competitive positioning: precision manufacturers competing on IT-grade tolerance achievement, and logistics-centric distributors competing on fulfillment velocity. Capacity expansion and backward integration into hardened material processing represent the dominant competitive moves across both archetypes.
Within the multinational specialist tier, MISUMI Group and Barnes Group exemplify divergent strategic positioning. MISUMI Group occupies a catalog-based distribution position with emphasis on Asian electronics manufacturing hub penetration. Barnes Group anchors engineered materials development for high-wear tooling environments. Erwin Halder sits within the geometric precision archetype, competing on locating component accuracy for automotive stamping die applications. These three entities collectively represent the competitive tension between fulfillment velocity and precision-grade manufacturing that shapes vendor selection criteria across end-use segments.
| Leading Market Players |
|---|
| MISUMI Group |
| Barnes Group |
| Erwin Halder |
| Meusburger Georg |
| Lapple |
| Hong Yue Mold Fittings |
| Nitrogas |
| DADCO |
| Strack Norma GmbH |
| Others |
Value Chain & Pricing Dynamics
Captive grinding capacity in Baden-Württemberg and Nagoya anchors supply positions for IT6-grade precision components while simultaneously supporting premium pricing power for hardened tool steel collets and locating systems. This integration choice insulates tier-1 suppliers from alloy surcharge volatility on 1.2379 grades but concentrates geographic exposure to single-region energy and logistics disruptions.
Pricing Analysis
Lead-time compression commands measurable premiums across European and Asian procurement channels, with 24-hour fulfillment architectures in Taiwan and South Korea extracting price escalations over standard four-week delivery cycles. Three-tier pricing structure across premium, standard, and economy levels separates ISO/TS 16949-certified automotive-grade components from IT7-grade general industrial and uncertified spot inventory. Cost compression in mid-volume hardened tool steel segments is intensifying because nickel and chromium spot market volatility transmits directly through alloy surcharge mechanisms. Electronics manufacturing buyers in Gyeonggi-do exhibit highest price sensitivity due to catalog-standard migration, while medical device OEMs in Germany and Switzerland absorb premiums for REACH-compliant coating reformulations without volume negotiation.
Supply Chain Analysis
CNC grinding specialist scarcity in Germany and Switzerland constrains capacity expansion for IT7-grade surface finish production, forcing lead-time extensions across automotive and medical tooling queues. Manufacturing concentrates in Germany, Japan, and China, with Baden-Württemberg and Nagoya prefecture housing captive precision grinding infrastructure while Yangtze River Delta nodes serve export-bound GB/T-compliant component demand. Raw material dependencies draw from hardened tool steel mills in Austria and Sweden, nickel-chromium alloy suppliers, and physical vapor deposition coating specialists. Single-source vulnerability clusters around Baden-Württemberg for critical locating component production. Distribution runs through catalog-based distributors with regional stocking nodes in Asian electronics hubs and direct mill relationships for automotive tier-1 die manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side capacity constraints in precision grinding infrastructure prop pricing power for incumbent manufacturers serving automotive and medical device tooling segments. CNC grinding specialist enrollment gaps in Germany and Switzerland represent the binding bottleneck sustaining margin structures.
For Market Incumbents: Anchor defensive positioning through backward integration into hardened material processing and captive grinding capacity additions in Baden-Württemberg. Accelerate JIS pre-certification to draft standards coordinated by Japan's METI before Asia-Pacific specification harmonization closes first-mover windows. Threaten substitution from additive manufacturing in low-volume aerospace prototyping demands accelerated R&D in conformal cooling insert geometries to maintain relevance. For New Entrants and Emerging Players: E-commerce catalog platforms with 24-hour fulfillment architectures offer the most penetrable entry vector into South Korean and Taiwanese electronics manufacturing hubs. Target composite fixturing materials for aerospace robotic end-of-arm tooling in France and the United States where weight-sensitive automation cells absorb carbon-fiber-reinforced clamping systems without incumbent supply relationships. Pursue white-label manufacturing partnerships with Yangtze River Delta mold base producers seeking GB/T export compliance upgrades. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational precision component groups seeking geographic footprint expansion in Asia-Pacific electronics corridors. Long-term viability hinges on sustained capital intensity in grinding infrastructure against additive manufacturing substitution curves. Acquisition target archetype: mid-tier distributors with established regional stocking node networks in South Korea or Taiwan. Signal to watch: JIS standard revision finalization timelines from Japan's METI as inflection indicator for pre-certified supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardened Material Processing | Captive 1.2379 and 1.2343 steel processing insulates margins from nickel-chromium alloy surcharge volatility in automotive supply chains. |
| Regional Stocking Node Expansion | Density in Gyeonggi-do and Incheon captures electronics manufacturing migration toward 24-hour catalog fulfillment architectures. |
| JIS Pre-Certification Investment | First-mover positioning before METI-coordinated Asia-Pacific specification harmonization closes competitive windows. |
| Composite Fixturing Material Development | Carbon-fiber-reinforced clamping systems address weight-sensitive robotic end-of-arm tooling demand in French and US aerospace. |
| REACH-Compliant Coating Reformulation | Physical vapor deposition substitution for hexavalent chromium plating maintains European medical device tooling market access under ECHA enforcement. |
Study Parameters
Trade association filings from VDW and JMTBA, customs databases tracking hardened tool steel component flows, and SEC 10-K disclosures from listed precision manufacturers formed the secondary backbone of this analysis. Primary interviews with die manufacturing procurement directors, CNC grinding operation managers, medical device tooling engineers, and catalog distribution channel heads combined with secondary validation through bottom-up and top-down triangulation approaches. The research integrated quantitative shipment data from regional tooling clusters with qualitative assessment of GB/T and JIS standard evolution timelines.
Historical trendline analysis of replacement cycle compression in automotive stamping die procurement established baseline growth assumptions across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, material grade, application process, and end-use industry vertical alongside geographic production cluster and certification tier. CAGRs derived from installed base expansion rates in five-axis machining centers and electric vehicle platform retooling schedules, cross-referenced against grinding capacity utilization rates in Baden-Württemberg and Nagoya prefecture.
The model holds under sustained alloy surcharge volatility within historical bands and stable JIS/GB/T standard implementation timelines; deviation in grinding specialist training program enrollment or REACH substance restriction acceleration would shift capacity and compliance cost assumptions. Forecasts reflect documented assumptions regarding electric vehicle platform transition speeds and unmanned production cell adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Chainsaw Market
Tools
Brushcutter Market
Tools
Cordless Multi Rotary Tools Market
Tools
Orbital Recip Saw Market
Tools
Europe Woodworking Power Tools Market
Tools
Digital Cutting Machine Market
Tools
Self-Clinching Fasteners Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Hand Saw Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Tension Tester Market
Tools
Woodworking Tools Market
Tools
Hydraulic Tools and Equipment Market
Tools
Multi Spindle Machines Market
Tools
Global Cordless Power Tools Market