
 Global Peptone Market | 2026-2036
Global Peptone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peptone Market Analysis
The EU Green Deal is decoupling European peptone procurement from carbon-intensive supply chains, compelling buyers to audit Scope 3 emissions across animal and plant-derived inputs. Kerry Group leverages its backward integration into yeast fermentation to secure certified low-carbon peptone streams. Merck KGaA anchors its position through pharmaceutical-grade manufacturing scale in Darmstadt. Thermo Fisher Scientific competes by controlling distribution channels into North American contract research organizations.
Peptones are water-soluble protein hydrolysates produced by enzymatic or acid digestion of animal, plant, or microbial biomass, typically containing 8-18% nitrogen by weight and serving as nitrogen sources in industrial microbiology and cell culture. Yeast extract dominates value capture due to its kosher and halogen-free certifications aligning with pharmaceutical purity mandates. Plant-based peptones represent the fastest-growing structural segment as biotechnology firms in Singapore and South Korea qualify non-animal media for regulatory submission. Powder form occupies the largest volume share given shelf stability and freight economics, though liquid concentrates gain traction in continuous bioprocessing installations.
The FDA enforces current Good Manufacturing Practice standards for peptone lots entering cell therapy supply chains, while the EMA's revised Annex 1 on sterile manufacturing elevates endotoxin testing burdens for European suppliers. China's NMPA and Japan's PMDA maintain divergent allergen labeling rules that fragment packaging requirements for multinational producers. Stakeholders must monitor how the EU AI Act and parallel FDA guidance on artificial intelligence in manufacturing will reshape batch release documentation and supplier qualification protocols.
Market Dynamics
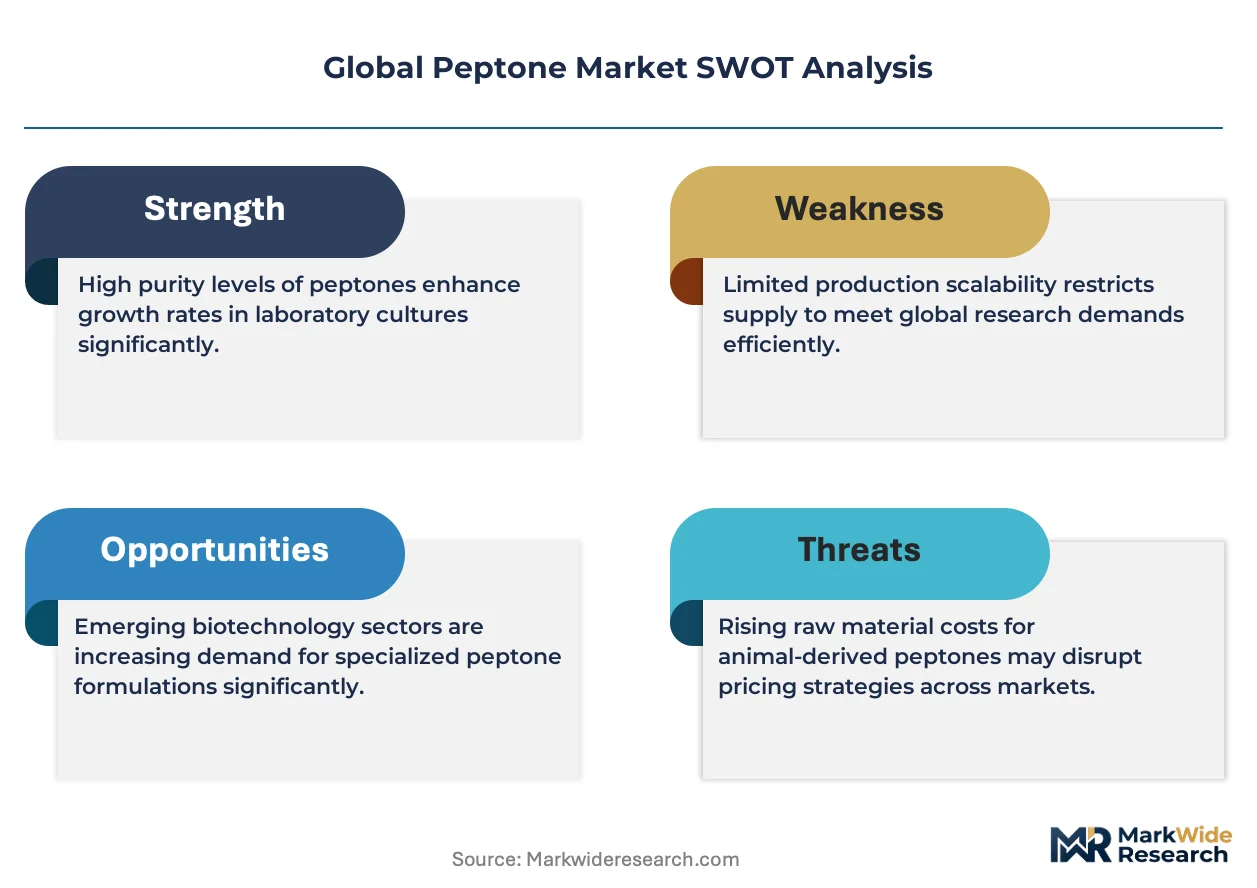
Pharmaceutical-grade peptone supply is tightening as cell therapy manufacturers in Germany, Singapore, and the United States compete for certified low-endotoxin lots, forcing buyers to qualify secondary suppliers and accept longer lead times.
Growth Catalysts
- EMA Annex 1 revisions:Sterile manufacturing mandates in Europe are elevating demand for pharmaceutical-grade peptones with documented endotoxin profiles, compelling media suppliers to upgrade quality systems.
- Cell therapy manufacturing:Autologous and allogeneic cell therapy producers in Boston-Cambridge and Singapore are consuming peptone volumes at scales previously reserved for industrial enzymes.
- Enzymatic hydrolysis advancement:Controlled protease digestion is yielding peptone lots with more consistent molecular weight distributions than acid hydrolysis methods.
Market Restraints
- Animal-derived input volatility:Bovine and porcine tissue supply from Argentina and Brazil faces recurring foot-and-mouth disease quarantines that disrupt hydrolysate production.
- Yeast extract supply concentration:Three fermentation facilities in China and one in Iowa supply the majority of pharmaceutical-grade yeast extract, creating single-source vulnerability.
- Endotoxin testing burden:LAL assay capacity constraints at contract testing laboratories are extending batch release timelines by four to six weeks.
Strategic Opportunities
- Plant-based peptone qualification:Pea and soy protein hydrolysates from Canadian and Ukrainian processors are entering regulatory submission packages for animal-origin-free media.
- Continuous bioprocessing adoption:Perfusion cell culture systems in South Korean and Swiss facilities are shifting demand toward liquid peptone concentrates with defined shelf lives.
- EU Green Deal bio-based procurement:Public tenders for research media in France and Denmark now award points for verified Scope 3 emission reductions in peptone supply chains.
Industry Challenges
- Peptide analytics expertise shortage:Mass spectrometry specialists capable of characterizing peptone molecular fingerprints command salaries 40% above general analytical chemists.
- Multi-regulatory dossier complexity:Suppliers must maintain separate allergen labeling, origin documentation, and stability data packages for FDA, EMA, PMDA, and NMPA submissions.
- Legacy batch record integration:Paper-based manufacturing records at established peptone plants require manual transcription into electronic quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peptone Market |
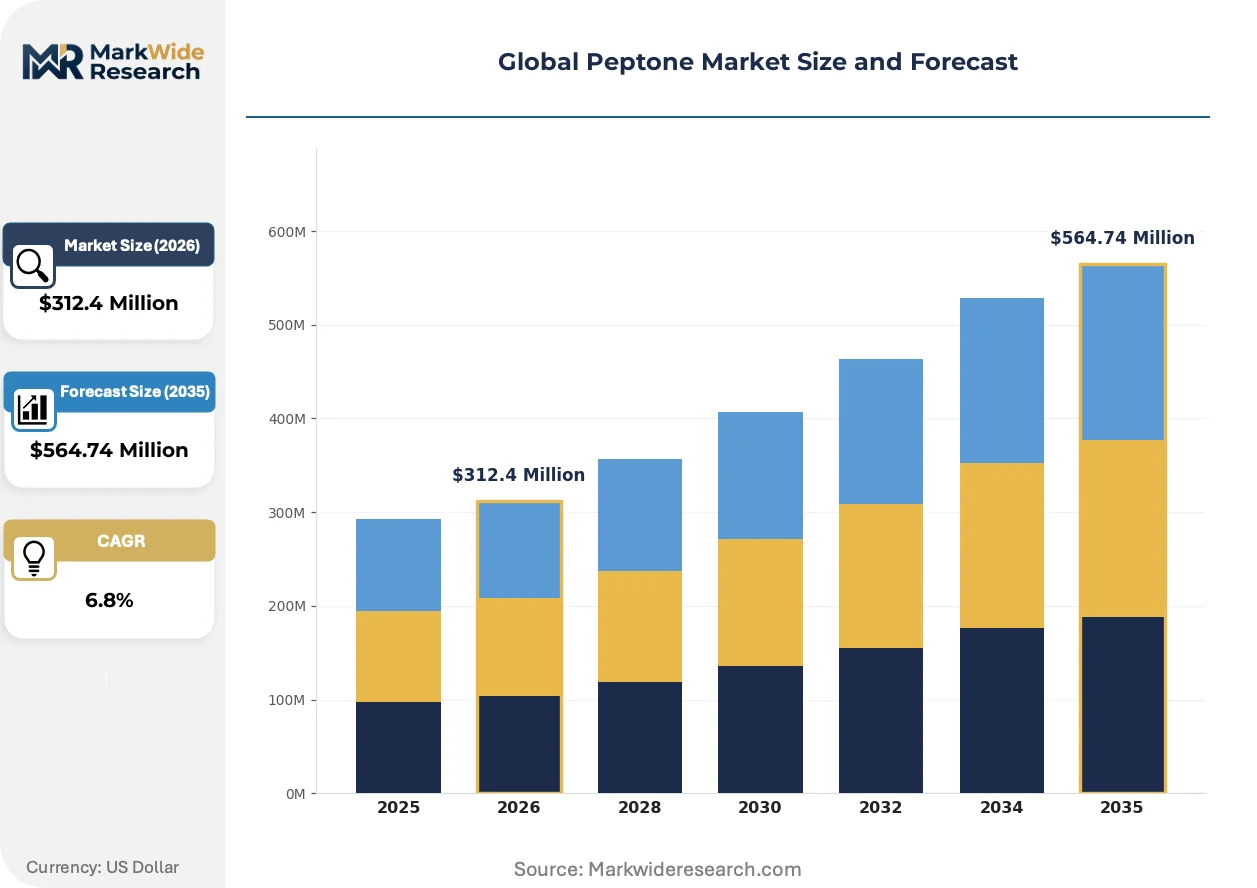
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Extract, Yeast Extract, Plant-Based Peptones, Hydrolyzed Proteins Application: Microbial Culture, Nutritional Supplements, Laboratory Research, Tissue Culture End User: Healthcare Laboratories, Academic Institutions, Pharmaceutical Companies, Biotechnology Firms Form: Powder, Liquid, Granules, Concentrate |
| Companies Covered | Kerry Group, BD Biosciences Systems & Reagents Inc., Merck KGaA, HiMedia Laboratories Pvt. Ltd., Titan Biotech Limited, Thermo Fisher Scientific Inc., Neogen Corporation, Lonza Group Ltd., Biospringer S.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peptone Market Emerging Trajectories
Peptone manufacturing is bifurcating between commodity hydrolysates for industrial fermentation and precision-characterized products for cell therapy, with technology investments concentrating in the higher-margin segment.
Single-use bioreactor integration is consolidating demand for liquid peptone concentrates with defined particulate specifications. Contract manufacturers in Massachusetts and North Carolina are specifying concentrates over powders to eliminate hydration steps and reduce contamination risk. This format shift is compressing the addressable market for traditional powder suppliers without aseptic liquid filling capability.
REACH substance registration requirements in Europe are forcing peptone importers to document full supply chain composition, including enzyme sources used in hydrolysis. German and Dutch distributors are now rejecting non-EU peptone lots lacking extended safety data sheets. Plant-derived peptone categories are benefiting as they face fewer REACH registration burdens than animal-derived alternatives.
Buyer qualification cycles are compressing as cell therapy developers in Singapore and South Korea accelerate vendor onboarding to secure supply for clinical trials. Traditional eighteen-month supplier qualification timelines are collapsing to six months for peptone categories with existing drug master files. This behavioral shift favors incumbent suppliers with established regulatory dossiers over new entrants with superior technical specifications.
Global Peptone Market Segmentation
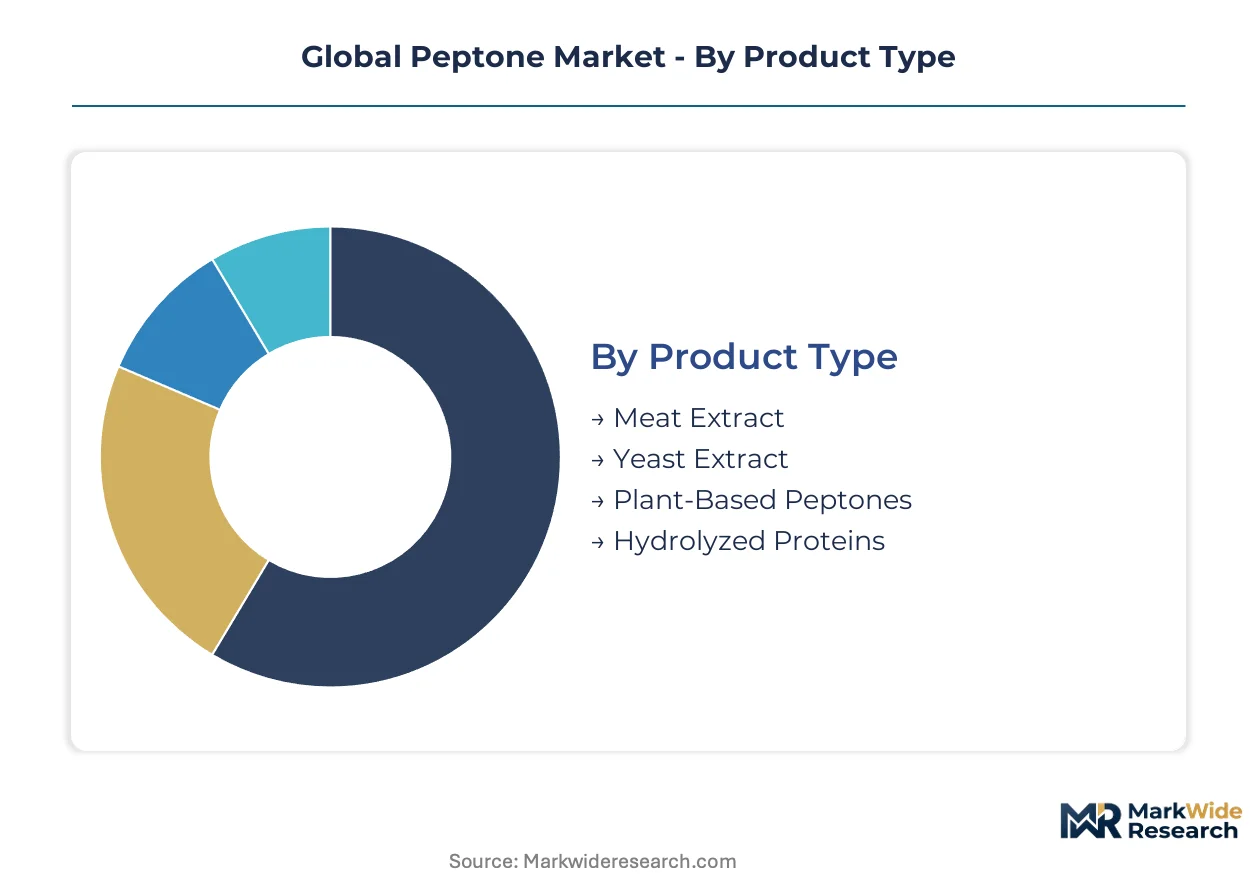
Peptone procurement splits sharply between commodity-grade hydrolysates for industrial fermentation and precision-characterized lots for cell therapy manufacturing. Understanding segment boundaries reveals where quality premiums command pricing power versus where freight economics and shelf stability dominate purchasing decisions.
Product Type:
Volume concentrates in established fermentation feedstocks, while premium capture shifts toward certified animal-origin-free alternatives.
- Yeast Extract:Produced through controlled autolysis of Saccharomyces cerevisiae biomass, yielding 8-12% nitrogen content with consistent amino acid profiles. Pharmaceutical manufacturers in Germany and Singapore specify kosher-certified lots for monoclonal antibody production, with EMA Annex 1 revisions tightening endotoxin documentation requirements.
- Plant-Based Peptones:Enzymatic hydrolysates from pea, soy, or wheat gluten proteins deliver nitrogen sources without TSE/BSE risk. Singaporean and South Korean biotechnology firms are qualifying these hydrolysates for regulatory submission packages, accelerating vendor onboarding timelines from eighteen months to six months where drug master files exist.
- Meat Extract:Bovine and porcine tissue hydrolysates retain cost advantages for industrial enzyme production despite recurring foot-and-mouth disease quarantines in Argentina and Brazil disrupting supply.
- Hydrolyzed Proteins:Acid or enzyme-digested collagen and casein fractions serve niche nutritional supplement applications with lower purity thresholds than pharmaceutical grades.
Today's leader: Yeast Extract. Tomorrow's challenger: Plant-Based Peptones.
Application:
End-use bifurcation tracks regulatory intensity, with cell therapy applications commanding tenfold quality premiums over industrial fermentation.
- Tissue Culture:Serum-free media formulations for stem cell and CAR-T manufacturing require peptone lots with documented molecular weight distributions below 10 kDa. Boston-Cambridge biotech clusters consume volumes previously reserved for commodity industrial applications, with FDA current Good Manufacturing Practice enforcement tightening batch release protocols.
- Microbial Culture:Bulk fermentation for industrial enzymes and probiotics tolerates higher endotoxin loads and variable peptide composition. Chinese and Indian antibiotic manufacturers dominate procurement here, prioritizing powder formats for ocean freight economics.
- Laboratory Research:Academic and government laboratories in France and Denmark now score EU Green Deal bio-based procurement points for verified Scope 3 emission reductions in peptone supply chains.
- Nutritional Supplements:Sports nutrition and clinical enteral feeding applications face lighter regulatory burdens than pharmaceutical cell culture, with allergen labeling requirements varying across FDA, EMA, PMDA, and NMPA jurisdictions.
Margin concentration: Tissue Culture. Volume anchor: Microbial Culture.
End User:
Customer sophistication determines specification stringency, with pharmaceutical-grade buyers auditing supplier quality systems while academic purchasers prioritize catalog availability.
- Pharmaceutical Companies:Merck KGaA, Roche, and Sanofi qualify peptone suppliers through eighteen-month vendor onboarding cycles, requiring drug master files and documented enzyme sources for REACH substance registration compliance.
- Biotechnology Firms:Cell therapy developers in Massachusetts and North Carolina specify liquid concentrates for single-use bioreactor integration, eliminating hydration contamination risks.
- Healthcare Laboratories:Hospital-based diagnostic labs consume standardized powder formats for microbial identification panels, with procurement centralized through group purchasing organizations.
- Academic Institutions:University research programs face budget constraints that favor generic hydrolysates over characterized peptone lots, though EU Green Deal public tenders are shifting procurement criteria toward carbon accounting.
Quality premium extraction: Pharmaceutical Companies. Growth velocity: Biotechnology Firms.
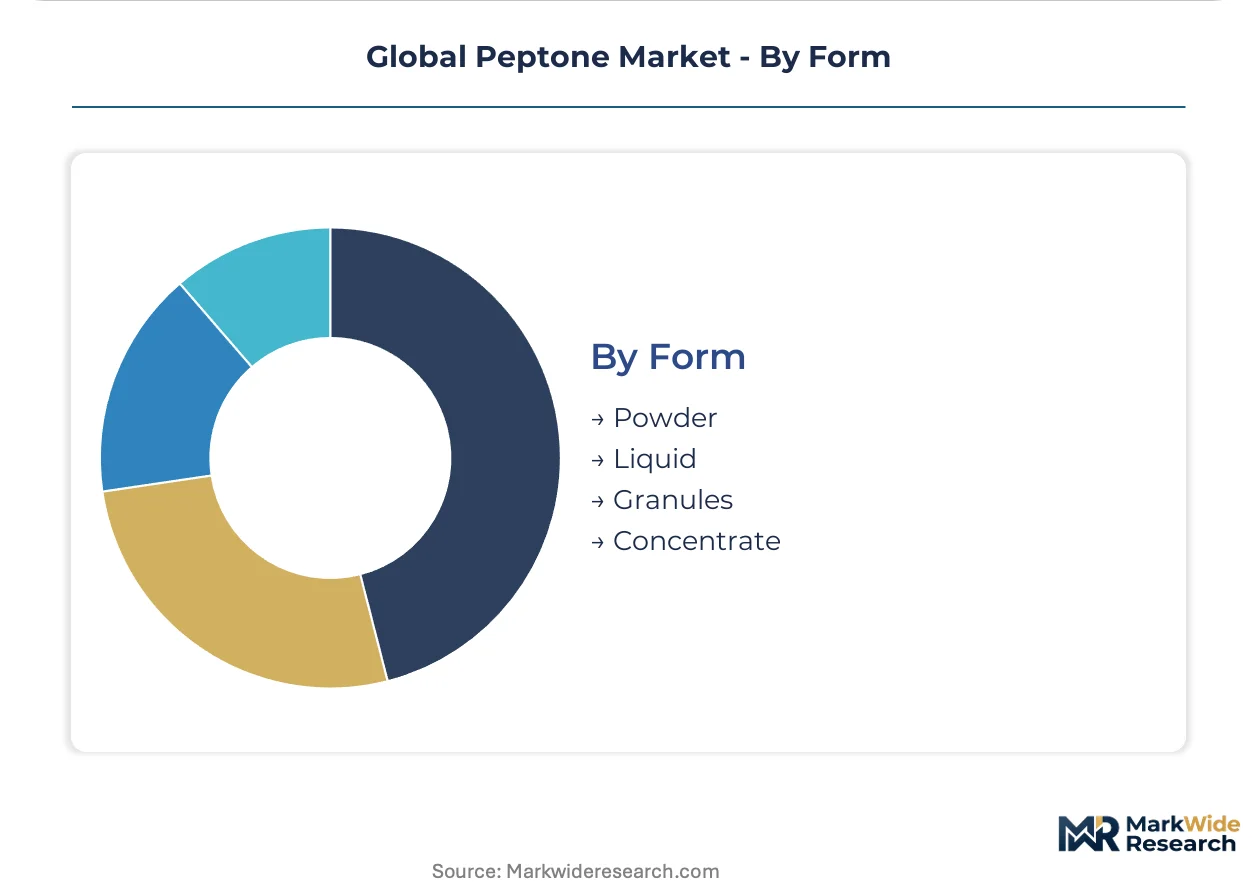
Form:
Physical format selection trades shelf stability against process integration efficiency, with continuous bioprocessing installations driving liquid adoption.
- Powder:Spray-dried hydrolysates dominate volume share through eighteen-month shelf stability and containerized freight economics. Legacy batch record systems at established plants require manual transcription into electronic quality management systems, creating compliance bottlenecks.
- Liquid:Aseptically filled concentrates with defined particulate specifications integrate directly into perfusion cell culture systems. South Korean and Swiss contract manufacturers specify these formats to eliminate hydration steps, compressing demand for traditional powder suppliers lacking liquid filling capability.
- Concentrate:Ten-fold concentrated solutions reduce warehousing footprint for high-throughput bioprocessing facilities, though defined shelf lives constrain inventory positioning.
- Granules:Intermediate flow properties suit automated dispensing systems in large-scale fermentation plants, occupying niche positioning between powder handling efficiency and liquid dissolution speed.
Established standard: Powder. Ascending format: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptone manufacturing originated in European meatpacking districts during the late nineteenth century, where protein hydrolysates were first isolated for microbiological culture media. Industrial biotechnology subsequently scaled production across three continents, with regulatory divergence now shaping procurement patterns in each major jurisdiction.
United States
FDA current Good Manufacturing Practice enforcement tightens batch release protocols for peptone lots entering cell therapy supply chains. The Boston-Cambridge biotech cluster consumes pharmaceutical-grade volumes previously reserved for commodity industrial applications, with contract manufacturers specifying liquid concentrates for single-use bioreactor integration.
Germany
EMA Annex 1 revisions on sterile manufacturing elevate endotoxin documentation requirements for peptone suppliers serving Darmstadt-based pharmaceutical manufacturers. The EU Green Deal decouples bio-based feedstock sourcing from carbon-intensive supply chains, compelling buyers to audit Scope 3 emissions across animal and plant-derived inputs.
China
NMPA allergen labeling rules fragment packaging requirements for multinational peptone producers exporting to domestic biotechnology firms. Three fermentation facilities supply the majority of pharmaceutical-grade yeast extract, creating single-source vulnerability for hydrolysate-dependent manufacturers.
Singapore
Cell therapy developers accelerate vendor onboarding timelines from eighteen months to six months to secure peptone supply for clinical trials. Biotechnology firms qualify plant-based hydrolysates for regulatory submission packages, driving demand for pea and soy protein hydrolysates from Canadian and Ukrainian processors.
Switzerland
Swissmedic maintains stringent purity mandates for peptone lots entering perfusion cell culture systems at contract manufacturing facilities. Continuous bioprocessing installations shift procurement toward liquid concentrates with defined particulate specifications and documented shelf lives.
Global Peptone Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and application-intensity dimensions. The market structure bifurcates between pharmaceutical-grade specialists with documented drug master files and industrial fermentation suppliers competing on freight economics and powder format availability. Three strategic archetypes dominate: backward-integrated yeast fermentation operators, precision-characterization laboratories serving cell therapy developers, and diversified life science distributors controlling North American contract research organization channels. Capacity expansion and regulatory dossier qualification constitute the dominant competitive moves, with secondary supplier onboarding accelerating as lead times extend.
Within the backward-integrated tier, Kerry Group leverages its captive yeast fermentation infrastructure to secure certified low-carbon peptone streams aligned with EU Green Deal procurement criteria. Merck KGaA anchors the pharmaceutical-grade manufacturing segment through Darmstadt-based production scale and EMA-compliant quality systems. Thermo Fisher Scientific occupies the distribution-control archetype, channeling characterized peptone lots into North American contract research organizations and cell therapy developers.
| Leading Market Players |
|---|
| Kerry Group |
| BD Biosciences Systems & Reagents Inc. |
| Merck KGaA |
| HiMedia Laboratories Pvt. Ltd. |
| Titan Biotech Limited |
| Thermo Fisher Scientific Inc. |
| Neogen Corporation |
| Lonza Group Ltd. |
| Biospringer S.A |
| Others |
Supply Flow & Price Mechanics
EMA Annex 1 revisions compelling pharmaceutical-grade endotoxin documentation are forcing buyers to absorb quality premiums or accept extended lead times from certified suppliers. This specification tightening concentrates procurement power with backward-integrated fermentation operators who control both yeast biomass supply and hydrolysate processing.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity-grade levels separates cell therapy manufacturers from bulk fermentation buyers. Price differentiation rests on certification depth and documented molecular weight distribution rather than nitrogen content alone. Cost compression in industrial-grade segments is intensifying as Chinese and Indian antibiotic manufacturers consolidate procurement volumes. Biotechnology firms in Singapore and South Korea exhibit lowest price sensitivity due to clinical trial supply security priorities.
Supply Chain Analysis
Dual-sourcing requirements now mandated by cell therapy manufacturers in Germany, Singapore, and the United States are fragmenting procurement across primary and secondary suppliers. Production concentrates in China, the United States, and Germany, with raw material dependencies spanning Saccharomyces cerevisiae biomass, protease enzymes, and acid hydrolysis reagents. Single-source vulnerability in pharmaceutical-grade yeast extract creates supply chain risk. Distribution runs through life science distributors controlling North American contract research organization channels and direct pharmaceutical manufacturer relationships in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Peptone Market operates as a regulatory compounder where EMA Annex 1 sterile manufacturing mandates continuously elevate specification thresholds and quality premiums.
For Market Incumbents: Extend drug master file coverage into plant-based peptone categories before secondary suppliers capture animal-origin-free qualification timelines. Expand aseptic liquid filling capacity in Massachusetts and North Carolina to serve single-use bioreactor integration demand. Defensive positioning requires preempting REACH substance registration burdens that disadvantage non-EU importers. For New Entrants and Emerging Players: Launch via direct qualification with Singaporean and South Korean biotechnology firms collapsing vendor onboarding to six-month cycles. Target pea and soy protein hydrolysate segments where Canadian and Ukrainian processors lack pharmaceutical-grade finishing capability. White-space opportunity sits in continuous bioprocessing liquid concentrates with defined particulate specifications. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-characterization laboratories serving cell therapy developers rather than commodity hydrolysate operators. Five-to-ten year viability favors acquisition targets possessing mass spectrometry peptide fingerprinting capabilities and existing regulatory dossiers. Watch for LAL assay capacity constraints extending batch release timelines as an inflection indicator for quality-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | EMA Annex 1 compliance opens German pharmaceutical procurement to qualified suppliers. |
| Backward Integration into Yeast Fermentation | Kerry Group's captive biomass supply secures EU Green Deal carbon accounting advantages. |
| Aseptic Liquid Filling Capacity Addition | Perfusion cell culture adoption in Swiss facilities shifts format preference from powder. |
| Plant-Based Peptone Qualification | Singaporean biotechnology firms prioritize animal-origin-free media for regulatory submissions. |
| Mass Spectrometry Analytical Capability | Peptide fingerprinting expertise commands salary premiums and vendor selection preference. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with cell therapy manufacturing executives, regulatory affairs specialists at pharmaceutical companies, fermentation plant managers, and life science distribution channel heads informed supply-side and demand-side perspectives. Secondary sources include FDA drug master file databases, EMA Annex 1 guidance documents, REACH substance registration records, and customs trade data for hydrolysate imports. Bottom-up volume modeling and top-down value triangulation cross-validated segment estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in pharmaceutical versus industrial applications. Segmentation dimensions modeled include product type, application intensity, end-user sophistication, and physical format. CAGRs derive from regression analysis against cell therapy clinical trial expansion, continuous bioprocessing adoption rates, and regulatory documentation burden indices. Forecast inputs incorporate EMA Annex 1 implementation timelines and EU Green Deal procurement scoring adoption.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained foot-and-mouth disease quarantines in South America or sudden LAL assay capacity constraints. Deviation in FDA enforcement intensity for current Good Manufacturing Practice standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Low Melt Inclusions Market
Additives
Agrochemicals Additives Market
Additives
Caprylyl Glycol Market
Additives
Calcium Stearate Market
Additives
Cetane Improver Additives Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Refinery Process Additives Market
Additives
LAMEA Driveline Additives Market
Additives
Global Propyl Acetate Market
Additives
Adjustive Agents Market
Additives
Tartaric Acid Market
Additives
Dry-Mix Mortar Additives and Chemicals Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Antimicrobial Ingredients Market
Additives
Silicone Additives Market
Additives
Tocopheryl Acetate Market