
 Global Pearlizing Agent Market | 2026-2036
Global Pearlizing Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pearlizing Agent Market Outlook
Aftermarket formulation services is reshaping margin capture in the pearlizing agent value chain. BASF SE leverages its integrated pigment-chemicals portfolio to control raw material pathways for cosmetic-grade pearlizers. Clariant AG anchors European supply through specialized effect pigment manufacturing in Switzerland. Croda International Plc differentiates via bio-based pearlizer development targeting clean-label personal care brands.
Pearlizing agents are specialty additives that impart iridescent luster through light interference, typically composed of mica substrates coated with titanium dioxide or iron oxide at controlled thicknesses of 50-500 nanometers, and serve primarily to enhance visual appeal in consumer-facing products. Synthetic pearlizers dominate volume in mass-market cosmetics where cost efficiency outweighs natural sourcing claims, while mica-based variants command premium positioning in prestige skincare as ethical sourcing certifications tighten. The liquid form segment leads application flexibility in emulsion-based formulations, though powder grades sustain stronger margins in industrial coatings where dispersibility requirements are less stringent.
REACH registration requirements in Europe and FDA color additive regulations in the United States govern ingredient safety thresholds and labeling protocols for cosmetic applications. China's NMPA and GB standards for cosmetic raw materials are raising compliance barriers for imported pearlizers. India's BIS and CDSCO frameworks are converging toward harmonized safety assessments for personal care inputs. Stakeholders must monitor evolving mica supply chain transparency mandates and pre-empt regulatory divergence across major formulation hubs.
Market Dynamics
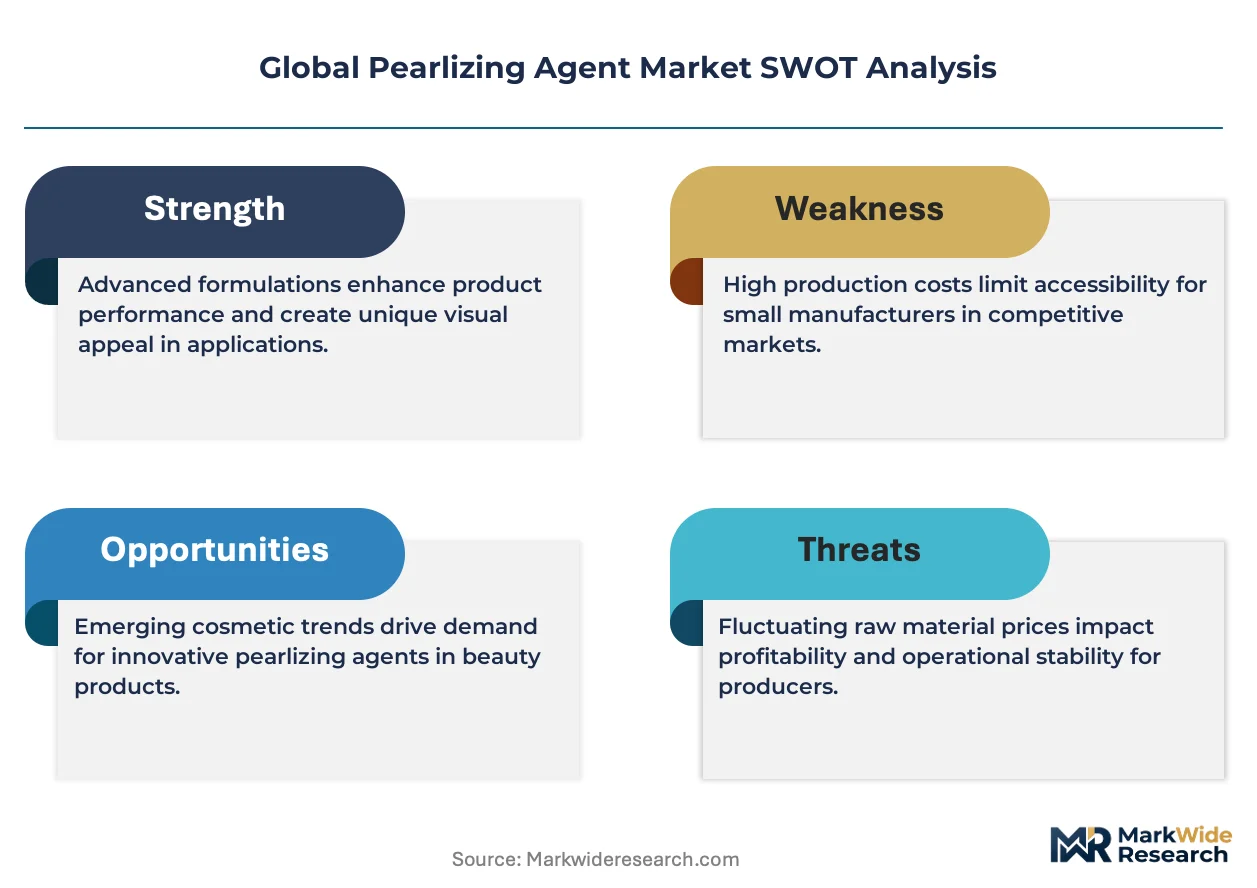
Clean-label certification requirements are fragmenting procurement patterns across cosmetic formulation houses, forcing pearlizing agent suppliers to maintain parallel inventory streams for REACH-registered synthetics and ethically audited natural mica grades.
Growth Catalysts
- Prestige skincare expansion:Premium beauty brands in China and South Korea are scaling pearlized serum and cushion compact lines, pulling titanium dioxide-coated mica demand upward.
- REACH registration completion:ECHA's 2023 dossier updates for nano-scale titanium dioxide have clarified compliance pathways, reducing regulatory uncertainty for European formulators.
- Biomimetic coating advances:Sol-gel deposition techniques now enable thinner, more uniform metal oxide layers, improving optical efficiency at reduced raw material loads.
Market Restraints
- Mica supply concentration:Jharkhand and Rajasthan in India supply over sixty percent of cosmetic-grade natural mica, creating geographic single-point vulnerability.
- Titanium dioxide cost volatility:Chloride-process pigment feedstock prices fluctuate with energy input costs, compressing margins for mid-tier pearlizer manufacturers.
- Substitution pressure from diffractive pigments:Holographic flake technologies in nail polish and automotive coatings are capturing visual-effect budgets that previously flowed to interference pearlizers.
Strategic Opportunities
- Indonesia personal care manufacturing:Domestic beauty brand formation in Jakarta and Surabaya is outpacing local pearlizer supply, opening import substitution potential.
- SAMR clean-label incentives:China's State Administration for Market Rewards prioritizes bio-based cosmetic ingredients in provincial industrial policy, advantaging certified sustainable pearlizers.
- Direct-to-brand e-commerce channels:Specialty chemical platforms are disintermediating traditional distributor networks, enabling smaller pearlizer producers to access mid-size cosmetic houses directly.
Industry Challenges
- Colorimetrist talent scarcity:Formulation science programs produce fewer specialists in interference optics than the expanding effect-pigment sector requires.
- ISO 16128 naturalness certification timelines:Third-party verification of bio-based content claims for mica alternatives extends eighteen to twenty-four months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pearlizing Agent Market |
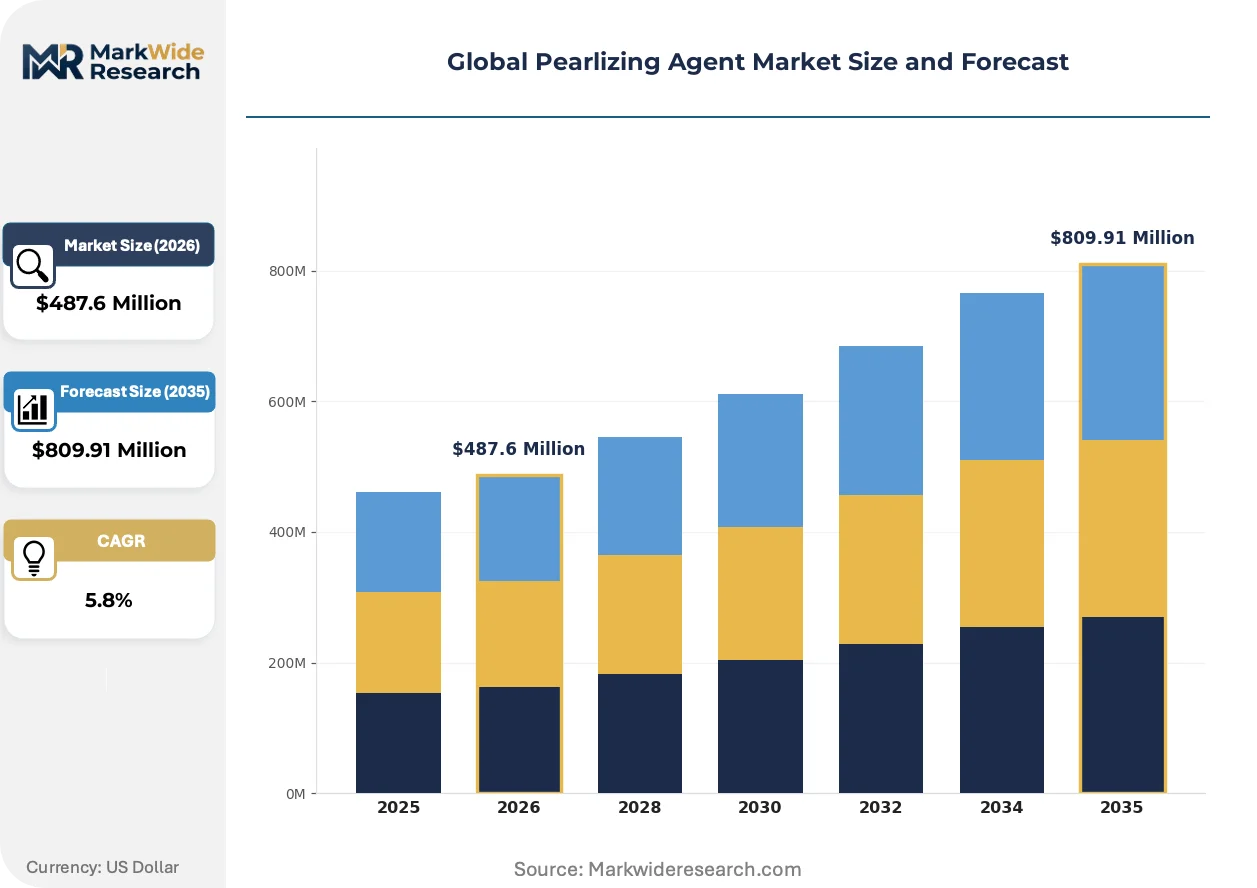
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Pearlizers, Synthetic Pearlizers, Mica-Based Pearlizers, Organic Pearlizers Application: Personal Care, Coatings, Plastics, Inks End User: Cosmetic Manufacturers, Paint Producers, Packaging Companies, Textile Industry Form: Powder, Liquid, Granule, Paste |
| Companies Covered | BASF SE, Clariant AG, Lubrizol Corporation, Ashland Global Holdings Inc., Croda International Plc, Galaxy Surfactants Ltd., Evonik Industries AG, Stepan Company, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pearlizing Agent Market Strategic Shifts
Formulation science is converging with supply chain traceability technology, redefining how pearlizing agents are specified, sourced, and validated across cosmetic value chains.
Synthetic mica substrates produced via high-temperature fusion of metal oxides are hybridizing with traditional natural mica in hybrid pearlizer grades. Korean color cosmetic houses are adopting these fused silica-core alternatives fastest, driven by ethical sourcing mandates from Western retail partners. The technology is hybridizing procurement specifications, forcing suppliers to maintain dual certification tracks for natural and synthetic provenance.
ECHA's 2023 restriction proposal on microplastics in leave-on cosmetics is tightening formulation constraints for polymer-based pearlizers in the European Union. The regulation is accelerating R&D investment in biodegradable film-forming alternatives by German and French specialty chemical divisions. Rinse-off applications face earlier compliance deadlines than skincare, shifting near-term demand toward powder-grade interference pigments with inherent dispersibility.
Beauty brand technical buyers are consolidating supplier panels and demanding lot-level blockchain traceability for mica origins. This concentration is displacing spot-market purchasing for unverified Indian mica, favoring integrated miners with in-house coating capabilities. The shift is most visible in German and Swiss formulation houses serving prestige skincare labels with explicit ethical sourcing pledges.
Global Pearlizing Agent Market Segmentation
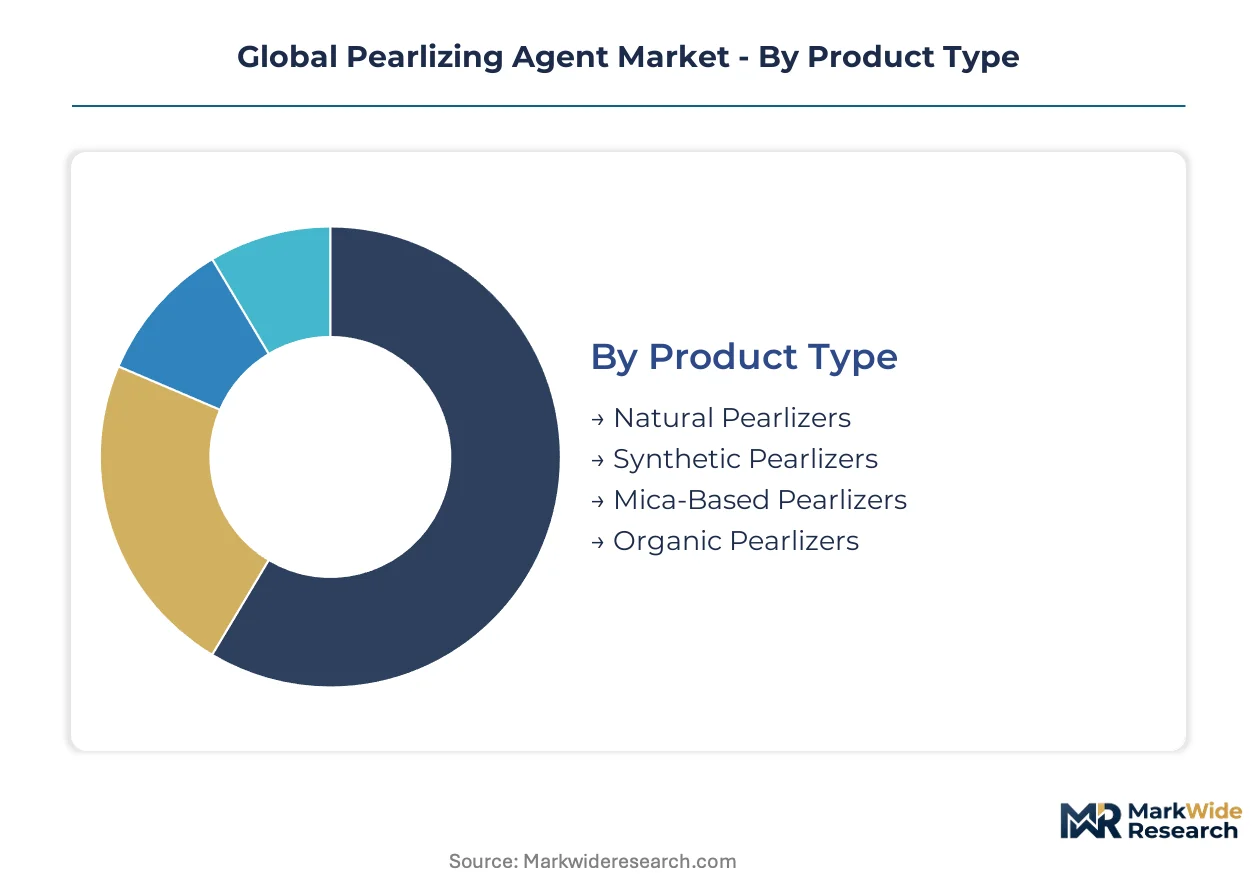
Pearlizing agent procurement patterns diverge sharply across formulation contexts, with cosmetic houses prioritizing ethical certification while industrial buyers optimize for dispersibility economics. Segment boundaries are blurring as hybrid grades emerge, yet distinct technical specifications still govern supplier qualification pathways.
Product Type:
After-sales technical support intensity varies dramatically across pearlizer chemistries, with natural mica grades requiring extensive supply chain documentation services that synthetic alternatives rarely demand.
- Synthetic Pearlizers:Manufactured via high-temperature fusion of metal oxides into silica-cored substrates with controlled refractive indices. Mass-market cosmetic manufacturers in China and Southeast Asia concentrate procurement here, drawn by batch-to-batch color consistency and simplified REACH dossier maintenance.
- Mica-Based Pearlizers:Natural muscovite or phlogopite substrates coated with titanium dioxide or iron oxide layers at 50-500 nanometer thicknesses. Prestige skincare formulators in Germany and Switzerland anchor demand, with procurement decisions increasingly contingent on blockchain-verified origin documentation from Jharkhand and Rajasthan mining clusters.
- Natural Pearlizers:Unmodified mineral substrates including untreated mica and bismuth oxychloride with inherent pearlescence. Niche organic cosmetic brands in France and California represent the primary offtake.
- Organic Pearlizers:Bio-based alternatives derived from cellulose, starch, or algae extracts with film-forming optical properties. Clean-label startups in South Korea and the Netherlands are piloting these grades despite ISO 16128 certification delays.
By volume, synthetic pearlizers lead. By growth pace, organic alternatives are climbing fastest as SAMR clean-label incentives reshape Chinese procurement priorities.
Application:
Margin structures across end-use applications reflect fundamentally different performance thresholds, with personal care commanding premium pricing for sensory attributes that coatings buyers dismiss.
- Personal Care:Emulsion-based color cosmetics, skincare serums, and hair care products requiring skin-safe particle sizes below 150 microns. Domestic beauty brand formation in Jakarta and Surabaya is expanding fastest, though European prestige houses still set formulation standards.
- Coatings:Automotive refinish, industrial maintenance, and decorative architectural applications where weathering resistance dominates specifications. Powder-grade interference pigments sustain stronger margins here due to less stringent dispersibility requirements.
- Plastics:Injection-molded packaging and consumer goods requiring thermal stability above 200°C. Mass-volume converters in China's Pearl River Delta represent the core demand cluster.
- Inks:Gravure and flexographic printing for decorative packaging. Narrower specification windows limit supplier switching compared to coatings.
Personal care generates the highest revenue per kilogram. Coatings deliver the steadiest volume offtake through automotive cycle resilience.
End User:
Customer concentration patterns determine contract structure, with cosmetic manufacturers demanding lot-level traceability that paint producers rarely require.
- Cosmetic Manufacturers:Ranging from multinational prestige houses to emerging direct-to-consumer brands. Technical buyer consolidation is displacing spot-market purchasing in favor of integrated suppliers with in-house coating capabilities.
- Paint Producers:Decorative and industrial coating formulators with specification-driven procurement. ECHA's microplastics restriction is accelerating R&D investment in biodegradable alternatives by German and French specialty chemical divisions.
- Packaging Companies:Rigid and flexible plastic converters seeking visual differentiation for consumer goods. Thermal processing constraints narrow the qualified supplier base.
- Textile Industry:Fiber and fabric finishers applying pearlizers through padding or exhaust methods. Smaller addressable market with specialized dispersant requirements.
Cosmetic manufacturers pay the steepest premium for certified provenance. Packaging companies are expanding offtake most quickly as Asian consumer goods brands scale pearlized product lines.
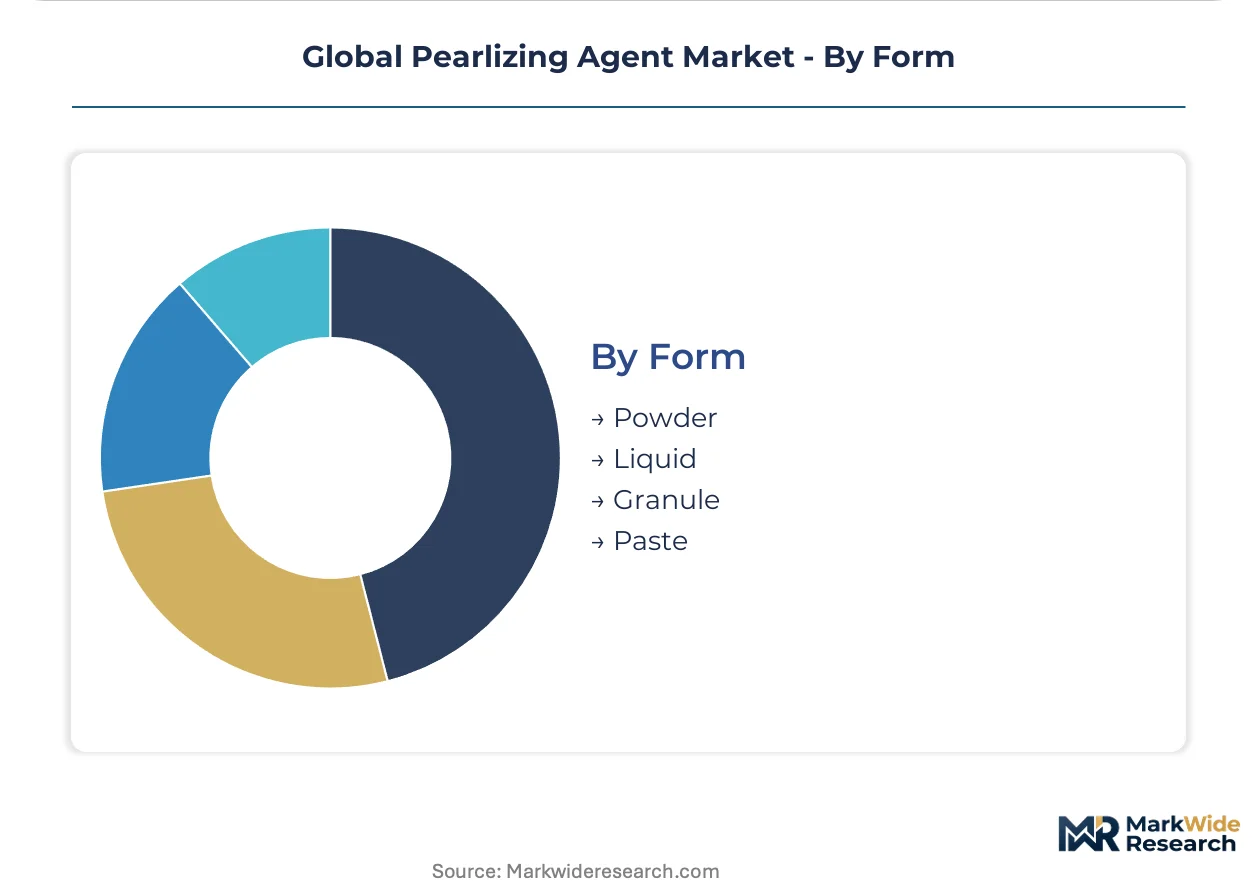
Form:
Physical state selection hinges on formulation infrastructure, with liquid grades favoring emulsion houses and powder forms dominating industrial coating operations.
- Liquid:Pre-dispersed aqueous or solvent-based concentrates eliminating milling steps. Emulsion cosmetic manufacturers prefer this form for production line efficiency.
- Powder:Free-flowing grades with controlled agglomeration for dry blending. Industrial coatings and plastics compounding rely predominantly on this form.
- Paste:High-solids dispersions in cosmetic-compatible carriers. Niche applications in premium color cosmetics.
- Granule:Dust-free handling formats for plastics extrusion. Limited adoption outside polymer processing.
Liquid forms dominate personal care flexibility. Powder grades command the broadest cross-industry applicability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across geographies. Chinese domestic brands squeeze mid-tier suppliers on titanium dioxide-coated mica costs, while German prestige houses absorb premiums for blockchain-verified Jharkhand origin documentation.
China
Domestic beauty brand formation in Shanghai and Hangzhou scales pearlized serum lines fastest. SAMR clean-label incentives in provincial industrial policy advantage certified sustainable pearlizers. The Yangtze River Delta concentration of emulsion cosmetic manufacturers pulls liquid-form concentrate imports upward.
Germany
Prestige skincare formulators in Hamburg and Düsseldorf anchor European demand for REACH-registered nano-scale titanium dioxide grades. ECHA's 2023 dossier updates clarified compliance pathways, reducing regulatory uncertainty. The Rhine-Ruhr specialty chemical corridor accelerates R&D investment in biodegradable film-forming alternatives.
United States
Direct-to-consumer cosmetic startups in Los Angeles and New York consolidate supplier panels demanding lot-level traceability. FDA color additive regulations govern labeling protocols for interference pigments. The Northeast formulation corridor serving prestige skincare labels with ethical sourcing pledges displaces spot-market purchasing.
South Korea
Korean color cosmetic houses adopt fused silica-core synthetic mica alternatives fastest, driven by Western retail partner ethical mandates. MFDS cosmetic raw material standards raise compliance barriers for imported pearlizers. The Seoul metropolitan area's cushion compact manufacturing clusters pull titanium dioxide-coated mica demand upward.
India
Jharkhand and Rajasthan mining clusters supply over sixty percent of cosmetic-grade natural mica, creating geographic single-point vulnerability. BIS and CDSCO frameworks converge toward harmonized safety assessments for personal care inputs. Mumbai-based formulation houses expanding pearlized hair care lines concentrate procurement from integrated miners with in-house coating capabilities.
Global Pearlizing Agent Market Competitive Environment
Capability concentration sits with integrated pigment-chemicals portfolios; scale advantage sits with mass-market emulsion specialists. The vendor base stratifies into three tiers: multinational diversified chemical conglomerates controlling raw material pathways, European effect pigment specialists anchoring premium supply, and regional surfactant houses serving cost-sensitive Asian formulators. Dominant competitive moves include backward integration into mica mining and coating operations, plus strategic partnerships with blockchain traceability platforms.
Within the diversified chemicals tier, BASF SE and Evonik Industries AG exemplify integrated players with captive control over titanium dioxide feedstock pathways. Clariant AG occupies a position as the European effect pigment specialist anchoring prestige supply through Swiss manufacturing concentration. Croda International Plc represents the bio-based development vector targeting clean-label certification timelines.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Lubrizol Corporation |
| Ashland Global Holdings Inc. |
| Croda International Plc |
| Galaxy Surfactants Ltd. |
| Evonik Industries AG |
| Stepan Company |
| Solvay S.A. |
| Others |
Value Chain & Pricing Dynamics
Jharkhand and Rajasthan mining clusters supply over sixty percent of cosmetic-grade natural mica, anchoring margin capture with integrated miners who control both extraction and coating operations while spot-market traders face displacement. Titanium dioxide feedstock volatility from chloride-process energy inputs compresses mid-tier pearlizer manufacturers, forcing pricing stratification across certification tiers.
Pricing Analysis
After-sales technical support intensity around supply chain documentation services drives lifetime value for natural mica grades, with blockchain-verified origin certification commanding premiums from German and Swiss prestige houses. Pricing stratifies across REACH-registered synthetics, ethically audited natural grades, and emerging bio-based alternatives. Cost compression in mass-market titanium dioxide-coated mica intensifies because Chinese domestic brands squeeze mid-tier suppliers on volume contracts. Cosmetic manufacturers absorb the steepest premiums for certified provenance, while industrial coatings buyers optimize for dispersibility economics alone.
Supply Chain Analysis
Titanium dioxide feedstock draws from chloride-process pigment production concentrated in China, Germany, and the United States, with mica substrate extraction anchored in India and synthetic fused silica-core alternatives scaling fastest in South Korea. Raw material dependencies center on titanium tetrachloride, natural muscovite, and high-purity metal oxide precursors. Single-source vulnerability from Jharkhand-Rajasthan concentration creates geographic risk exposure. Distribution runs through specialty chemical platforms disintermediating traditional distributor networks for direct brand access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interference optics expertise scarcity constrains formulation science program output, with colorimetrist talent gaps widening faster than effect-pigment sector expansion can absorb qualified specialists.
For Market Incumbents: Build regulatory moats around REACH-registered nano-scale dossiers and blockchain-verified mica origin documentation to defend against synthetic mica substitution and clean-label startup disruption. Deepen captive control over Jharkhand-Rajasthan mining clusters through backward integration into coating operations. Anchor European prestige supply through specialized effect pigment manufacturing concentration. For New Entrants and Emerging Players: Build out direct-to-brand e-commerce channels targeting mid-size cosmetic houses in Jakarta and Surabaya where domestic beauty brand formation outpaces local pearlizer supply. Indonesia personal care manufacturing represents the most penetrable geography. Pursue SAMR clean-label certification pathways to access Chinese provincial industrial policy incentives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional surfactant houses serving cost-sensitive Asian formulators, where capability gaps in interference optics R&D create consolidation opportunity. Long-term viability favors integrated miners with in-house coating capabilities over spot-market traders. Watch for ECHA microplastics restriction enforcement timelines as inflection signal for biodegradable film-forming alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mica Mining | Captures margin pools from Jharkhand-Rajasthan extraction through coating operations consolidation. |
| Blockchain Traceability Partnership | Enables lot-level origin documentation demanded by German prestige skincare formulators. |
| Biomimetic Coating R&D Investment | Improves optical efficiency at reduced titanium dioxide loads via sol-gel deposition advances. |
| Direct-to-Brand E-Commerce Channel | Disintermediates distributor networks for mid-size cosmetic house access in Southeast Asia. |
| SAMR Clean-Label Certification | Unlocks provincial industrial policy advantages in China's Yangtze River Delta manufacturing clusters. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade customs data, ECHA registration dossiers, and SEC specialty chemical filings, with input from formulation scientists at cosmetic houses, procurement leads at coating manufacturers, technical directors at effect pigment specialists, and supply chain managers at integrated mining operations. Bottom-up volume modeling triangulates against top-down market sizing from regulatory filings and industry association reports.
Forecast inputs include pearlizer grade tier, end-use application, physical form factor, and regional production hub clustering across the projection horizon. CAGRs derive from segment-level growth rate analysis applied to base-year value estimates. Specific inputs encompass titanium dioxide cost volatility indices, clean-label certification penetration curves, and prestige skincare brand formation rates in target geographies.
Stress conditions across titanium dioxide feedstock price bands, ECHA microplastics restriction enforcement timelines, and Jharkhand-Rajasthan supply disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory divergence or biomimetic coating technology breakthroughs. Cross-checking against customs trade flow data and specialty chemical distributor inventory reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Adjustive Agents Market
Additives
Sorbitan Tristearate Market
Additives
Guanylic Acid Market
Additives
Metal Deactivators Market
Additives
Global Chelated Trace Minerals Market
Additives
North America Phosphate Esters Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Chelating Agents Market
Additives
Extruded Inclusions Market
Additives
China Citric Acid Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Ammonium Acetate Market
Additives
Green Polymer Additive Market
Additives
North America Fuel Additives Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Japan Sodium Reduction Ingredient Market