

Additives for Metalworking Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Additives for Metalworking Fluids Market Insights
The capital-intensity divergence between integrated compounders and standalone additive suppliers is rotating competitive advantage toward in-house synthesis capabilities. Lubrizol leverages backward integration into sulfurized olefin chemistry to sustain margin capture across extreme pressure agent lines. Afton Chemical anchors its position through dedicated R&D facilities in Asia-Pacific formulation centers. Evonik Industries differentiates via specialty ester technology leadership that commands specification adherence from aerospace tier-one suppliers.
Additives for metalworking fluids comprise chemically engineered compounds—typically sulfurized hydrocarbons, phosphate esters, boron derivatives, and amine-based corrosion inhibitors—dosed at 1-15% concentration to modify lubricity, thermal stability, and microbial resistance in cutting and grinding operations. Their primary industrial purpose centers on extending tool life, improving surface finish quality, and enabling higher machining speeds in ferrous and non-ferrous metal removal processes. Corrosion inhibitors and extreme pressure agents command the deepest margin pools due to specification-critical performance requirements in aerospace and precision engineering end uses. Synthetic technology formulations are outpacing mineral oil based alternatives as machinery fabrication customers impose tighter biodegradability and mist exposure thresholds.
EPA oversight of metalworking fluid mist exposure limits and OSHA workplace safety standards directly shape product formulation decisions and facility ventilation investments across United States manufacturing. REACH registration requirements and ECHA substance restriction protocols in Europe are eliminating certain chlorinated paraffin and formaldehyde-releasing biocide chemistries from approved additive lists. Stakeholders must monitor regulatory divergence between EPA hazard communication standards and EU Green Deal chemical sustainability criteria to anticipate reformulation timelines and raw material qualification cycles.
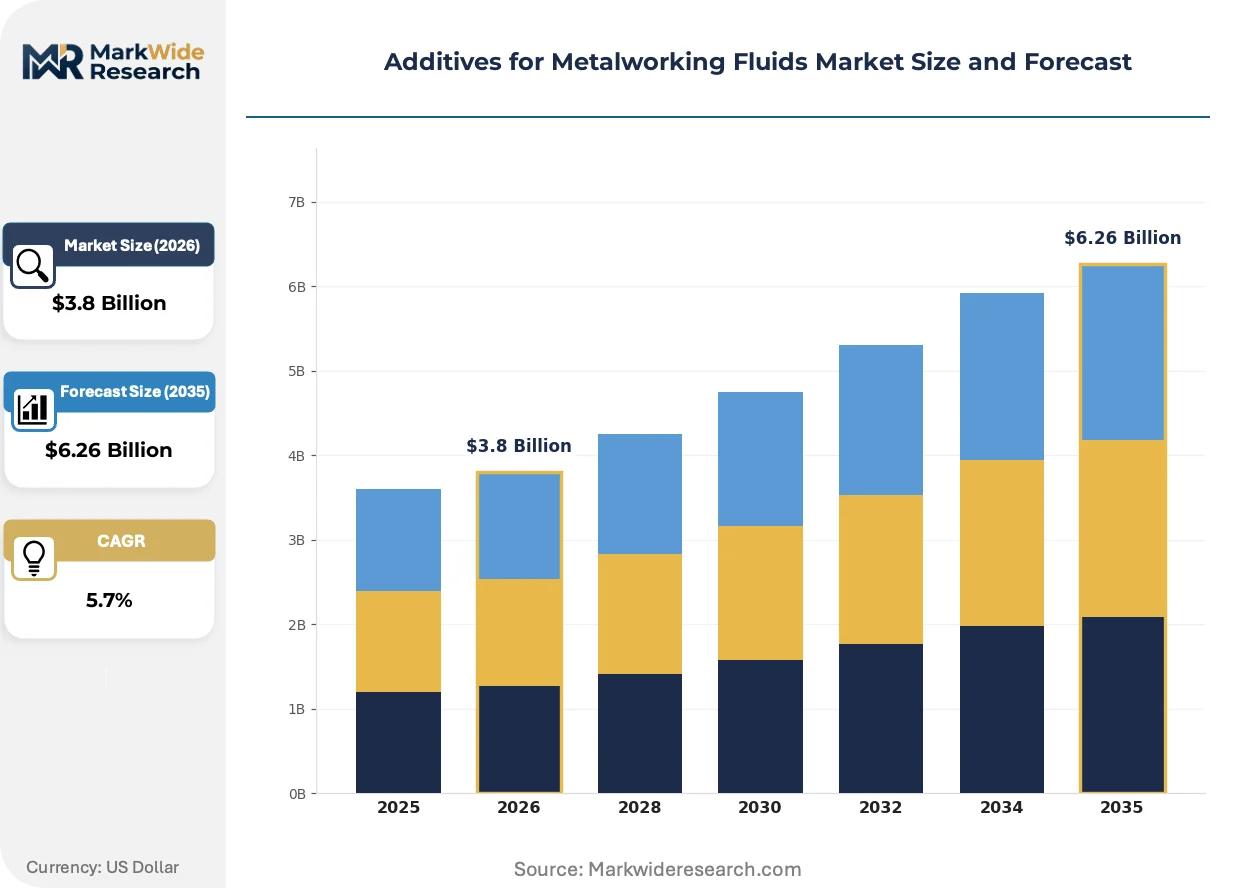
Market Dynamics
REACH substance restrictions and EPA mist exposure mandates are forcing simultaneous reformulation across extreme pressure and corrosion inhibitor additive lines, compressing qualification timelines while elevating specification-grade purchasing power.
Growth Catalysts
- EU Green Deal chemical sustainability criteria:Bio-based ester chemistries gain specification adherence from aerospace tier-one suppliers seeking REACH-compliant alternatives to chlorinated paraffins.
- German precision engineering clusters:Stuttgart and Munich manufacturing belts concentrate demand for high-performance sulfurized olefin formulations in multi-axis machining centers.
- Synthetic technology formulations:Biodegradability thresholds in metalworking fluid mist exposure protocols accelerate displacement of mineral oil base stocks across automotive powertrain machining.
Market Restraints
- Base oil supply concentration:Integrated compounders with captive sulfurized olefin synthesis capabilities limit standalone additive supplier margin capture in extreme pressure agent segments.
- ECHA formaldehyde-releasing biocide restrictions:Approved additive lists exclude triazine derivatives, forcing reformulation of microbial resistance packages in water-miscible fluids.
- Technical limitation in bio-based EP performance:Vegetable-derived sulfur carriers fail to match thermal stability of petroleum-based equivalents in high-speed ferrous grinding.
Strategic Opportunities
- India BIS certification pathways:Domestic metalworking fluid compounders seek qualified additive suppliers for automotive component machining expansion in Pune and Chennai industrial corridors.
- Technology convergence of boron derivatives and ionic liquids:Hybrid corrosion inhibitor platforms address multi-metal protection requirements in aerospace aluminum-titanium stack machining.
- OSHA workplace safety standard enforcement:Mist collection system upgrades in US job shops create pull for low-mist semisynthetic formulations with reduced volatile organic compound profiles.
Industry Challenges
- REACH registration dossier compilation timelines:Small and mid-cap additive suppliers face 18-24 month qualification cycles for novel ester chemistry submissions to ECHA.
- Legacy mineral oil formulation integration:Machinery fabrication customers resist full synthetic conversion due to coolant system incompatibility and retraining costs on shop floors.
- Specialized tribochemistry skill scarcity:Formulation chemists with expertise in phosphate ester-sulfurized olefin synergy effects command premium compensation in tight labor markets.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additives for Metalworking Fluids Market Trends and Innovations
Active regulatory phase-outs of conventional chemistries are fragmenting established additive portfolios while creating specification-grade entry points for bio-derived and synthetic alternatives.
Boron-nitrogen complex technology is fragmenting traditional amine-based corrosion inhibitor segments. Aerospace component manufacturers in Germany and Japan adopt these complexes for aluminum alloy protection in high-humidity machining environments. The displacement of conventional chemistries compresses pricing power for legacy inhibitor suppliers while rewarding backward-integrated compounders with proprietary boron derivative synthesis.
EPA metalworking fluid mist exposure limit enforcement intensified through updated OSHA workplace safety standards. US machinery fabrication facilities face mandatory ventilation upgrades or reformulation to semisynthetic low-mist alternatives. Precision engineering job shops in Michigan and Ohio industrial belts accelerate coolant system conversions to reduce personal protective equipment compliance costs.
Buyer concentration among aerospace tier-one suppliers intensifies specification-grade purchasing leverage. Long-term supply agreements with Boeing and Airbus machining contractors displace spot-market additive procurement. Germany and France-based precision engineering clusters consolidate supplier qualification lists to three approved compounders per additive category.
Additives for Metalworking Fluids Market Segmentation
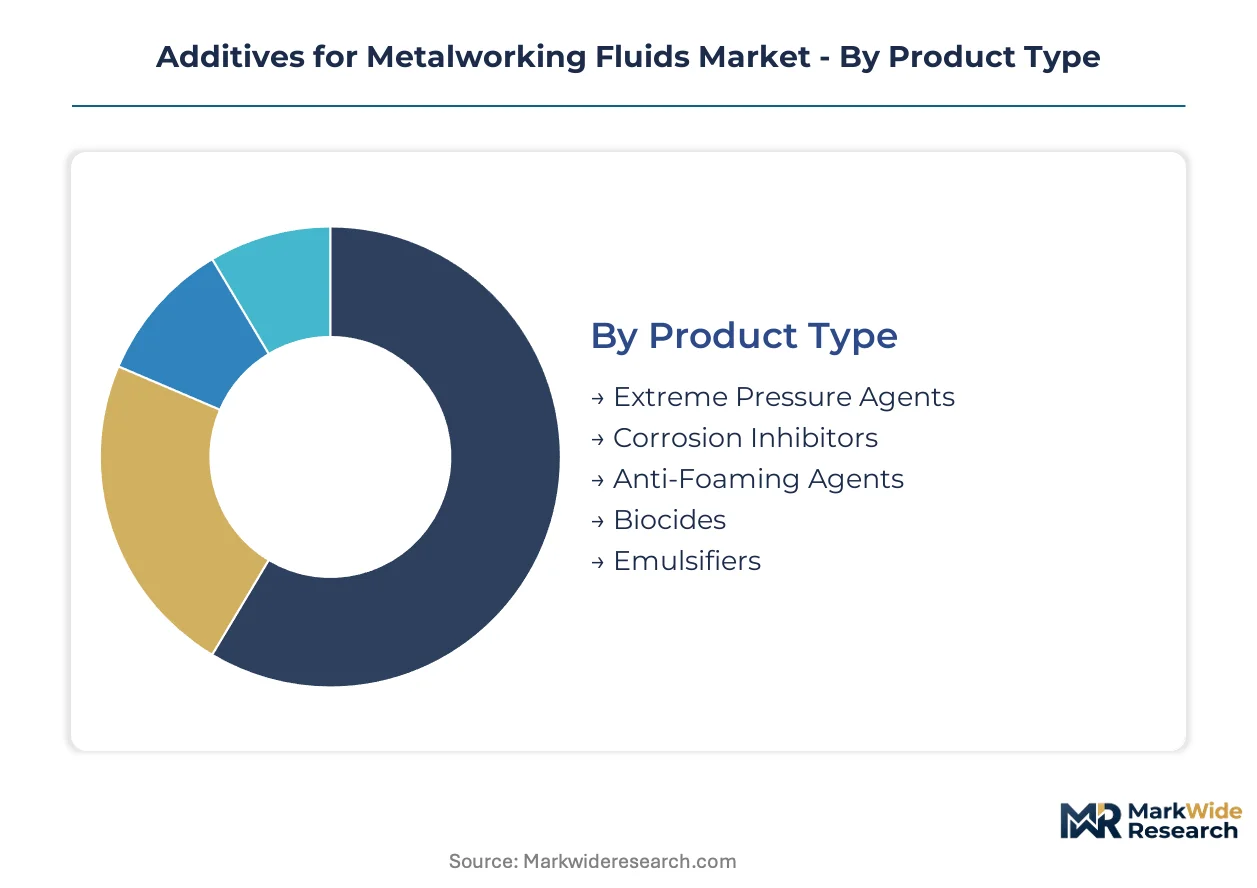
Additive selection in metalworking fluids hinges on machining intensity, base fluid chemistry, and regulatory compliance thresholds. Specification-grade purchasing concentrates in aerospace and precision engineering end uses where tool life and surface finish requirements command premium formulation investments.
Product Type:
Margin pools concentrate in extreme pressure agents and corrosion inhibitors due to specification-critical performance requirements and reformulation complexity under REACH substance restrictions.
- Extreme Pressure Agents:Sulfurized olefins and phosphate esters form sacrificial films under high-load metal-to-metal contact. Aerospace tier-one suppliers in Germany and Japan specify these chemistries for titanium and nickel alloy machining, driving qualification-grade purchasing with 18-24 month approval cycles.
- Corrosion Inhibitors:Amine-based and boron-nitrogen complexes protect ferrous and non-ferrous surfaces from humidity-induced degradation. Stuttgart precision engineering clusters specify boron-nitrogen technology for aluminum alloy protection, displacing legacy chemistries amid ECHA formaldehyde-releasing biocide restrictions.
- Anti-Foaming Agents:Silicone and polyacrylate chemistries control air entrainment in high-pressure coolant delivery systems.
- Biocides:Microbial resistance packages face reformulation pressure as triazine derivatives exit approved additive lists under European regulatory protocols.
- Emulsifiers:Surfactant systems stabilize oil-in-water dispersions for water-miscible cutting fluids across automotive powertrain machining.
Extreme pressure agents hold installed capacity in legacy petroleum-based formulations. Corrosion inhibitors are rotating up the share rankings as boron-nitrogen complexes gain specification adherence.
Technology:
Cost tiers separate synthetic formulations commanding premium pricing from mineral oil based alternatives facing displacement pressure under biodegradability mandates.
- Synthetic:Polyalkylene glycol and synthetic ester base stocks deliver thermal stability and biodegradability compliance. Automotive powertrain machining in Michigan and Ohio industrial belts accelerates conversion to these formulations under OSHA mist exposure enforcement.
- Semi-Synthetic:Hybrid oil-water emulsions balance lubricity with coolant system compatibility. Job shops resisting full synthetic conversion favor this tier for reduced retraining costs and existing infrastructure reuse.
- Mineral Oil Based:Conventional paraffinic and naphthenic base stocks face regulatory pressure from EPA and EU Green Deal chemical sustainability criteria.
- Water Soluble:Dilutable concentrates serve high-volume flood coolant applications in heavy equipment manufacturing.
- Ester Based:Bio-derived and synthetic ester chemistries address REACH-compliant alternatives to chlorinated paraffins in aerospace specification work.
Mineral oil based technology retains installed base in legacy machinery. Synthetic formulations are climbing the fastest as machinery fabrication customers impose tighter biodegradability thresholds.
Application:
Volume concentration tracks machining intensity, with grinding and cutting operations consuming additive packages at divergent dose rates and performance specifications.
- Metal Cutting:Turning, boring, and broaching operations demand balanced lubricity and cooling across ferrous and non-ferrous alloys. Multi-axis machining centers in German precision engineering clusters specify high-performance sulfurized olefin formulations for extended tool life.
- Grinding:High-speed abrasive processes generate thermal loads requiring specialized extreme pressure and anti-wear chemistries. Thermal stability limitations in vegetable-derived sulfur carriers constrain bio-based penetration in ferrous grinding applications.
- Drilling:Deep-hole penetration operations require enhanced chip evacuation and tool cooling.
- Milling:Intermittent cutting cycles impose cyclic thermal loading on additive thermal stability.
- Tapping:Thread-forming operations demand high lubricity additives to prevent galling in stainless steel and titanium alloys.
Metal cutting commands established volume share. Grinding is expanding most quickly as surface finish specifications tighten in aerospace component manufacturing.
End User Industry:
Customer type stratification separates specification-grade aerospace purchasing from price-sensitive heavy equipment procurement, with precision engineering representing the margin optimization tier.
- Aerospace Components:Boeing and Airbus machining contractors enforce long-term supply agreements with qualified additive compounders. Tier-one supplier consolidation in Germany and France restricts approved supplier lists to three compounders per additive category.
- Precision Engineering:Stuttgart and Munich manufacturing belts concentrate demand for high-performance formulations in medical device and instrumentation machining. REACH registration requirements elevate purchasing power toward backward-integrated compounders with proprietary synthesis capabilities.
- Machinery Fabrication:General job shops in US industrial belts face OSHA workplace safety standard enforcement driving mist collection upgrades or reformulation investments.
- Heavy Equipment:Construction and mining machinery manufacturers prioritize cost efficiency in high-volume flood coolant applications.
- Electronics Manufacturing:Precision machining of aluminum heat sinks and enclosures requires corrosion protection without ionic contamination.
Machinery fabrication retains broad installed base. Aerospace components are gaining share fastest as supply agreements displace spot-market procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between aerospace-driven specification markets in Germany and cost-optimized automotive machining in China. European demand concentrates in REACH-compliant bio-based formulations, while US job shops prioritize low-mist semisynthetics under OSHA enforcement.
Germany
Stuttgart and Munich precision engineering clusters drive specification-grade purchasing for sulfurized olefin formulations. REACH substance restrictions eliminate chlorinated paraffins from approved additive lists, accelerating bio-based ester qualification. Baden-Württemberg's multi-axis machining centers enforce 18-24 month supplier approval cycles for Boeing and Airbus tier-one contractors.
United States
EPA metalworking fluid mist exposure mandates reshape formulation decisions across Michigan and Ohio industrial belts. OSHA workplace safety standard enforcement drives coolant system conversions toward low-mist semisynthetics. Automotive powertrain machining in the Great Lakes region accelerates displacement of mineral oil base stocks under biodegradability thresholds.
China
Automotive component manufacturing expansion in Yangtze River Delta and Pearl River Delta regions concentrates additive demand. MEE environmental compliance protocols tighten discharge standards for metalworking fluid waste streams. Domestic compounders in Shanghai and Guangzhou industrial corridors seek qualified extreme pressure agent suppliers for high-volume flood coolant applications.
Japan
Precision machining of aluminum-titanium aerospace stacks drives boron-nitrogen corrosion inhibitor adoption in Nagoya and Osaka manufacturing belts. METI industrial standards emphasize thermal stability performance in high-speed grinding operations. Chubu region's medical device machining clusters specify REACH-compliant alternatives to formaldehyde-releasing biocides.
India
Automotive component machining expansion in Pune and Chennai industrial corridors creates demand for BIS-certified additive suppliers. CDSCO chemical safety protocols align formulation requirements with export market access. Domestic metalworking fluid compounders in Maharashtra and Tamil Nadu seek qualified extreme pressure and corrosion inhibitor packages for multi-metal protection.
Additives for Metalworking Fluids Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the additives for metalworking fluids market. Backward-integrated compounders with captive sulfurized olefin synthesis capabilities capture margin pools in extreme pressure agent segments, while standalone additive suppliers face compression in qualification timelines. Two strategic archetypes dominate: specification-grade formulators serving aerospace tier-one suppliers, and scale-driven suppliers addressing automotive powertrain machining. Competitive moves concentrate on portfolio diversification into bio-based chemistries and geographic expansion through Asia-Pacific formulation center investments.
Within the integrated compounder tier, Lubrizol and Infineum exemplify backward-integrated positioning with proprietary synthesis capabilities. Afton Chemical occupies a position among Asia-Pacific-anchored specialists with dedicated R&D facility investments. These three represent divergent strategic vectors: captive raw material control, regional formulation proximity, and specification-grade qualification expertise respectively.
| Leading Market Players |
|---|
| Lubrizol |
| Infineum |
| Afton Chemical |
| Lanxess |
| Chevron Oronite |
| Evonik Industries |
| BASF |
| Dow |
| FUCHS |
| Others |
Pricing and Supply Chain Analysis
Bio-based ester chemistries displacing chlorinated paraffins under REACH mandates are redrawing raw material procurement maps from Germany to India while compressing margin capture for additive suppliers lacking backward integration into sulfurized olefin synthesis. This substitution dynamic concentrates pricing power with integrated compounders who control captive production of specification-grade extreme pressure agents.
Pricing Analysis
Long-term supply agreements with Boeing and Airbus tier-one contractors dominate procurement structures, displacing spot-market transactions in aerospace-grade additive segments. Price differentiation separates REACH-registered premium formulations from standard mineral-oil alternatives, with certification-grade boron-nitrogen complexes commanding substantial premiums over legacy amine-based inhibitors. Cost compression in mid-tier semisynthetics is intensifying because automotive powertrain manufacturers impose volume-scale purchasing leverage. Heavy equipment manufacturers exhibit highest price sensitivity, while aerospace component suppliers prioritize specification adherence over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for specialty ester raw materials sourced from Chinese and Indian chemical manufacturers. Supply concentrates in Germany, the United States, and China, with Stuttgart precision engineering clusters and Michigan automotive corridors serving as formulation demand anchors. Raw material dependencies center on sulfurized olefins, phosphate esters, and boron derivatives. Single-source vulnerability characterizes extreme pressure agent supply where captive synthesis capabilities remain limited to integrated compounders. Distribution runs through qualified compounder networks rather than direct additive supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where REACH-compliant formulation ecosystems are consolidating around backward-integrated suppliers capable of delivering specification-grade interoperability across aerospace supply chains.
For Market Incumbents: Consolidate supplier qualification relationships with Boeing and Airbus machining contractors through dedicated R&D facility investments in Stuttgart and Nagoya precision engineering clusters. Deepen backward integration into sulfurized olefin chemistry to defend margin pools against emerging bio-based entrants lacking thermal stability performance in high-speed ferrous grinding applications.
For New Entrants and Emerging Players: BIS certification fast-tracks for automotive component machining in Pune and Chennai industrial corridors unlock white-space access where domestic Indian compounders seek qualified extreme pressure agent suppliers. Target water-miscible fluid biocide reformulation segments where triazine derivative exclusions create immediate specification gaps. Deploy technical service partnerships with regional compounders as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: ECHA formaldehyde-releasing biocide restrictions reshape the acquisition landscape by devaluing legacy microbial resistance package portfolios while elevating boron-nitrogen complex technology platforms. Five-to-ten-year viability favors mid-cap specialists with proprietary ester synthesis capabilities and established REACH registration dossiers. Monitor India BIS certification completion rates as the signal to watch for geographic demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfurized Olefin Synthesis | Captive raw material control secures margin capture in extreme pressure agent segments dominated by aerospace specification work. |
| REACH-Compliant Bio-Based Ester Qualification | Alternative chemistry registration opens specification-grade access as chlorinated paraffins exit approved additive lists. |
| Asia-Pacific Formulation Center Investment | Regional R&D proximity accelerates qualification timelines for Boeing and Airbus tier-one supplier approval cycles. |
| Long-Term Supply Agreement Consolidation | Contracted offtake structures displace spot procurement among precision engineering clusters in Germany and Japan. |
| Boron-Nitrogen Complex Technology Acquisition | Proprietary corrosion inhibitor platforms address multi-metal protection requirements in aluminum-titanium aerospace stack machining. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with additive R&D directors, procurement leads at aerospace tier-one suppliers, metalworking fluid compounder technical managers, and ECHA regulatory affairs specialists; alongside secondary validation through customs trade databases, SEC 10-K filings of integrated chemical companies, REACH registration dossiers, and ACC industry reports. Bottom-up volume modeling triangulated against top-down market sizing across product type, technology, application, and end-user industry dimensions.
Across the analysis window, the forecasting framework applied segment-specific CAGRs derived from machinery fabrication customer conversion rates to synthetic formulations, aerospace production build schedules, and regulatory phase-out timelines for restricted chemistries. Modeled dimensions included extreme pressure agent versus corrosion inhibitor product tiers, synthetic versus mineral-oil technology strata, and precision engineering versus heavy equipment end-user archetypes. Price-volume elasticity parameters incorporated specification-grade purchasing concentration effects.
Underlying assumptions cover REACH substance restriction enforcement continuity, OSHA mist exposure standard maintenance, and aerospace supply chain consolidation trajectories, with deviation risk concentrated in bio-based EP performance breakthroughs and India BIS certification pathway acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.