
 Agrochemicals Additives Market | 2026-2036
Agrochemicals Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Agrochemicals Additives Market Analysis
Aftermarket service revenue for adjuvant blending and compatibility testing is fragmenting across regional agrochemical distributors. BASF leverages its integrated additive-formulation pipeline to sustain technical service contracts with large-scale cooperatives. Corteva anchors its position through proprietary drift-reduction polymer technology that commands premium positioning in North American row-crop segments. FMC competes by extending its biological adjuvant portfolio into Latin American specialty crop markets.
Agrochemicals additives comprise surfactants, emulsifiers, stabilizers, and compatibility agents that modify the physical or chemical properties of active ingredients to improve spray deposition, rainfastness, and root uptake. These materials typically constitute 5-15% of formulated product volume yet determine field efficacy thresholds and operator safety profiles. Liquid emulsion concentrates dominate value contribution due to higher adjuvant loading requirements and precision-application compatibility with drone spraying systems. Granular fertilizer coatings represent the fastest-expanding form segment as coated urea and NPK products penetrate irrigated farming belts where leaching losses drive grower willingness to pay for controlled-release performance.
EPA registration requirements under FIFRA govern adjuvant labeling and efficacy claims in the United States, while REACH restricts certain nonylphenol ethoxylate surfactants across European formulation facilities. India's Central Insecticides Board mandates adjuvant disclosure in registered pesticide compositions, creating compliance differentiation between domestic blenders and import-dependent distributors. Stakeholders must monitor evolving residue tolerance harmonization between Codex Alimentarius and national food safety authorities to anticipate reformulation cycles and regional product registration timelines.
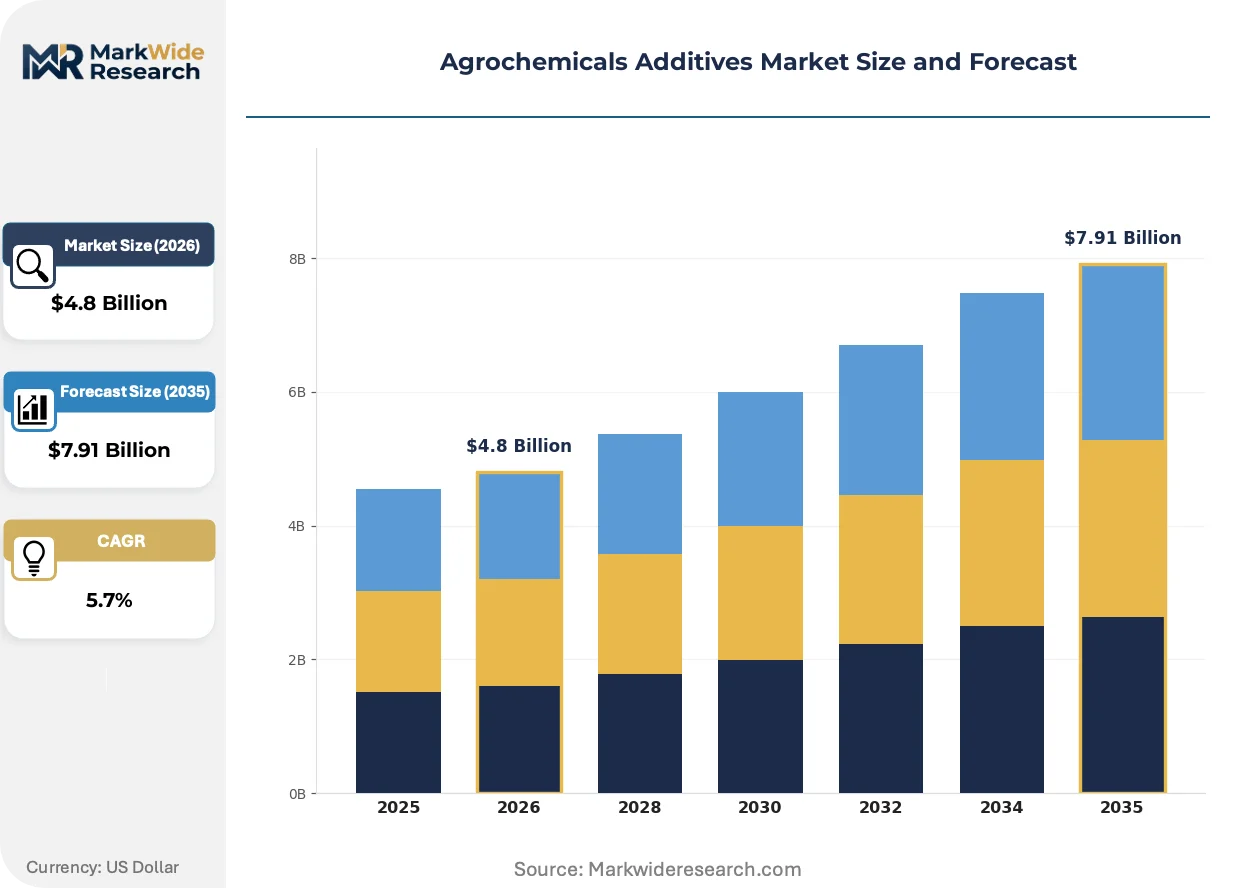
Market Dynamics
REACH and EU Green Deal mandates are compressing formulation timelines across European agrochemical plants. Specialty fertilizer coatings are capturing grower attention in Brazil's irrigated belts as leaching losses intensify nutrient efficiency requirements.
Growth Catalysts
- Controlled-Release Polymer Coatings:Specialty urea and NPK coatings penetrate Brazil's commercial farming operations where water management constraints elevate grower willingness to pay for leaching reduction.
- Drone Application Compatibility:Liquid emulsion concentrates with precision-spray adjuvant loadings align with aerial spraying adoption across India's Gujarat and Maharashtra extension program zones.
- Biodegradable Surfactant Mandates:EU Green Deal compliance requirements redirect European formulation investments away from legacy petroleum-based adjuvant systems toward bio-based alternatives.
Market Restraints
- Petrochemical Feedstock Volatility:Surfactant and emulsifier input costs fluctuate with ethylene oxide and fatty alcohol supply disruptions, compressing blender margins during price spike periods.
- Registration Timeline Friction:EPA FIFRA adjuvant efficacy claim substantiation and India's Central Insecticides Board disclosure mandates extend product commercialization cycles by 18-36 months.
- Biological Adjuvant Substitution:Microbial inoculant and bio-stimulant formulations reduce synthetic adjuvant loadings in Latin American specialty crop segments where organic certification premiums apply.
Strategic Opportunities
- Aftermarket Technical Services:Adjuvant blending and compatibility testing contracts fragment across regional distributors, creating service revenue pools beyond commodity additive sales.
- Micronutrient-Enriched Formulations:India's state-level agricultural extension programs in Gujarat and Maharashtra promote micronutrient additive uptake, opening formulation partnerships with domestic blenders.
- Drift-Reduction Polymer Premium Positioning:North American row-crop segments reward polymer-based deposition aids that reduce off-target movement liability under increasingly stringent buffer zone regulations.
Industry Challenges
- Formulation Chemist Talent Scarcity:Expertise in surfactant-polymer compatibility and stability testing concentrates among aging technical specialists at legacy agrochemical houses.
- Legacy Equipment Integration:Granular coating lines at established fertilizer plants require capital retrofitting to handle controlled-release polymer application rates, delaying coated product scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agrochemicals Additives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Herbicides, Insecticides, Fungicides Application: Agricultural, Horticultural, Turf Management, Public Health Form: Liquid, Granular, Powder, Emulsion Packaging Type: Bulk, Drum, Sack, Sachet |
| Companies Covered | Syngenta Crop Protection, Bayer Crop Science, BASF, Corteva, UPL, FMC, ADAMA, Sumitomo Chemical, Dow AgroSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agrochemicals Additives Market Emerging Trajectories
Biopolymer and bio-surfactant chemistries are displacing petroleum-derived adjuvant systems as regulatory pressure intensifies across multiple jurisdictions. Formulation houses must rebuild technical service capabilities around compatibility testing and precision-application optimization.
Microencapsulation technology for active ingredient stabilization is rendering obsolete conventional tank-mix adjuvant protocols in high-value specialty crop segments. California and Florida vegetable growers adopt pre-formulated microencapsulated products to reduce field mixing errors and operator exposure. This shift compresses aftermarket adjuvant blending revenue pools while elevating registration and stability testing burdens on formulation providers.
REACH restrictions on nonylphenol ethoxylate surfactants force European formulation facilities to reformulate legacy emulsifier systems before 2026 compliance deadlines. Industrial consequence includes accelerated bio-based surfactant qualification programs and supply contract renegotiations with ethoxylate suppliers. German and French agrochemical plants face the steepest transition costs due to concentrated legacy NPE capacity.
Large-scale agricultural cooperatives in North America consolidate procurement of adjuvant-inclusive formulated products, displacing independent tank-mix additive purchases. Technical service contracts now bundle compatibility testing, drift reduction validation, and application equipment calibration. This concentration is most visible in Iowa and Illinois corn-soy belts where cooperative purchasing power exceeds individual grower scale.
Agrochemicals Additives Market Segmentation
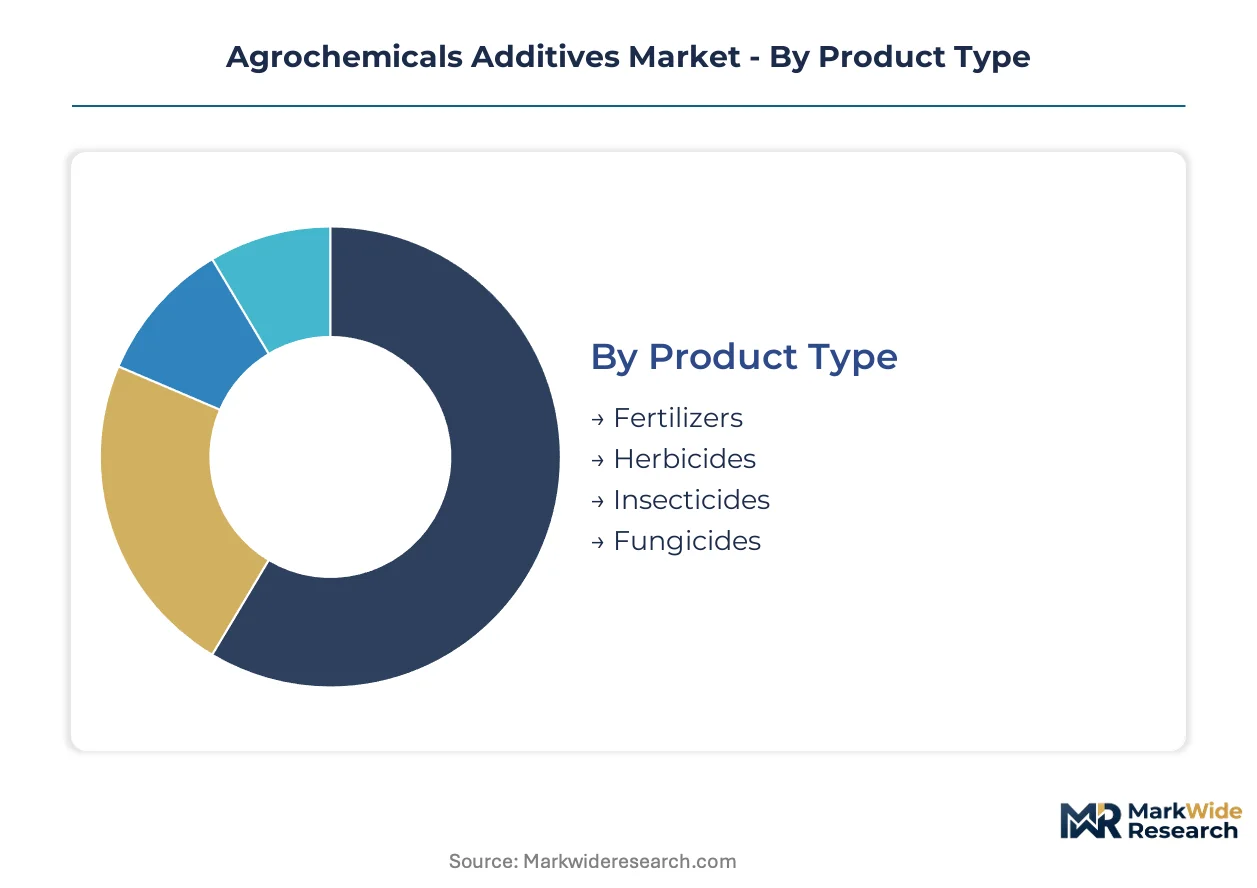
Additive formulation requirements diverge sharply across crop protection and plant nutrition applications. Each segment category reflects distinct technical specifications, regulatory exposure, and supply chain configurations that determine blender margin structures and distributor procurement patterns.
Product Type:
Use-case spectrum spans soil fertility management through crop protection chemistry, with additive loadings varying by active ingredient solubility and application method.
- Fertilizers:Controlled-release polymer coatings and micronutrient carriers modify nitrogen, phosphorus, and potassium delivery profiles. Specialty urea coatings penetrate Brazil's irrigated farming belts where leaching losses intensify grower willingness to pay for nutrient efficiency.
- Herbicides:Surfactant packages enhance cuticle penetration and translocation of systemic active ingredients. Glyphosate and dicamba formulations in North American row-crop segments drive demand for drift-reduction polymers and volatility suppressants under tightening buffer zone regulations.
- Insecticides:Emulsifier systems stabilize pyrethroid and neonicotinoid concentrates for foliar spray applications. Compatibility agents prevent antagonism when tank-mixed with fungicides in India's Gujarat and Maharashtra extension program zones.
- Fungicides:Stabilizer additives protect azole and strobilurin actives from hydrolysis in aqueous formulations. Rainfastness promoters gain priority in European cereal protection programs facing unpredictable precipitation patterns.
Established volume favors fertilizers; emerging adoption favors herbicide drift-reduction technologies.
Application:
Customer type determines formulation complexity, with commercial agriculture demanding precision-application compatibility and amenity sectors prioritizing operator safety profiles.
- Agricultural:Large-scale mechanized operations require adjuvant systems optimized for aerial and ground-rig spraying equipment. India's state-level extension programs in Gujarat and Maharashtra concentrate procurement of micronutrient-enriched formulations for cash crop intensification.
- Horticultural:High-value fruit and vegetable production demands microencapsulated active stabilization and reduced-residue surfactant packages. California and Florida growers adopt pre-formulated products to eliminate field mixing errors and operator exposure risks.
- Turf Management:Golf course and sports field maintenance prioritizes aesthetic performance and rapid re-entry intervals. Biodegradable surfactant mandates under EU Green Deal compliance redirect European formulation investments toward bio-based adjuvant alternatives.
- Public Health:Vector control programs require ultra-low volume spray compatibility and thermal fogging stability. EPA FIFRA registration timelines for adjuvant efficacy claims extend product commercialization cycles by 18-36 months in this segment.
Agricultural procurement dominates tonnage; horticultural applications command the steepest premium pricing tiers.
Form:
Volume concentration tracks equipment compatibility, with liquid systems aligning to precision-application infrastructure and granular forms addressing nutrient leaching constraints.
- Liquid:Emulsion concentrates with precision-spray adjuvant loadings align with drone spraying adoption across extension program zones. Higher adjuvant loading requirements and compatibility with aerial application systems sustain value contribution leadership.
- Granular:Fertilizer coatings represent the steepest expansion trajectory as coated urea and NPK products penetrate irrigated farming belts. Controlled-release polymer application rates require capital retrofitting of legacy coating lines at established fertilizer plants.
- Powder:Wettable powder formulations serve markets with limited water quality and storage infrastructure. Dust suppression additives and anti-caking agents determine field efficacy and handler safety profiles.
- Emulsion:Oil-in-water systems stabilize hydrophobic actives for foliar uptake optimization. REACH restrictions on nonylphenol ethoxylate surfactants force European facilities to reformulate legacy emulsifier systems before compliance deadlines.
Liquid emulsion concentrates anchor current revenue pools; granular coatings are climbing the fastest on nutrient efficiency demand.
Packaging Type:
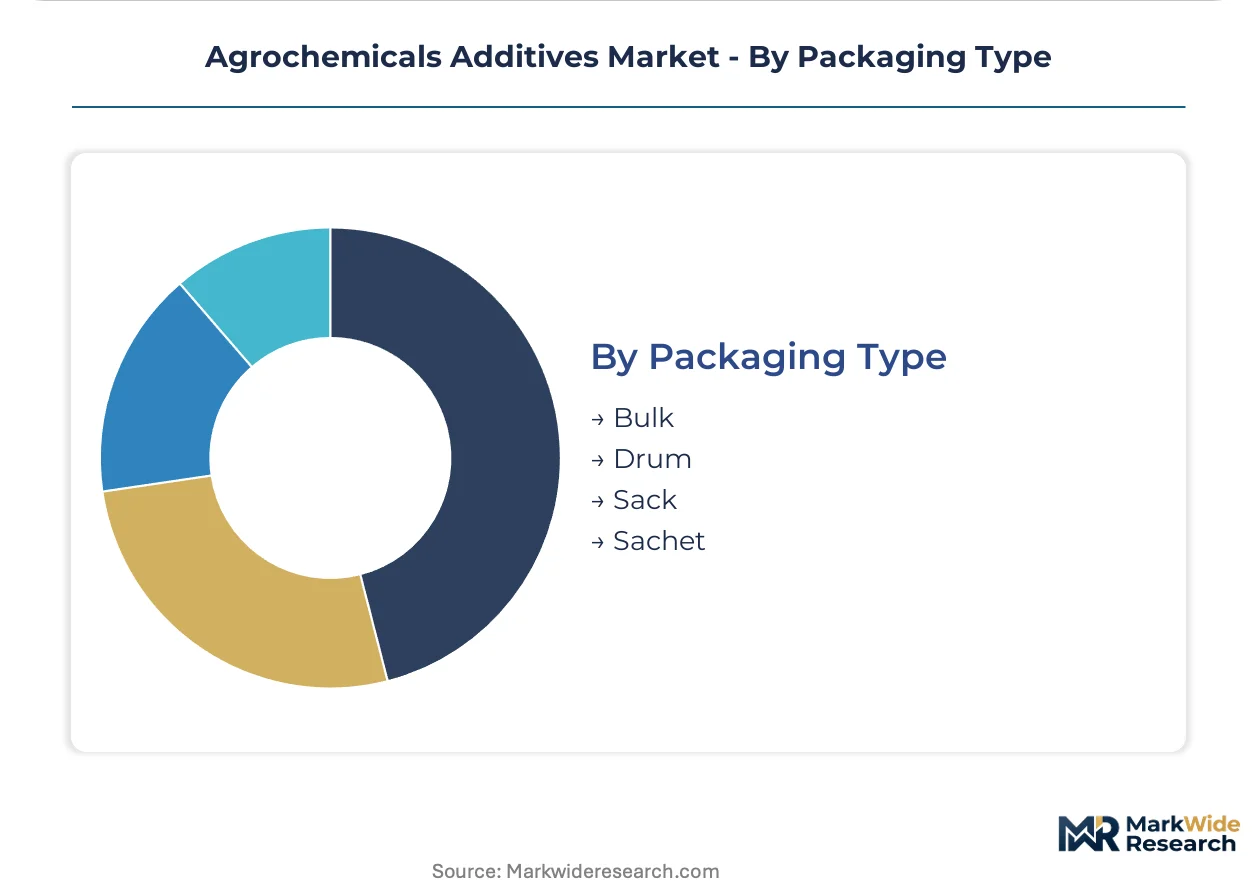
Supply concentration dictates packaging economics, with bulk systems serving integrated cooperatives and unitized formats reaching fragmented retail channels.
- Bulk:Tanker and tote deliveries supply large-scale agricultural cooperatives in Iowa and Illinois corn-soy belts. Cooperative procurement consolidation displaces independent tank-mix additive purchases in these concentration zones.
- Drum:Standard 200-liter containers serve commercial applicators and mid-scale farming operations. Returnable drum programs reduce packaging waste compliance costs under extended producer responsibility frameworks.
- Sack:Multi-wall paper and woven polypropylene bags deliver granular products to regional blending facilities. India's Central Insecticides Board mandates adjuvant disclosure in registered pesticide compositions, differentiating domestic sack-format blenders from import-dependent distributors.
- Sachet:Single-use packets enable precise dosing for smallholder applications and specialty crop segments. Unitization elevates per-kilogram packaging costs while reducing field mixing error rates.
Bulk shipments capture cooperative volume; sachet formats penetrate smallholder access markets with highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity clusters in Germany, the United States, Brazil, India, and China, with each jurisdiction imposing distinct registration and environmental compliance burdens on additive suppliers.
United States
Large-scale agricultural cooperatives in Iowa and Illinois consolidate procurement of adjuvant-inclusive formulated products, displacing independent tank-mix additive purchases. EPA FIFRA registration requirements govern adjuvant labeling and efficacy claims, extending product commercialization cycles by 18-36 months. The Corn Belt states anchor drift-reduction polymer demand as buffer zone regulations tighten for dicamba and glyphosate applications.
Germany
German agrochemical plants face steep transition costs as REACH restrictions on nonylphenol ethoxylate surfactants force reformulation of legacy emulsifier systems before 2026 deadlines. The EU Green Deal redirects formulation investments toward biodegradable adjuvant alternatives across German and French facilities. Industrial concentration in the Rhine-Ruhr and Ludwigshafen chemical corridors accelerates bio-based surfactant qualification programs.
Brazil
Specialty fertilizer coatings penetrate Brazil's irrigated farming belts as leaching losses intensify nutrient efficiency requirements among commercial growers. ANVISA and the Ministry of Agriculture regulate adjuvant disclosure in registered pesticide compositions. São Paulo and Mato Grosso states concentrate demand for controlled-release polymer coatings on urea and NPK products in precision-irrigated soybean and sugarcane operations.
India
State-level agricultural extension programs in Gujarat and Maharashtra promote micronutrient-enriched agrochemical applications, concentrating demand in these western states. The Central Insecticides Board mandates adjuvant disclosure in registered pesticide compositions, creating compliance differentiation between domestic blenders and import-dependent distributors. Drone spraying adoption across extension program zones drives liquid emulsion concentrate uptake with precision-spray adjuvant loadings.
China
Domestic formulation houses rebuild technical service capabilities around compatibility testing and precision-application optimization to serve mechanized farming operations. The Ministry of Agriculture and Rural Affairs and national GB standards govern additive quality and environmental release profiles. Shandong and Jiangsu provinces concentrate surfactant and emulsifier manufacturing capacity, though feedstock volatility in ethylene oxide and fatty alcohol supply chains compresses blender margins.
Agrochemicals Additives Market Vendor Landscape
Integrated agrochemical conglomerates and specialized additive suppliers split the market between formulation-integrated service bundles and commodity surfactant sales. Three strategic archetypes dominate: multinational crop science majors with captive additive pipelines, regional blenders serving domestic registration requirements, and bio-based specialty chemical entrants capturing regulatory-driven substitution demand. Competitive moves center on backward integration into polymer coating capacity and technology licensing partnerships for microencapsulation systems.
Among the integrated majors, BASF, Corteva, and FMC occupy distinct positioning vectors. BASF exemplifies the formulation-integrated archetype through technical service contracts with large-scale cooperatives. Corteva anchors premium positioning in North American row-crop segments through proprietary drift-reduction polymer technology. FMC represents biological adjuvant extension strategies into Latin American specialty crop markets. These three companies illustrate how scale, specialization, and geographic focus segment competitive terrain without exhaustive market share claims.
| Leading Market Players |
|---|
| Syngenta Crop Protection |
| Bayer Crop Science |
| BASF |
| Corteva |
| UPL |
| FMC |
| ADAMA |
| Sumitomo Chemical |
| Dow AgroSciences |
| Others |
Supply Flow & Price Mechanics
Shandong and Jiangsu provinces anchor surfactant and emulsifier manufacturing capacity, concentrating input cost leverage among ethylene oxide suppliers and compressing blender margins when fatty alcohol feedstock volatility spikes. This geographic clustering of specialty chemical production translates directly into pricing power asymmetries between integrated formulators and regional distributors.
Pricing Analysis
REACH and EU Green Deal mandates dictate the pricing tier structure across European formulation facilities, separating biodegradable bio-surfactant formulations from legacy petroleum-based systems. Premium-mid-economy pricing differentiation tracks certification grade and volume scale, with large-scale agricultural cooperatives in Iowa and Illinois extracting favorable contract terms through consolidated procurement. Cost compression in standard-tier emulsion concentrates is intensifying because ethylene oxide supply disruptions compress blender margins. Smallholder-facing sachet formats exhibit highest price sensitivity, while horticultural microencapsulated products command least elasticity due to error-reduction premiums.
Supply Chain Analysis
Export-control regimes on advanced polymer coating technologies limit controlled-release formulation knowledge transfers, constraining capacity buildout in emerging manufacturing hubs. Supply concentrates in Germany, the United States, and China, with Shandong and Jiangsu provinces feeding surfactant inputs to downstream blenders. Raw material dependencies center on ethylene oxide, fatty alcohols, and specialty polyurethanes for coating applications. Single-source vulnerability runs through concentrated ethoxylate supplier networks in the Rhine-Ruhr chemical corridor. Distribution runs through bulk tanker deliveries to agricultural cooperatives and drum formats for commercial applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone spraying adoption and biodegradable surfactant mandates constitute dual technological-regulatory inflections reshaping competitive positioning in agrochemical additives. Formulators must recalibrate R&D allocation and technical service capabilities to capture value from precision-application infrastructure and compliance-driven substitution cycles.
For Market Incumbents: Entrench formulation-integrated service bundles by deepening backward integration into polymer coating capacity and locking technical service contracts with large-scale cooperatives. Biological adjuvant substitution in Latin American specialty crop segments threatens synthetic additive loadings, requiring accelerated bio-surfactant qualification programs to defend margin position. For New Entrants and Emerging Players: India's Gujarat and Maharashtra extension program zones offer the most penetrable white-space for micronutrient-enriched formulation partnerships with domestic blenders. Granular fertilizer coating retrofits at legacy plants present equipment-as-a-service entry angles, while sachet format precision-dosing for smallholders enables premium per-kilogram margin capture without cooperative scale requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bio-based specialty chemical entrants capturing regulatory-driven substitution demand across multiple jurisdictions. Long-term viability hinges on backward integration into polymer coating capacity and microencapsulation technology licensing portfolios. The signal to watch is drift-reduction polymer validation rates under tightening EPA buffer zone regulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Coating Capacity | Captures margin from controlled-release urea demand in Brazil's irrigated belts. |
| Biodegradable Surfactant Qualification Programs | Secures REACH compliance ahead of 2026 deadlines for German and French facilities. |
| Technical Service Contract Bundling | Locks cooperative procurement consolidation in Iowa and Illinois corn-soy belts. |
| Microencapsulation Technology Licensing | Addresses California and Florida grower demand for pre-formulated error reduction. |
| Drone Application Compatibility Certification | Aligns liquid emulsion concentrates with Maharashtra and Gujarat extension program zones. |
Methodological Framework
Operator-level perspectives from formulation chemists, agricultural cooperative procurement managers, regional distributor technical service heads, and fertilizer plant coating line engineers anchored the qualitative base. Primary interview data combined with secondary validation from EPA FIFRA registration filings, REACH compliance disclosures, India Central Insecticides Board composition mandates, and customs trade data for ethylene oxide and fatty alcohol flows. Bottom-up volume modeling across product type, application, form, and packaging segments triangulated against top-down value estimates.
Scenario-bracketing around regulatory compliance timelines and feedstock volatility bands informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type spectrum from fertilizers through crop protection chemistry, application tier from agricultural through horticultural and public health, form factor from liquid emulsion through granular coating, and packaging format from bulk cooperative delivery through sachet unitization. CAGRs derived from elasticity-adjusted adoption curves for controlled-release polymer penetration and bio-surfactant substitution rates. Forecast inputs incorporated drone spraying infrastructure deployment in Indian extension zones and buffer zone regulatory tightening in North American row-crop segments.
Practitioners should monitor REACH enforcement intensity, EPA dicamba registration revisions, and ethylene oxide supply disruption frequency for early signals. Forecasts reflect assumptions on regulatory timeline adherence and cooperative procurement consolidation trajectories. Material shifts in EU Green Deal implementation speed or biological adjuvant efficacy validation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Surface Modifiers Market
Additives
Automotive Additives Market
Additives
Asia-Pacific Water Enhancer Market
Additives
Europe Anti-Caking Market
Additives
Packaging Coating Additives Market
Additives
Sodium Potassium Tartrate Market
Additives
Grease Additives Market
Additives
Antiblock Agents Market
Additives
Anti-Wear Additives Market
Additives
Triazine UV Absorber Market
Additives
Global Performance Additives Market
Additives
Asia Pacific Plastic Additives Market
Additives
Low Melt Inclusions Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Global Cement and Concrete Additives Market