
 Friction Modifier Additives Market | 2026-2036
Friction Modifier Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Friction Modifier Additives Market Analysis
The performance gap between premium synthetic friction modifiers and commodity mineral-oil blends is broadening as OEMs tighten fuel-economy specifications. Afton Chemical Corporation leverages its integrated additive technology platform to serve tier-1 lubricant blenders with customized organic friction modifier packages. BASF SE anchors its position through backward integration into molybdenum dithiocarbamate chemistry, controlling raw material quality for high-performance automotive applications. The Lubrizol Corporation specializes in multi-functional additive systems that combine friction reduction with wear protection, differentiating its portfolio from single-purpose competitors.
Friction modifier additives are surface-active chemical compounds—typically organo-molybdenum complexes, fatty acid esters, or functionalized polymers—formulated at treat rates of 0.1–3.0 weight percent to reduce boundary friction between sliding metal surfaces in lubricated systems. Their primary industrial purpose is to improve mechanical efficiency, reduce fuel consumption, and extend equipment life in engines, transmissions, and hydraulic systems. Organic additives dominate automotive lubricant formulations due to compatibility with Group II/III base oils and favorable cost-performance ratios, while synthetic polymers command premium positioning in industrial gear and hydraulic fluids where thermal stability requirements exceed 150°C. Biodegradable additives represent the fastest-growing structural category, driven by marine and offshore applications where MARPOL regulations restrict conventional lubricant discharge.
EPA fuel-economy standards and the EU F-Gas Regulation shape product development trajectories by mandating lower viscosities and reduced volatile organic compound emissions from lubricant formulations. REACH chemical authorization requirements in Europe and FDA indirect food-contact regulations for incidental lubricant exposure in food-processing equipment constrain raw material selection and supplier qualification processes. Stakeholders must monitor evolving OEM factory-fill specifications and regulatory timelines for per- and polyfluoroalkyl substance restrictions that could disqualify certain fluorinated friction modifier chemistries from future formulations.
Market Dynamics
Automotive OEMs are tightening factory-fill specifications for low-viscosity engine oils, forcing additive suppliers to reformulate friction modifier packages that maintain boundary lubrication performance at thinner film thicknesses. This specification compression is redrawing competitive boundaries between integrated additive houses and specialty chemical suppliers.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:US automakers must achieve fleet-wide efficiency targets, driving procurement of organo-molybdenum friction modifiers in 0W-16 and 0W-8 grade lubricants.
- Marine sector biodegradability requirements:MARPOL Annex VI implementation in EU ports is accelerating substitution of mineral-oil friction modifiers with ester-based biodegradable alternatives in stern tube and thruster applications.
- Germany's KBA emissions enforcement:The national automotive regulator's real-driving emissions testing protocol directly influences additive treat rate specifications for European OEM factory fills.
Market Restraints
- Molybdenum disulfide supply concentration:Over 70% of refined molybdenum feedstock originates from Chilean and Chinese mining operations, exposing formulators to concentrate price volatility and export quota disruptions.
- REACH authorization timelines:ECHA's substance evaluation process for boron-containing friction modifiers extends 18-36 months, freezing formulation choices for European lubricant blenders awaiting regulatory clarity.
- Polymer friction modifier thermal ceiling:Functionalized polymethacrylates degrade above 165°C, excluding their use in high-performance dual-clutch transmission fluids where organo-molybdenum complexes dominate.
Strategic Opportunities
- India's BS-VI Phase II implementation:The country's tightened particulate matter limits for commercial vehicles create first-mover positioning for additive suppliers offering combined friction modifier-detergent packages compatible with lower SAPS formulations.
- Wind turbine gearbox life extension:5+ MW offshore turbines require synthetic friction modifier systems with 15-year oil drain intervals, opening premium positioning for polyalphaolefin-compatible polymer architectures.
- EU Green Deal sustainable chemistry incentives:The European Commission's funding mechanisms for bio-based industrial processes accelerate R&D timelines for plant-derived fatty acid ester friction modifiers with equivalent performance to petrochemical benchmarks.
Industry Challenges
- Tribochemistry expertise scarcity:Formulation chemists capable of optimizing boundary film formation across mixed lubrication regimes command premium compensation, constraining mid-tier additive houses' product development velocity.
- OEM qualification cycle compression:Volkswagen, BMW, and Mercedes-Benz have compressed factory-fill approval timelines from 48 months to 24 months, forcing simultaneous bench testing, field trials, and regulatory documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Friction Modifier Additives Market |
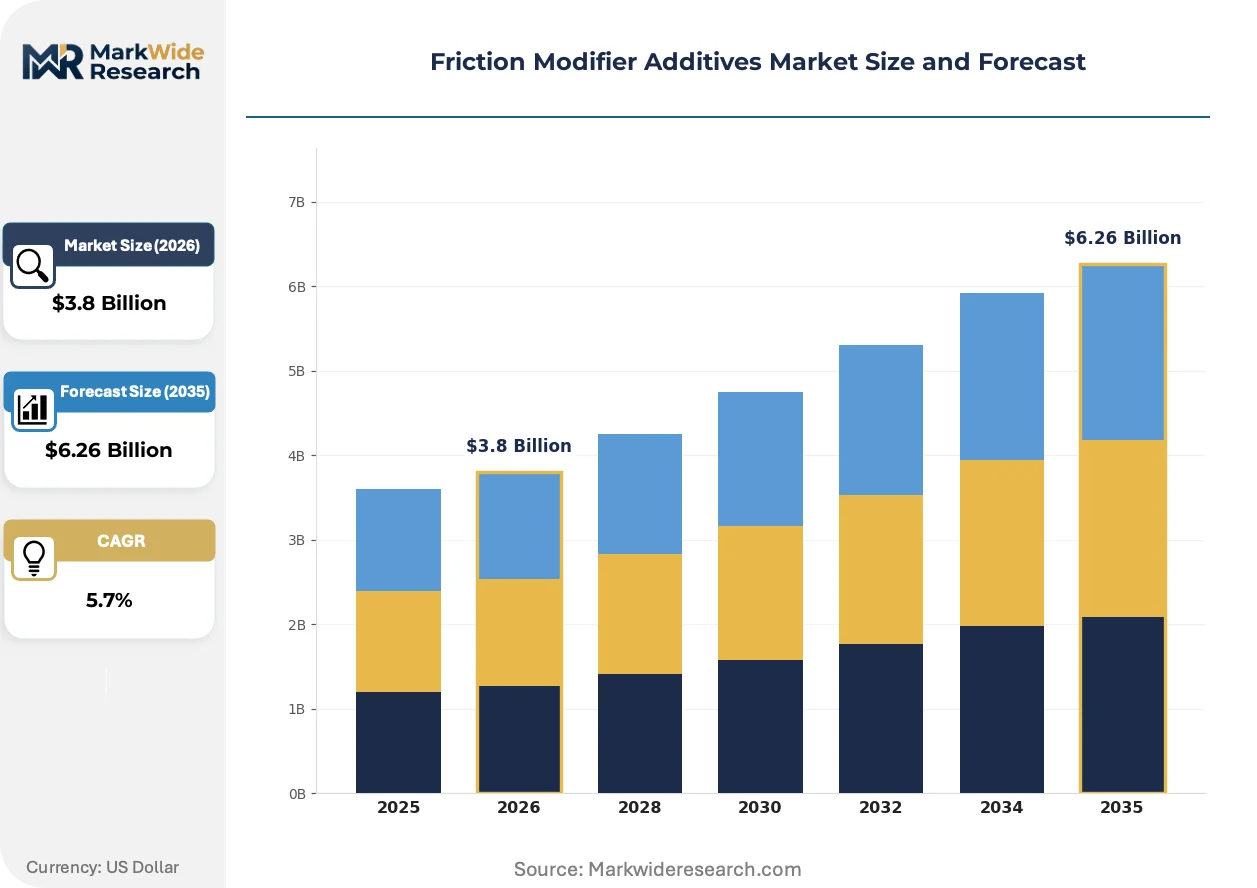
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Additives, Inorganic Additives, Synthetic Polymers, Biodegradable Additives Application: Automotive Lubricants, Industrial Lubricants, Marine Applications, Heavy Machinery End User: OEMs, Tier-1 Suppliers, Manufacturing Plants, Oil & Gas Industry Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Afton Chemical Corporation, BASF SE, The Lubrizol Corporation, Infineum International Limited, Croda International Plc, Chevron Oronite Company, Evonik Industries AG, Royal Dutch Shell PLC, ExxonMobil Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Friction Modifier Additives Market Emerging Trajectories
Friction modifier technology is bifurcating along thermal stability and environmental compliance axes, with synthetic polymer architectures displacing organometallic complexes in high-temperature industrial applications while biodegradable esters capture marine and food-contact lubricant segments.
Functionalized ionic liquid friction modifiers are rewriting the performance envelope for electric vehicle reduction gear fluids. These non-volatile salts form tenacious boundary films at contact pressures exceeding 2 GPa, enabling automakers to eliminate copper corrosion inhibitors from e-axle lubricants. BMW and Hyundai Motor Group have qualified ionic liquid-containing formulations for their dedicated EV platforms since 2023.
REACH restriction proposals for per- and polyfluoroalkyl substances are forcing reformulation of fluorinated polymer friction modifiers used in aerospace hydraulic fluids. The ECHA consultation process, initiated in 2023, threatens to disqualify PTFE-based additives from future aviation lubricant specifications. Safran and Rolls-Royce are accelerating qualification of ceramic nanoparticle alternatives for next-generation engine oil systems.
Integrated lubricant service contracts are consolidating procurement decision-making at fleet operators and industrial asset managers. Shell Lubricant Solutions and Castrol have shifted from product sales to total cost of ownership agreements covering oil condition monitoring, additive replenishment, and drain interval optimization. This model compresses supplier rosters to 2-3 qualified partners per major fleet, privileging additive houses with captive base oil supply and technical service infrastructure. The transformation is most advanced in German commercial vehicle fleets operating under TÜV-monitored maintenance protocols.
Friction Modifier Additives Market Segmentation
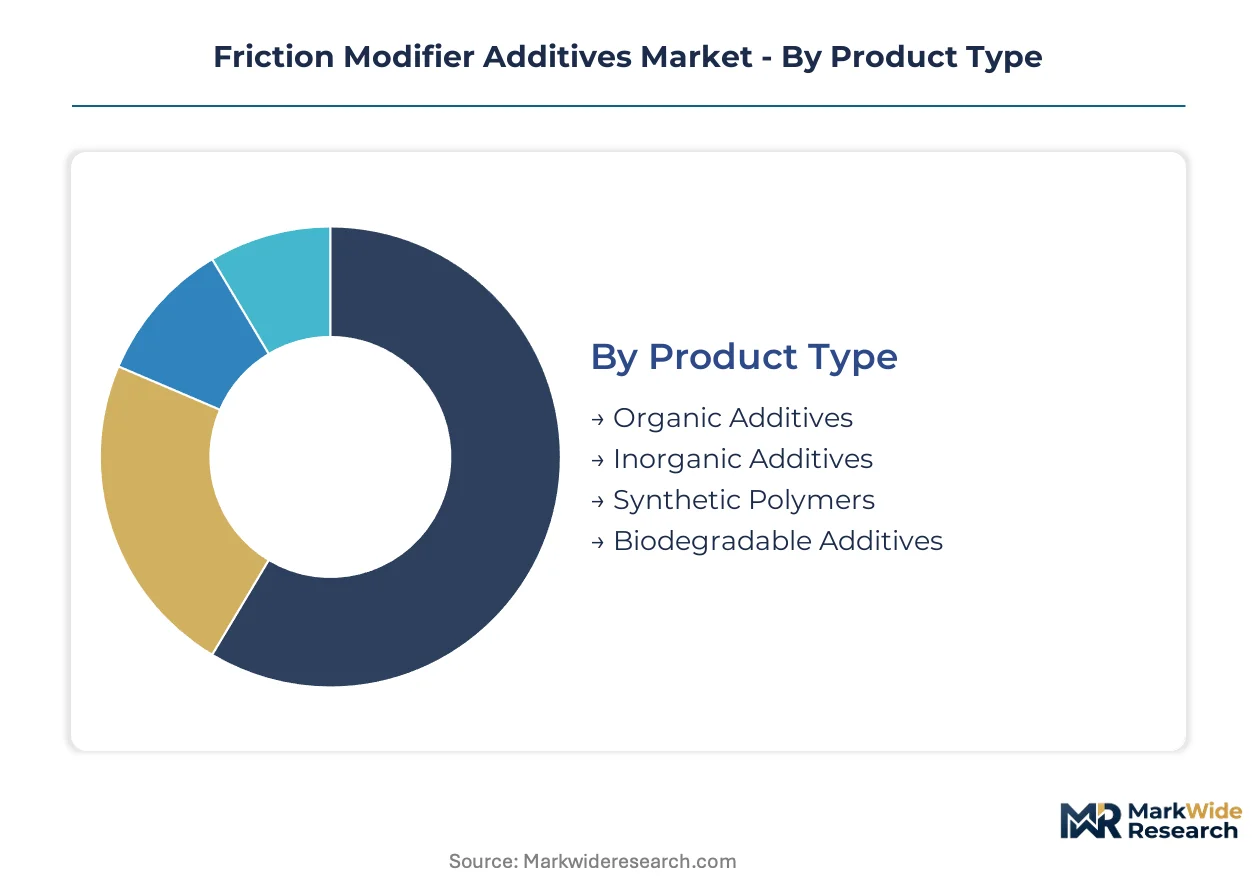
Friction modifier additives serve divergent performance requirements across automotive, industrial, and marine lubricant systems. Segmentation reveals how formulation chemistry, application severity, and procurement channel structure create distinct competitive arenas with varying margin profiles and technical barriers.
Product Type:
Buyers in this category differentiate primarily by thermal ceiling requirements and regulatory compliance obligations rather than unit cost.
- Organic Additives:Fatty acid esters and amide derivatives formulated at 0.5-2.0 weight percent in Group II/III base oils. Automotive OEMs in Germany specify these for factory-fill 0W-16 engine oils to meet KBA emissions testing protocols while avoiding heavy-metal regulatory scrutiny.
- Inorganic Additives:Organo-molybdenum complexes and graphite dispersions delivering extreme-pressure film formation. Demand concentrates in dual-clutch transmission fluids where contact pressures exceed 1.5 GPa, though Chilean molybdenum concentrate volatility constrains formulator procurement security.
- Synthetic Polymers:Functionalized polymethacrylates and polyalphaolefin-compatible architectures for industrial gear systems. These command premium positioning in 5+ MW offshore wind turbine applications requiring 15-year drain intervals.
- Biodegradable Additives:Ester-based formulations derived from vegetable oil feedstocks. MARPOL Annex VI enforcement in EU ports is accelerating substitution from mineral-oil alternatives in stern tube lubricants.
Organic additives lead volumes today; biodegradable additives are gaining share fastest.
Application:
Application segmentation tracks lubricant system operating temperature, film thickness requirements, and drain interval specifications.
- Automotive Lubricants:Engine oils, transmission fluids, and axle lubricants where EPA Corporate Average Fuel Economy mandates drive 0W-8 and 0W-16 grade proliferation. Factory-fill qualification cycles have compressed from 48 to 24 months at Volkswagen, BMW, and Mercedes-Benz.
- Industrial Lubricants:Hydraulic fluids, compressor oils, and metalworking lubricants for manufacturing asset managers. Integrated service contracts from Shell Lubricant Solutions and Castrol are consolidating procurement to 2-3 qualified suppliers per major fleet.
- Marine Applications:Stern tube oils, thruster lubricants, and deck machinery fluids subject to MARPOL discharge restrictions. Ester-based biodegradable friction modifiers are displacing mineral-oil formulations in EU port operations.
- Heavy Machinery:Mining equipment, construction vehicles, and agricultural machinery operating in severe dust and moisture conditions. These applications prioritize wear protection co-formulation with detergents over pure friction reduction.
Automotive lubricants dominate revenue contribution; marine applications show the steepest expansion trajectory.
End User:
End user segmentation reflects procurement sophistication, specification authority, and technical service requirements.
- OEMs:Vehicle and equipment manufacturers with factory-fill specification authority. BMW and Hyundai Motor Group have qualified ionic liquid friction modifiers for dedicated EV platforms since 2023.
- Tier-1 Suppliers:Lubricant blenders and component manufacturers serving aftermarket and service-fill demand. These buyers require customized additive packages from integrated technology platforms like Afton Chemical's.
- Manufacturing Plants:Industrial asset managers optimizing total cost of ownership through oil condition monitoring and drain interval extension. TÜV-monitored maintenance protocols in German commercial vehicle fleets exemplify this procurement model.
- Oil & Gas Industry:Upstream and midstream operators requiring drilling lubricants and pipeline drag reducers. Thermal stability above 150°C distinguishes specifications in this segment.
OEMs anchor premium pricing power; manufacturing plants are expanding procurement volume most rapidly.
Distribution Channel:
Channel structure determines technical service intensity, inventory carrying cost allocation, and buyer relationship depth.
- Direct Sales:Integrated additive houses serving tier-1 lubricant blenders with formulation support and regulatory documentation. BASF SE leverages backward integration into molybdenum dithiocarbamate chemistry to secure direct relationships.
- Distributors:Regional chemical distributors stocking standard friction modifier packages for mid-tier blenders and compounders. These intermediaries absorb inventory risk but add margin layers.
- Online Retail:E-commerce platforms serving small-volume buyers and specialty lubricant formulators. Digital procurement is expanding in aftermarket segments with standardized treat rate specifications.
- Others:Cooperative purchasing arrangements and consortium buying for fleet operators. These channels consolidate demand to negotiate volume-based pricing.
Direct sales capture the highest margin transactions; online retail is expanding fastest among small-volume buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized tribochemistry talent concentrates in Germany's Rhine-Main and Upper Bavaria regions, where additive formulation expertise developed alongside automotive OEM technical centers. This workforce density shapes procurement patterns and regulatory influence across European lubricant markets.
United States
EPA Corporate Average Fuel Economy mandates drive organo-molybdenum demand in 0W-16 and 0W-8 grade lubricants. The agency's fuel-economy standards directly determine factory-fill specifications at Detroit automakers. Houston anchors petrochemical additive production, with integrated lubricant service contracts consolidating procurement for commercial vehicle fleets operating under TÜV-monitored protocols.
Germany
KBA real-driving emissions testing protocols influence additive treat rate specifications for European OEM factory fills. REACH chemical authorization requirements constrain raw material selection for boron-containing friction modifiers. The Stuttgart and Munich automotive clusters compress qualification timelines from 48 to 24 months, forcing simultaneous bench testing and field trials.
China
MIIT fuel-economy standards for domestic automakers expand procurement of low-friction engine oils. The country's dual carbon goals accelerate substitution toward organic and polymer-based friction modifiers. Shanghai and Yangtze River Delta lubricant blenders face concentrate price volatility from Chilean and Chinese molybdenum mining operations.
India
BS-VI Phase II particulate matter limits for commercial vehicles create demand for combined friction modifier-detergent packages compatible with lower SAPS formulations. BIS standards increasingly reference EU emissions testing methodologies. The Pune and Chennai automotive corridors attract first-mover additive suppliers establishing technical service infrastructure.
Japan
METI energy-efficiency standards for industrial machinery prioritize thermal stability above 150°C in hydraulic fluid specifications. JIS lubricant standards incorporate friction reduction performance metrics adopted by regional OEMs. The Chubu region around Nagoya maintains formulation expertise serving Toyota and Honda factory-fill requirements.
Friction Modifier Additives Market Vendor Landscape
Top-tier vendors anchor integrated additive technology platforms, while specialty chemical suppliers occupy formulation niches requiring tribochemistry expertise. The market structure reflects consolidation around backward-integrated molybdenum chemistry houses and diversified petrochemical majors. Three archetypes dominate: integrated additive technology platforms, petrochemical majors with captive base oil supply, and specialty chemical suppliers focused on single-purpose friction modifiers. Competitive moves center on qualification cycle compression and geographic expansion into India's BS-VI implementation window.
Within the integrated technology tier, Afton Chemical Corporation and The Lubrizol Corporation exemplify platform-based suppliers serving tier-1 lubricant blenders with customized organic friction modifier packages. BASF SE anchors the backward-integrated archetype through in-house production of molybdenum dithiocarbamate chemistry. These three positions illustrate how control over raw material quality and multi-functional formulation capabilities separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Afton Chemical Corporation |
| BASF SE |
| The Lubrizol Corporation |
| Infineum International Limited |
| Croda International Plc |
| Chevron Oronite Company |
| Evonik Industries AG |
| Royal Dutch Shell PLC |
| ExxonMobil Chemical Company |
| Others |
Supply Flow & Price Mechanics
A performance gap between premium synthetic friction modifiers and commodity mineral-oil blends manifests in both pricing stratification and supply chain configuration. OEM factory-fill specifications for 0W-16 and 0W-8 grade lubricants command premium positioning through organo-molybdenum complexes and functionalized polymers, while aftermarket blenders compete on cost with fatty acid ester formulations sourced through regional distributors.
Pricing Analysis
Bundled service contracts from Shell Lubricant Solutions and Castrol separate pricing from pure product transactions, embedding oil condition monitoring and drain interval optimization into multi-year agreements. Price differentiation stems from thermal stability certification above 150°C and OEM qualification status at Volkswagen, BMW, or Mercedes-Benz. Cost compression in commodity organic additives is intensifying because Chilean molybdenum concentrate volatility squeezes formulator margins. Tier-1 lubricant blenders show least price sensitivity due to factory-fill specification authority, while small-volume aftermarket buyers negotiate aggressively on standard treat rate packages.
Supply Chain Analysis
Organo-molybdenum chemistry rests on refined concentrate feedstock from Chilean and Chinese mining operations, with over seventy percent of global supply originating from these two sources. Fatty acid ester inputs draw from vegetable oil processors in Malaysia and Indonesia, while functionalized polymethacrylate production centers on German and US specialty chemical manufacturers. Single-source vulnerability in molybdenum disulfide exposes formulators to export quota disruptions and concentrate price spikes. Distribution runs through direct sales channels for integrated additive houses serving qualified tier-1 blenders, with regional distributors absorbing inventory risk for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as automotive OEM procurement shifts decisively toward low-friction engine oils meeting corporate fuel-economy mandates. Specification compression at thinner film thicknesses rewards suppliers with tribochemistry expertise and backward-integrated raw material control.
For Market Incumbents: Anchor factory-fill relationships by compressing qualification timelines from 24 months toward 18 months through simultaneous bench testing and field trial execution. Invest in captive molybdenum dithiocarbamate production to secure supply continuity against Chilean concentrate volatility. Defend against ionic liquid substitution in electric vehicle reduction gear fluids by accelerating multi-functional additive system development.
For New Entrants and Emerging Players: Enter via biodegradable ester formulations for marine stern tube applications where MARPOL Annex VI enforcement creates specification discontinuity. Target India's BS-VI Phase II implementation window with combined friction modifier-detergent packages compatible with lower SAPS formulations. Pursue technical service partnerships with Pune and Chennai automotive corridor blenders lacking in-house tribochemistry capability.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier additive houses lack integrated technology platforms and face compressed OEM qualification cycles. Long-term viability favors suppliers with backward integration into organometallic chemistry and multi-functional formulation expertise. Acquisition targets include specialty chemical suppliers with ionic liquid friction modifier patents and established EV platform qualifications. Watch ECHA restriction timelines for per- and polyfluoroalkyl substances as inflection indicator for fluorinated polymer displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molybdenum Chemistry | Captive supply of organo-molybdenum feedstock insulates formulators from Chilean concentrate volatility. |
| Biodegradable Ester Formulation Development | Plant-derived friction modifiers capture marine applications under MARPOL Annex VI enforcement. |
| Ionic Liquid Qualification for EV Platforms | BMW and Hyundai Motor Group factory-fill approvals establish premium positioning in electric vehicle lubricants. |
| Integrated Service Contract Expansion | Shell Lubricant Solutions and Castrol consolidate procurement to 2-3 qualified suppliers per major fleet. |
| REACH Compliance Documentation Investment | ECHA authorization timelines for boron-containing additives require 18-36 month regulatory preparation. |
Methodological Framework
Coverage spans Germany, the United States, China, India, and Japan, with primary inputs from each market cluster. The analysis combines structured interviews with lubricant formulators, OEM procurement specialists, additive R&D directors, and marine classification society technical officers with secondary validation from customs trade data, SEC 10-K filings, ECHA substance evaluation databases, and automotive production registries. Bottom-up segmentation modeling triangulates against top-down demand aggregation from regional lubricant consumption trends.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. The analytical framework models friction modifier demand by product type (organic, inorganic, synthetic polymer, biodegradable), application severity (automotive, industrial, marine, heavy machinery), and procurement channel structure (direct sales, distributor, integrated service contract). CAGRs derive from segment-level growth rate blending weighted by base-year revenue contribution. Industry-specific inputs include OEM factory-fill specification timelines, REACH authorization stage gates, and molybdenum concentrate price elasticity assumptions.
The model holds under stable regulatory enforcement trajectories and intact OEM qualification cycles; deviation in ECHA restriction timelines or KBA emissions protocol amendments would shift additive chemistry substitution rates. Forecasts reflect documented assumptions regarding treat rate specifications, base oil compatibility requirements, and regional lubricant demand growth. A small set of named triggers warrants ongoing watch: Chilean mining export policy changes, ionic liquid patent expiration schedules, and EU Green Deal sustainable chemistry funding disbursement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Coalescing Agent Market
Additives
Global Packaging Additives Market
Additives
North America Pectin Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Global Asphalt Additives Market
Additives
Indonesia Feed Additives Market
Additives
Guanylic Acid Market
Additives
United Kingdom Feed Additives Market
Additives
Global Isononanoic Acid Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Ammonium Acetate Market
Additives
Global Metal Scavenging Agents Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Crystal Growth Modifier Market
Additives
Global Peptone Market
Additives
Polyoxyethylene Sorbitan Monostearate Market