
 Cyclooxygenase 2 Inhibitor Market | 2026-2036
Cyclooxygenase 2 Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclooxygenase 2 Inhibitor Market Insights
CE marking under the EU Medical Device Regulation is bifurcating competitive access for drug-device combination products incorporating COX-2 inhibitors. Pfizer leverages its manufacturing scale to sustain supply commitments across North American and European hospital networks. Novartis anchors its position through specialized rheumatology distribution channels that reach outpatient clinics directly. Bayer competes in the topical delivery segment where dermatological and musculoskeletal crossover applications create niche prescribing opportunities.
Cyclooxygenase 2 inhibitors constitute a selective prostaglandin synthesis suppression class engineered to block the COX-2 isoenzyme while sparing COX-1 mediated gastric protection, with celecoxib demonstrating approximately 375-fold selectivity for COX-2 over COX-1 in vitro assays. These compounds serve primarily to reduce inflammation and pain in osteoarthritis, rheumatoid arthritis, and acute postoperative settings where gastrointestinal tolerability concerns limit non-selective NSAID use. The oral delivery mode dominates prescription volumes due to patient familiarity and cost efficiency, though the injectable segment captures perioperative hospital formulary placements where rapid onset analgesia commands premium positioning. Celecoxib maintains the largest revenue share among product types while etoricoxib growth accelerates in markets where regulatory approvals remain active.
FDA cardiovascular risk evaluation frameworks and EMA periodic safety update report requirements shape clinical development timelines and label expansion strategies for COX-2 inhibitor developers. The US pharmacovigilance system mandates Risk Evaluation and Mitigation Strategies for newer entrants, while Japan's PMDA applies distinct hepatic metabolism assessment protocols that filter market access. India's CDSCO and China's NMPA impose local bioequivalence study requirements that extend registration timelines for multinational sponsors. Stakeholders must monitor evolving cardiovascular outcome study demands and biosimilar erosion timelines to calibrate portfolio prioritization and geographic resource allocation.
Market Dynamics
FDA cardiovascular safety mandates and EMA pharmacovigilance requirements are compressing clinical trial timelines while elevating post-market surveillance costs for COX-2 inhibitor developers. These regulatory pressures favor sponsors with established risk-management infrastructure and hospital network relationships.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States exhibit expanding osteoarthritis patient pools where gastrointestinal-sparing analgesia protocols prioritize COX-2 selective agents over traditional NSAIDs.
- REACH Compliance Pathways:European chemical registration frameworks for active pharmaceutical ingredients are streamlining cross-border manufacturing approvals, reducing redundant toxicology burdens for multi-site production networks.
- Perioperative Formulary Expansion:Hospital anesthesia departments are integrating injectable COX-2 inhibitors into enhanced recovery after surgery protocols, creating institutional prescribing momentum beyond outpatient settings.
Market Restraints
- Cardiovascular Outcome Study Costs:FDA-mandated long-term safety trials impose capital intensity that filters mid-cap developers from label expansion pursuits.
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for celecoxib and etoricoxib concentrates in Chinese and Indian chemical parks, exposing sponsors to geopolitical trade friction and environmental compliance disruptions.
- Generic Erosion Velocity:Patent expirations and abbreviated new drug application approvals for celecoxib are compressing branded pricing power in mature markets.
Strategic Opportunities
- Topical Delivery White Space:Dermatological and musculoskeletal crossover applications for localized COX-2 inhibition remain underdeveloped relative to oral and injectable segments.
- India's CDSCO Registration Pathways:Local bioequivalence study requirements, while extending timelines, create first-mover advantages for sponsors establishing domestic manufacturing partnerships.
- Drug-Device Convergence:Transdermal patch technologies and implantable depot formulations are converging with selective COX-2 chemistry to enable sustained-release pain management.
Industry Challenges
- Pharmacovigilance Talent Scarcity:Risk Evaluation and Mitigation Strategy implementation requires specialized epidemiologists and signal detection analysts that compete for limited qualified personnel across therapeutic areas.
- Legacy System Integration:Post-market surveillance data aggregation from heterogeneous hospital electronic health record systems complicates real-world evidence generation for cardiovascular safety monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclooxygenase 2 Inhibitor Market |
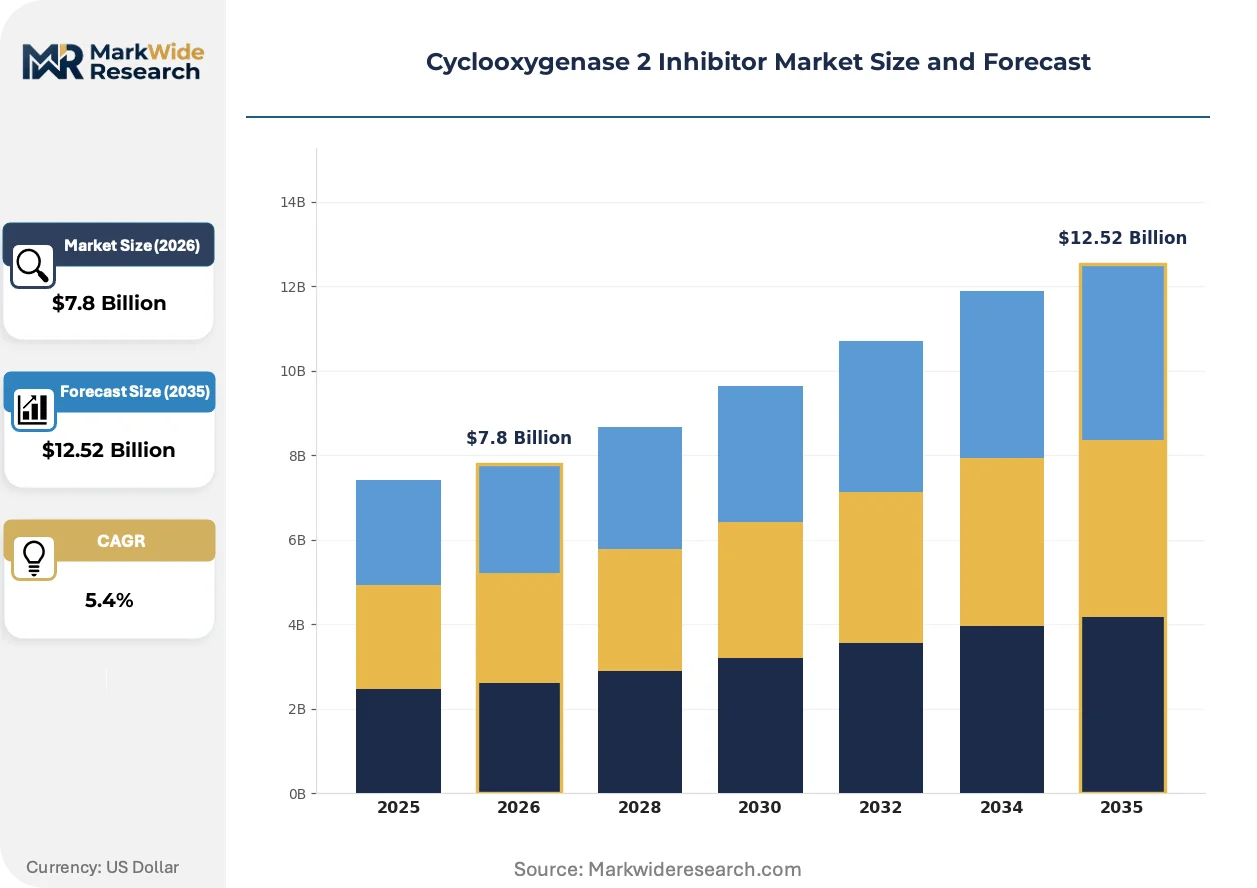
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Celecoxib, Rofecoxib, Etoricoxib, Parecoxib Therapy Area: Chronic Pain, Osteoarthritis, Rheumatoid Arthritis, Inflammation End User: Hospitals, Outpatient Clinics, Specialty Pharmacies, Homecare Providers Delivery Mode: Oral, Injectable, Transdermal, Topical |
| Companies Covered | Pfizer, Novartis, Bayer, Merck, AbbVie, Cadila Pharmaceuticals, GlaxoSmithKline, Jiangsu Hengrui Pharma, Sabinsa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclooxygenase 2 Inhibitor Market Trends and Innovations
COX-2 inhibitor development is pivoting toward delivery modality differentiation and real-world evidence generation as competitive moats. Formulation innovation and regulatory data science capabilities are separating viable sponsors from marginalized participants.
Long-acting injectable depot formulations are displacing conventional oral dosing in perioperative and chronic pain settings where adherence variability undermines efficacy. Academic medical centers in the United States and Japan are piloting these platforms for total joint replacement protocols. The technology is displacing hospital reliance on multimodal opioid-sparing regimens that require complex nursing coordination.
EMA's periodic safety update report requirements and FDA's Sentinel Initiative are mandating active surveillance infrastructure that smaller sponsors cannot replicate without contract research organization partnerships. This regulatory density is consolidating development activity among entities with integrated pharmacovigilance capabilities. The European Union and United States markets are responding with label restriction strategies that emphasize prescriber education over outright withdrawal.
Hospital procurement committees are unbundling analgesic purchasing from anesthesia service contracts, creating direct formulary competition between COX-2 inhibitors and regional nerve block alternatives. This disintermediation places greater weight on pharmacoeconomic modeling and readmission risk reduction claims. The shift is most visible in German and Japanese hospital networks where diagnosis-related group reimbursement incentives align with length-of-stay compression goals.
Cyclooxygenase 2 Inhibitor Market Segmentation
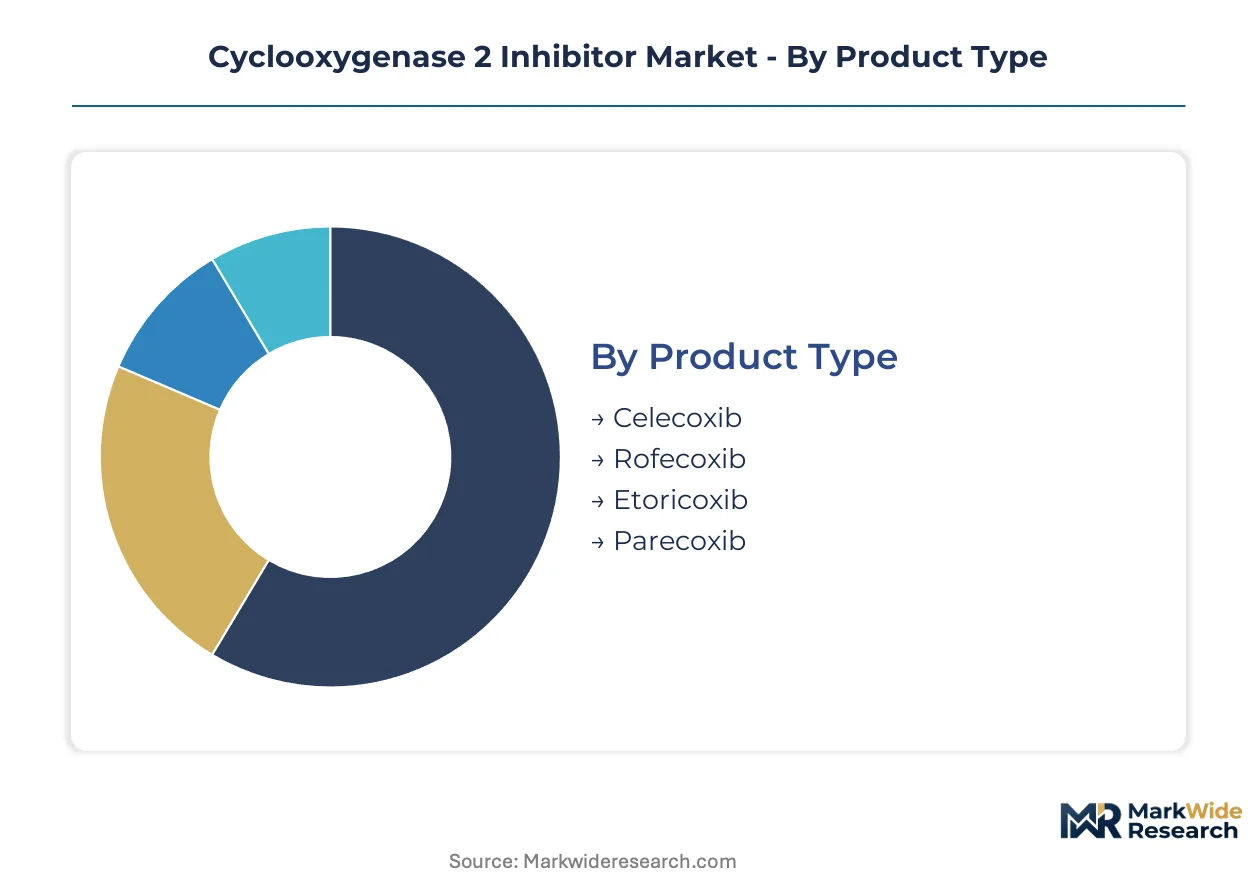
Segmentation in the COX-2 inhibitor market determines channel strategy, pricing architecture, and regulatory pathway selection. Product chemistry, therapy focus, delivery technology, and care setting each create distinct margin profiles and competitive barriers.
Product Type:
Hospital formulary placement and outpatient prescription flows concentrate differently across this category, with perioperative procurement committees favoring specific molecular profiles.
- Celecoxib:The sulfonamide-derived COX-2 selective agent delivers approximately 375-fold enzyme selectivity in vitro. Demand concentrates in United States outpatient settings where established reimbursement codes and prescriber familiarity sustain volume leadership despite generic erosion.
- Etoricoxib:A biphenyl derivative with extended half-life enabling once-daily dosing protocols. Expansion concentrates in markets where EMA-approved indications remain active, particularly German and Italian rheumatology practices seeking cardiovascular risk stratification alternatives.
- Rofecoxib:Withdrawn from major markets following cardiovascular safety signals; residual presence limited to specific regulatory exemptions and legacy inventory protocols.
- Parecoxib:Prodrug formulation optimized for injectable perioperative applications where rapid onset and opioid-sparing properties command institutional formulary placement.
Celecoxib dominates installed base. Etoricoxib is where expansion concentrates.
Therapy Area:
Reimbursement intensity and treatment duration vary sharply across indications, creating tiered margin structures from acute postoperative protocols to chronic maintenance regimens.
- Osteoarthritis:Degenerative joint disease affecting weight-bearing articulations drives sustained prescription volumes among aging demographics. German and Japanese orthopedic practices prioritize GI-sparing protocols for long-term analgesia.
- Rheumatoid Arthritis:Autoimmune inflammatory joint destruction requiring combination therapy with DMARDs. United States rheumatology clinics integrate selective COX-2 agents into step-care algorithms before biologic escalation.
- Chronic Pain:Persistent nociceptive and neuropathic conditions extending beyond specific structural pathology. Multidisciplinary pain centers in academic medical centers employ these agents within multimodal regimens.
- Inflammation:Broad anti-inflammatory applications including acute soft tissue injury and postoperative edema control. Hospital emergency departments favor rapid-onset formulations for discharge protocols.
Osteoarthritis anchors volume share. Rheumatoid Arthritis exhibits the steepest expansion trajectory as biologic-sparing protocols gain protocol adoption.
End User:
Procurement authority and price sensitivity diverge across care settings, with institutional buyers leveraging formulary control against dispersed retail prescription economics.
- Hospitals:Integrated delivery networks and standalone acute care facilities with anesthesia department formulary authority. Perioperative enhanced recovery protocols in Japanese and German hospital systems drive injectable segment procurement.
- Outpatient Clinics:Community rheumatology and orthopedic practices with direct prescriber influence over pharmacy benefit manager tier placement. United States clinic consolidation is shifting volume toward affiliated specialty pharmacies.
- Specialty Pharmacies:Limited distribution channels handling prior authorization complexity and patient adherence monitoring for high-cost chronic therapies.
- Homecare Providers:Infusion and nursing services supporting post-discharge injectable administration for complex chronic pain patients.
Hospitals dominate injectable volume. Outpatient Clinics is where oral formulation expansion concentrates.
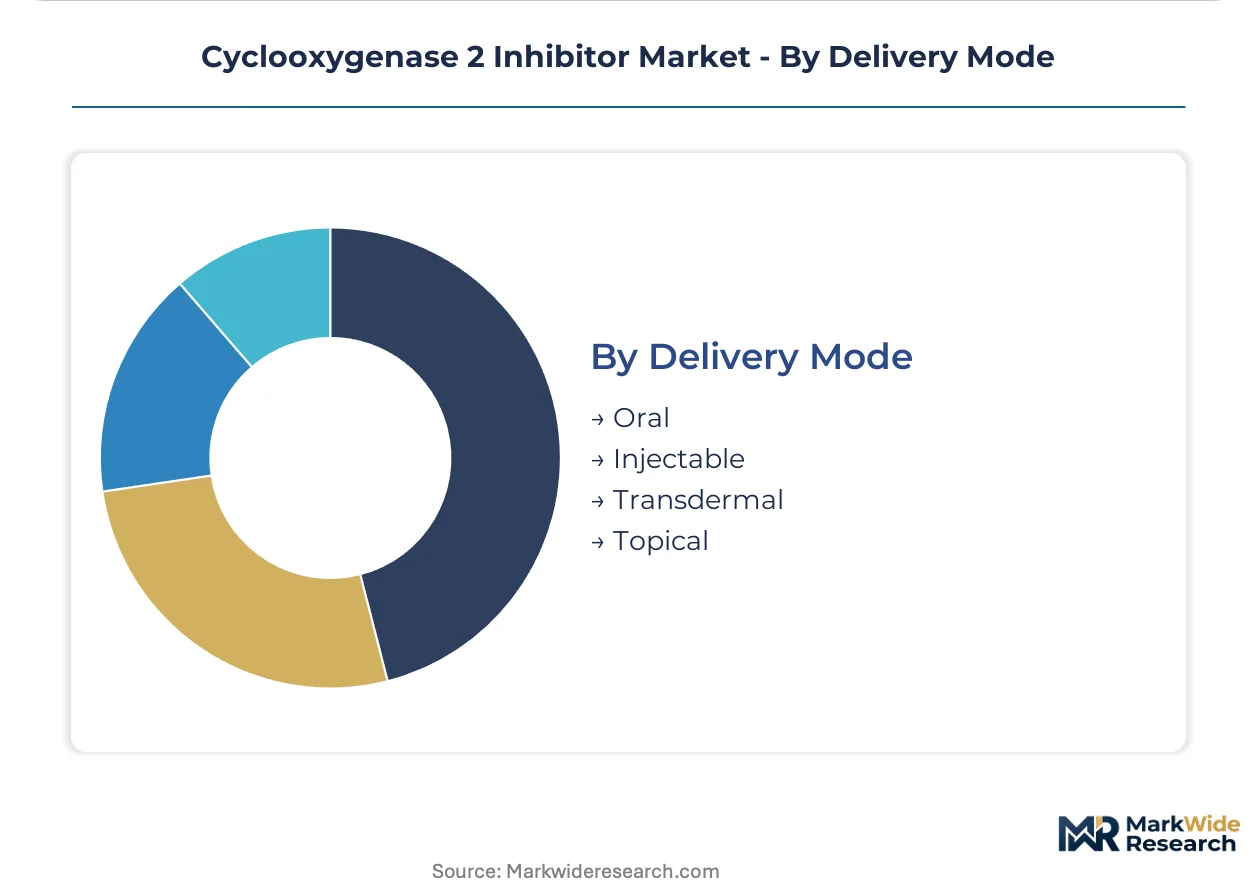
Delivery Mode:
Manufacturing complexity and bioequivalence requirements create divergent competitive moats, with advanced formulations filtering generic entrants.
- Oral:Capsule and tablet formulations dominating prescription economics through manufacturing scale and patient self-administration convenience. Cost compression from abbreviated new drug applications intensifies pricing pressure.
- Injectable:Intravenous and intramuscular formulations capturing perioperative settings where rapid plasma concentration achievement supports opioid-reduction goals. German diagnosis-related group reimbursement incentives align with length-of-stay compression.
- Transdermal:Patch-based sustained release technologies enabling steady-state plasma levels without hepatic first-pass metabolism. Development pipelines concentrate in Japanese pharmaceutical research corridors.
- Topical:Localized dermal and mucosal applications for musculoskeletal and dermatological crossover indications. Bayer's dermatology channel presence creates niche prescribing access.
Oral formulations dominate installed base. Injectable is where perioperative protocol adoption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement pathway maturity and cardiovascular risk stratification protocols are diverging prescription economics across major pharmaceutical markets. FDA REMS requirements and EMA pharmacovigilance mandates are filtering market access for newer entrants while sustaining established agent volumes in aging populations.
United States
Medicare Part D formularies and commercial pharmacy benefit manager tier placement sustain celecoxib prescription dominance despite generic erosion. FDA Risk Evaluation and Mitigation Strategies impose signal detection infrastructure costs that favor sponsors with integrated pharmacovigilance capabilities. The Boston-Cambridge corridor anchors real-world evidence generation partnerships between academic medical centers and COX-2 developers.
Germany
Diagnosis-related group reimbursement incentives align hospital anesthesia departments with enhanced recovery after surgery protocols incorporating injectable COX-2 inhibitors. EMA periodic safety update report requirements and REACH chemical registration frameworks streamline cross-border manufacturing approvals for active pharmaceutical ingredients. The Rhine-Main pharmaceutical cluster concentrates formulation development and perioperative drug-device combination research.
Japan
PMDA hepatic metabolism assessment protocols and geriatric dosing guidelines shape label expansion strategies for COX-2 selective agents in osteoarthritis patients. METI industrial policy supports long-acting injectable depot development through academic-industry partnerships in chronic pain management. The Kanto region's rheumatology practice networks drive outpatient prescription volumes for gastrointestinal-sparing analgesia protocols.
India
CDSCO local bioequivalence study requirements and domestic manufacturing partnership mandates extend registration timelines while creating first-mover advantages for sponsors establishing local production. The PLI scheme for pharmaceuticals incentivizes active pharmaceutical ingredient manufacturing scale-up in Gujarat and Maharashtra chemical parks. Hyderabad's contract research organization corridor concentrates clinical trial execution and pharmacovigilance outsourcing capabilities.
China
NMPA cardiovascular outcome study expectations and local clinical data requirements filter multinational sponsor market access for COX-2 inhibitors. National reimbursement drug list negotiations compress branded pricing while expanding patient access to selective NSAID therapy. The Yangtze River Delta's pharmaceutical manufacturing base concentrates celecoxib and etoricoxib active pharmaceutical ingredient production for regional and export markets.
Cyclooxygenase 2 Inhibitor Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established risk-management infrastructure and hospital network relationships. The competitive structure concentrates around entities with integrated pharmacovigilance capabilities and perioperative formulary access. Two strategic archetypes dominate: multinational incumbents leveraging manufacturing scale across North American and European distribution channels, and regional specialists exploiting local regulatory knowledge and domestic manufacturing partnerships. Consolidation through strategic partnerships and geographic expansion into emerging markets with localized bioequivalence requirements represent the dominant competitive moves.
Among multinational pharmaceutical conglomerates, Pfizer, Novartis, and Bayer occupy positions exemplifying divergent competitive vectors within the COX-2 inhibitor space. Pfizer represents the manufacturing scale archetype sustaining supply commitments across hospital networks. Novartis exemplifies specialized therapeutic channel concentration reaching outpatient rheumatology clinics directly. Bayer occupies a position in topical delivery segments where dermatological and musculoskeletal crossover applications create niche prescribing access. These three entities anchor the competitive landscape through distinct route-to-market strategies rather than homogeneous product positioning.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| Bayer |
| Merck |
| AbbVie |
| Cadila Pharmaceuticals |
| GlaxoSmithKline |
| Jiangsu Hengrui Pharma |
| Sabinsa Corporation |
| Others |
Pricing and Supply Chain Analysis
Injectable parecoxib's displacement of oral celecoxib in perioperative protocols is simultaneously redrawing API sourcing maps from Gujarat chemical parks toward sterile formulation facilities in Germany and Japan, while compressing margin structures across oral generic tiers.
Pricing Analysis
Certification level creates the primary spread, with FDA-validated GMP batches commanding premium positioning against Indian CDSCO-registered equivalents. Three-tier pricing structure separates innovator brands from authorized generics and commodity API suppliers. Pricing pressure stems from abbreviated new drug application approvals for celecoxib that erode branded pricing power. Hospital procurement committees exhibit lowest price sensitivity due to diagnosis-related group reimbursement alignment, while retail pharmacy channels face intense cost compression.
Supply Chain Analysis
Active pharmaceutical ingredient manufacturing concentrates in Chinese Yangtze River Delta chemical parks and Indian Gujarat pharmaceutical corridors. Celecoxib and etoricoxib production draws from 4-methylacetophenone and trifluoromethyl-substituted intermediates sourced through multi-step synthesis. Single-source vulnerability persists for specialized chiral catalysts required in enantioselective manufacturing. Distribution runs through hospital group purchasing organizations in North America and direct-to-pharmacy networks in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital network consolidation in the United States and Germany, where integrated delivery networks now command formulary authority over dispersed outpatient clinics.
For Market Incumbents: Fortify pharmacovigilance infrastructure against FDA Risk Evaluation and Mitigation Strategy compliance costs that filter mid-cap competitors. Deepen backward integration into API manufacturing through partnerships in Indian PLI scheme corridors. Secure perioperative formulary placement through enhanced recovery after surgery protocol sponsorships that lock out generic substitution.
For New Entrants and Emerging Players: CDSCO fast-track registration for topical delivery formats offers first-mover positioning in dermatological-musculoskeletal crossover applications. Target German outpatient rheumatology clinics where etoricoxib growth accelerates and prescriber relationships remain fragmented. Pursue drug-device combination pathways under EU Medical Device Regulation to differentiate from commodity oral formulations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Indian API manufacturers seeking formulation-forward integration. Long-term viability hinges on cardiovascular outcome study capabilities that sustain label expansion in regulated markets. Monitor EMA periodic safety update report filing patterns as early indicator of sponsor pharmacovigilance maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacovigilance Infrastructure Investment | FDA REMS compliance creates defensible moat against mid-cap generic entrants lacking epidemiology capabilities. |
| Perioperative Formulary Partnership | German diagnosis-related group incentives align hospital anesthesia departments with injectable COX-2 adoption. |
| API Manufacturing Scale-Up | Indian PLI scheme subsidies in Gujarat chemical parks reduce cost base for celecoxib and etoricoxib production. |
| Topical Delivery Development | Dermatological channel access through musculoskeletal crossover indications opens prescriber relationships outside rheumatology. |
| Real-World Evidence Generation | Academic medical center partnerships in Boston-Cambridge corridor support label expansion through FDA Sentinel Initiative data. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads, hospital formulary directors, pharmaceutical procurement managers, and pharmacovigilance specialists; and secondary validation through FDA filings, EMA periodic safety update reports, ClinicalTrials.gov records, and national reimbursement drug list databases. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical market audits.
Across the analysis window, the forecasting framework modeled segmentation by product chemistry, therapy area, delivery mode, and care setting. CAGRs derived from patient population epidemiology, patent expiration timelines, and regulatory approval pathway velocity. Inputs included PMDA hepatic metabolism assessment protocols and CDSCO bioequivalence study requirement changes.
Underlying assumptions cover cardiovascular outcome study completion rates and API supply chain stability, with deviation risk concentrated in geopolitical trade friction affecting Chinese chemical park operations. Practitioners should keep alternative scenarios live as EMA pharmacovigilance mandates and FDA REMS requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market