
 Chelating Agents Market | 2026-2036
Chelating Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Chelating Agents Market Analysis
The capital-intensity divergence between integrated petrochemical producers and specialty chemical specialists is reorganizing competitive tiers in chelating agents. Nouryon leverages its integrated ethylene amine chain to control feedstock costs for EDTA derivatives. Dow anchors North American supply through scale advantages in ethylene oxide-based chelant chemistry. Mitsubishi Chemical Corporation differentiates via proprietary organometallic complexes serving semiconductor wafer cleaning applications.
Chelating agents are coordination compounds containing multidentate ligands that form stable, water-soluble complexes with metal ions through two or more donor atoms; EDTA, the most widely produced variant, binds metals at a 1:1 molar ratio across pH ranges from 4 to 10, enabling sequestration in hard water treatment and industrial cleaning. Product type dynamics favor EDTA for volume but reveal faster structural momentum in citric acid and lactic acid biobased alternatives as formulators respond to biodegradability mandates. Industrial application segmentation shows water treatment occupying the largest share while pulp and paper represents a contracting margin pool due to digitization-driven demand erosion.
EPA effluent limitation guidelines and REACH Annex XVII restrictions on persistent organic pollutants shape formulation choices, with ECHA classification of certain aminocarboxylic acids as substances of very high concern accelerating R&D into greener ligand architectures. FDA pharmaceutical-grade monographs and USP standards govern chelant purity in parenteral drug applications, creating qualification barriers for new entrants. Stakeholders must monitor regulatory divergence between EU biodegradability thresholds and emerging economy enforcement gaps when allocating capacity investments.
Market Dynamics
REACH Annex XVII restrictions on persistent organic pollutants and EPA effluent limitation guidelines are forcing formulators to abandon aminocarboxylic acid chemistries, accelerating capital redeployment toward biodegradable ligand architectures across water treatment and industrial cleaning verticals.
Growth Catalysts
- EU biodegradability mandates:REACH classification of certain chelants as substances of very high concern compels manufacturers to reformulate with citric acid and lactic acid derivatives.
- Electronics manufacturing clustering:Semiconductor wafer cleaning applications in East Asian production hubs expand consumption of high-purity organometallic complexes.
- Industrial discharge standards:China's Ministry of Ecology and Environment tightens wastewater parameters, driving substitution of phosphates with biodegradable sequestrants in textile processing.
Market Restraints
- Ethylene amine feedstock concentration:Integrated petrochemical producers control upstream supply chains, squeezing margin capture for specialty chemical specialists dependent on merchant markets.
- Technical performance gaps:Biobased alternatives exhibit inferior calcium-binding capacity across pH extremes below 4 and above 10, limiting substitution in boiler water treatment.
- Regulatory fragmentation:Divergent biodegradability thresholds between EU enforcement and emerging economy gaps complicate unified product platform strategies.
Strategic Opportunities
- Pharmaceutical-grade qualification:FDA monographs and USP standards for parenteral drug applications create defensible moats for producers achieving purity certification.
- Pulp and paper demand erosion:Digitization-driven volume contraction frees manufacturing capacity for redeployment into higher-margin semiconductor and pharmaceutical segments.
- Channel consolidation:Direct technical service relationships with municipal water utilities displace distributor intermediaries in large-volume procurement.
Industry Challenges
- Organometallic synthesis expertise:Scarce technical talent in coordination chemistry limits scale-up of proprietary complexes for electronics applications.
- Multi-jurisdiction compliance timelines:Sequential qualification across FDA, EMA, and NMPA regulatory pathways extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chelating Agents Market |
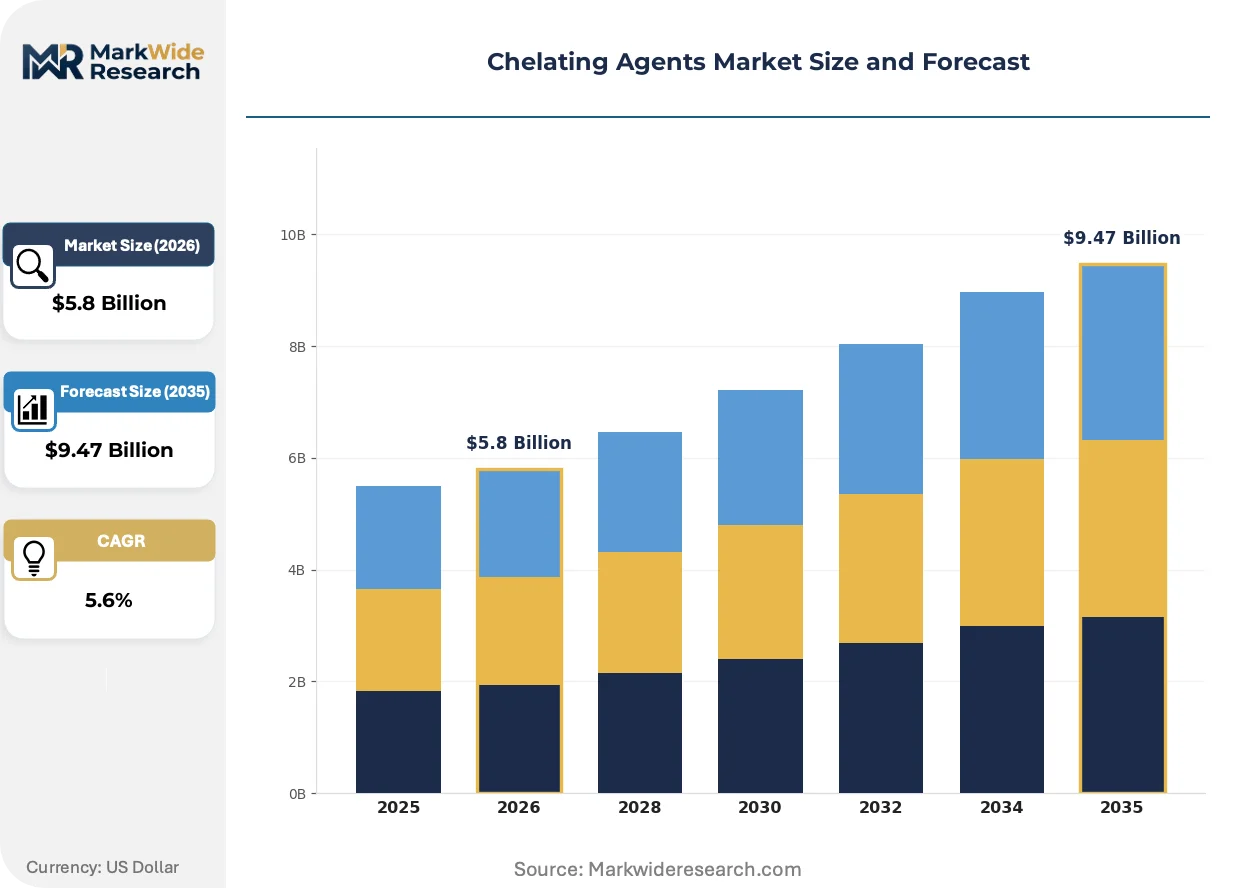
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.47 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylenediaminetetraacetic Acid, Nitrilotriacetic Acid, Lactic Acid, Citric Acid Industrial Application: Water Treatment, Agriculture, Pharmaceuticals, Pulp & Paper End User: Chemical Manufacturers, Agriculture Producers, Healthcare Facilities, Textile Industry Formulation: Liquid, Powder, Granules, Concentrate |
| Companies Covered | Nouryon, BASF SE, Dow, Lanxess AG, Mitsubishi Chemical Corporation, Kemira, AkzoNobel N.V., Nippon Shokubai Co., Ltd., Hexion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chelating Agents Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based molecular architectures as regulatory pressure compounds, while procurement patterns concentrate volume with integrated suppliers capable of delivering technical service alongside commodity chelants.
Glutamic acid N,N-diacetic acid (GLDA) and methylglycinediacetic acid (MGDA) deliver sequestration performance comparable to EDTA across neutral pH ranges. Pulp and paper mills in Nordic regions adopt these alternatives at accelerated pace to meet EU Ecolabel criteria. The technology is supplanting traditional aminocarboxylates in institutional cleaning products where biodegradability certification commands price premiums.
EPA effluent limitation guidelines under the Clean Water Act impose numeric criteria for metal discharge in industrial wastewater. Facilities operating electroplating and metal finishing processes face capital expenditure decisions on treatment infrastructure. North American metalworking fluid formulators respond by specifying chelants with demonstrated removal efficiency in biological wastewater systems.
Water treatment utilities consolidate supplier relationships around providers offering analytical services and dosing optimization software. Municipal procurement teams in Germany and the Netherlands award multi-year framework agreements bundling chemical supply with performance guarantees. This pattern concentrates volume with integrated ethylene amine producers while marginalizing pure-play distributors lacking technical service capabilities.
Chelating Agents Market Segmentation
Chelating agent specifications diverge sharply across regulatory jurisdictions, with REACH biodegradability thresholds in Europe and EPA effluent guidelines in the United States forcing distinct formulation portfolios. Segmentation strategy must align product architecture with compliance geography rather than treating specifications as fungible across borders.
Product Type:
REACH Annex XVII restrictions on persistent organic pollutants and EPA effluent limitation guidelines create divergent demand profiles for synthetic versus biobased molecular architectures.
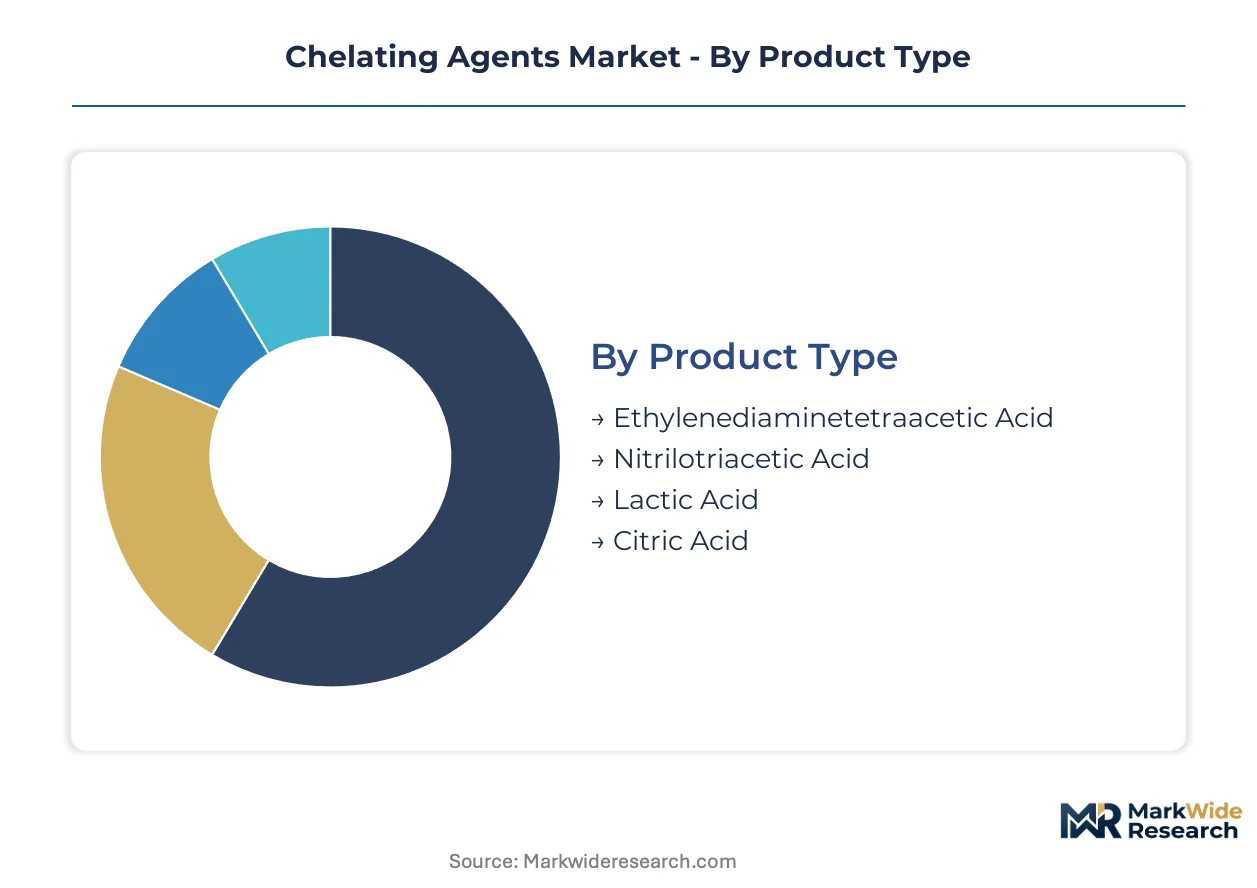
- Ethylenediaminetetraacetic Acid:The aminocarboxylic acid binds metal ions at 1:1 molar ratio across pH 4-10, serving hard water treatment and industrial cleaning applications. Water treatment utilities in Germany and the Netherlands specify EDTA for boiler feedwater conditioning despite ECHA scrutiny of its biodegradability profile.
- Citric Acid:This tricarboxylic acid delivers metal sequestration through three carboxylate donor groups with complete biodegradability under OECD 301B testing. Institutional cleaning formulators in France and Belgium adopt citric acid derivatives to secure EU Ecolabel certification for household detergents.
- Nitrilotriacetic Acid:The tridentate ligand exhibits stronger chelation at lower pH ranges than EDTA analogues.
- Lactic Acid:This alpha-hydroxy acid forms moderately stable complexes with transition metals in personal care and pharmaceutical buffer systems.
Established volume favors Ethylenediaminetetraacetic Acid; emerging adoption favors Citric Acid.
Industrial Application:
Customer procurement patterns concentrate volume with suppliers bundling analytical services and dosing optimization software alongside commodity chemicals.
- Water Treatment:Municipal utilities and industrial facilities deploy chelants for scale inhibition, metal ion control, and corrosion protection in boiler and cooling systems. China's Ministry of Ecology and Environment tightened wastewater discharge parameters, driving phosphate substitution with biodegradable sequestrants in textile processing clusters around Shaoxing and Suzhou.
- Pulp & Paper:Bleach sequencing and pitch control applications consume aminocarboxylates for metal ion management during Kraft pulping. Nordic mills in Sweden and Finland accelerate GLDA and MGDA adoption to meet EU Ecolabel criteria as digitization erodes graphic paper demand.
- Agriculture:Micronutrient delivery systems employ chelated iron, zinc, and manganese to prevent precipitation in alkaline soils.
- Pharmaceuticals:Parenteral drug formulations require USP-grade chelants for metal ion stabilization in injectable solutions.
Procurement concentration favors Water Treatment; margin expansion favors Pharmaceuticals.
End User:
Technical service requirements and qualification barriers stratify the customer base between specification-driven and price-sensitive segments.
- Chemical Manufacturers:Industrial formulators integrate chelants into metalworking fluids, cleaners, and process chemicals requiring consistent lot-to-lot quality. North American metalworking fluid producers specify chelants with demonstrated removal efficiency in biological wastewater systems to satisfy EPA Clean Water Act numeric criteria.
- Healthcare Facilities:Hospital pharmacies and compounding operations demand FDA-monographed chelants meeting USP purity standards for parenteral applications. Multi-jurisdiction qualification across FDA, EMA, and NMPA pathways extends supplier onboarding cycles.
- Agriculture Producers:Fertilizer blenders and specialty nutrient suppliers specify chelated micronutrients for foliar and soil applications.
- Textile Industry:Dyeing and finishing operations in China's Zhejiang and Guangdong provinces consume sequestrants for water softening and heavy metal control.
Qualification moats favor Healthcare Facilities; volume scale favors Chemical Manufacturers.
Formulation:
Physical form selection balances handling economics, dissolution kinetics, and dosing precision across application environments.
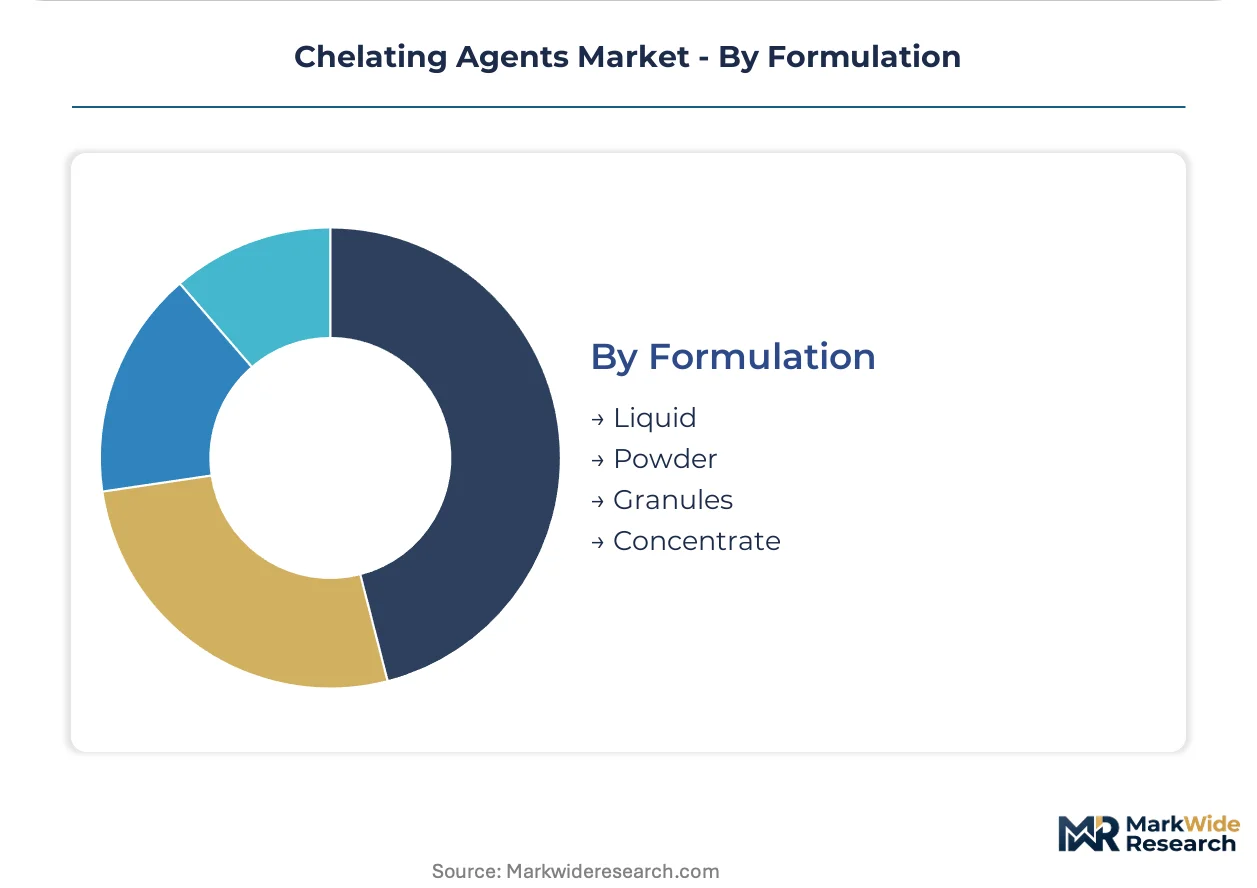
- Liquid:Ready-to-use solutions eliminate dissolution equipment and dust exposure in municipal water treatment plants. German and Dutch utilities award multi-year framework agreements bundling liquid chelant supply with performance guarantees and remote monitoring services.
- Powder:Dry formulations reduce transportation costs and enable custom blending at point of use. Agriculture producers favor powder chelants for integration into solid fertilizer matrices.
- Granules:Intermediate particle size balances flowability with dissolution rate in automated dosing systems.
- Concentrate:High-active formulations minimize freight expenditure for remote industrial sites.
Service integration favors Liquid; logistics optimization favors Concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and the Netherlands exceeds that in China's coastal manufacturing belts, where phosphate substitution mandates compress margins for biodegradable sequestrant suppliers.
United States
EPA effluent limitation guidelines under the Clean Water Act drive metalworking fluid formulators toward chelants with demonstrated removal efficiency in biological wastewater systems. Semiconductor fabrication clusters in Arizona and Texas expand consumption of high-purity organometallic complexes for wafer cleaning protocols.
Germany
Municipal water utilities in the Ruhr and Rhine regions award multi-year framework agreements bundling liquid chelant supply with performance guarantees. ECHA classification of certain aminocarboxylic acids as substances of very high concern accelerates R&D into GLDA and MGDA alternatives at industrial chemical parks in Ludwigshafen and Leverkusen.
China
MEE tightened wastewater discharge parameters in 2023, driving phosphate substitution with biodegradable sequestrants across textile processing clusters in Shaoxing and Suzhou. Electronics manufacturing concentration in the Yangtze River Delta sustains demand for EDTA derivatives in printed circuit board fabrication.
Japan
METI industrial standards govern chelant purity specifications for electronics-grade applications. Precision chemical producers in the Osaka-Kobe corridor supply organometallic complexes to semiconductor fabrication facilities in Kyushu's silicon island cluster.
India
BIS formulation standards for agricultural micronutrient fertilizers expand addressable demand for iron and zinc chelates. Textile dyeing operations in Surat and Tiruppur adopt citric acid derivatives to meet export market biodegradability certification requirements.
Chelating Agents Market Vendor Landscape
Concentration sits with integrated petrochemical producers controlling captive ethylene amine supply chains. Specialty chemical specialists face margin compression from merchant feedstock exposure. Three archetypes define competitive positioning: backward-integrated commodity producers, pharmaceutical-grade qualification specialists, and biobased formulation innovators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players reposition around regulatory-driven substitution cycles.
Among integrated producers, Nouryon and Dow exemplify the commodity-scale archetype through captive control over ethylene oxide and ethylene amine feedstocks. Mitsubishi Chemical Corporation occupies a position within the specialty-grade tier, serving electronics applications requiring coordination chemistry expertise. These three anchors illustrate how competitive advantage segregates between upstream integration depth and downstream qualification barriers.
| Leading Market Players |
|---|
| Nouryon |
| BASF SE |
| Dow |
| Lanxess AG |
| Mitsubishi Chemical Corporation |
| Kemira |
| AkzoNobel N.V. |
| Nippon Shokubai Co., Ltd. |
| Hexion |
| Others |
Supply Flow & Price Mechanics
Phosphate substitution with biodegradable sequestrants in China's textile processing clusters simultaneously redraws procurement geography and compresses margin structures for suppliers lacking captive ethylene amine production. This feedstock transition concentrates pricing power with backward-integrated producers while fragmenting margin capture among merchant-market-dependent specialists.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade USP-certified chelants from standard technical grades across water treatment and industrial applications. Contract-based long-term offtake dominates municipal utility procurement in Germany and the Netherlands, where volume scale and after-sales service bundling drive price differentiation. Cost compression in standard-grade aminocarboxylates is intensifying because REACH-driven substitution to GLDA and MGDA alternatives expands supply availability. Chemical manufacturers exhibit highest price sensitivity due to formulation cost pass-through constraints, while healthcare facilities accept premium positioning for FDA-monographed purity certification.
Supply Chain Analysis
Germany and the Netherlands anchor European chelant manufacturing through integrated ethylene amine production at Ludwigshafen and Rotterdam chemical parks. China draws from domestic ethylene oxide capacity and imported ethylene amine feedstocks to supply textile and electronics processing clusters. Raw material dependencies center on ethylene oxide, ethylene amine, and organometallic precursors for semiconductor-grade complexes. Single-source vulnerability concentrates in ethylene amine supply chains controlled by integrated petrochemical producers. Distribution runs through direct technical service relationships with municipal utilities, displacing traditional distributor intermediaries in large-volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among municipal water utilities consolidating procurement around integrated suppliers offering performance-guaranteed framework agreements. This consolidation fragments margin capture for distributors lacking technical service capabilities.
For Market Incumbents: Fortify backward integration into ethylene amine feedstocks to defend margin position against merchant-market exposure. Prioritize pharmaceutical-grade USP certification investment to create defensible moats as REACH classification of aminocarboxylates accelerates substitution pressure. Channel control through direct technical service relationships with German and Dutch utilities locks out distributor competitors. For New Entrants and Emerging Players: Differentiate on biobased molecular architectures serving EU Ecolabel-certified institutional cleaning formulators in France and Belgium. Target pharmaceutical-grade qualification as the most penetrable segment, where FDA monograph compliance creates onboarding barriers that favor specialized entrants over commodity incumbents. Pursue analytical service bundling as the go-to-market angle to displace pure-play distributors in municipal procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical specialists holding pharmaceutical-grade certification but lacking ethylene amine integration. Long-term viability across the analysis window hinges on regulatory-driven substitution cycles favoring biodegradable ligand architectures. Watch ECHA SVHC classification expansion as the inflection signal indicating accelerated capital redeployment toward GLDA and MGDA alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene amine production defends margin capture against merchant feedstock volatility. |
| Pharmaceutical-Grade Certification | FDA and USP qualification creates defensible pricing power in parenteral drug applications. |
| Green Manufacturing Transition | GLDA and MGDA capacity expansion captures REACH-driven substitution in EU institutional cleaning. |
| Long-term Supply Agreement | Multi-year framework contracts with German and Dutch utilities displace distributor intermediaries. |
| Joint Venture | Electronics-grade organometallic partnerships with East Asian semiconductor fabricants secure wafer cleaning demand. |
Methodological Framework
Cross-validation between primary interviews with plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA effluent guideline documentation. Bottom-up demand modeling across end-use segments triangulates with top-down supply capacity assessments to constrain estimate variance.
Sensitivity analysis across feedstock cost scenarios and regulatory implementation timelines tests forecast robustness. The analytical framework segments by grade tier, end-use industry, formulation type, and regional production hub throughout the projection horizon. CAGRs derive from segment-level volume trajectories calibrated to historical substitution elasticities and capacity expansion announcements. Forecast inputs incorporate REACH biodegradability threshold enforcement patterns and MEE wastewater discharge parameter tightening in China.
Decision-makers should treat outputs as directional under sustained regulatory pressure for phosphate substitution and stable ethylene amine feedstock availability; material deviation would warrant model refresh. Specific risks include divergent biodegradability enforcement between EU and emerging economies, organometallic synthesis talent scarcity limiting electronics-grade scale-up, and pulp and paper demand erosion freeing capacity redeployment. Recalibration cycles align with material shifts in ECHA SVHC classification and MEE discharge standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Competitive Inhibitors Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Chemical Silage Additives Market
Additives
Gelatin Peptones Market
Additives
Paint Additives Market
Additives
Anti Crystallizing Agents Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Nucleating and Clarifying Agents Market
Additives
Gluconic Acid and Derivatives Market
Additives
Clouding Agents Market
Additives
Liquid Silage Additive Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Dispersing Agents Market
Additives
Wax Additives Market
Additives
Sodium Citrate Anhydrous Market
Additives
Antimicrobial Ingredients Market