
 Healthcare Assistive Robot Market | 2026-2036
Healthcare Assistive Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Assistive Robot Market Analysis
Market Context
Lightweight carbon fiber composites are replacing traditional aluminum chassis in exoskeleton frames, which is expanding unit economics for mid-tier rehabilitation devices. Intuitive Surgical leverages decades of minimally invasive platform expertise to anchor its position in surgical assistive systems. Ekso Bionics specializes in powered exoskeletons for neurorehabilitation, sustaining clinical validation through partnerships with Veterans Health Administration facilities. SoftBank Robotics competes in companion robotics through emotional interaction software deployed across Japanese eldercare networks.
Technical Definition and Segments
A healthcare assistive robot is a programmable electromechanical system designed to support patient mobility, therapeutic intervention, or social companionship, typically incorporating torque-limited actuators, force-sensitive resistors, and ISO 13482-compliant safety architectures for human-robot physical interaction. Rehabilitation robots currently lead installed base volume, though AI-driven systems within the technology segment are capturing disproportionate R&D investment as neural-network gait adaptation improves stroke recovery outcomes. Mobility aids occupy the most mature margin pool, while companion robots represent the fastest-expanding application category as loneliness interventions gain reimbursement traction in European long-term care frameworks.
Regulatory Outlook
The FDA breakthrough device program and EU MDR Class IIa certification requirements jointly shape product development timelines and clinical evidence burdens for manufacturers seeking dual-market access. Japan's PMDA and METI coordinate on eldercare robot subsidies that directly influence domestic adoption velocity and export reference pricing for Asian markets. Stakeholders must monitor evolving liability frameworks for autonomous patient handling, as precedent-setting litigation in the United States and Germany will determine insurance cost structures and deployment risk appetites across the sector.
Market Dynamics
Japan's PMDA-METI subsidy coordination for eldercare robotics is compressing procurement cycles and forcing export manufacturers to recalibrate pricing architectures for Asian reference markets. This regulatory-commercial nexus now shapes competitive positioning more than raw technical differentiation.
Growth Catalysts
- EU MDR Class IIa certification harmonization:Streamlined clinical evidence requirements for ISO 13482-compliant safety architectures are accelerating dual-market FDA-EU submissions for rehabilitation device manufacturers.
- Carbon fiber composite chassis adoption:Lightweight material substitution in exoskeleton frames is reducing per-unit actuator load requirements and expanding addressable patient weight ranges for mid-tier devices.
- German aged-care labor shortages:Staffing crises in Bavarian and North Rhine-Westphalia nursing networks are mandating automation of patient mobility transfers regardless of capital budget constraints.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing bottlenecks in East Asian supply chains are creating six-month lead time volatility for powered exoskeleton manufacturers.
- Torque-limited actuator cost structure:Force-sensitive drive systems require precision harmonic gearing that carries 3-4x the component cost of industrial robotics equivalents.
- ISO 13482 compliance timeline friction:Human-robot physical interaction safety validation protocols extend development cycles by 14-18 months versus industrial automation standards.
Strategic Opportunities
- Home-based rehabilitation penetration:Post-acute stroke recovery protocols in the United States are shifting toward residential settings, creating demand for compact gait training systems without clinical infrastructure requirements.
- AI Act regulatory tailwind:EU conformity assessment frameworks for machine-learning-enabled therapeutic devices are creating first-mover certification advantages for neural-network gait adaptation systems.
- Emotional interaction software convergence:Integration of affective computing with mobility assistance functions is opening reimbursement pathways for loneliness intervention bundles in Dutch and Danish long-term care frameworks.
Industry Challenges
- Rehabilitation robotics clinical evidence generation:Randomized controlled trials for stroke recovery outcomes require 18-24 month follow-up periods that strain startup capitalization timelines.
- Legacy hospital IT integration complexity:Electronic health record interoperability with robotic therapy data streams demands custom HL7 FHIR middleware development for each major EHR vendor.
- Biomechanical engineering talent scarcity:Cross-disciplinary expertise combining kinesiology, control systems, and safety-critical software is concentrated in Swiss and German academic clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Assistive Robot Market |
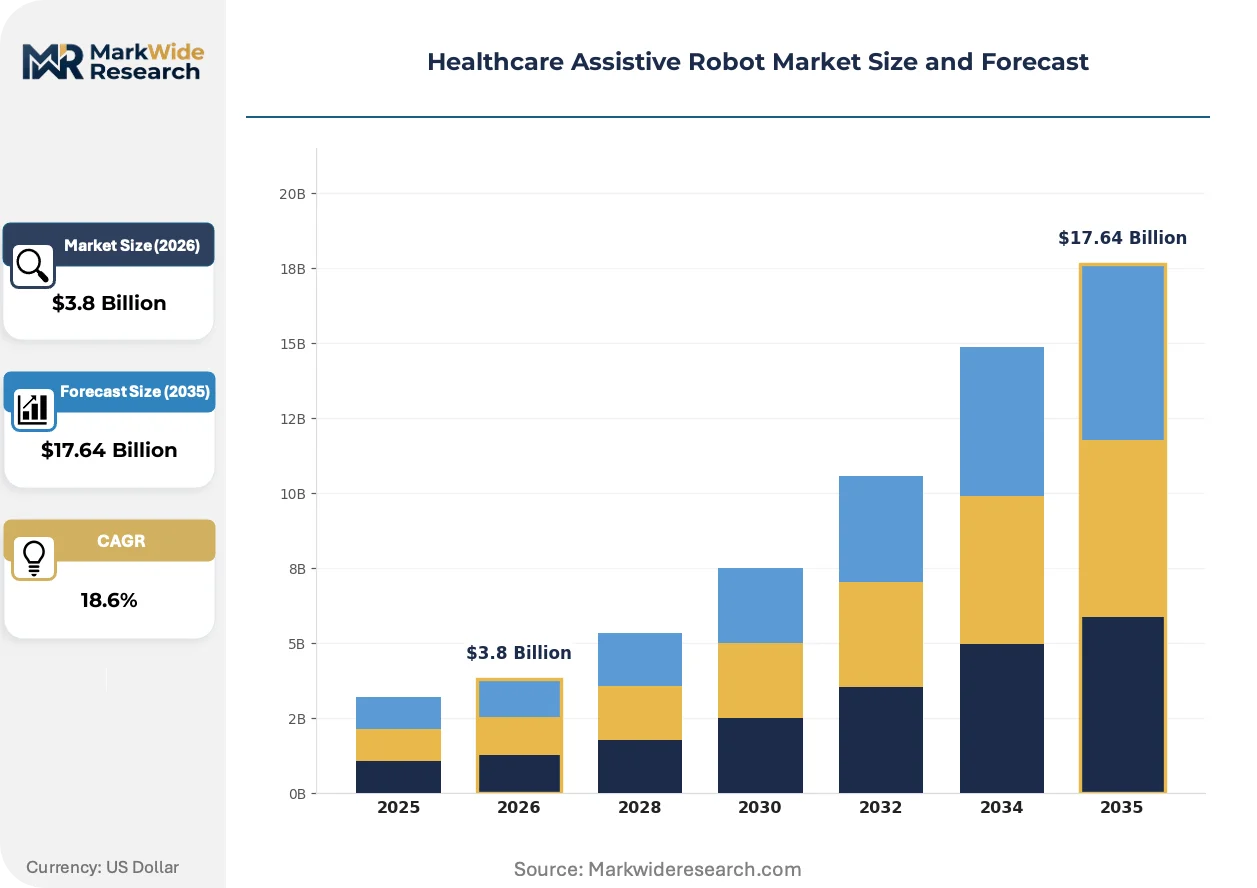
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rehabilitation Robots, Surgical Assistants, Companion Robots, Mobility Aids End User: Hospitals, Homecare Providers, Rehabilitation Centers, Nursing Facilities Technology: AI-Driven Systems, Telepresence, Sensor-Based Navigation, Voice Recognition Application: Patient Assistance, Surgical Support, Physical Therapy, Geriatric Care |
| Companies Covered | Intuitive Surgical, SoftBank Robotics, Ekso Bionics, Cyberdyne Inc., PARO Robots U.S., Inc., Kinova Inc., Toyota Motor Corporation, Honda Motor Co., Ltd., Intuition Robotics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Assistive Robot Market Emerging Trajectories
Neural-network-driven gait adaptation is compressing the boundary between assistive and rehabilitative robotics, forcing manufacturers to reposition hardware platforms across multiple reimbursement categories simultaneously.
Soft actuation technologies employing pneumatic artificial muscles and dielectric elastomer actuators are expanding into pediatric and geriatric applications where rigid electromechanical joints pose safety liabilities. Children's hospitals in the United States and eldercare networks in Japan are piloting these systems for cerebral palsy and Parkinson's mobility support. The technology is expanding into previously inaccessible patient demographics by eliminating pinch-point hazards and reducing device mass below 8 kilograms.
Japan's PMDA has established a dedicated review pathway for eldercare companion robots that compresses premarket notification timelines from 18 months to 9 months for devices demonstrating dementia care efficacy. This regulatory innovation is prompting METI to expand subsidy eligibility to AI-driven therapeutic conversation systems. German manufacturers seeking Asian market entry are now prioritizing PMDA clearance over FDA breakthrough device designation due to faster commercialization velocity.
Acute care networks are unbundling after-sales service contracts from hardware procurement, creating standalone revenue pools for predictive maintenance and software update subscriptions. Hospital systems in the Netherlands and Belgium are piloting per-patient-mobility-event pricing models that shift capital expenditure to operational budgets. This restructuring is most visible in Flemish rehabilitation centers where municipal ownership constraints favor opex-based vendor relationships over direct equipment purchases.
Healthcare Assistive Robot Market Segmentation
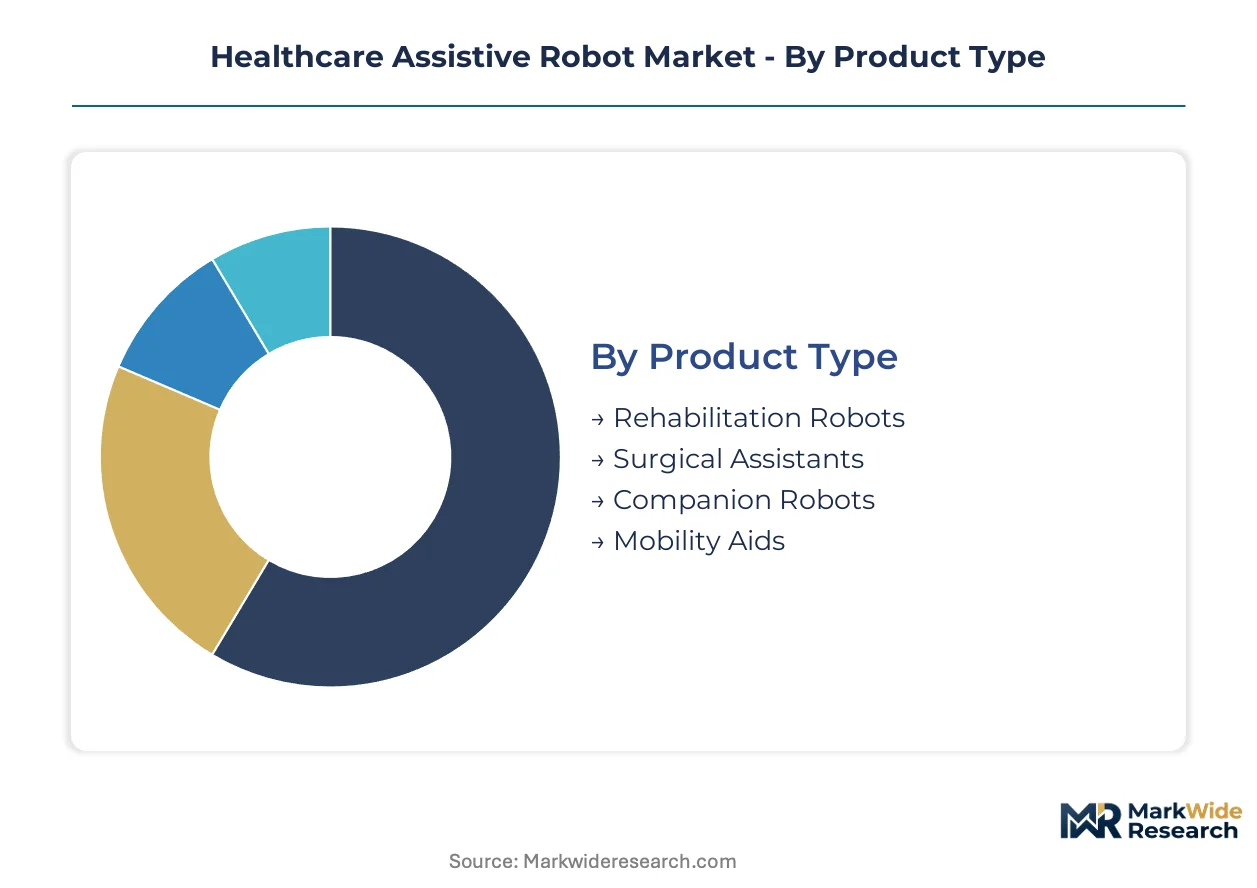
Segmentation reveals divergent margin structures and regulatory pathways across healthcare assistive robotics. Manufacturers must align chassis material choices, software architectures, and reimbursement strategies to specific category requirements rather than pursuing horizontal platform plays.
Product Type:
Supply concentration in precision actuator manufacturing favors platforms with standardized torque-limited drive systems across multiple form factors.
- Rehabilitation Robots:Powered exoskeletons and end-effector devices incorporate carbon fiber composite frames with ISO 13482-compliant safety architectures. Veterans Health Administration facilities in the United States drive procurement volume for stroke and spinal cord injury protocols.
- Companion Robots:Emotional interaction software platforms deploy affective computing for dementia care and loneliness intervention. Japanese nursing facilities accelerate procurement through METI-PMDA subsidy coordination that compresses procurement cycles.
- Surgical Assistants:Minimally invasive platforms leverage decades of laparoscopic expertise with haptic feedback and tremor filtration.
- Mobility Aids:Autonomous wheelchairs and patient transfer systems address Bavarian and North Rhine-Westphalia staffing crises in German aged-care networks.
Rehabilitation robots absorb the bulk of installed capacity; companion robots are expanding most quickly.
End User:
Customer procurement authority determines software integration depth and service contract structure.
- Hospitals:Acute care networks demand HL7 FHIR interoperability with electronic health record systems and predictive maintenance subscriptions. Flemish rehabilitation centers pilot per-patient-mobility-event pricing that shifts capital expenditure to operational budgets.
- Nursing Facilities:Long-term care operators prioritize ISO 13482-compliant safety validation for autonomous patient handling to mitigate liability exposure. German municipal ownership constraints favor opex-based vendor relationships.
- Rehabilitation Centers:Post-acute stroke recovery protocols require 18-24 month clinical evidence generation timelines that strain startup capitalization.
- Homecare Providers:Residential settings demand compact gait training systems without clinical infrastructure requirements.
Hospitals command the largest procurement budgets; homecare providers are climbing the fastest as reimbursement shifts toward residential settings.
Technology:
Development cost tiers separate neural-network platforms from deterministic control systems.
- AI-Driven Systems:Neural-network gait adaptation algorithms improve stroke recovery outcomes through real-time biomechanical adjustment. EU AI Act conformity assessment frameworks create first-mover certification advantages for therapeutic device manufacturers.
- Sensor-Based Navigation:LiDAR and depth-camera arrays enable autonomous mobility in unstructured clinical environments.
- Voice Recognition:Natural language processing supports hands-free operation for patients with limited dexterity.
- Telepresence:Remote physician consultation capabilities expand specialist access to rural and underserved regions.
AI-driven systems capture disproportionate R&D investment; sensor-based navigation maintains the broadest installed base across product categories.
Application:
Reimbursement code availability shapes addressable market size more than technical capability.
- Physical Therapy:Gait training and repetitive motion protocols generate clinical evidence requirements that extend FDA breakthrough device pathway timelines.
- Geriatric Care:Loneliness intervention bundles gain traction in Dutch and Danish long-term care frameworks through affective computing integration.
- Patient Assistance:Mobility transfer automation addresses labor shortages in Japanese eldercare networks through PMDA fast-track clearance.
- Surgical Support:Haptic feedback and tremor filtration systems anchor premium pricing in minimally invasive procedures.
Physical therapy commands the deepest clinical validation; geriatric care is gaining share fastest as European reimbursement frameworks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Kanto Special Economic Zone clusters METI-subsidized eldercare robotics development, concentrating PMDA fast-track clearance activity and export reference pricing power for Asian markets.
United States
Veterans Health Administration facilities drive exoskeleton procurement volume for spinal cord injury rehabilitation protocols. FDA breakthrough device designation streamlines AI-driven rehabilitation system clearances, compressing premarket timelines. Pittsburgh and Boston academic medical centers anchor clinical validation networks for neural-network gait adaptation systems.
Germany
Bavarian and North Rhine-Westphalia nursing networks mandate patient mobility automation amid acute staffing shortages regardless of capital constraints. EU MDR Class IIa certification harmonization accelerates dual-market FDA-EU submissions for ISO 13482-compliant safety architectures. Baden-Württemberg precision actuator manufacturers supply torque-limited drive systems to rehabilitation device producers.
Japan
METI-PMDA subsidy coordination compresses eldercare robot procurement cycles and forces export manufacturers to recalibrate Asian pricing architectures. Dedicated PMDA review pathways for companion robots slash premarket notification timelines from 18 months to 9 months for dementia care efficacy demonstrations. Tokyo and Osaka metropolitan clusters concentrate affective computing development for loneliness intervention systems.
Netherlands
Flemish rehabilitation centers pilot per-patient-mobility-event pricing models that shift capital expenditure to operational budgets under municipal ownership constraints. Dutch long-term care frameworks expand reimbursement pathways for loneliness intervention bundles integrating affective computing. Eindhoven's robotics engineering ecosystem supports soft actuation technology development for pediatric and geriatric safety applications.
China
Dual carbon policy targets accelerate lightweight carbon fiber composite adoption in exoskeleton chassis manufacturing. NMPA regulatory harmonization with ISO 13482 standards shapes domestic safety validation protocols for human-robot physical interaction. Shenzhen and Shanghai industrial clusters concentrate mid-tier rehabilitation device assembly for cost-sensitive Asian markets.
Healthcare Assistive Robot Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with rehabilitation robotics consolidating around clinical validation networks while companion robotics fragments across emotional interaction software platforms. Tier-one positions concentrate with firms possessing decades of minimally invasive platform expertise or Veterans Health Administration partnership depth. Three archetypes dominate: integrated surgical platform operators, powered exoskeleton specialists, and affective computing software developers. Strategic moves center on PMDA fast-track clearance prioritization over FDA breakthrough designation, plus predictive maintenance subscription unbundling from hardware procurement.
Among Japan-based conglomerates with robotics divisions, Toyota Motor Corporation and Honda Motor Co., Ltd. occupy positions spanning mobility assistance and humanoid research, while SoftBank Robotics exemplifies the affective computing archetype through emotional interaction software deployment across domestic eldercare networks. These firms represent contrasting strategic postures: hardware-integrated platform depth versus software-centric rapid iteration for reimbursement-adjacent loneliness interventions.
| Leading Market Players |
|---|
| Intuitive Surgical |
| SoftBank Robotics |
| Ekso Bionics |
| Cyberdyne Inc. |
| PARO Robots U.S., Inc. |
| Kinova Inc. |
| Toyota Motor Corporation |
| Honda Motor Co., Ltd. |
| Intuition Robotics Ltd. |
| Others |
Supply Flow & Price Mechanics
Carbon fiber composite chassis adoption in exoskeleton manufacturing simultaneously compresses per-unit actuator costs and concentrates procurement leverage among Japanese and German precision materials suppliers. This materials transition reshapes margin distribution across rehabilitation device tiers while tethering mid-tier manufacturers to specialized composite fabricators in Baden-Württemberg and Kansai industrial clusters.
Pricing Analysis
Volume concentrates in mid-tier rehabilitation devices while margin pools anchor in premium AI-driven systems with neural-network gait adaptation. Pricing stratifies across FDA breakthrough designation, EU MDR Class IIa certification, and unvalidated economy tiers, with certification grade commanding the steepest premium differentials. Cost compression in mid-tier exoskeletons intensifies because carbon fiber composite sourcing consolidates among limited Japanese suppliers. Hospital procurement committees exhibit lowest price sensitivity for surgical assistant platforms, while municipal nursing facilities in Germany face acute budget constraints.
Supply Chain Analysis
Direct-to-hospital channels handle Veterans Health Administration and academic medical center demand, while distributor networks serve European municipal nursing facilities. Precision actuator manufacturing concentrates in Germany, Switzerland, and Japan, with torque-limited harmonic gearing sourcing from Baden-Württemberg and Nagoya industrial bases. Lithium-ion battery cathode processing feeds from East Asian supply chains, creating single-source vulnerability for powered exoskeleton manufacturers. Distribution runs through specialized medical device distributors with ISO 13482 compliance expertise rather than general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13482 safety validation protocols function as a cost-of-compliance moat, with 14-18 month development timeline extensions filtering out undercapitalized entrants and protecting validated incumbents from rapid commoditization.
For Market Incumbents: Anticipate margin pressure from soft actuation technologies by securing exclusive carbon fiber composite supply agreements with Japanese and German fabricators. Prioritize PMDA fast-track clearance investment over FDA breakthrough designation to capture Asian reference pricing power. Defensive patent filings around pneumatic artificial muscle integration will block pediatric and geriatric market entry by emerging competitors.
For New Entrants and Emerging Players: Launch via home-based rehabilitation distribution partnerships to bypass hospital IT integration complexity and capital expenditure approval cycles. White-space opportunity concentrates in compact gait training systems for post-acute stroke recovery in residential settings, where reimbursement shifts favor operational expenditure models. Target Dutch and Danish long-term care frameworks with loneliness intervention bundles combining affective computing and mobility assistance.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisitions by surgical robotics conglomerates seeking rehabilitation diversification and by Japanese eldercare networks expanding affective computing capabilities. Five-to-ten year viability favors firms with Veterans Health Administration validation depth and PMDA clearance velocity rather than pure technology plays. Watch for EU AI Act conformity assessment completion as inflection indicator for neural-network therapeutic device premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Fast-Track Clearance | Compresses premarket timelines from 18 months to 9 months for dementia care efficacy demonstrations. |
| Carbon Fiber Supply Integration | Captures cost advantages in mid-tier exoskeleton manufacturing through Baden-Württemberg supplier partnerships. |
| Home-Based Rehabilitation Launch | Aligns with US post-acute stroke protocol shifts toward residential settings without clinical infrastructure. |
| EU AI Act Conformity Assessment | Creates first-mover certification advantages for neural-network gait adaptation systems in European markets. |
| Predictive Maintenance Unbundling | Generates recurring revenue pools from acute care networks in Netherlands and Belgium piloting per-event pricing. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with rehabilitation clinicians, biomedical engineers, hospital purchasing committees, GPO contracts managers, and METI subsidy program administrators. FDA 510(k) and breakthrough device designation databases, PMDA premarket notification records, EU MDR notified body certificates, and Veterans Health Administration procurement disclosures provided validation anchors. Bottom-up installed base estimates triangulated against top-down reimbursement code analysis across German, Japanese, and US payment frameworks.
Segmentation granularity modeled product type, end user procurement authority, technology architecture, and application reimbursement category across the projection horizon. Neural-network gait adaptation penetration curves, carbon fiber composite cost decline trajectories, and PMDA-METI subsidy expansion scenarios informed analytical framework construction. CAGRs derived from logistic diffusion models of clinical validation completion and regulatory clearance velocity rather than linear extrapolation.
Regulatory timeline delays, lithium-ion supply chain disruptions, and reimbursement code expansion failures are the dominant revision risks. Forecasts reflect assumptions regarding PMDA fast-track pathway continuity, EU MDR Class IIa harmonization stability, and Veterans Health Administration procurement volume sustainability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Robot Operating System Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Sweden Robotic Lawn Mower Market
Robotics and Automation
Construction Robotics Market