

Robotics-Ready Fulfillment Center Design and Integration Services Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics-Ready Fulfillment Center Design and Integration Services Market Insights
Autonomous mobile robot certification tiers is collapsing the traditional barrier between pilot deployments and scaled warehouse automation. Dematic leverages its deep vertical integration across conveyor and software layers to sustain project margins on complex multi-site rollouts. Swisslog anchors European demand through specialized pharma-compliant cleanroom integration capabilities.
Robotics-ready fulfillment center design and integration services encompass the engineering, layout optimization, and system orchestration required to deploy automated material handling infrastructure with throughput specifications exceeding 10,000 picks per hour. These services bridge mechanical automation, warehouse control software, and operational workflow redesign to enable same-day and next-day order fulfillment at scale. System integration commands the largest margin pool due to multi-vendor orchestration complexity, while robotics deployment represents the fastest-growing service type as collaborative robot and AMR installations accelerate across brownfield retrofits. Goods-to-person systems dominate application spending because they directly address labor scarcity in high-SKU environments, whereas sortation investment matures in parcel hub markets.
FDA cGMP guidelines and EU Machinery Directive standards shape pharma and grocery distribution facility designs by mandating traceability interfaces and safety-rated collaborative workspaces. OSHA lockout/tagout requirements and ISO 3691-4 for industrial trucks further constrain robot commissioning timelines and integration vendor qualification. Stakeholders must monitor evolving cyber-physical system insurance frameworks and regional building code adaptations for automated rack-supported structures.
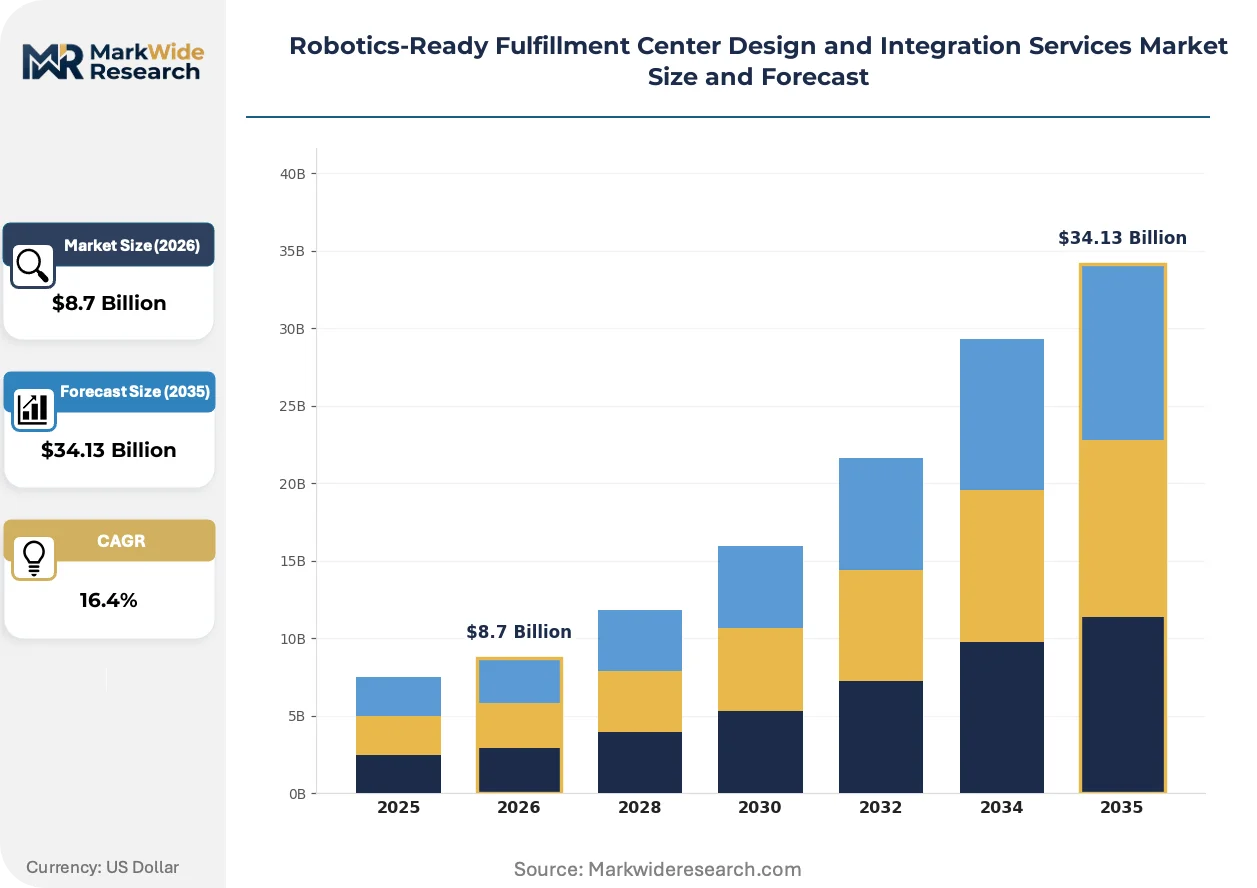
Market Dynamics
The collapse of certification barriers between pilot AMR deployments and scaled warehouse automation is compressing sales cycles and forcing integration vendors to restructure project delivery models around modular commissioning protocols.
Growth Catalysts
- EU Machinery Directive 2006/42/EC amendments:Safety-rated collaborative workspace mandates are accelerating retrofit demand in brownfield distribution facilities across Germany and France.
- Same-day fulfillment velocity requirements:E-commerce operators are reconfiguring fulfillment networks to support 10,000+ picks per hour throughput specifications.
- Goods-to-person robotics maturation:Labor scarcity in high-SKU grocery and pharma distribution is displacing traditional zone-picking workflows with automated storage and retrieval systems.
Market Restraints
- Steel and semiconductor input cost volatility:Rack-supported structure fabrication and robot controller component sourcing face margin compression from commodity price swings.
- Integration engineering talent concentration:Certified systems architects cluster in southern Germany and northern Italy, creating geographic supply bottlenecks for complex multi-site rollouts.
- Brownfield structural limitations:Legacy facility ceiling heights and floor load ratings constrain AS/RS deployment in pre-2010 industrial real estate.
Strategic Opportunities
- Pharma-compliant cleanroom integration:FDA cGMP and EMA GMP guidelines create specialized service margins for temperature-validated automated handling in vaccine distribution.
- India warehouse automation emergence:PLI scheme incentives for electronics manufacturing are driving greenfield fulfillment center construction with native robotics integration requirements.
- Cyber-physical insurance framework evolution:Emerging coverage models for autonomous system liability are reducing buyer risk perception in early AMR adoption decisions.
Industry Challenges
- ISO 3691-4 commissioning timelines:Industrial truck safety standard validation extends robot deployment schedules by four to eight weeks in multi-vendor environments.
- Warehouse control software interoperability:Proprietary WCS protocols from incumbent conveyor manufacturers create integration friction with third-party AMR fleets.
- OSHA lockout/tagout compliance sequencing:Energy isolation procedure certification for collaborative robot cells adds labor cost overhead to installation contracts.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics-Ready Fulfillment Center Design and Integration Services Market Trends and Innovations
Three forces are compressing the traditional boundary between mechanical automation and software-defined orchestration in fulfillment infrastructure deployment.
Edge computing nodes embedded within autonomous mobile robots are miniaturizing warehouse control system architecture. Third-party logistics operators in the Netherlands and Belgium are deploying these distributed intelligence platforms to reduce latency in pick-path optimization. The shift is miniaturizing the centralized WCS footprint and enabling sub-100-millisecond response times in high-density storage environments.
REACH substance restrictions and EU AI Act risk classification frameworks are reshaping component sourcing for robotic systems deployed in European distribution networks. Battery chemistry disclosure requirements and high-risk AI system registration mandates are extending vendor qualification timelines. Pharma and cold chain operators in Germany and Denmark are restructuring supplier audit protocols to preempt compliance gaps.
Performance-based contracting is displacing fixed-fee integration models in enterprise fulfillment deployments. Retailers are tying vendor payments to achieved throughput benchmarks and system availability metrics rather than milestone-based invoices. This shift is most pronounced in UK and French grocery distribution networks where labor cost volatility makes outcome-aligned pricing preferable to capital-intensive ownership models.
Robotics-Ready Fulfillment Center Design and Integration Services Market Segmentation
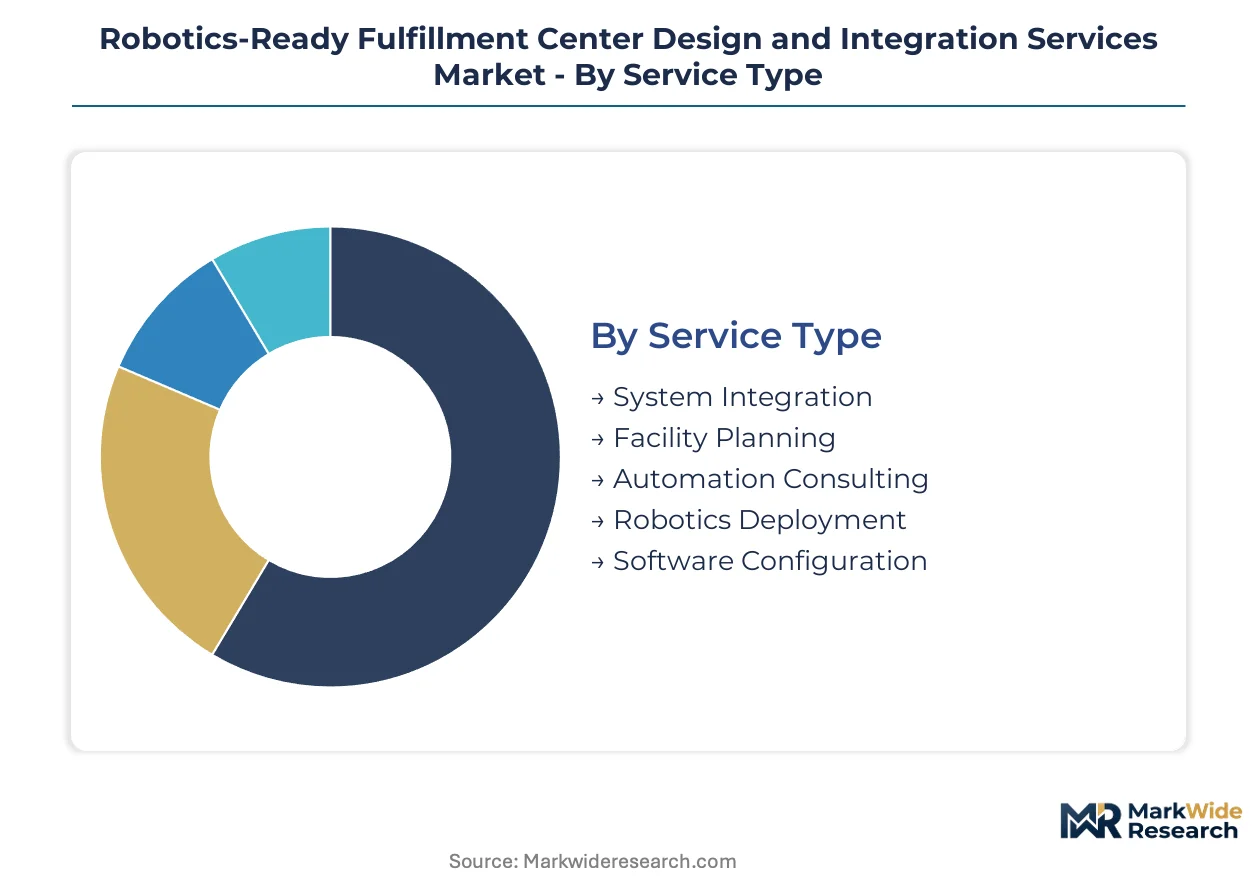
Segmentation in robotics-ready fulfillment services reveals how vendor capabilities align with buyer automation maturity. Service type and application segments show distinct geographic demand patterns, while end-user verticals concentrate in regulatory-intensive European markets.
Service Type:
Domestic engineering capabilities dominate facility planning and automation consulting, whereas system integration and robotics deployment increasingly rely on cross-border vendor mobility.
- System Integration:Multi-vendor orchestration of mechanical, electrical, and software layers requires certified architects. Demand clusters in Germany's southern industrial belt where Dematic and Swisslog maintain dense project execution teams.
- Robotics Deployment:AMR and collaborative robot commissioning services are expanding most quickly. Brownfield retrofits in France and Belgium drive specialized installation protocols for ISO 3691-4 compliance.
- Facility Planning:Layout optimization for throughput targets exceeding 10,000 picks per hour.
- Automation Consulting:Workflow redesign and ROI modeling for capital-intensive transformation programs.
- Software Configuration:WCS-WMS integration and edge computing node deployment.
System integration holds the largest share; momentum sits with robotics deployment.
Application:
Cost tier differentiation separates high-complexity goods-to-person installations from standardized sortation retrofits.
- Goods-to-Person Systems:Automated storage and retrieval with robotic shuttles and vertical lift modules. Grocery distribution networks in the Netherlands and UK prioritize these configurations to address labor scarcity in high-SKU environments.
- Sortation:High-speed parcel routing for hub-and-spoke distribution. Mature demand concentrates in Belgian and German parcel hub markets where throughput specifications exceed 15,000 items per hour.
- Order Picking:Zone-to-zone and pick-to-light automation for e-commerce fulfillment.
- Inventory Management:Cycle counting and slotting optimization through autonomous mobile platforms.
- Packing Optimization:Automated dimensioning and void-fill systems for parcel efficiency.
Goods-to-person systems command premium pricing; sortation exhibits volume concentration.
End User:
Customer type segmentation distinguishes asset-light operators seeking outcome-based contracts from capital-intensive owners pursuing vertical integration.
- E-commerce Operators:Same-day fulfillment velocity requirements drive 10,000+ picks per hour specifications. Amazon and Zalando deployment patterns in Germany and Poland set regional engineering standards.
- Pharma Distributors:FDA cGMP and EMA GMP compliance mandates create specialized cleanroom integration demand. Temperature-validated automated handling in vaccine distribution commands specialized service margins.
- Third-Party Logistics Providers:Multi-tenant facility automation with flexible reconfiguration requirements.
- Grocery Distribution:High-SKU perishables handling with cold chain integration.
- Consumer Electronics Warehouses:Fragile goods handling with anti-static and shock-protection protocols.
E-commerce operators anchor current spending; pharma distributors generate the steepest expansion trajectory.
Technology:
Supply concentration for core components shapes deployment feasibility across technology categories.
- Collaborative Robots:Safety-rated workspace design with force-limiting and speed-monitoring capabilities. EU Machinery Directive 2006/42/EC amendments accelerate retrofit demand in French brownfield facilities.
- Warehouse Management Software:Cloud-native platforms with API-first architecture for multi-vendor robot fleets. Dutch and Belgian 3PLs deploy distributed intelligence to achieve sub-100-millisecond response times.
- Automated Guided Vehicles:Magnetic tape and laser-guided transport for repetitive horizontal movement.
- Conveyor Systems:Belt, roller, and sortation conveyor integration with legacy equipment.
- Vision Systems:Barcode scanning and package dimensioning for quality control and routing.
Warehouse management software holds the largest share; collaborative robots are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified systems architects cluster in southern Germany and northern Italy, creating geographic supply bottlenecks that shape where complex multi-site rollouts originate. Vendor mobility across borders determines project feasibility in fragmented European markets.
Germany
E-commerce operators including Amazon and Zalando drive 10,000+ picks per hour specifications across fulfillment networks. EU Machinery Directive 2006/42/EC amendments accelerate retrofit demand in brownfield distribution facilities. Stuttgart and Munich anchor dense vendor ecosystems where Dematic and Swisslog maintain project execution teams for multi-site automation rollouts.
France
Grocery distribution networks prioritize goods-to-person configurations to address labor scarcity in high-SKU perishables handling. Safety-rated collaborative workspace mandates under EU Machinery Directive reshape installation protocols. Paris and Lyon concentrate brownfield retrofit activity where ISO 3691-4 commissioning extends deployment schedules.
Netherlands
Third-party logistics operators deploy edge computing nodes within autonomous mobile robots to achieve sub-100-millisecond response times. REACH substance restrictions reshape component sourcing for robotic systems. The Randstad logistics corridor hosts distributed intelligence platforms that miniaturize centralized warehouse control system architecture.
Belgium
High-speed parcel routing for hub-and-spoke distribution generates mature demand for sortation investment exceeding 15,000 items per hour. EU AI Act risk classification frameworks extend vendor qualification timelines. Antwerp and Brussels anchor performance-based contracting models where retailers tie vendor payments to throughput benchmarks.
India
PLI scheme incentives for electronics manufacturing drive greenfield fulfillment center construction with native robotics integration requirements. The country's national industrial policy regulator structures production-linked incentives for automated material handling infrastructure. Maharashtra and Karnataka emerge as automation deployment clusters serving contract manufacturing networks.
Robotics-Ready Fulfillment Center Design and Integration Services Market Competitive Landscape
Concentration sits with full-system integrators possessing deep vertical integration across conveyor and software layers. The vendor base spans three tiers: global turnkey providers, regional specialists with pharma-compliant cleanroom capabilities, and modular robotics pure-plays. Strategic differentiation runs through M&A activity targeting software assets and capacity expansion into underpenetrated Asian markets.
Within the full-system integrator tier, Dematic and Swisslog exemplify archetypes sustaining project margins on complex multi-site rollouts. KNAPP occupies a position among European fabricators with specialized capabilities in automated storage and retrieval systems. These three anchors represent how vendor mobility and certified architect concentration determine competitive positioning across fragmented regional markets.
| Leading Market Players |
|---|
| Dematic |
| Swisslog |
| KNAPP |
| Vanderlande |
| FORTNA |
| TGW Logistics |
| Bastian Solutions |
| Daifuku |
| AutoStore |
| Others |
Pricing and Supply Chain Analysis
Project-based contracting with milestone-linked payment schedules locks in multi-year supply commitments for rack-supported structures and robot controller components while providing cost visibility to integration vendors navigating steel and semiconductor price volatility. This structure aligns German and French brownfield retrofit timelines with fabrication capacity reservations at southern European steel fabricators.
Pricing Analysis
EU Machinery Directive 2006/42/EC amendments dictate the pricing tier structure by mandating safety-rated collaborative workspace certification that separates premium integrators from standard-tier competitors. Pricing stratifies across certified-architect, qualified-installer, and basic-deployment tiers based on ISO 3691-4 compliance depth and after-sales service bundling. Cost compression in the standard tier is intensifying because steel input volatility squeezes fixed-fee margins. Third-party logistics providers exhibit the highest price sensitivity due to outcome-based contracting preferences, whereas pharma distributors accept premium pricing for temperature-validated cleanroom capabilities.
Supply Chain Analysis
Germany and Italy anchor precision rack fabrication and certified systems architect talent pools that feed integration demand across France and the Netherlands. Controller electronics draw from South Korean and Japanese semiconductor supply chains, while battery systems for AMR fleets rest on Chinese and South Korean cell manufacturing. Single-source vulnerability concentrates in safety-rated sensor modules certified under EU Machinery Directive standards. Distribution runs through direct vendor-client project contracts with limited intermediary channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as e-commerce operators disaggregate single-vendor dependencies and demand modular, multi-source automation architectures.
For Market Incumbents: Consolidate software asset portfolios through targeted acquisition of warehouse control system specialists to defend against proprietary protocol fragmentation threatening multi-vendor orchestration margins. Deepen captive supply of edge computing nodes to reduce third-party dependency in distributed intelligence deployments. Lock in certified architect talent through apprenticeship pipelines anchored in Stuttgart and Munich industrial clusters. For New Entrants and Emerging Players: ISO 3691-4 fast-track certification programs unlock brownfield retrofit opportunities in French grocery distribution networks where incumbent commissioning timelines extend deployment schedules. White-space concentration sits with pharma-compliant cleanroom integration in Denmark and Germany where FDA cGMP and EMA GMP mandates create specialized service premiums. Pursue outcome-based contracting models aligned with UK retailer risk-transfer preferences. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists possessing pharma-cleanroom capabilities and dense certified-architect workforces in underpenetrated Indian greenfield markets. Long-term viability hinges on software-defined orchestration assets that decouple from mechanical automation commoditization. Monitor PLI scheme incentive disbursement velocity in Maharashtra and Karnataka as inflection signal for Indian warehouse automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Fast-Track Investment | ISO 3691-4 and EU Machinery Directive compliance accelerates brownfield retrofit access in France. |
| Software Asset Acquisition | Warehouse control system specialists reduce proprietary protocol friction with third-party AMR fleets. |
| Pharma-Cleanroom Capability Buildout | FDA cGMP and EMA GMP alignment captures vaccine distribution automation premiums in Germany. |
| Edge Computing Node Integration | Distributed intelligence platforms achieve sub-100-millisecond response times for Dutch 3PL operators. |
| India Greenfield Partnership | PLI scheme-aligned facility construction addresses electronics manufacturing fulfillment demand in Maharashtra. |
Research Methodology
A spread of perspectives from warehouse control software engineers, certified systems integrators, e-commerce fulfillment operations directors, and pharma distribution facility managers converged on the working assumptions driving segmentation splits. Primary interview insights were cross-validated against EU Machinery Directive regulatory filings, OSHA technical documentation, SEC disclosures from automation vendors, and customs records for steel and semiconductor trade flows. Bottom-up project pipeline enumeration was triangulated with top-down e-commerce fulfillment network expansion announcements.
Segmentation dimensions modeled include service type complexity tier, application throughput specification, end-user vertical regulatory intensity, and technology deployment architecture across the projection horizon. CAGRs were derived from installation volume trajectories weighted by average project value per throughput tier. Forecast inputs incorporated brownfield retrofit feasibility indices and certified architect supply concentration metrics.
Decision-makers should treat outputs as directional under assumptions of sustained EU Machinery Directive enforcement and stable steel-semiconductor input cost ratios; material deviation would warrant model refresh. Recalibration cycles align with material shifts in PLI scheme incentive structures and cyber-physical insurance framework maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.