
 Underwater Rescue Robot Market | 2026-2036
Underwater Rescue Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Rescue Robot Market Insights
EU MDR is broadening the cost-of-entry calculus for underwater rescue robot manufacturers seeking defense and civil contracting in Europe. Kongsberg Maritime leverages its Nordic manufacturing base to sustain long-cycle naval procurement relationships. ECA Group specializes in mine-countermeasure derivatives that anchor its rescue-system pipeline. Saab Seaeye controls a dominant share of North Sea inspection and intervention work, extending its technology into emergency-response configurations.
An underwater rescue robot is a submersible electromechanical system rated for pressures exceeding 300 bar, equipped with thruster propulsion, sensor payloads, and tethered or autonomous command links, purpose-built to locate, assess, and recover personnel or objects from submerged environments. Remotely Operated Vehicles occupy the mature core of the product mix, while Hybrid Systems capture expanding margin pools as operators demand seamless transitions between supervised and unsupervised mission phases. AI Navigation represents the fastest-growing technology dimension, reshaping competitive positioning as sonar-imaging incumbents race to integrate real-time path-planning software.
FCC equipment authorization governs wireless control frequencies for US-deployed systems, while EU REACH compliance constrains pressure-hull coatings and battery chemistries sold into European maritime authorities. Japan's METI sets domestic testing protocols that shape product certification timelines for regional vendors. Stakeholders must monitor how diverging national safety standards fragment platform interoperability and force parallel development tracks.
Market Dynamics
Hybrid autonomy architectures are compressing development cycles as navies and coast guards demand platforms that switch seamlessly between supervised and unsupervised operation modes without hardware swaps.
Growth Catalysts
- Coastal disaster mandates:Japan's METI protocols for autonomous underwater vehicle certification are accelerating domestic procurement timelines for municipal maritime authorities.
- Deep-water recovery prioritization:NOAA and Coast Guard modernization programs in the United States are channeling capital toward extended-range search systems rated below 6,000 meters.
- AI path-planning convergence:Real-time sonar-imaging integration with neural navigation algorithms is extending mission endurance without surface tether dependence.
Market Restraints
- Pressure-hull material costs:Titanium alloy and ceramic composite prices fluctuate with aerospace demand, squeezing margins on deep-rated platforms.
- Battery chemistry constraints:EU REACH compliance limits lithium-sulfur and solid-state electrolyte formulations available to European vendors, extending qualification periods.
- Specialized component concentration:High-density thruster motors and precision acoustic transducers source from a narrow supplier base concentrated in Germany and Japan.
Strategic Opportunities
- Arctic search coverage gaps:Underpenetrated Norwegian and Canadian coast guard fleets present first-mover potential for ice-rated autonomous systems.
- Dual-use mine-countermeasure pivot:Naval procurement for explosive ordnance disposal creates technology transfer pathways into civil rescue configurations.
- Leased fleet models:Municipal harbor authorities in Spain and Italy are testing subscription-based access to shared rescue robot pools, reducing capital barriers.
Industry Challenges
- Subsea software engineering scarcity:Developers with expertise in acoustic positioning and fault-tolerant control systems command premium compensation, constraining vendor scaling.
- Multi-agency certification complexity:Systems must satisfy diverging national safety standards from FCC equipment authorization, EU MDR, and Japan's METI, forcing parallel documentation tracks.
- Legacy vessel integration friction:Retrofitting autonomous launch-and-recovery systems onto existing coast guard cutters requires hull modifications that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Rescue Robot Market |
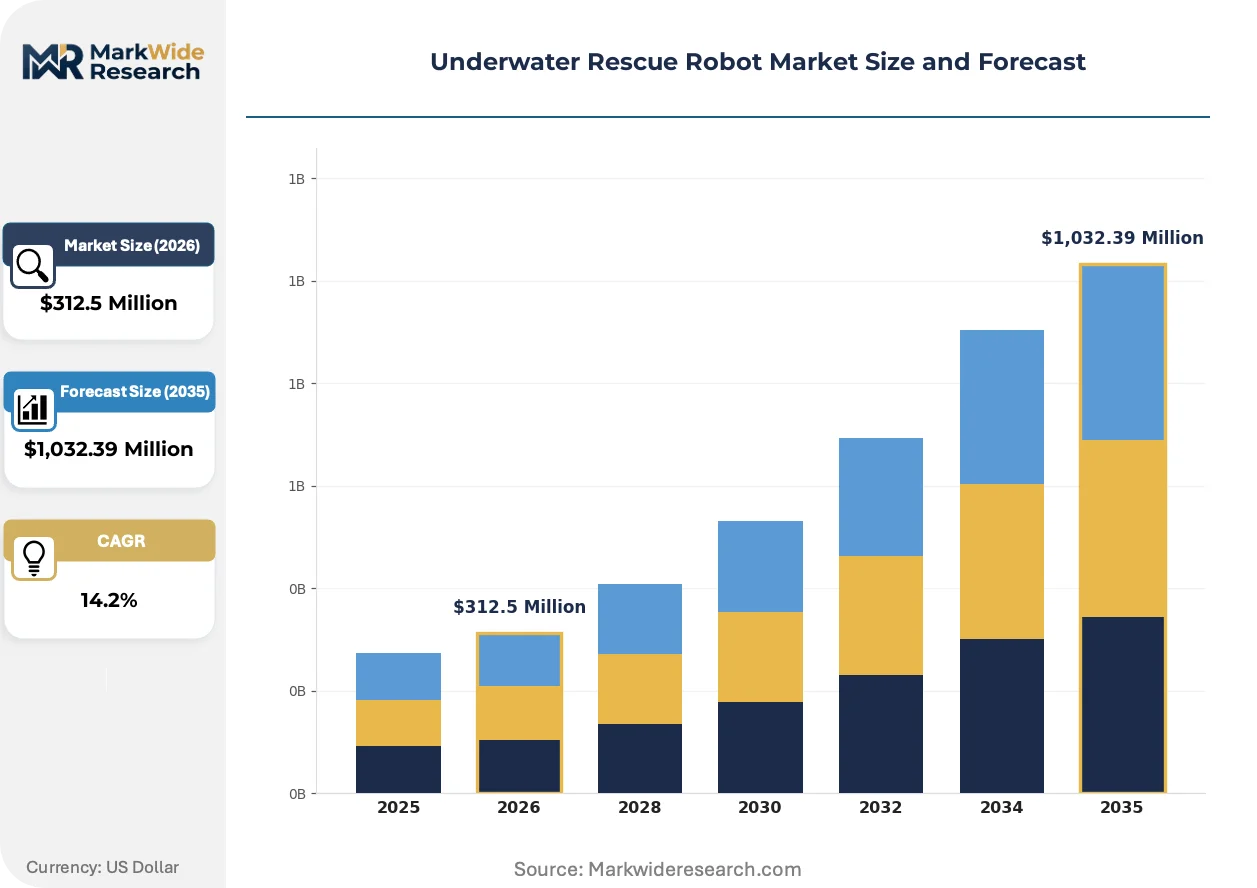
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,032.39 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remotely Operated Vehicles, Autonomous Underwater Vehicles, Hybrid Systems, Inspection Robots Technology: Sonar Imaging, LiDAR Mapping, Robotic Manipulation, AI Navigation, Wireless Control Application: Search & Recovery, Deep Sea Inspection, Environmental Monitoring, Incident Response End User: Maritime Authorities, Offshore Platforms, Naval Forces, Salvage Operators |
| Companies Covered | Bluefin Robotics, Inc., Deep Trekker Inc., Oceaneering International, Inc., Teledyne Marine Services, Inc., Kongsberg Maritime AS, ECA Group S.A.S., Aquabotix Technology Corp., Fujian Oceanalpha Marine Technology Co., Ltd., Saab Seaeye Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Rescue Robot Market Trends and Innovations
Acoustic communication bandwidth limitations are driving investment in edge-computing payloads that process sensor data locally rather than streaming raw feeds to surface vessels.
Optical-acoustic sensor fusion is absorbing mission-critical functions previously handled by separate sonar and camera systems. Naval operators in the United Kingdom and Australia are field-testing integrated perception stacks that reduce payload volume by thirty percent. This convergence is absorbing hardware slots and compressing the addressable market for standalone imaging suppliers.
EU MDR classification of rescue robots as Class III active implantable equivalents is extending conformity assessment timelines for vendors seeking defense and civil contracting in Europe. The regulation imposes clinical-equivalence documentation requirements that diverge from ISO 9001 quality management norms. Manufacturers with established Nordic manufacturing bases are absorbing these compliance costs more efficiently than new entrants.
Harbor authorities are consolidating procurement through multi-year framework agreements that bundle maintenance, training, and periodic technology refresh. This model displaces transactional equipment purchases and concentrates vendor relationships with firms offering integrated lifecycle support. The shift is most visible in Mediterranean port clusters where municipal budget constraints favor operational expenditure structures over capital deployment.
Underwater Rescue Robot Market Segmentation
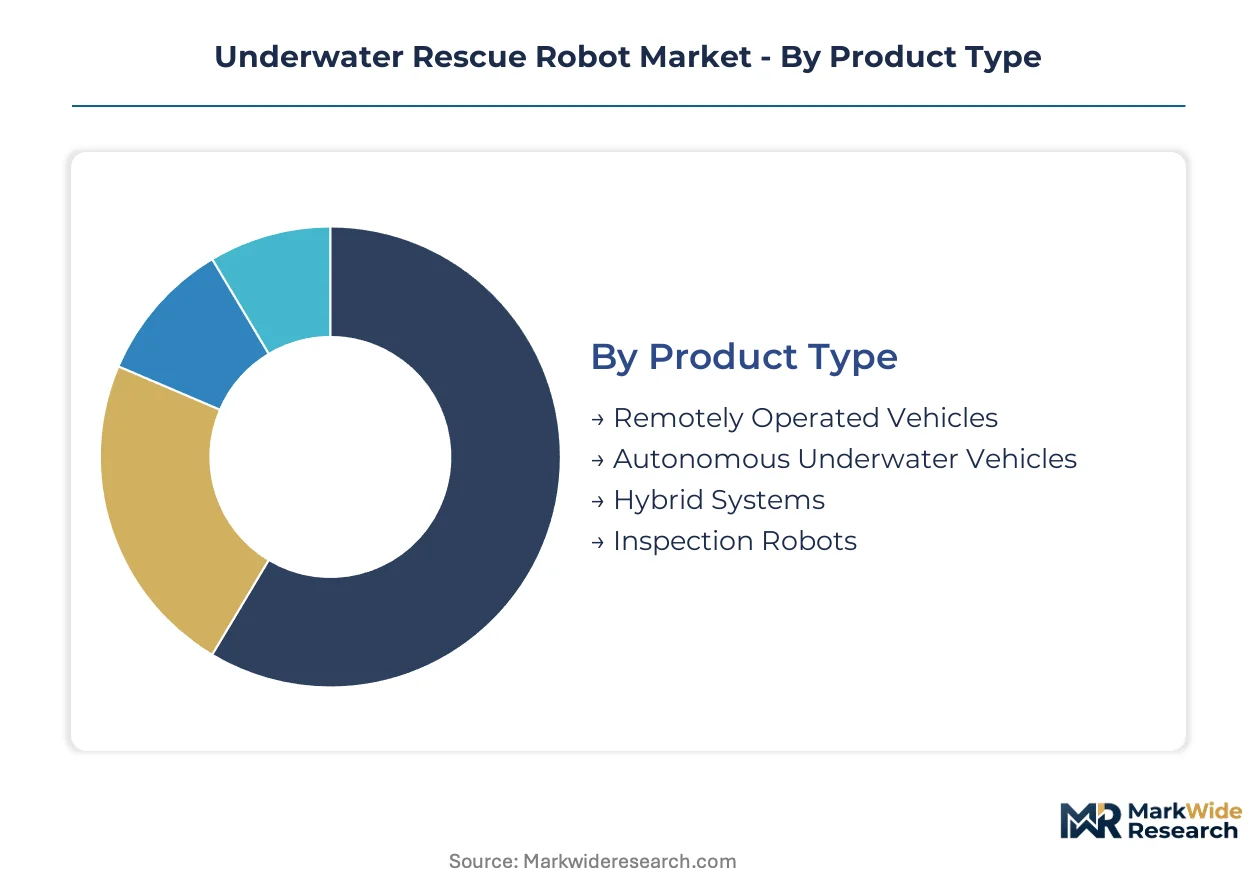
Segmentation in underwater rescue robotics reveals how procurement priorities diverge across operational depths, autonomy levels, and institutional buyers. Product architecture choices cascade through technology sourcing, certification pathways, and lifecycle cost structures.
Product Type:
Supply concentration in pressure-rated components and precision thruster manufacturing favors vendors with captive Nordic or Japanese production bases.
- Remotely Operated Vehicles:Tethered electromechanical platforms with real-time surface control dominate municipal harbor authorities and shallow-water salvage operations. Japan's METI-certified systems concentrate procurement from domestic shipyards responding to coastal disaster mandates.
- Autonomous Underwater Vehicles:Untethered platforms with pre-programmed mission profiles extend operational range beyond communication cable limits. NOAA and Coast Guard modernization programs in the United States prioritize these systems for deep-water search grids below 6,000 meters.
- Hybrid Systems:Architectures enabling supervised-to-unsupervised mode transitions capture expanding margin pools as navies demand operational flexibility without hardware swaps.
- Inspection Robots:Compact platforms optimized for structural assessment and confined-space penetration serve offshore platform operators with rapid-deployment requirements.
Remotely Operated Vehicles absorb the bulk of installed capacity; Hybrid Systems are expanding most quickly.
Technology:
Cost tier stratification separates premium sensor fusion stacks from standardized acoustic imaging packages, with AI integration commanding substantial development premiums.
- Sonar Imaging:Acoustic sensing arrays generating bathymetric and object-detection data constitute the baseline perception layer for most operational deployments.
- LiDAR Mapping:Optical distance measurement systems provide centimeter-scale precision in turbidity-controlled environments, penetrating markets where water clarity permits.
- Robotic Manipulation:Multi-degree-of-freedom manipulator arms with force feedback enable physical intervention for object recovery and entanglement resolution.
- AI Navigation:Neural path-planning algorithms processing real-time sensor feeds are climbing the fastest as operators eliminate surface tether dependence for extended missions.
- Wireless Control:Acoustic and optical communication links for untethered command transmission face FCC equipment authorization constraints in United States deployments.
Sonar Imaging retains the largest installed base; AI Navigation is gaining share fastest among new procurements.
Application:
Volume concentration in civil maritime authorities contrasts with margin concentration in naval and deep-water commercial contracts requiring specialized certification.
- Search & Recovery:Personnel and object location missions in submerged environments drive procurement from coast guard fleets and municipal harbor authorities.
- Deep Sea Inspection:Infrastructure assessment at abyssal depths requires pressure-rated platforms with extended endurance, absorbing capital from offshore energy operators.
- Environmental Monitoring:Long-duration data collection for marine ecosystem assessment attracts research funding from oceanographic institutions.
- Incident Response:Rapid-deployment configurations for maritime accidents and submarine emergencies command premium pricing from naval procurement channels.
Search & Recovery absorbs the bulk of installed capacity; Incident Response carries the steepest expansion trajectory in defense contracting.
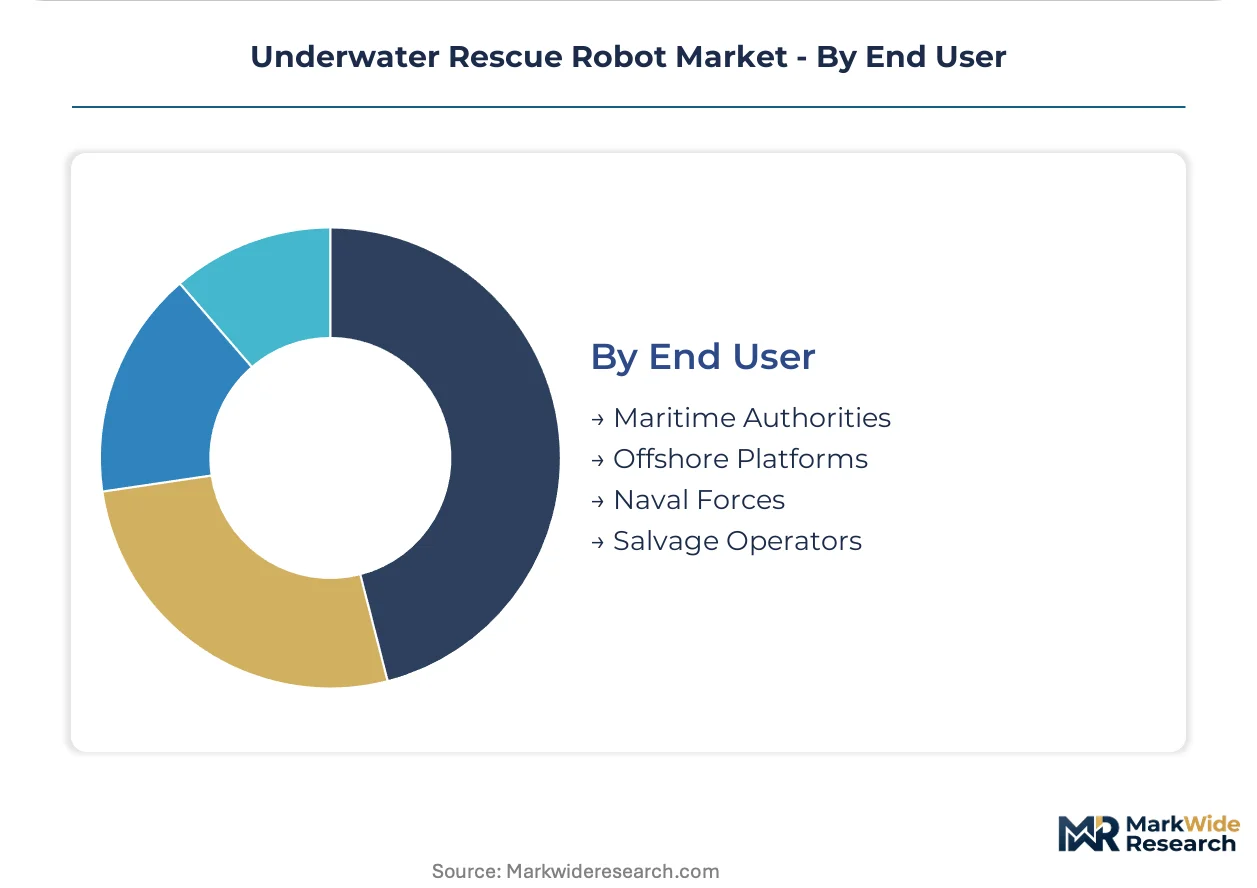
End User:
Customer type determines procurement rhythm, with naval programs running multi-year development cycles and salvage operators demanding immediate equipment availability.
- Maritime Authorities:Coast guard and harbor police fleets prioritize interoperability with existing vessel infrastructure and multi-agency response protocols.
- Offshore Platforms:Oil and gas installation operators require inspection-class systems with rapid turnaround for regulatory compliance and structural integrity verification.
- Naval Forces:Military procurement channels fund dual-use mine-countermeasure derivatives that transfer technology into civil rescue configurations.
- Salvage Operators:Commercial recovery firms demand leased fleet access and subscription-based equipment pools to minimize capital deployment.
Maritime Authorities absorb the bulk of installed capacity; Salvage Operators are expanding most quickly through operational expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's coastal special economic zones for maritime technology concentrate underwater rescue robot development, drawing METI-certified manufacturers to Yokohama and Kobe harbor clusters. Tax incentives for autonomous vessel R&D accelerate domestic procurement timelines.
United States
NOAA deep-water recovery programs and Coast Guard modernization drive demand for 6,000-meter-rated autonomous systems. FCC equipment authorization governs wireless control frequencies for all US-deployed platforms. Boston and San Diego harbor technology clusters absorb federal contracting capital for extended-range search missions.
Japan
METI protocols for autonomous underwater vehicle certification compress municipal procurement cycles for coastal disaster response. The regulator mandates domestic testing standards that shape product development timelines for regional vendors. Yokohama shipyards and Kobe maritime technology parks concentrate production of shallow-water ROV systems for harbor authorities.
Norway
Arctic search coverage gaps in the Norwegian Coast Guard fleet create first-mover demand for ice-rated autonomous platforms. The Norwegian Maritime Authority coordinates with NATO standardization agreements for subsea rescue interoperability. Stavanger and Bergen offshore technology clusters develop pressure-rated platforms for dual-use mine-countermeasure applications.
United Kingdom
Naval procurement for explosive ordnance disposal channels technology transfer into civil rescue configurations. The Maritime and Coastguard Agency adopts ISO 9001-aligned quality protocols that diverge from EU MDR clinical-equivalence requirements. Plymouth and Aberdeen subsea engineering hubs test optical-acoustic sensor fusion stacks for thirty-percent payload reduction.
Australia
Offshore energy operators in the Bass Strait require rapid-deployment inspection robots for regulatory compliance and structural integrity verification. The Australian Maritime Safety Authority funds long-endurance autonomous systems for search grids in the Timor Sea. Perth and Sydney harbor technology clusters develop leased fleet models for municipal subscription-based equipment access.
Underwater Rescue Robot Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Large maritime technology groups leverage captive Nordic or Japanese manufacturing bases to sustain multi-year naval procurement relationships. Mid-scale autonomous system developers occupy the hybrid architecture segment. Strategic moves concentrate on M&A for acoustic positioning capabilities and partnerships for battery chemistry qualification under diverging national standards.
Among Nordic-based maritime technology groups, Kongsberg Maritime AS and Saab Seaeye Ltd. exemplify the diversified conglomerate archetype with integrated lifecycle support offerings. ECA Group S.A.S. represents the specialized defense-civil pivot model, anchoring technology transfer pathways from naval mine-countermeasure programs. These three occupy positions where EU MDR compliance costs and METI certification timelines filter competitive entry.
| Leading Market Players |
|---|
| Bluefin Robotics, Inc. |
| Deep Trekker Inc. |
| Oceaneering International, Inc. |
| Teledyne Marine Services, Inc. |
| Kongsberg Maritime AS |
| ECA Group S.A.S. |
| Aquabotix Technology Corp. |
| Fujian Oceanalpha Marine Technology Co., Ltd. |
| Saab Seaeye Ltd. |
| Others |
Pricing and Supply Chain Analysis
EU REACH compliance on pressure-hull coatings and battery chemistries gates qualified supply for European maritime authorities and anchors premium-tier pricing access for vendors with established Nordic manufacturing bases. Buyers absorbing these compliance costs demand corresponding performance guarantees and extended lifecycle support, compressing margins for unprepared competitors.
Pricing Analysis
Short lead-time premiums dominate municipal harbor procurement, with Japan's METI-certified systems commanding substantial markups over spot inventory from non-certified vendors. Three-tier pricing structure across premium, standard, and economy levels separates deep-rated autonomous platforms from shallow-water ROVs and inspection-class rentals. Cost compression in titanium alloy and ceramic composite inputs is intensifying because aerospace demand fluctuations squeeze margins on 6,000-meter-rated systems. Salvage operators leasing equipment pools exhibit highest price sensitivity, while naval procurement channels prioritize capability over unit economics.
Supply Chain Analysis
Japan's domestic-content mandates for METI certification reshape sourcing, compelling foreign vendors to establish Yokohama or Kobe harbor partnerships. High-density thruster motors and precision acoustic transducers draw from supplier bases concentrated in Germany and Japan, with lithium-sulfur battery formulations tethered to EU REACH qualification timelines. Single-source vulnerability in pressure-rated ceramic composites exposes vendors to aerospace sector demand spikes. Distribution runs through multi-year framework agreements bundling maintenance and technology refresh, displacing transactional equipment purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. EU MDR classification of rescue robots as Class III active implantable equivalents creates a barrier-to-entry moat that filters competitive pressure toward established Nordic and Japanese manufacturers with absorbed certification infrastructure.
For Market Incumbents: Cement multi-year naval procurement relationships by expanding captive Nordic manufacturing capacity for pressure-rated components. Deepen backward integration into high-density thruster motor production to offset supplier concentration risk from German and Japanese sources. EU MDR documentation requirements favor incumbents with existing clinical-equivalence filing experience over emerging entrants lacking regulatory affairs scale.
For New Entrants and Emerging Players: Launch via leased fleet models targeting municipal harbor authorities in Mediterranean port clusters where operational expenditure structures displace capital deployment barriers. Arctic search coverage gaps in Norwegian and Canadian coast guard fleets represent the most penetrable geography for ice-rated autonomous systems without established vendor relationships. Partner with established battery chemistry qualifiers to bypass EU REACH timeline disadvantages.
For Investors and Strategic Acquirers: Japan's acceleration of coastal special economic zone tax incentives for autonomous vessel R&D is the leading indicator that domestic procurement timelines will compress favoring regional production footprints. Over the projection horizon, acquisition targets should profile as mid-scale hybrid architecture specialists with METI certification progress and acoustic positioning software stacks. Watch for FCC equipment authorization backlog clearance as signal of US procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Positioning Acquisition | Absorbs mission-critical sensor fusion capabilities from standalone imaging suppliers facing convergence pressure. |
| Arctic Platform Certification | Positions vendors for Norwegian Coast Guard first-mover contracts addressing underpenetrated ice-rated search gaps. |
| Battery Chemistry Partnership | Accelerates EU REACH qualification timelines for solid-state electrolyte formulations constrained by regulatory limits. |
| Leased Fleet Model Launch | Reduces capital barriers for Spanish and Italian municipal harbor authorities testing subscription-based equipment access. |
| Dual-Use Naval Technology Transfer | Channels mine-countermeasure R&D from explosive ordnance disposal programs into civil rescue configurations. |
Research Methodology
Trade publications, customs databases, and regulatory filing repositories formed the secondary backbone, supplemented by primary interviews with coast guard procurement officers, naval mine-countermeasure program directors, subsea engineering firm executives, and harbor authority fleet managers. Bottom-up vendor shipment tracking and top-down maritime authority budget allocation analysis were triangulated against METI certification timelines and NOAA modernization program disclosures.
Historical trendline analysis of autonomous underwater vehicle procurement cycles informed the analytical framework across the analysis window, with segmentation modeled by product architecture, autonomy level, operational depth rating, and end-user institutional type. CAGRs were derived from installed base replacement rates and technology refresh cadences observed in framework agreement structures, incorporating AI navigation algorithm maturity curves and pressure-hull material cost trajectories as industry-specific forecast inputs.
Tariff exposure on German and Japanese precision components, divergence in national safety standards, and battery chemistry regulatory restriction are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Underwater Robot Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
North America Cloud Robotics Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
North America Service Robotics Market