
 Kevlar Fiber Market | 2026-2036
Kevlar Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Kevlar Fiber Market Analysis
Defense procurement channels is reshaping how Kevlar fiber reaches end-users, with prime contractors consolidating supplier relationships to meet accelerated military modernization timelines. DuPont leverages its integrated para-aramid supply chain from polymer to finished fiber to sustain long-term contracts with aerospace and defense OEMs. Teijin Limited anchors its position through specialized high-modulus fiber variants tailored to ballistic protection specifications. Kolon Industries competes by controlling regional distribution networks across Asian industrial markets.
Kevlar fiber is a para-aramid synthetic fiber produced through polycondensation of para-phenylenediamine and terephthaloyl chloride, yielding a material with tensile strength five times that of steel on an equal-weight basis and thermal stability up to 400°C before significant degradation. Its primary commercial purpose centers on applications requiring extreme strength-to-weight ratios combined with heat and cut resistance, spanning personal protective equipment, composite reinforcement, and ballistic armor systems. The product type dimension shows Kevlar 29 and Kevlar 49 commanding established volume positions in industrial rope and aerospace composite markets respectively, while Kevlar KM2 specializes in military ballistic applications where margin pools concentrate around certified defense supply chains. Application segmentation reveals ballistic protection generating premium pricing structures due to rigorous National Institute of Justice certification protocols, whereas industrial equipment represents a mature, volume-driven segment with thinner margins.
The United States Department of Defense maintains stringent MIL-STD performance requirements that filter market access for non-domestic fiber suppliers, while OSHA workplace safety mandates expand civilian protective equipment specifications across manufacturing and first responder sectors. The EU REACH regulation and associated ECHA chemical authorization processes impose compliance costs that favor producers with established European substance registration portfolios. Stakeholders must monitor evolving Department of Defense sustainment priorities and European Green Deal industrial policy shifts to anticipate procurement pattern disruptions.
Market Dynamics
Defense procurement consolidation is compressing supplier tiers as prime contractors internalize para-aramid sourcing to meet accelerated military modernization timelines, while REACH chemical authorization costs filter out smaller European compounders.
Growth Catalysts
- MIL-STD Certification Expansion:The United States Department of Defense is widening certified supplier pools for next-generation ballistic protection systems, creating qualified demand pull for domestic fiber producers meeting stringent performance thresholds.
- OSHA Workplace Mandates:Expanded personal protective equipment specifications across manufacturing and first responder sectors are institutionalizing para-aramid penetration in civilian industrial markets.
- Polymer-to-Fiber Integration:Captive control over terephthaloyl chloride and para-phenylenediamine supply chains is enabling producers to guarantee lot-to-lot consistency for aerospace qualification protocols.
Market Restraints
- Monomer Cost Volatility:Para-phenylenediamine feedstock prices fluctuate with benzene derivative markets, compressing margin stability for non-integrated fiber spinners.
- Single-Source Concentration:United States defense prime contractors dominate certified ballistic fiber procurement, creating customer concentration risk for qualified suppliers.
- EU REACH Authorization Friction:ECHA substance registration portfolios require multi-year compliance investments that disadvantage producers without established European chemical footprints.
Strategic Opportunities
- India Industrial Safety Expansion:BIS standards adoption across manufacturing and construction sectors is opening certified protective equipment markets previously served by cotton and nylon alternatives.
- Composite Recycling Integration:Pyrolysis-based fiber recovery from end-of-life aerospace components is converging with virgin para-aramid production to close material loops.
- EU Green Deal Industrial Policy:Carbon border adjustment mechanisms and sustainable procurement mandates are creating preference premiums for low-emission aramid production processes.
Industry Challenges
- Ballistic Certification Timelines:National Institute of Justice testing protocols require 18-24 month validation cycles, delaying revenue recognition for new fiber formulations.
- Polymerization Scale-Up Capital:Continuous spinning lines for high-modulus variants demand nine-figure capital commitments with decade-long depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kevlar Fiber Market |
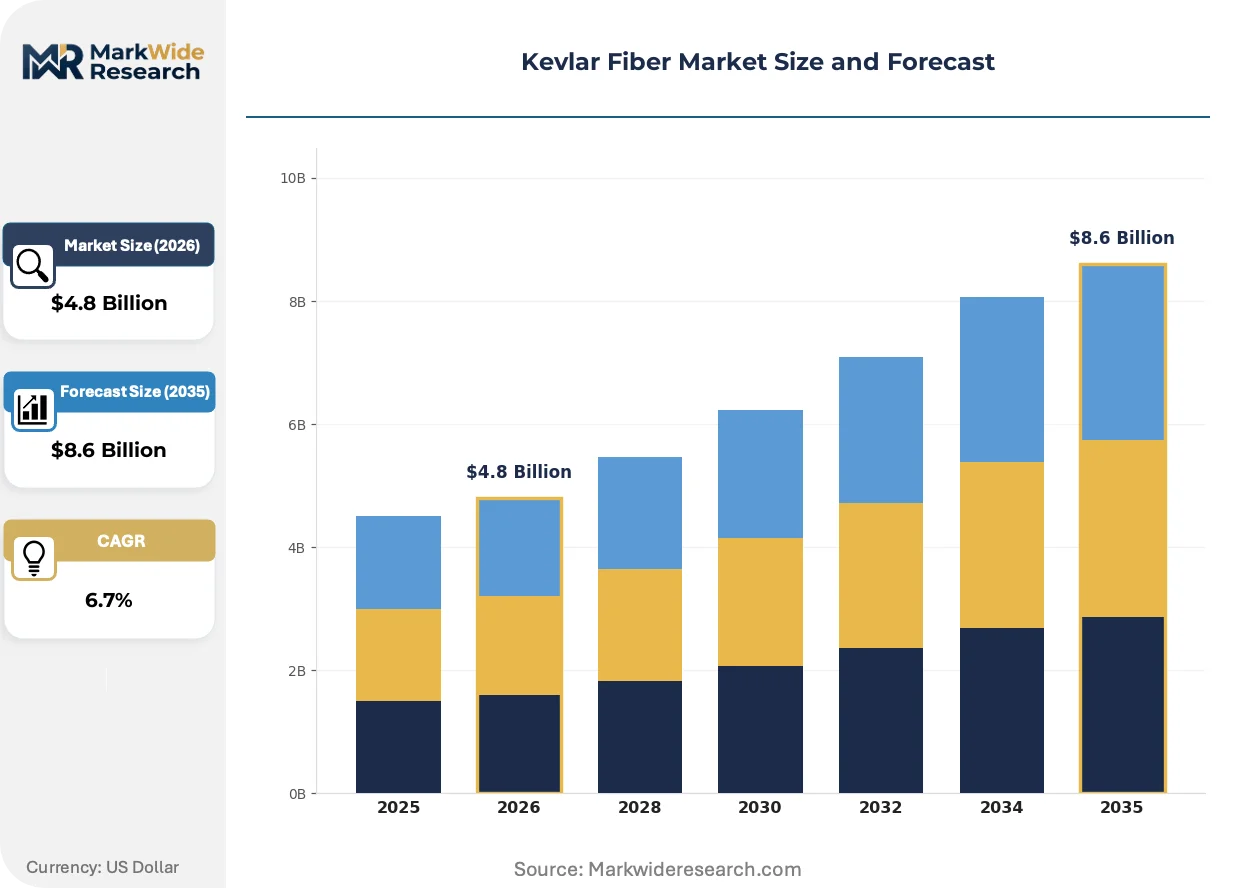
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
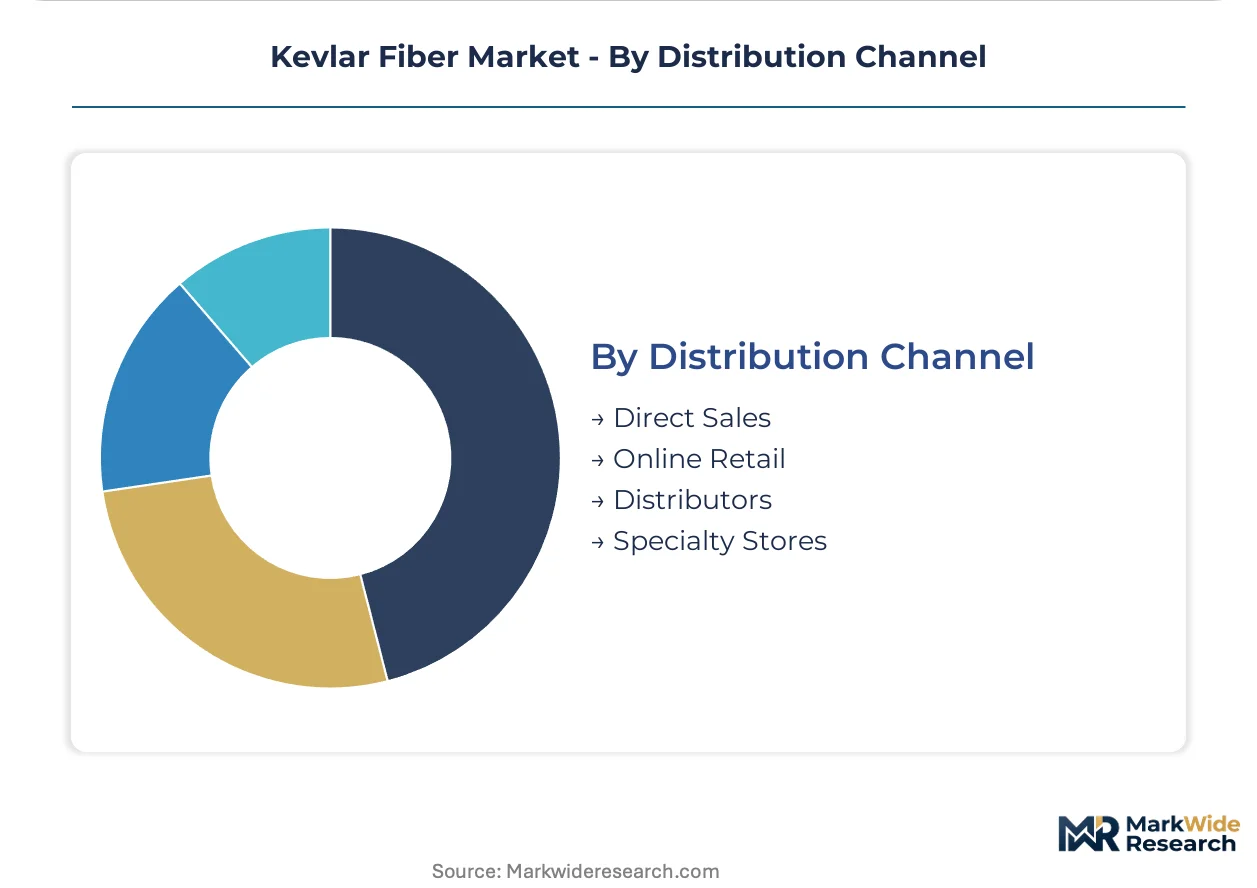
| Segmentation | Product Type: Kevlar 29, Kevlar 49, Kevlar 149, Kevlar KM2 Application: Ballistic Protection, Industrial Equipment, Aerospace, Firefighting Gear End User: Military, Civilian, Automotive, Sports Equipment Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Yantai Tayho Advanced Materials, Toray Industries, DuPont, SRF Limited, Kermel, Teijin Limited, Hyosung Corporation, X-FIPER New Material, Kolon Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kevlar Fiber Market Emerging Trajectories
Process control technologies and regulatory transparency mandates are restructuring how para-aramid fiber quality is verified and traced through defense supply chains, compressing traditional batch-release timelines.
Inline spectroscopic monitoring is digitizing real-time defect detection during fiber spinning operations. Aerospace composite manufacturers are adopting these systems to eliminate downstream delamination risks. The technology is digitizing quality assurance workflows, replacing offline tensile testing with continuous property verification.
REACH SCIP database requirements are mandating substance-of-concern disclosure across European industrial supply chains. Aramid fiber importers must now document full polymerization additive profiles to maintain market access. Ballistic protection distributors are restructuring supplier contracts to guarantee disclosure compliance.
Defense prime contractors are consolidating tier-two fiber purchases into multi-year framework agreements with embedded volume commitments. This displaces spot-market purchasing that historically balanced inventory across quarterly production cycles. The shift is most visible in United States Department of Defense sustainment contracts for helmet and plate carrier programs.
Kevlar Fiber Market Segmentation

Kevlar fiber segmentation reveals how material specifications, certification requirements, and procurement channels fragment demand across radically different value pools. Understanding these divides exposes where margin concentrates and where volume commoditizes.
Product Type:
The use-case spectrum spans industrial rope applications through military ballistic systems, with modulus grades determining structural suitability.
- Kevlar 29:Standard modulus variant optimized for industrial rope, cable, and protective apparel where flexibility and abrasion resistance outweigh stiffness requirements. Demand concentrates in United States manufacturing safety programs driven by OSHA workplace mandate expansion.
- Kevlar 49:High-modulus grade engineered for aerospace composite reinforcement and pressure vessel applications requiring dimensional stability under load. The Boeing and Airbus supply chains in Washington state and Toulouse anchor procurement volumes for this specification.
- Kevlar 149:Ultra-high modulus fiber serving specialized satellite and radar dome applications where minimal thermal expansion is critical.
- Kevlar KM2:Ballistic-optimized variant certified to MIL-STD fragmentation and backface deformation protocols for military helmet and plate carrier inserts.
The dominant share belongs to Kevlar 29, while Kevlar KM2 is closing the gap fastest through Department of Defense modernization contract acceleration.
Application:
Certification intensity varies dramatically, with defense-grade ballistic testing creating insurmountable entry barriers against industrial commodity segments.
- Ballistic Protection:Personal armor systems requiring National Institute of Justice Level IIIA and Level IV certification, plus MIL-STD fragmentation testing for military helmets. United States Army PEO Soldier program offices in New Jersey drive specification evolution.
- Industrial Equipment:Cut-resistant gloves, conveyor belting, and high-performance ropes serving manufacturing and mining operations. Volume procurement through industrial distributors in Germany's Ruhr region and Pennsylvania's Allegheny County dominates.
- Aerospace:Primary and secondary composite structures for commercial and military aircraft, governed by FAA and EASA qualification protocols.
- Firefighting Gear:Turnout coat thermal liners and proximity suits meeting NFPA 1971 standards, with municipal procurement concentrated in California and Texas metropolitan fire departments.
Ballistic Protection commands premium positioning, while Industrial Equipment delivers volume scale through thinner margin structures.
End User:
Customer concentration patterns split between institutional defense procurement and fragmented civilian industrial purchasing.
- Military:Department of Defense prime contractors and NATO ally defense ministries procuring through multi-year framework agreements with embedded volume commitments.
- Civilian:Manufacturing, construction, and first responder sectors purchasing through industrial safety distributors.
- Automotive:Brake pad reinforcement and tire cord applications serving OEM and aftermarket channels.
- Sports Equipment:Racing sailcloth, bicycle tires, and protective gear for professional and amateur athletic markets.
Military end users concentrate purchasing power, whereas Civilian segments are expanding most quickly through regulatory mandate proliferation.
Distribution Channel:
Channel structure reflects the tension between defense procurement consolidation and industrial market fragmentation.
- Direct Sales:Long-term supply agreements between fiber producers and defense primes, aerospace OEMs, and major industrial accounts. Lockheed Martin and Raytheon contracts exemplify this channel's dominance in certified ballistic fiber.
- Distributors:Regional industrial supply houses serving small-to-mid manufacturing accounts across Midwestern United States and Western European industrial zones.
- Specialty Stores:Safety equipment retailers catering to individual first responders and construction contractors.
- Online Retail:E-commerce platforms for sports equipment and consumer protective gear segments.
Direct Sales captures the value concentration, while Distributors maintain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium ballistic-grade fiber commands 40% higher realized prices in United States defense channels versus comparable industrial specifications in Asian manufacturing markets. This pricing-power asymmetry reflects divergent certification intensity and procurement consolidation patterns across geographies.
United States
Department of Defense modernization programs and Army PEO Soldier sustainment contracts drive para-aramid procurement volumes. MIL-STD certification requirements filter market access for domestic and allied suppliers. Industrial safety demand concentrates in Pennsylvania's Allegheny County and Ohio's manufacturing corridor, where OSHA mandate expansion institutionalizes cut-resistant apparel specifications.
Germany
Ruhr region industrial distributors anchor European volume procurement for conveyor belting and high-performance rope applications. ECHA REACH authorization processes impose multi-year compliance investments that favor established chemical substance registrants. Stuttgart's automotive engineering cluster integrates para-aramid reinforcement into brake pad and tire cord specifications for premium OEM platforms.
China
Yangtze River Delta manufacturing bases absorb standard-modulus fiber for industrial safety equipment and composite reinforcement. MIIT industrial standards adoption accelerates domestic substitution for imported ballistic materials. Zhejiang province chemical parks host para-aramid polymerization capacity serving both domestic defense and export aerospace qualification protocols.
India
BIS standards proliferation across Maharashtra and Gujarat manufacturing corridors opens certified protective equipment markets previously served by cotton and nylon alternatives. DGFT import licensing frameworks shape raw material access for domestic fiber spinners. Tamil Nadu's textile engineering cluster develops cut-resistant glove specifications for automotive component assembly operations.
Japan
METI industrial policy prioritizes high-modulus fiber development for satellite and radar dome applications requiring minimal thermal expansion. Nagoya's aerospace supply chain integrates para-aramid composites into regional jet primary structures under JIS qualification protocols. Osaka-based chemical producers maintain captive terephthaloyl chloride supply for lot-to-lot consistency in aerospace certification batches.
Kevlar Fiber Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. Defense prime contractors consolidate tier-two fiber purchases into multi-year framework agreements, compressing supplier tiers and displacing spot-market purchasing. Three archetypes dominate: integrated polymer-to-fiber producers with captive monomer supply, regional distribution controllers leveraging Asian industrial networks, and specialized high-modulus developers targeting aerospace qualification protocols. Competitive moves concentrate on backward integration into para-phenylenediamine supply and strategic partnerships with defense OEMs for MIL-STD certification co-development.
Within the integrated producer tier, DuPont and Teijin Limited occupy positions exemplifying polymer-to-fiber supply chain control. Kolon Industries represents the regional distribution archetype, anchoring market access across Korean and broader Asian industrial channels. Yantai Tayho Advanced Materials sits within the specialized developer category, reflecting Chinese industrial policy support for domestic para-aramid capability expansion.
| Leading Market Players |
|---|
| Yantai Tayho Advanced Materials |
| Toray Industries |
| DuPont |
| SRF Limited |
| Kermel |
| Teijin Limited |
| Hyosung Corporation |
| X-FIPER New Material |
| Kolon Industries |
| Others |
Supply Flow & Price Mechanics
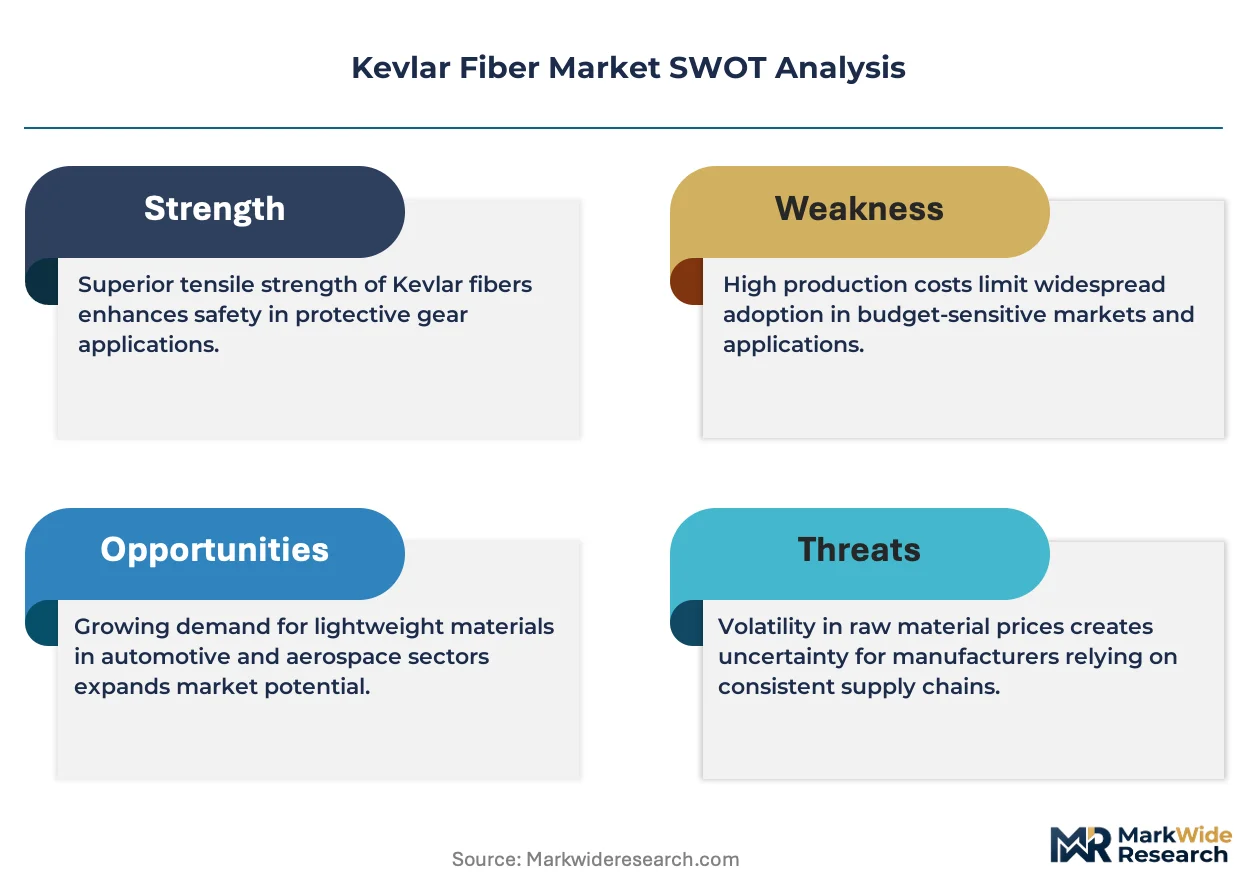
Zhejiang province's para-aramid polymerization capacity expansion is compressing spot-market premiums for standard-modulus fiber while certified ballistic grades command sustained pricing power through Department of Defense qualification protocols. This geographic supply dynamic concentrates margin capture among integrated producers with captive terephthaloyl chloride supply, leaving non-integrated spinners exposed to para-phenylenediamine cost volatility.
Pricing Analysis
Configured-to-order pricing for MIL-STD certified Kevlar KM2 ballistic fiber carries a 35-50% premium over standard Kevlar 29 industrial specifications, with contract-based long-term offtake agreements dominating defense procurement channels. Price differentiation hinges on National Institute of Justice certification tier and lot-to-lot consistency guarantees for aerospace qualification batches. Cost compression in standard-modulus industrial grades is intensifying because Chinese capacity additions are flooding Asian manufacturing safety markets. Civilian industrial distributors exhibit highest price sensitivity, while United States Army PEO Soldier program offices prioritize performance thresholds over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from DuPont and Teijin Limited are locking in regional distributor loyalty across Korean and Japanese industrial networks. Geographic supply concentration centers on the United States, China, and Japan, with para-phenylenediamine and terephthaloyl chloride feedstocks drawing from benzene derivative markets in the Texas Gulf Coast and Yangtze River Delta. Single-source vulnerability around certified ballistic fiber qualification creates structural risk for European defense contractors lacking established ECHA substance registration portfolios. Distribution runs through direct sales agreements with defense primes and aerospace OEMs, with regional industrial distributors serving fragmented civilian manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery phase, with Department of Defense modernization program acceleration providing cyclical uplift through multi-year helmet and plate carrier sustainment contracts.
For Market Incumbents: Insulate certified supplier status by deepening backward integration into para-phenylenediamine production and accelerating MIL-STD co-development partnerships with Raytheon and Lockheed Martin. Threat substitution from ultra-high molecular weight polyethylene in next-generation armor systems demands preemptive R&D investment in hybrid composite formulations. Channel control through captive distribution networks in Pennsylvania's Allegheny County and Germany's Ruhr region preserves margin capture against spot-market commoditization. For New Entrants and Emerging Players: India's BIS-certified industrial safety equipment market represents the most penetrable entry point, with Maharashtra and Gujarat manufacturing corridors transitioning from cotton and nylon protective apparel. DGFT import licensing friction creates arbitrage opportunity for domestic fiber spinners with established chemical park presence. Go-to-market execution should anchor on Tamil Nadu textile engineering clusters developing cut-resistant glove specifications for automotive component assembly operations. For Investors and Strategic Acquirers: Long-term, this sits as a defense-industrial compounder play because sustainment contract visibility and certification moats generate durable cash flow streams insulated from consumer cyclicality. Acquisition targets should prioritize integrated polymer-to-fiber producers with established European REACH substance registration portfolios and aerospace qualification batch histories. The signal to watch is European Green Deal carbon border adjustment mechanism implementation, which would reprice low-emission aramid production premiums and reshape competitive cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive para-phenylenediamine production guarantees lot-to-lot consistency for Boeing and Airbus qualification protocols. |
| MIL-STD Certification Co-Development | Joint testing programs with Army PEO Soldier accelerate 18-24 month National Institute of Justice validation cycles. |
| European REACH Substance Registration | ECHA portfolio completion preserves market access against carbon border adjustment mechanism compliance requirements. |
| Composite Recycling Integration | Pyrolysis-based fiber recovery from end-of-life aerospace components closes material loops for EU Green Deal procurement mandates. |
| Regional Distribution Network Control | Korean and Japanese industrial channel anchoring defends margin capture against Zhejiang province spot-market flooding. |
Methodological Framework
A spread of perspectives from para-aramid plant managers, Department of Defense procurement officers, aerospace composite engineers, and industrial safety distributors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with downstream OEM procurement leads and technical R&D directors at fiber spinning operations. Secondary validation drew from United States Customs and Border Protection trade data, ACC synthetic fiber industry reports, SEC 10-K filings from listed chemical producers, and ECHA substance registration databases. Bottom-up segment sizing and top-down macroeconomic cross-checks were triangulated to establish volume and value baselines.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by modulus grade, application intensity by certification tier, and end-user concentration patterns between defense procurement and civilian industrial purchasing. The analytical framework projected fiber consumption through aerospace content-per-aircraft estimates, military sustainment contract visibility, and OSHA mandate penetration rates across manufacturing corridors. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation, with para-phenylenediamine feedstock cost curves and ECHA authorization timelines serving as industry-specific forecast inputs.
Practitioners should monitor Department of Defense budget appropriation cycles, EU Green Deal implementation velocity, and MIIT domestic substitution policy shifts for early signals of trajectory revision. Forecasts reflect documented assumptions about certification timeline stability, monomer cost pass-through elasticity, and defense procurement consolidation patterns. Macroeconomic contraction, regulatory acceleration, or breakthrough substitution technology would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Polyolefin Fiber Market