
 Melt Spun Fibers Market | 2026-2036
Melt Spun Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Melt Spun Fibers Market Analysis
Asset-light leasing models for extrusion equipment is reconfiguring capital barriers, enabling mid-scale entrants to challenge established producers without owning full production lines. Toray Industries leverages backward integration into polymer resin to sustain margin control across polyamide and polyester grades. DuPont de Nemours anchors its position through R&D intensity in high-performance fiber architectures. Invista competes on geographic dominance in nylon 6,6 supply chains across North America and Asia.
Melt spun fibers are thermoplastic filaments produced by extruding molten polymer through spinnerets at controlled temperatures and draw ratios, yielding continuous strands with tunable tenacity and denier for industrial and consumer applications. Polyester commands the largest volume share due to cost-performance balance in textiles and packaging reinforcement, while biodegradable grades represent the fastest-expanding margin pool as brand sustainability mandates intensify. Nonwovens applications absorb substantial polypropylene throughput, driven by hygiene and medical disposables demand.
EPA emissions standards and REACH chemical registration frameworks constrain feedstock choices and waste discharge protocols for melt spun fiber manufacturers in the United States and European Union. China's GB standards and dual carbon goals impose energy-intensity ceilings on petrochemical-derived filament production. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance costs and qualify for preferential market access.
Market Dynamics
The Melt Spun Fibers Market is being fundamentally restructured by the collision of automotive lightweighting mandates and the geographic consolidation of petrochemical-to-textile production corridors, which together are rewiring capital deployment and supplier qualification pathways.
Growth Catalysts
- Automotive Upholstery Lightweighting:OEM specifications for interior mass reduction are pulling high-tenacity polyester and polyamide filaments into seat fabrics and headliner substrates, displacing heavier woven materials.
- REACH Chemical Disclosure:The European Union's tightened registration requirements are accelerating substitution toward traceable polymer feedstocks, rewarding producers with certified supply chain documentation.
- China's Integrated Petrochemical Hubs:Concentrated production corridors linking refinery output directly to filament extrusion are compressing conversion costs and enabling rapid grade switching for export markets.
Market Restraints
- Crude-Derived Feedstock Volatility:Paraxylene and caprolactam pricing tied to naphtha cracking economics exposes margin stability to petroleum market swings.
- Single-Source Concentration Risk:Nylon 6,6 polymer supply for industrial-grade melt spun fiber remains geographically concentrated in select North American and Asian production basins.
- Biodegradable Performance Gap:PLA and PHA-based alternatives currently fail to match the hydrolytic stability and mechanical tenacity required for automotive and industrial filtration end-uses.
Strategic Opportunities
- India's Technical Textiles Push:The country's PLI scheme for man-made fiber and technical textile production is creating localized incentive structures for extrusion capacity expansion.
- Hygiene Nonwoven Differentiation:Spunbond-meltblown-spunbond composite structures for medical disposables represent an underexploited margin pool as healthcare procurement tightens sterility specifications.
- Chemical Recycling Integration:Pyrolysis-based polymer regeneration is converging with virgin-equivalent filament production, enabling circularity claims that satisfy EU Green Deal procurement criteria.
Industry Challenges
- Process Engineer Scarcity:Specialized expertise in multi-zone temperature control and draw ratio optimization for high-denier industrial filament remains concentrated among aging practitioner cohorts.
- REACH Pre-Registration Timelines:The European Chemicals Agency's extended evaluation windows for novel polymer additives are delaying commercialization of flame-retardant and antimicrobial fiber grades.
- Legacy DCS Integration:Brownfield extrusion lines with proprietary distributed control systems face friction when retrofitting Industry 4.0 sensor networks for real-time denier monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melt Spun Fibers Market |
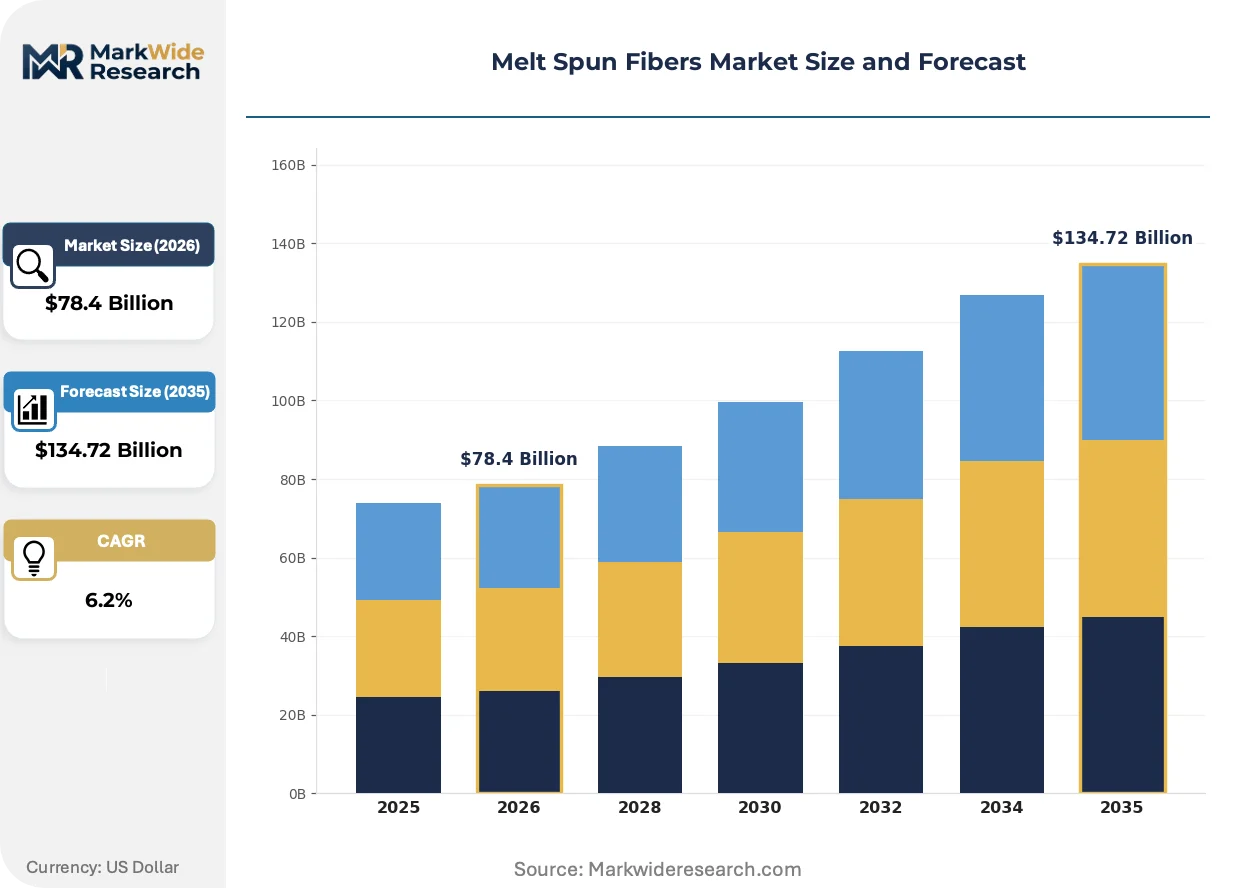
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Polyamide, Acetate End Use Industry: Textiles, Automotive, Geotextiles, Filtration Grade: Standard, High-Strength, Low-Melt, Biodegradable Application: Clothing, Composite Materials, Insulation, Nonwovens |
| Companies Covered | Toray Industries, Inc., Invista, DuPont de Nemours, Inc., Toyobo Co., Ltd., Kolon Industries, Inc., Teijin Limited, BASF, Honeywell International Inc., Mitsubishi Chemical Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melt Spun Fibers Market Emerging Trajectories
Active innovation in melt spun fiber production is compressing development cycles and rewiring competitive advantage around material circularity, process digitization, and regulatory anticipation rather than scale alone.
Bi-component sheath-core spinning technology is collapsing the traditional trade-off between surface functionality and bulk mechanical properties in filament architecture. Medical textile manufacturers are adopting this approach at accelerated qualification timelines to embed antimicrobial agents in sheath layers without compromising core tensile strength. The structural consequence is collapsing the premium commanded by post-treatment finishing processes, as functional performance becomes intrinsic to extrusion.
ECHA's SVHC candidate list expansion under REACH is forcing reformulation of conventional polymer stabilizers and pigment carriers across European supply chains. Industrial fiber producers serving automotive and construction end-uses are substituting halogen-free flame retardants and heavy-metal-free colorants ahead of formal restriction dates. The segment most affected is polypropylene industrial yarn, where legacy additive packages face accelerated obsolescence and replacement qualification costs are concentrating procurement among vertically integrated compounders.
Brand sustainability mandates are compressing supplier qualification cycles and unbundling traditional volume-commitment contracts in favor of certified-cotton-substitute sourcing. Apparel and home textile brands are disintermediating commodity traders to contract directly with extruders holding GRS or OEKO-TEX Chain of Custody documentation. This pattern is most visible in Northern European markets, where retailer consortiums are consolidating preferred supplier lists around traceability-verified polyester and polyamide filament sources.
Melt Spun Fibers Market Segmentation
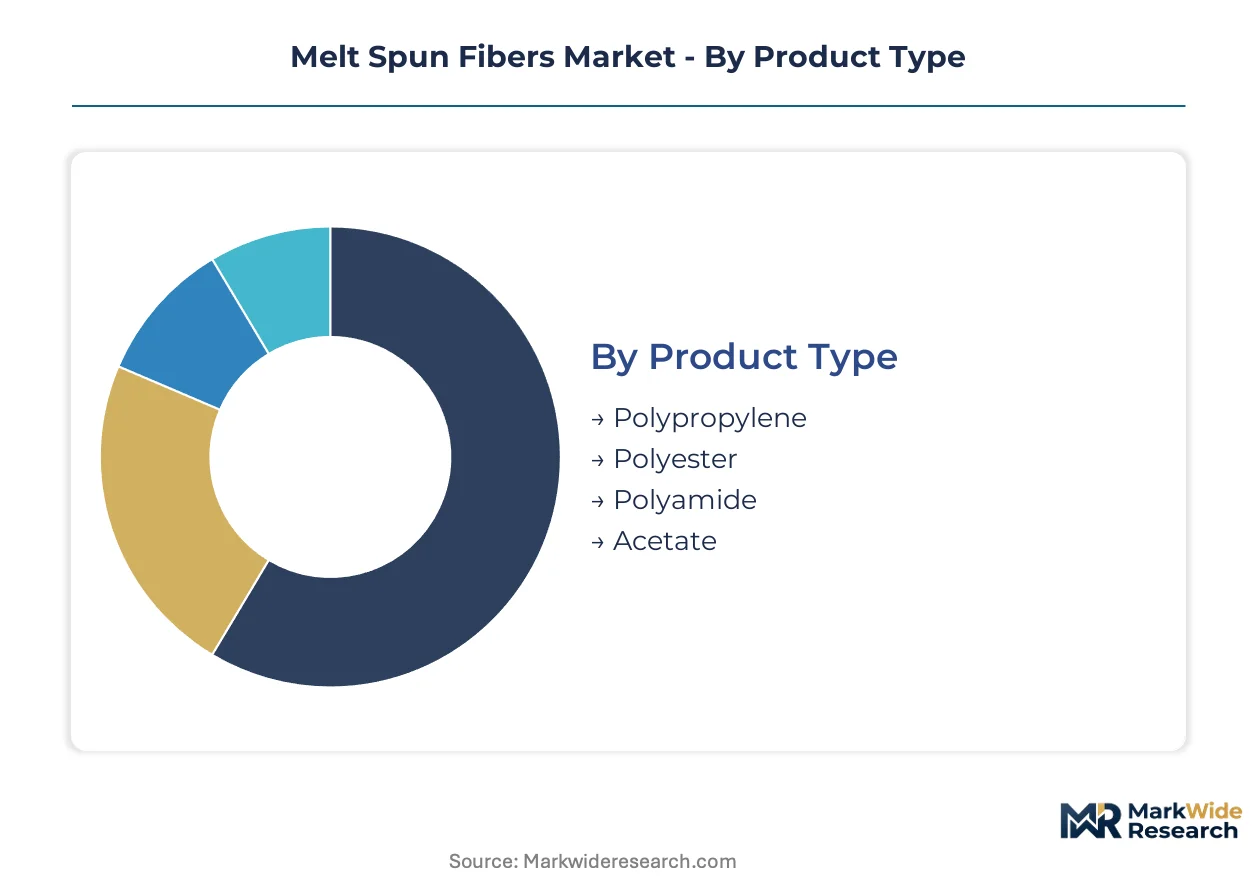
Segmentation in melt spun fibers separates commodity-grade volume from performance-premium pricing, enabling producers to align extrusion configurations with specific mechanical specifications and regulatory compliance requirements across automotive, medical, and industrial end-uses.
Product Type:
Cost tier determines feedstock sourcing strategies and margin architecture across polymer chemistries, with petrochemical integration depth varying sharply by material family.
- Polyester:Polyethylene terephthalate filaments dominate volume throughput due to balanced tenacity-to-cost ratios in apparel and packaging reinforcement applications. Demand concentrates in China's Zhejiang and Jiangsu provinces, where integrated refinery-to-filament corridors compress conversion economics for export-grade POY and FDY yarns.
- Polypropylene:Isotactic polypropylene extrusion yields low-density, chemically resistant filaments optimized for hygiene nonwovens and industrial strapping. Spunbond capacity expansion in India and Southeast Asia is absorbing regional propylene monomer output as hygiene brand procurement localizes.
- Polyamide:Nylon 6 and 6,6 polymers produce high-tenacity filaments for tire cord and airbag fabrics requiring thermal stability above 150°C. Caprolactam supply concentration in North American and North Asian production basins creates geographic dependency for industrial-grade specifications.
- Acetate:Cellulose acetate tow serves cigarette filter and specialty textile applications with controlled denier and crimp retention. Wood pulp sourcing from certified sustainable forestry programs is becoming a procurement qualifier under EU Green Deal supply chain due diligence rules.
Polyester holds installed capacity. Polypropylene is rotating up the share rankings.
End Use Industry:
Application-specific performance thresholds create divergent qualification pathways, with automotive and medical sectors imposing the most stringent certification burdens on extruders.
- Textiles:Apparel and home furnishing applications absorb commodity-grade polyester and polypropylene filaments where hand-feel and dye uptake dominate specification sheets. REACH-compliant additive packages for colorants and UV stabilizers are becoming mandatory for EU-bound finished goods.
- Automotive:OEM upholstery and airbag fabric specifications demand high-tenacity polyamide and polyester with controlled thermal shrinkage for interior safety compliance. NHTSA and ECE R14 regulations govern airbag deployment performance, requiring batch-level traceability from polymer chip to woven substrate.
- Geotextiles:Civil engineering applications utilize UV-stabilized polypropylene for soil reinforcement and drainage matrices in infrastructure projects. China's GB/T 17639 standard and ASTM D4632 govern tensile strength retention under accelerated weathering exposure.
- Filtration:Industrial air and liquid filtration media require precise denier control and surface area optimization for particulate capture efficiency. EPA Method 319 and EN 1822-1 test protocols determine qualification for environmental and HVAC end-uses.
Textiles maintains volume dominance. Automotive is climbing the fastest on value-per-kilogram metrics.
Grade:
Performance tier stratification enables price realization across standardized commodity output and engineered specialty filaments with certified property envelopes.
- Standard:Conventional tenacity filaments serve mass-market textile and packaging applications where specification tolerance bands accommodate wider variation. Price discovery ties directly to PTA and MEG spot market movements for polyester grades.
- High-Strength:Industrial yarn specifications achieve tenacity above 7.5 g/denier through optimized draw ratios and molecular orientation for tire cord and conveyor belt reinforcement. Qualification timelines with tire manufacturers extend 18-24 months for new extrusion line approvals.
- Low-Melt:Bicomponent sheath-core structures with reduced melting point outer layers enable thermal bonding in nonwoven consolidation without adhesive application. Spunbond-meltblown composite lines for medical disposables represent the primary demand concentration.
- Biodegradable:PLA and PHA-based filaments target single-use textile and agricultural mulch applications with compostability certification. Hydrolytic stability limitations currently exclude these grades from automotive and industrial filtration end-uses.
Standard grade commands installed capacity. Biodegradable is gaining share fastest as brand sustainability mandates harden.
Application:
Functional end-use requirements dictate filament architecture from solid round cross-sections to profiled or hollow configurations for thermal and acoustic performance.
- Clothing:Apparel applications prioritize dye affinity, moisture wicking, and tactile properties through profiled and microdenier polyester filaments. Direct-to-garment printing compatibility is emerging as a specification driver for fast-fashion supply chains.
- Composite Materials:Glass-mat reinforced thermoplastic and unidirectional tape applications utilize high-modulus polypropylene and polyester as matrix binders and structural reinforcements. Automotive lightweighting programs are qualifying these materials for interior panel substrates.
- Insulation:Hollow and crimped polyester filaments trap air for thermal and acoustic insulation in building construction and apparel interlinings. California Title 24 energy efficiency standards and similar codes in Germany and Japan drive specification for building envelope applications.
- Nonwovens:Spunbond, meltblown, and spunlace structures consume substantial polypropylene throughput for hygiene, medical, and industrial wipe applications. FDA 21 CFR 177.1520 and ISO 10993 biocompatibility standards govern medical nonwoven qualification.
Clothing retains installed capacity leadership. Nonwovens is rotating up the share rankings on healthcare procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for technical textiles is accelerating extrusion capacity builds. China's dual carbon goals are capping energy intensity in Zhejiang filament corridors. Germany's REACH enforcement is tightening additive disclosure for automotive-grade polymer supply.
China
Integrated petrochemical-to-textile hubs in Zhejiang and Jiangsu provinces compress conversion costs for export-grade POY and FDY yarns. GB standards and dual carbon goals impose energy-intensity ceilings on naphtha-derived filament production. Shaoxing and Suzhou industrial clusters host the densest concentrations of draw-texturing capacity serving global apparel supply chains.
United States
Automotive upholstery lightweighting specifications from Detroit OEMs pull high-tenacity polyester into seat fabric and headliner substrates. EPA emissions standards constrain waste discharge protocols for extrusion lines operating in the Southeast manufacturing belt. The Carolinas textile corridor retains specialized airbag yarn qualification expertise with tire and safety system manufacturers.
Germany
ECHA's SVHC candidate list expansion forces reformulation of polymer stabilizers for industrial fiber serving automotive and construction end-uses. REACH pre-registration timelines delay commercialization of flame-retardant grades. The Rhine-Ruhr chemical complex maintains compounding and masterbatch capabilities for halogen-free additive packages.
India
The PLI scheme for man-made fiber production creates localized incentive structures for extrusion expansion in technical textiles. BIS certification requirements govern tensile specifications for geotextile and filtration applications. Surat and Ahmedabad clusters concentrate draw-texturing and air-jet spinning capacity for domestic apparel and home furnishing markets.
Japan
METI industrial policy supports high-performance fiber R&D for aerospace and medical textile applications. JIS standards govern denier consistency and thermal shrinkage for industrial yarn qualifications. The Nagoya-Tokyo corridor hosts compounders specializing in bicomponent sheath-core structures for medical nonwoven applications.
Melt Spun Fibers Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around three archetypes: petrochemical-integrated resin producers, independent extrusion specialists, and regional compounders serving qualified industrial niches. Dominant competitive moves include backward integration into polymer chip production and geographic expansion through distributed extrusion assets rather than centralized mega-facilities.
Among Asia-Pacific-based integrated producers, Toray Industries, Inc. and Teijin Limited occupy positions representing the resin-to-filament control archetype, while Invista exemplifies the geographic dominance model in nylon 6,6 supply chains. DuPont de Nemours, Inc. anchors the R&D-intensive tier for high-performance fiber architectures. These three names illustrate how competitive advantage separates between feedstock control, regional logistics scale, and materials science depth.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Invista |
| DuPont de Nemours, Inc. |
| Toyobo Co., Ltd. |
| Kolon Industries, Inc. |
| Teijin Limited |
| BASF |
| Honeywell International Inc. |
| Mitsubishi Chemical Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Shaoxing's draw-texturing clusters in Zhejiang province concentrate filament conversion capacity, compressing regional conversion costs and amplifying pricing power for integrated producers serving export-grade POY and FDY yarn markets. This geographic concentration enables rapid grade switching in response to downstream specification shifts, while simultaneously exposing margin stability to naphtha-derived feedstock volatility.
Pricing Analysis
Certification level (OEKO-TEX/GRS/REACH-compliant) creates the primary spread between commodity-grade polyester and premium-positioned sustainable filaments. Three-tier pricing structure across premium, standard, and economy levels reflects performance tenacity, additive package sophistication, and chain-of-custody documentation depth. Cost compression in standard-grade POY yarn is intensifying because China's dual carbon goals are capping energy subsidies for naphtha-cracking corridors. Apparel brand procurement teams exhibit the highest price sensitivity, while automotive Tier 1 suppliers prioritize batch traceability and thermal shrinkage consistency over unit cost.
Supply Chain Analysis
Export-control regimes on advanced spinneret manufacturing technology limit equipment flows from Germany and Japan to emerging extrusion markets, constraining capacity buildout velocity outside established corridors. Raw material supply concentrates in China, South Korea, and Saudi Arabia for purified terephthalic acid and monoethylene glycol feedstocks. Caprolactam for nylon 6,6 industrial yarn draws from North American and North Asian production basins, creating geographic dependency for high-tenacity specifications. Single-source vulnerability in specialty polymer additive compounding represents the dominant structural risk. Distribution runs through integrated petrochemical-to-textile hubs rather than independent trading networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Melt Spun Fibers Market operates as a regulatory-entrenchment story where REACH compliance documentation and automotive qualification timelines create switching costs that protect incumbent positions. This structural advantage rewards early investment in certified supply chain infrastructure.
For Market Incumbents: Build certification moats through accelerated OEKO-TEX and GRS Chain of Custody documentation that exceeds downstream brand mandates by 12-18 months. Capture backward integration into polymer chip production to insulate margin control from paraxylene spot volatility. Threaten emerging entrants by pre-empting capacity in India's PLI-subsidized technical textile corridors. Prioritize R&D investment in bicomponent sheath-core architectures for medical nonwoven applications where qualification timelines extend 24-36 months. For New Entrants and Emerging Players: India's technical textiles push under the PLI scheme represents the most penetrable entry point for mid-scale extruders seeking to bypass China's integrated hub dominance. Biodegradable filament grades for agricultural mulch and single-use textiles offer white-space positioning where incumbent qualification investments remain minimal. Partner with regional hygiene brand procurement teams to establish spunbond-meltblown composite supply relationships before multinational incumbents localize capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders holding captive additive formulation expertise for halogen-free flame retardant and heavy-metal-free colorant packages. Long-term viability over the projection horizon favors acquisition targets with demonstrated automotive airbag yarn qualification and established OEM approved-supplier status. Monitor ECHA SVHC candidate list expansion velocity as the primary inflection signal for reformulation-driven consolidation among mid-tier extruders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Chip Production | Captive PTA supply from Zhejiang refinery corridors insulates margin control from naphtha volatility. |
| REACH-Compliant Additive Reformulation | Halogen-free flame retardant packages secure automotive upholstery qualification ahead of SVHC restriction dates. |
| India PLI Scheme Capacity Buildout | Localized extrusion assets capture technical textile incentives while bypassing China's dual carbon energy ceilings. |
| Bicomponent Sheath-Core Technology Licensing | Medical nonwoven antimicrobial embedding commands premium positioning over post-treatment finishing processes. |
| Chemical Recycling Integration Partnership | Pyrolysis-based polymer regeneration enables circularity claims satisfying EU Green Deal procurement criteria. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with extrusion plant managers, procurement leads at automotive Tier 1 suppliers, technical textile R&D directors, and hygiene brand supply chain executives. Secondary validation drew from customs and trade flow databases, SEC filings of petrochemical-integrated producers, European Chemicals Agency REACH registration dossiers, and China GB standards documentation. Bottom-up filament capacity modeling and top-down end-use consumption estimates were triangulated to converge volume and value outputs.
Calibration against historical capacity utilization rates and disclosed expansion timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include polymer chemistry, performance grade tier, end-use industry application, and regional production hub configuration. CAGRs were derived from slope analysis of disclosed capacity additions correlated with downstream demand elasticity parameters. Industry-specific forecast inputs incorporated automotive lightweighting program specifications and hygiene nonwoven procurement cycle intensities.
Practitioners should monitor crude-derived feedstock volatility, ECHA regulatory timeline acceleration, and automotive OEM platform standardization shifts for early signals of forecast revision triggers. Forecasts reflect documented assumptions regarding capacity commissioning schedules and qualification timeline stability. Material shifts in REACH restriction implementation velocity or dual carbon policy enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Clothing Fibers Market