
 Shipping Container Modification Market | 2026-2036
Shipping Container Modification Market Size, Share, and Industry Trends Forecast 2026-2036
Shipping Container Modification Market Analysis
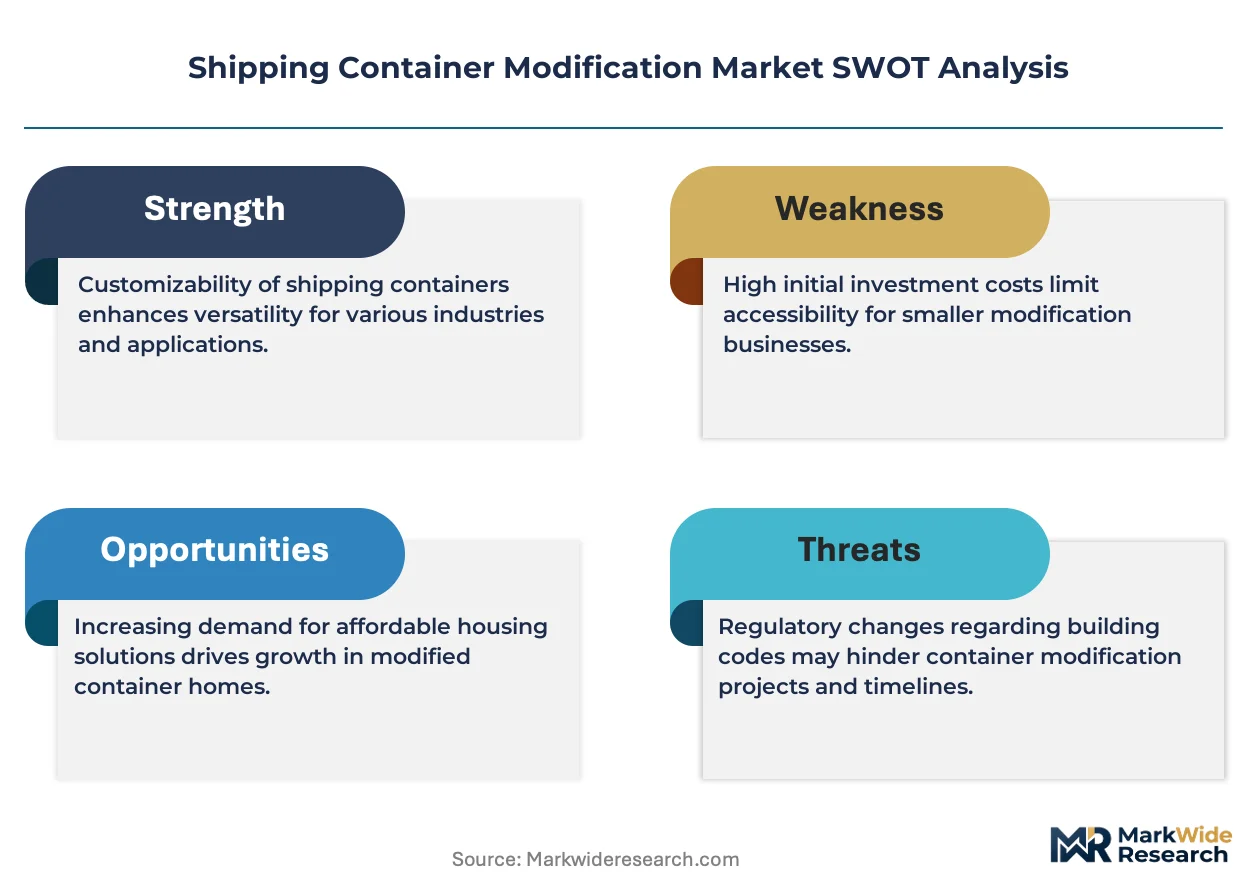
Project finance tied to infrastructure buildouts is narrowing the competitive field to firms with balance-sheet capacity or leasing partnerships. Falcon Structures leverages vertical integration across fabrication and site delivery to sustain margin control on large government contracts. Container Modification World anchors its position through geographic dominance in the southwestern United States, where energy sector demand remains concentrated. Algeco Scotsman Group competes via asset-light leasing models that reduce customer capital burdens on multi-year deployments.
Shipping container modification encompasses the structural alteration of ISO-certified steel boxes through cutting, framing, insulation, and utility integration to create habitable or functional enclosed spaces. Standard containers typically measure 20 or 40 feet in length with Corten steel walls rated for stacked maritime transport loads, then reinforced with steel framing and weatherproofing for permanent or semi-permanent installation. Standard containers dominate volume shipments due to their lower base cost and universal parts availability, while refrigerated containers command premium pricing in pharmaceutical cold-chain and food service applications. Electrical systems modification represents the fastest-growing segment as remote work requirements and off-grid power integration expand addressable use cases.
The EPA enforces emissions and energy efficiency standards for temporary structures that shape insulation specifications and HVAC system choices in modified container builds. OSHA workplace safety regulations mandate specific egress, ventilation, and structural load requirements that directly determine design parameters for office and storage deployments. The International Code Council's modular construction guidelines influence state-level permitting consistency, though local building departments retain final approval authority. Stakeholders must monitor evolving energy code adoptions across municipalities, as jurisdictions tightening envelope performance standards will disqualify basic container configurations from permitted use.
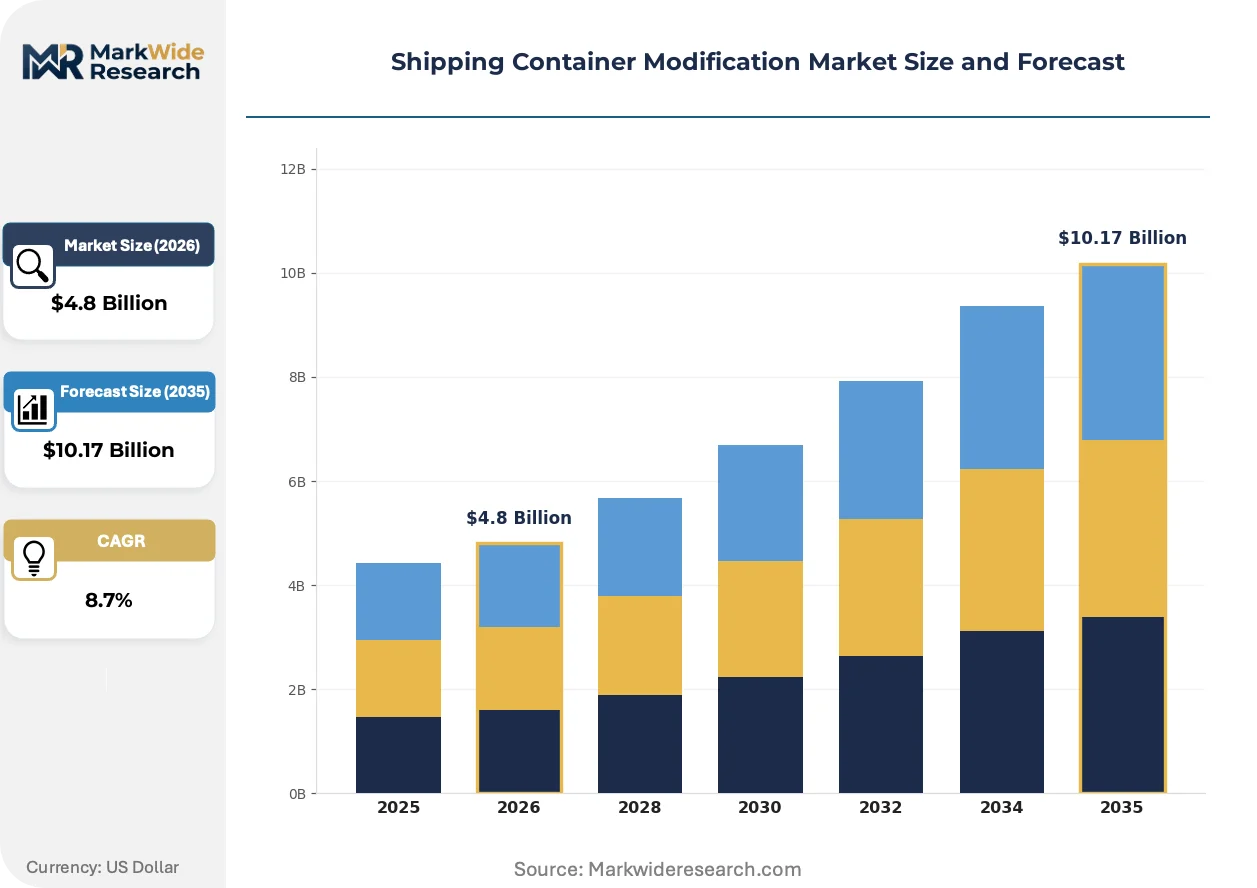
Market Dynamics
Project finance requirements for infrastructure buildouts are consolidating competitive positioning around firms with balance-sheet capacity or established leasing partnerships, while EPA emissions standards for temporary structures reshape insulation and HVAC specifications across supplier portfolios.
Growth Catalysts
- Remote Workforce Housing:Oilfield operators in Texas and disaster relief agencies sustain large-volume procurement of customized container units for workforce accommodation at isolated project sites.
- EPA Emissions Standards:The agency's energy efficiency mandates for temporary structures push suppliers toward insulated container designs with integrated climate control systems.
- Electrical Systems Integration:Off-grid power requirements and remote work connectivity needs expand addressable use cases for modified containers across construction and energy sectors.
Market Restraints
- Corten Steel Price Volatility:Fluctuations in raw material costs for maritime-grade steel containers compress fabrication margins and create quoting uncertainty for multi-year contracts.
- Local Permitting Fragmentation:The International Code Council's modular construction guidelines lack binding authority, forcing suppliers to navigate municipality-specific approval processes that extend project timelines.
- Traditional Construction Substitution:Conventional stick-built temporary structures retain cost advantages in markets without stringent energy code enforcement or rapid deployment requirements.
Strategic Opportunities
- Pharmaceutical Cold-Chain:Refrigerated container modifications command premium pricing for temperature-sensitive drug storage and distribution networks requiring validated thermal performance.
- Leasing Model Expansion:Asset-light rental structures reduce customer capital burdens on multi-year deployments, opening government and municipal procurement channels.
- Southwestern Geographic Concentration:Energy sector demand clusters in Texas and adjacent states create regional scale advantages for fabrication and site delivery operations.
Industry Challenges
- Certified Welder Scarcity:Structural modification of Corten steel containers requires specialized welding expertise that fabrication shops struggle to recruit and retain at competitive wage rates.
- Utility Integration Complexity:Coordinating electrical, plumbing, and HVAC subcontractors across dispersed project sites creates scheduling conflicts and quality control gaps in final container commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipping Container Modification Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Standard Container, Refrigerated Container, Open-Top Container, Flat Rack Container Modification Type: Insulation, Ventilation, Customized Interiors, Electrical Systems End Use: Storage, Office Space, Retail Outlets, Event Spaces Construction Material: Steel, Aluminum, Composite, Other Materials |
| Companies Covered | Container Management, Container Modification World, Falcon Structures, Acton Mobile Industries, Modular Space Corporation, Ultimate Bunker, Container Alliance, Algeco Scotsman Group, Container Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipping Container Modification Market Emerging Trajectories
Container modification workflows are converging with modular construction methodologies, compressing traditional build timelines while expanding the addressable market beyond conventional maritime reuse applications.
Prefabricated electrical panel systems with pre-wired conduit routing are collapsing the on-site installation phase for container-based offices and workforce housing. Remote construction camps and oilfield service companies are specifying these plug-and-play configurations to reduce skilled electrician deployment to isolated locations. The technology is collapsing project commissioning timelines from weeks to days, enabling faster revenue recognition on rental fleet deployments.
The EPA's evolving emissions standards for temporary structures are mandating higher-performance envelope specifications that disqualify basic uninsulated container configurations from permitted use in an expanding number of jurisdictions. Fabricators must now engineer thermal breaks and continuous insulation systems that add material cost but unlock compliance-driven procurement channels. Energy sector buyers in regulated states face the tightest constraints, driving specification divergence between premium and economy product tiers.
Leasing arrangements are displacing outright purchase for multi-year container deployments across government and municipal buyers seeking to preserve capital for core infrastructure spending. Rental fleet operators capture recurring revenue streams while assuming residual value risk and maintenance obligations that customers previously self-managed. Texas state agencies and county emergency management departments represent the most visible adopters of this procurement model shift.
Shipping Container Modification Market Segmentation
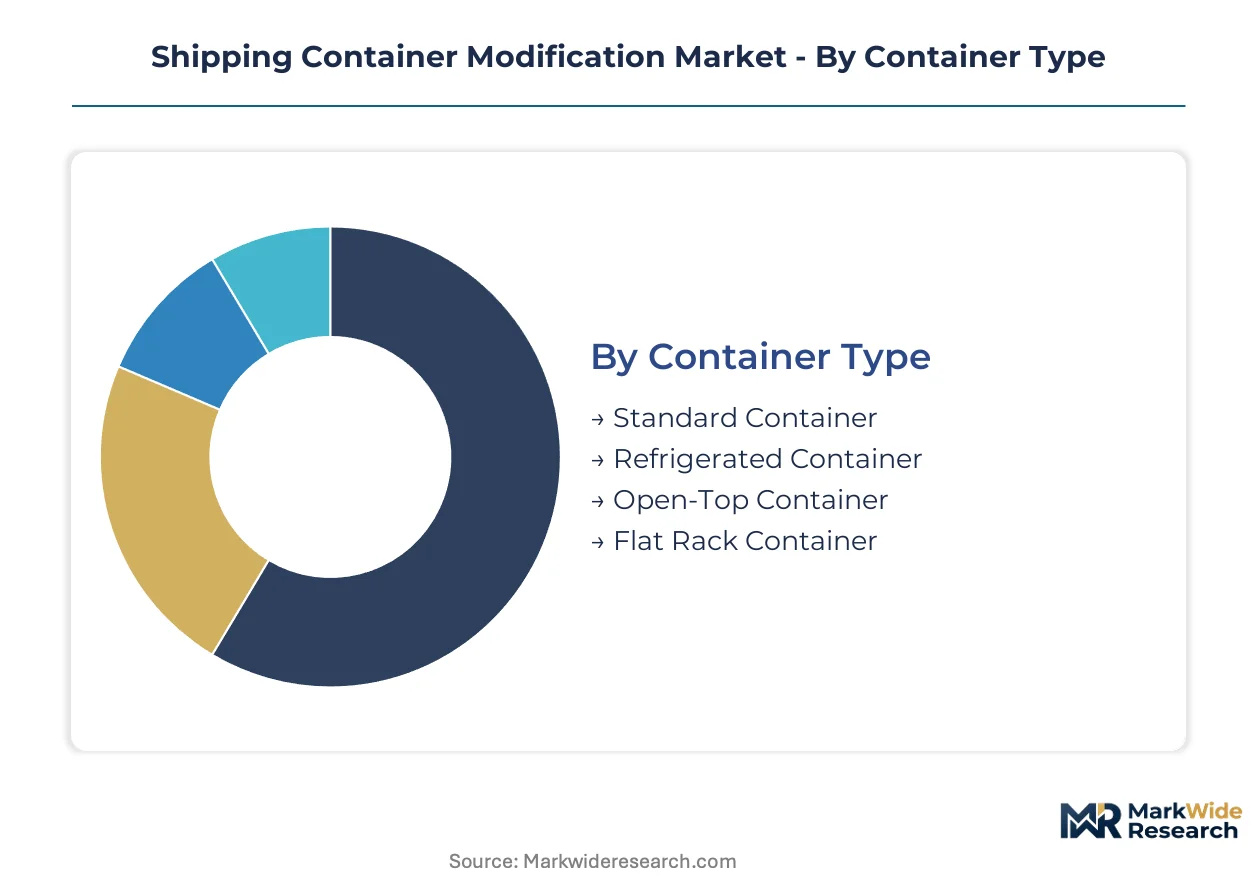
Segmentation in the shipping container modification market reveals distinct service intensity profiles across container types and modification complexity. After-sales requirements vary dramatically between basic storage units and climate-controlled pharmaceutical deployments, reshaping supplier capability investments and margin structures.
Container Type:
After-sales service intensity escalates with container specialization, as refrigerated units demand continuous compressor maintenance while standard boxes require minimal post-delivery support.
- Standard Container:Corten steel construction with maritime-grade weatherproofing supports the broadest modification applications at lowest base unit cost. Demand concentrates in Texas oilfield operations and disaster relief procurement, where volume buyers prioritize rapid deployment over thermal performance. Standard Container holds the largest share; momentum sits with Refrigerated Container.
- Refrigerated Container:Integrated cooling systems with validated temperature control enable pharmaceutical cold-chain and food service applications requiring thermal performance documentation. Cold-chain logistics operators in regulated states drive specification upgrades as EPA envelope standards tighten.
- Open-Top Container:Removable tarpaulin roof accommodates oversized cargo and vertical loading for construction equipment storage.
- Flat Rack Container:Collapsible end walls facilitate heavy machinery transport and specialized industrial staging.
Standard Container dominates procurement volume; Refrigerated Container commands premium pricing tiers.
Modification Type:
Cost tier stratification separates basic weatherproofing from integrated building systems, with electrical modifications capturing the steepest expansion trajectory.
- Electrical Systems:Pre-wired panel systems with conduit routing collapse commissioning timelines for remote site deployment. Off-grid power integration and workforce connectivity requirements drive specification across construction camps and energy sector buyers.
- Insulation:Continuous thermal barriers and thermal break engineering satisfy EPA emissions standards for temporary structures. Jurisdictions with stringent energy codes now disqualify uninsulated configurations from permitted use.
- Ventilation:OSHA-mandated air exchange systems for occupied workspace modifications.
- Customized Interiors:Partition framing, flooring, and fixture integration for retail and office applications.
Insulation modifications anchor compliance-driven procurement; Electrical Systems expand the addressable market fastest.
End Use:
Application diversity stretches from passive storage to revenue-generating retail, with workforce housing commanding the most complex utility integration.
- Office Space:Climate control, egress compliance, and communication infrastructure for construction site administration. Remote project locations in the southwestern United States sustain large-volume orders from energy sector contractors.
- Storage:Basic weatherproofing and security modifications for equipment and inventory protection. Lowest service intensity supports rental fleet operators seeking capital-efficient asset utilization.
- Retail Outlets:Customer-facing finishes and utility connections for temporary commercial presence.
- Event Spaces:Rapid-deployment configurations for seasonal and promotional activations.
Storage captures the widest customer base; Office Space generates the highest per-unit modification revenue.
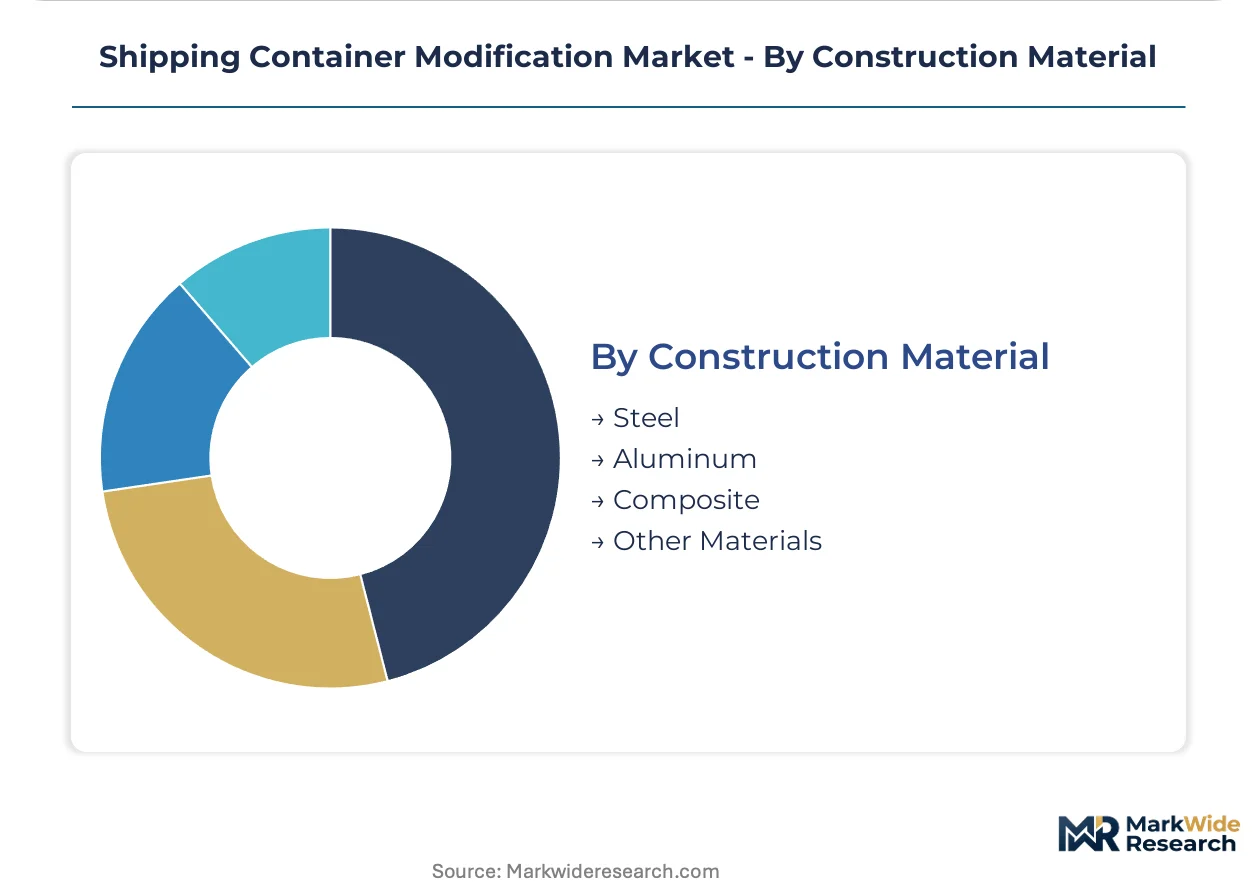
Construction Material:
Supply concentration in steel fabrication creates margin pressure when Corten prices fluctuate, while alternative materials serve weight-sensitive transport applications.
- Steel:Corten alloy construction with maritime corrosion resistance supports stacked load ratings and structural modification durability. Fabrication shops across Texas and adjacent states maintain welding capacity for reinforced framing.
- Aluminum:Lightweight alternative for mobile and frequently relocated container deployments.
- Composite:Insulation-integrated panels for high-performance envelope specifications.
- Other Materials:Wood and hybrid systems for specialized aesthetic or acoustic requirements.
Steel dominates fabrication throughput; Composite materials gain specification in energy code-advanced jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure incentives and state-level energy code adoptions are reshaping procurement patterns across key container modification markets. Regional demand clusters around energy extraction zones, disaster-prone corridors, and construction-intensive metropolitan areas where rapid deployment requirements override traditional building timelines.
United States
Texas oilfield operations and FEMA disaster relief procurement sustain the highest national order volumes for customized workforce housing units. EPA emissions standards for temporary structures mandate insulated envelope specifications that disqualify basic container configurations in California and northeastern states. Houston and Midland fabrication clusters serve Permian Basin energy contractors with vertically integrated production and site delivery capabilities.
Canada
Remote mining camps in Alberta and British Columbia drive demand for off-grid electrical integration and extreme-climate insulation systems. The National Building Code of Canada's modular construction provisions create permitting consistency across provinces, reducing project timeline uncertainty. Calgary and Edmonton fabrication shops concentrate on energy sector contracts requiring CSA-certified electrical installations for arctic-grade deployments.
Germany
Industrial construction projects and temporary office requirements from manufacturing expansion sustain steady modification orders across Bavaria and North Rhine-Westphalia. The EU Green Deal's building energy performance standards push suppliers toward high-efficiency envelope designs with documented thermal bridging mitigation. Munich and Stuttgart engineering clusters specialize in precision-finished container offices for automotive and machinery sector clients.
Australia
Mining operations in Western Australia and Queensland's infrastructure buildouts generate sustained demand for remote workforce accommodation modules. The National Construction Code's energy efficiency provisions for temporary structures mirror EPA trajectory, favoring insulated specifications over basic weatherproofing. Perth fabrication capacity serves Pilbara iron ore and LNG projects with cyclone-rated structural reinforcements and dust-sealed HVAC systems.
United Arab Emirates
Expo legacy site conversions and ongoing construction mega-projects in Dubai and Abu Dhabi sustain premium-tier demand for finished container retail and hospitality spaces. The Emirates Authority for Standardization and Metrology's modular building regulations provide clearer permitting pathways than fragmented North American jurisdictions. Jebel Ali industrial zone fabricators leverage port-adjacent container supply chains for rapid-turnaround modification services.
Shipping Container Modification Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: vertically integrated fabricators with captive steel processing and site logistics, regional specialists leveraging geographic proximity to energy sector demand clusters, and asset-light leasing operators capturing recurring revenue through rental fleet management. Strategic differentiation hinges on welding capacity retention, multi-trade subcontractor coordination, and balance-sheet depth for multi-year government contract performance bonds. Capacity expansion and leasing partnership formation represent the dominant competitive moves as project finance requirements narrow viable bidders.
Among United States-based fabricators, Falcon Structures exemplifies the vertically integrated archetype through controlled fabrication and direct site delivery, while Container Modification World anchors regional positioning through southwestern geographic concentration. Algeco Scotsman Group occupies the asset-light leasing tier, reducing customer capital burdens through rental structures that open municipal and government procurement channels. These three patterns—integration, regional density, and fleet-based financing—capture the competitive vectors reshaping supplier positioning across North American and European markets.
| Leading Market Players |
|---|
| Container Management |
| Container Modification World |
| Falcon Structures |
| Acton Mobile Industries |
| Modular Space Corporation |
| Ultimate Bunker |
| Container Alliance |
| Algeco Scotsman Group |
| Container Technology |
| Others |
Supply Flow & Price Mechanics
Port of Houston container flow dynamics compress inbound freight costs for Texas-based fabricators while amplifying price differentiation between Gulf Coast suppliers and inland competitors serving energy sector buyers. Corten steel container availability through this corridor anchors supply concentration that feeds into three-tier pricing stratification across premium insulated configurations, standard modified units, and basic storage-grade boxes.
Pricing Analysis
Certification level creates the primary spread between economy and premium tiers, with EPA-compliant insulated envelopes and OSHA-certified egress systems commanding substantial premiums over basic weatherproofed configurations. Project-based contract pricing dominates procurement, though leasing arrangements are displacing outright purchase for multi-year government deployments. Price differentiation rests on thermal performance grade and electrical integration complexity, with cold-chain pharmaceutical specifications capturing the highest margins. Cost compression in standard container tiers is intensifying because Corten steel price volatility erodes fabrication margins. Municipal buyers exhibit the sharpest price sensitivity, while pharmaceutical logistics operators prioritize validated thermal performance over unit cost.
Supply Chain Analysis
Corten steel feedstock availability hinges on maritime container decommissioning rates from China, South Korea, and Vietnam, where shipping line fleet renewal programs generate the core supply of modification-ready boxes. Fabrication inputs draw from domestic steel framing suppliers, pre-wired electrical panel manufacturers, and HVAC subsystem providers concentrated in Texas and adjacent southwestern states. Single-source vulnerability sits with specialized welding labor pools, where certified Corten steel fabricators remain scarce relative to demand growth. Distribution runs through vertically integrated fabricators with captive site delivery capabilities, regional specialists leveraging proximity to Permian Basin operations, and asset-light leasing operators managing rental fleet logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service intensity represents the fastest-expanding revenue layer, with refrigerated container compressor maintenance contracts and multi-year HVAC service agreements outpacing hardware margin growth. Recurring revenue from leasing fleet management and utility system commissioning support creates durable customer lock-in beyond initial modification sales.
For Market Incumbents: Build regulatory certification moats by securing EPA envelope compliance documentation and OSHA workplace safety validations ahead of tightening energy code adoptions across municipalities. Deepen backward integration into Corten steel container sourcing through direct shipping line partnerships, reducing exposure to spot market volatility. Expand welding apprenticeship programs in Houston and Midland fabrication clusters to counter certified fabricator scarcity threatening capacity growth.
For New Entrants and Emerging Players: Pharmaceutical cold-chain logistics in regulated northeastern and California markets represent the most penetrable entry point, where EPA emissions standards have disqualified basic container configurations and incumbent capacity remains constrained. Remote mining camps in Alberta and British Columbia offer secondary white-space opportunity, with extreme-climate insulation requirements creating specification barriers for generalist competitors. Pursue CSA-certified electrical installation partnerships as the go-to-market angle, leveraging Canadian National Building Code permitting consistency to accelerate deployment timelines.
For Investors and Strategic Acquirers: Regional fabrication specialists with demonstrated energy sector contract execution and established Permian Basin site delivery networks anchor acquisition interest, given their irreplaceable geographic positioning. Long-term viability over the coming decade rests on leasing model transition success and residual value management capabilities rather than pure fabrication scale. Watch refrigerated container fleet utilization rates as the inflection signal, with sustained premium pricing in pharmaceutical cold-chain indicating durable competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corten Steel Sourcing | Direct shipping line partnerships insulate fabrication margins from container spot price volatility. |
| Leasing Fleet Expansion | Asset-light rental structures open municipal procurement channels and generate recurring revenue streams. |
| EPA Compliance Certification Investment | Validated envelope performance documentation unlocks regulated state procurement opportunities. |
| Welding Capacity Apprenticeship Programs | Certified fabricator pipelines counter labor scarcity threatening Texas fabrication cluster growth. |
| Pharmaceutical Cold-Chain Thermal Validation | Documented temperature control performance commands premium pricing in drug distribution networks. |
Methodological Framework
The analysis maps standard container modifications, refrigerated container configurations, electrical systems integration, and insulation specification tiers, each validated through fabrication shop operators, energy sector procurement managers, municipal contract officers, and HVAC subcontractor coordinators. Primary interviews with these stakeholders combined secondary validation through EPA emissions standard filings, OSHA workplace safety guidance documents, International Code Council modular construction guidelines, and customs data on Corten steel container imports. Bottom-up project pipeline tracking and top-down addressable market sizing triangulate volume estimates across the analysis window.
Assumption sets held fixed regulatory adoption trajectories for EPA emissions standards and OSHA workplace safety requirements while varying Corten steel price scenarios and energy sector capital expenditure cycles. Segmentation dimensions modeled include container type, modification complexity tier, end-use application, and regional energy code stringency. CAGRs derive from regression-based demand forecasting anchored to oilfield operation counts, disaster relief procurement volumes, and pharmaceutical cold-chain expansion rates. Off-grid power integration adoption curves and leasing model penetration assumptions feed directly into growth projections.
Macroeconomic conditions sit as an overlay; deviation in federal infrastructure spending levels, energy commodity prices, or interest rate environments would shift the trajectory materially. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and shipping container decommissioning rates. Cross-checking against FEMA procurement databases and energy sector EPC contractor order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
Project Logistics Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
North America Same Day Delivery Market