
 Peru Cold Chain Logistics Market | 2026-2036
Peru Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Cold Chain Logistics Market Analytics
Temperature-controlled monitoring as a subscription service is repositioning how logistics contracts are structured in Peru. Emergent Cold LatAm leverages its integrated warehouse network to anchor cold storage capacity along the Pan-American Highway corridor. South Pacific Logistics sustains competitive differentiation through specialized pharmaceutical handling certifications at its Callao facilities. Transporte Lipa dominates last-mile frozen distribution into Andean cities where altitude complicates refrigeration performance.
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure—reefer trucks, insulated containers, and climate-regulated warehouses maintaining precise thermal parameters typically between minus twenty-five and positive fifteen degrees Celsius—designed to preserve product integrity of perishable goods from origin to consumption. Refrigerated service leads value generation due to asparagus and avocado export volumes, while frozen storage registers the fastest structural expansion driven by seafood processing growth from Paita and Chimbote. IoT Solutions command disproportionate investment attention as real-time telemetry reduces spoilage claims and enables predictive maintenance across the fleet.
SAN and the Ministry of Transport and Communications jointly enforce cold chain integrity standards for agricultural exports, while BPA accreditation requirements from destination markets in the United States and Europe shape equipment specifications and facility certifications. Peru's national quality institute INACAL administers traceability protocols that mandate digital temperature logging for cross-border shipments. Stakeholders must monitor how forthcoming carbon border adjustments in key export destinations will recalibrate energy choices for refrigeration systems and warehouse operations.
Market Dynamics
Controlled-atmosphere reefers are compressing spoilage windows for asparagus and blueberry exporters, while SAN's HACCP mandates force facility upgrades across Ica and La Libertad. This dual pressure from equipment automation and regulatory enforcement is restructuring contract terms between growers and logistics providers.
Growth Catalysts
- Export-oriented cold storage mandates:SAN enforces HACCP compliance for all horticultural shipments bound for US and European markets, compelling warehouse retrofits in Lima-Callao.
- Seafood processing expansion:Anchovy and giant squid operations in Paita and Chimbote require frozen storage capacity along the northern coast.
- IoT telemetry adoption:Real-time temperature monitoring is automating spoilage detection and reducing insurance claims for reefer operators.
Market Restraints
- Diesel price volatility:Reefer truck operators face margin compression from fuel cost swings that erode contracted per-kilometer rates.
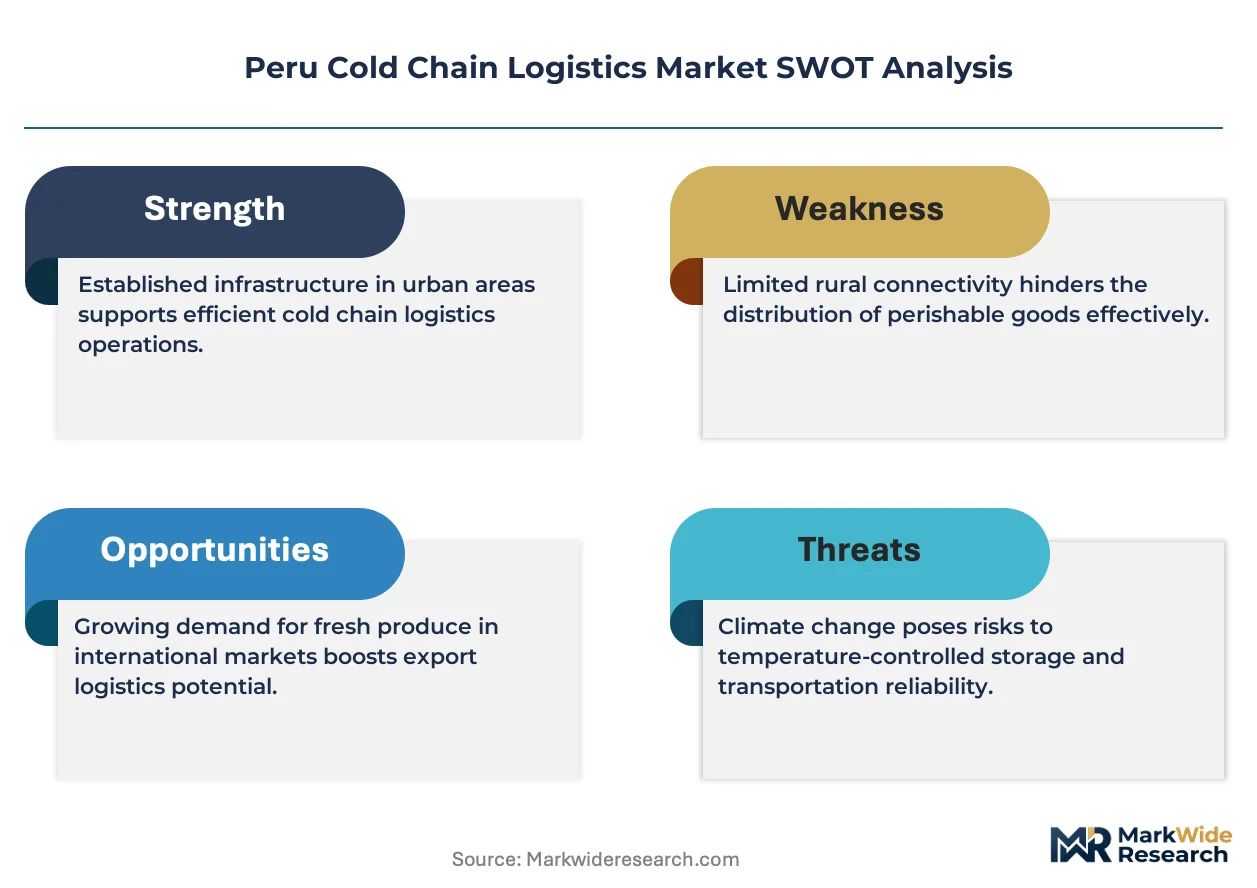
- Equipment import dependency:Refrigeration compressors and reefer units concentrate sourcing from Chinese and European manufacturers, exposing lead time risks.
- Andean altitude penalties:Refrigeration systems lose thermal efficiency above 2,500 meters, constraining frozen distribution to Cusco and Arequipa.
Strategic Opportunities
- Amazon basin penetration:Iquitos and Pucallpa remain underserved for temperature-sensitive pharmaceuticals, creating whitespace for riverine cold chain services.
- Carbon border adjustment preparation:EU Green Deal compliance requirements will reward facilities with solar-powered refrigeration ahead of 2026 implementation.
- Subscription monitoring services:Temperature-logging-as-a-service is displacing capital-intensive fleet ownership models among mid-size exporters.
Industry Challenges
- Refrigeration technician scarcity:Specialized ammonia and CO2 system maintenance skills lag fleet expansion in secondary cities.
- INACAL traceability integration:Digital temperature logging mandates require legacy warehouse management system overhauls with 18-month compliance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Cold Chain Logistics Market |
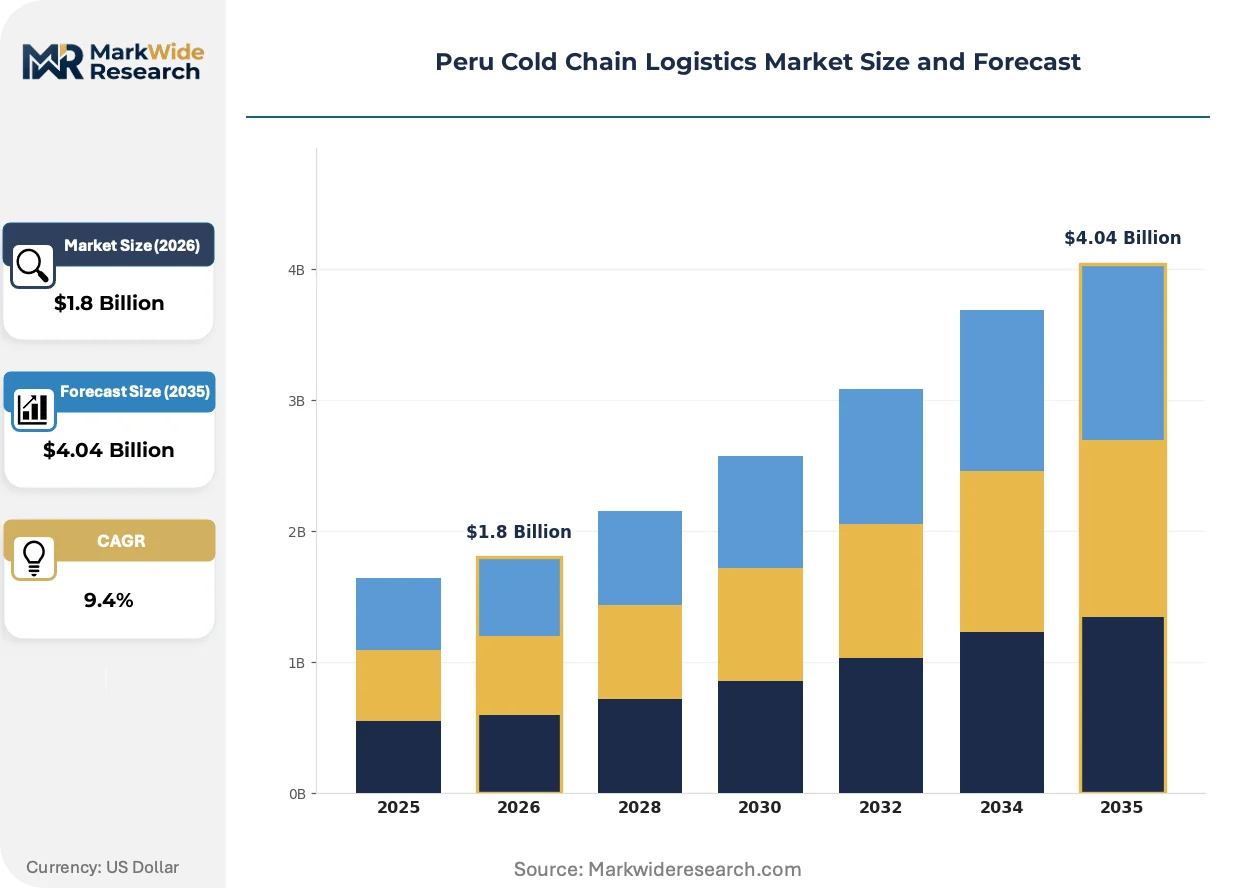
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Packaging, Monitoring Temperature Range: Standard Temperature, Refrigerated, Frozen, Deep Frozen End User: Pharmaceuticals, Food & Beverage, Chemicals, Agriculture Technology: IoT Solutions, Tracking Systems, Insulation Materials, Refrigeration Systems |
| Companies Covered | South Pacific Logistics, Transporte Lipa, Emergent Cold LatAm, Grupo Romero, Peru Cargo, Ransa Comercial, TIMCO SAC, Agrovision Logistics, DHL Supply Chain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Cold Chain Logistics Market Evolving Landscape
Digital infrastructure is displacing manual temperature verification across Peru's cold chain. Three concurrent developments are compressing operational timelines and reshaping competitive requirements for logistics contracts.
Telematics platforms integrating GPS and thermal sensors are automating route optimization and exception alerting for reefer fleets. Asparagus exporters in Ica have adopted these systems fastest, with real-time alerts now standard for shipments to Callao port. This automation is compressing response windows for mechanical failures from hours to minutes.
SAN and the Ministry of Transport and Communications jointly enforce cold chain integrity standards for agricultural exports, with inspection frequency intensifying for blueberry and mango seasons. Facilities must demonstrate continuous temperature logging or face shipment holds. Exporters to the United States are prioritizing BPA-accredited warehouses to preempt FDA detention risks.
Service contracts are unbundling equipment ownership from operational responsibility. Mid-size avocado growers now lease reefer capacity with embedded monitoring rather than maintaining captive fleets. This shift concentrates most visibly in La Libertad, where cooperatives aggregate smallholder volumes through third-party cold storage.
Peru Cold Chain Logistics Market Segmentation
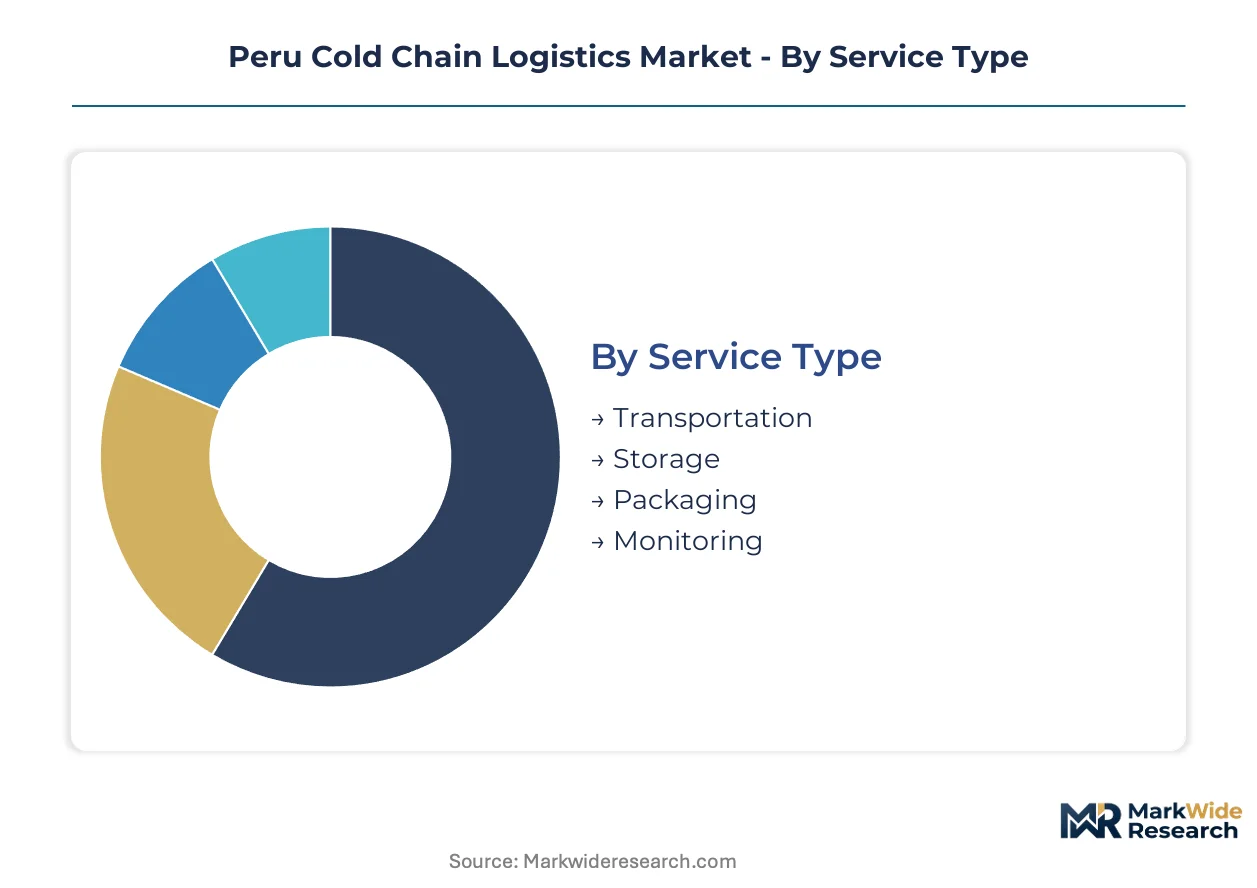
Peru's cold chain logistics market fragments across service modalities, thermal specifications, and end-use applications. Each segment carries distinct infrastructure requirements shaped by export compliance mandates and Andean geography.
Service Type:
Equipment refresh cycles and facility upgrade timelines differentiate competitive positioning across service categories.
- Transportation:Reefer trucks and controlled-atmosphere trailers dominate capital deployment, with asparagus exporters in Ica driving fleet expansion along the Pan-American Highway corridor. SAN inspection protocols now mandate real-time temperature logging for all horticultural cargo bound for US markets.
- Storage:Climate-regulated warehouses concentrate in Lima-Callao, where BPA-accredited facilities command premium contract terms from blueberry and avocado exporters. Controlled-atmosphere chambers are compressing spoilage windows for high-value produce.
- Packaging:Insulated containers and gel-pack systems serve pharmaceutical distributors requiring last-mile integrity to Andean cities above 2,500 meters.
- Monitoring:Temperature-logging-as-a-service is displacing capital-intensive fleet ownership among mid-size cooperatives in La Libertad.
Transportation sits at the top of the volume ranking, with Monitoring climbing the fastest.
Temperature Range:
Energy intensity and equipment specifications vary sharply across thermal bands, with altitude penalties complicating inland distribution.
- Standard Temperature:Ambient-controlled logistics for shelf-stable pharmaceuticals and processed foods, concentrated in Lima-Callao distribution hubs with lower capital barriers to entry.
- Refrigerated:Positive two to positive fifteen degrees Celsius systems anchor asparagus and avocado export flows from Ica and La Libertad to Callao port.
- Frozen:Minus eighteen degrees Celsius infrastructure is expanding most quickly along Peru's northern coast, where anchovy and giant squid processing in Paita and Chimbote drives cold storage construction.
- Deep Frozen:Minus twenty-five degrees Celsius and below systems serve specialized pharmaceutical cold chains and high-value seafood preservation, requiring ammonia-based refrigeration with scarce technician availability in secondary cities.
Refrigerated commands the largest revenue share, while Frozen gains share fastest on seafood processing growth.
End User:
Regulatory stringency and certification requirements create tiered service expectations across customer verticals.
- Pharmaceuticals:GDP-compliant cold chains with continuous temperature documentation serve vaccine and biologic distribution, with specialized handling certifications at Callao facilities differentiating top-tier providers.
- Food & Beverage:HACCP-mandated infrastructure dominates investment, spanning dairy processing, meat distribution, and prepared meal logistics with SAN enforcement intensifying for export-oriented segments.
- Chemicals:Temperature-sensitive industrial inputs and reagents require controlled storage with lower volume throughput but higher margin profiles than agricultural commodities.
- Agriculture:Fresh produce exporters generate the dominant demand flow, with INACAL traceability protocols mandating digital temperature logging for cross-border blueberry, mango, and asparagus shipments.
Agriculture anchors volume, with Pharmaceuticals expanding most quickly on cold-chain drug distribution growth.
Technology:
Digital adoption curves and capital replacement schedules are restructuring competitive requirements for equipment providers.
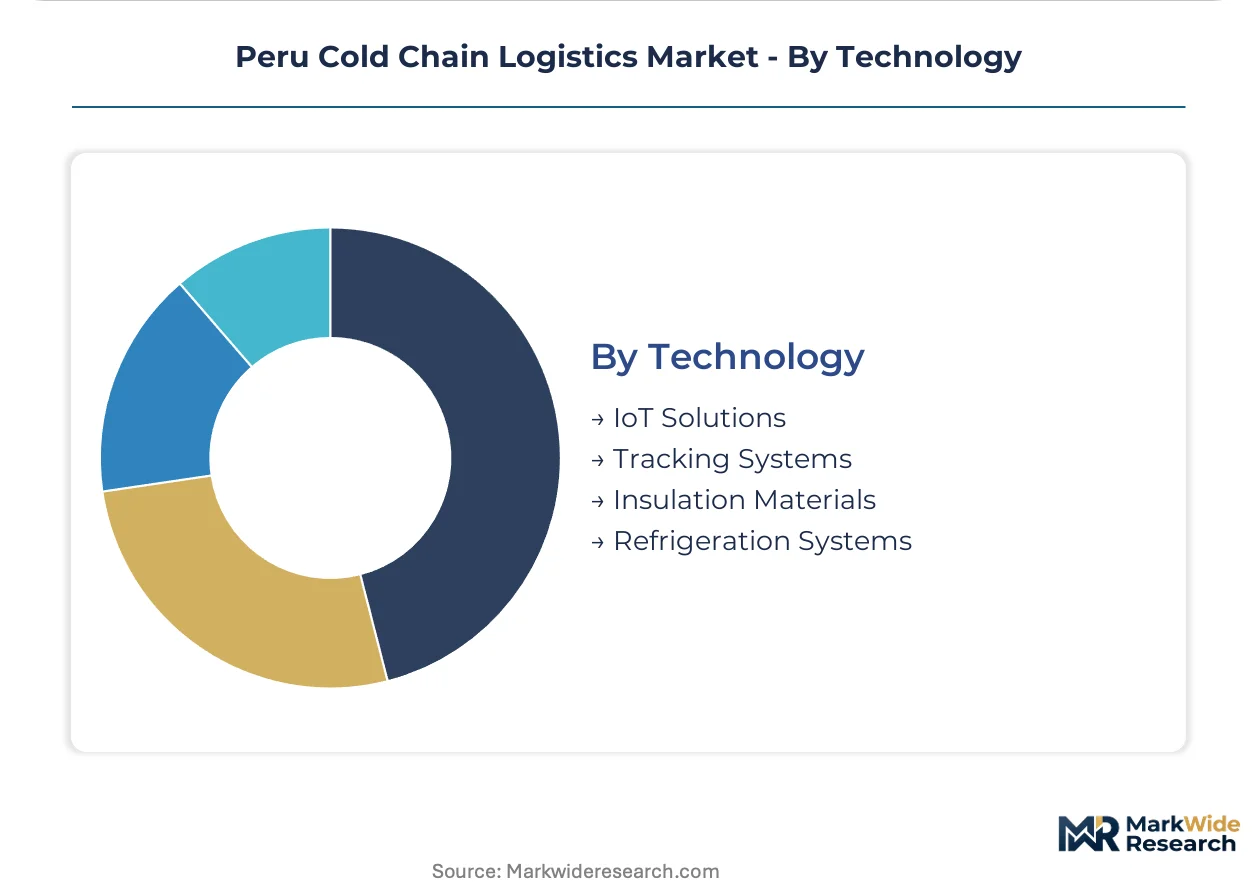
- IoT Solutions:Real-time telemetry platforms integrating GPS and thermal sensors automate spoilage detection and predictive maintenance, with subscription models displacing upfront hardware purchases among mid-size operators.
- Tracking Systems:RFID and barcode-based location monitoring provide foundational visibility for warehouse management systems, now standard in BPA-accredited facilities.
- Insulation Materials:Vacuum-insulated panels and advanced polyurethane foams improve thermal efficiency in reefers and containers, critical for altitude-impaired refrigeration performance in Cusco and Arequipa.
- Refrigeration Systems:Compressor units and climate-control hardware concentrate sourcing from Chinese and European manufacturers, exposing operators to lead time risks and import dependency.
Refrigeration Systems dominates installed base value, with IoT Solutions showing the steepest expansion trajectory on monitoring-as-a-service adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cold chain investment patterns across Peru as exporters relocate processing capacity to regions with lower compliance costs and superior port access. Cost-of-compliance gaps between Lima-Callao and secondary regions are driving facility migration toward Ica and La Libertad.
Lima-Callao
Peru's dominant cold chain cluster concentrates eighty percent of temperature-sensitive cargo throughput at Callao port. SAN and the Ministry of Transport and Communications enforce HACCP compliance through intensified inspection protocols for blueberry and mango export seasons. BPA-accredited warehouses in Callao command premium contract terms from avocado exporters seeking FDA pre-clearance.
Ica
Asparagus exporters drive controlled-atmosphere reefer adoption along the Pan-American Highway corridor. INACAL traceability protocols mandate digital temperature logging for all cross-border horticultural shipments originating from this region. Real-time telemetry systems now automate spoilage detection for shipments bound to Callao port.
La Libertad
Mid-size avocado cooperatives aggregate smallholder volumes through third-party cold storage facilities. Temperature-logging-as-a-service is displacing capital-intensive fleet ownership among growers seeking SAN compliance without infrastructure investment. Trujillo anchors regional consolidation as logistics providers establish satellite facilities.
Piura and Tumbes
Blueberry cultivation expansion is generating demand for pre-cooling capacity near harvest zones. SAN inspection frequency intensifies during peak export windows, forcing facility upgrades in previously underserved northern districts. Paita port infrastructure investments are attracting frozen seafood processors from Chimbote.
Cusco and Arequipa
Andean altitude penalties constrain frozen distribution above 2,500 meters, where refrigeration systems lose thermal efficiency. Transporte Lipa dominates last-mile frozen delivery into these highland cities despite operational challenges. Pharmaceutical cold chains represent whitespace opportunity as GDP-compliant infrastructure remains limited.
Peru Cold Chain Logistics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated warehouse networks commanding premium positioning against asset-light monitoring providers. The vendor base concentrates around three archetypes: Pan-American Highway corridor operators with captive storage assets, pharmaceutical-certified specialists at Callao facilities, and subscription-based telemetry platforms displacing traditional fleet ownership. Consolidation pressure is intensifying as SAN enforcement raises compliance barriers for subscale operators. Strategic moves center on BPA accreditation acquisition and solar-powered refrigeration retrofitting ahead of EU carbon border adjustments.
Among integrated corridor operators, Emergent Cold LatAm anchors cold storage capacity along the Pan-American Highway, while South Pacific Logistics occupies a position within the pharmaceutical-certified tier at Callao. Transporte Lipa exemplifies the high-altitude distribution archetype, serving Andean cities where thermal efficiency constraints limit competitor entry. These three represent distinct strategic positioning vectors—geographic coverage, certification differentiation, and operational specialization—rather than direct segment overlap.
| Leading Market Players |
|---|
| South Pacific Logistics |
| Transporte Lipa |
| Emergent Cold LatAm |
| Grupo Romero |
| Peru Cargo |
| Ransa Comercial |
| TIMCO SAC |
| Agrovision Logistics |
| DHL Supply Chain |
| Others |
Value Network & Pricing Analysis
Diesel fuel costs cascade through Peruvian cold chain pricing tiers, compressing margins for reefer truck operators serving Lima-Callao while concentrating premium pricing power among BPA-accredited warehouse providers. This energy-cost transmission from transport to storage segments reshapes contract structures between asparagus exporters and logistics providers.
Pricing Analysis
Direct-to-exporter contract discounts dominate pricing structures for mid-size avocado cooperatives in La Libertad, while three-tier pricing structure across premium, standard, and economy levels differentiates BPA-certified facilities from commodity cold storage. Price differentiation hinges on SAN HACCP certification grade and real-time telemetry integration. Pricing pressure stems from diesel volatility eroding per-kilometer rates for Pan-American Highway corridor operators. Smallholder aggregators show highest price sensitivity, whereas pharmaceutical distributors accept premium tiers for GDP-compliant handling.
Supply Chain Analysis
Domestic-content mandates remain absent in Peruvian refrigeration equipment procurement, leaving operators exposed to import dependency for compressors and reefer units sourced from China, Germany, and Italy. Raw material dependencies center on ammonia refrigerants, polyurethane insulation foams, and aluminum alloy framing. Single-source vulnerability concentrates in European compressor manufacturers with extended lead times. Distribution runs through Lima-Callao port cluster consolidation, with satellite facilities in Ica and La Libertad feeding into this hub.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peru's cold chain logistics market offers margin expansion through solar-powered refrigeration retrofits that preempt EU carbon border adjustment costs, shifting energy-intensive storage toward premium-tier positioning.
For Market Incumbents: Cement BPA accreditation moats at Callao facilities before SAN enforcement intensifies for blueberry export seasons. Expand controlled-atmosphere capacity along the Pan-American Highway corridor to capture asparagus volume growth from Ica. Threat substitution emerges from subscription-based telemetry platforms displacing fleet ownership among mid-size exporters. For New Entrants and Emerging Players: Begin with Amazon basin pharmaceutical cold chains serving Iquitos and Pucallpa, where GDP-compliant infrastructure remains scarce and riverine distribution creates natural barriers to incumbent expansion. Target temperature-logging-as-a-service for avocado cooperatives in La Libertad seeking SAN compliance without capital deployment. Go-to-market leverage rests on INACAL traceability protocol pre-integration. For Investors and Strategic Acquirers: Roll-up economics work for regional cold storage consolidators because SAN enforcement is raising compliance barriers that subscale operators cannot absorb, creating forced sellers across Ica and La Libertad. Five-to-ten-year viability centers on facilities with solar retrofit optionality ahead of EU Green Deal implementation. Acquisition target archetype: BPA-accredited warehouses with Pan-American Highway corridor positioning. Signal to watch: carbon border adjustment timeline acceleration in European destination markets.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Powered Refrigeration Retrofit | EU Green Deal compliance positions BPA-accredited Callao facilities for premium contract terms. |
| Controlled-Atmosphere Capacity Expansion | Pan-American Highway corridor investments capture asparagus export volume growth from Ica. |
| Temperature-Logging-as-a-Service Launch | Subscription models displace capital-intensive fleet ownership among La Libertad avocado cooperatives. |
| Pharmaceutical Cold Chain Certification | GDP-compliant infrastructure in Cusco and Arequipa addresses whitespace in Andean highland distribution. |
| Amazon Basin Riverine Service Development | Iquitos and Pucallpa penetration exploits natural barriers limiting incumbent last-mile reach. |
Research Methodology
Bottom-up agricultural export modeling reconciled against top-down cold storage capacity tracking forms the analytical core of this study. Primary interviews with reefer fleet operators, warehouse facility managers, SAN compliance officers, and asparagus export cooperative leaders combined with secondary validation from Peru's Ministry of Transport and Communications filings, INACAL traceability protocol documentation, BPA accreditation registries, and customs export data. Top-down and bottom-up triangulation cross-validates volume estimates against infrastructure capacity surveys.
Historical trendline analysis of refrigerated cargo throughput at Callao port anchors the projection framework across the analysis window. Segmentation dimensions modeled include service type, temperature range, end-use vertical, and technology adoption tier. CAGRs derive from equipment refresh cycles, facility upgrade timelines, and export volume elasticity to destination market demand. Industry-specific forecast inputs incorporate SAN inspection frequency intensification patterns and EU carbon border adjustment preparation timelines.
Several conditions sit outside the modeled scope, including abrupt diesel subsidy policy shifts, compressor import tariff changes, and unscheduled SAN protocol amendments. Forecasts reflect documented assumptions about seafood processing growth continuity from Paita and Chimbote. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
Iraq Air Freight Transport Market
Logistics and Shipping
Fine Art Logistics Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Armenia Freight and Logistics Market