
 US Fourth-Party Logistics (4PL) Market | 2026-2036
US Fourth-Party Logistics (4PL) Market Size, Share, and Industry Trends Forecast 2026-2036
US Fourth-Party Logistics (4PL) Market Insights
Freight brokerage networks is tilting toward integrated control-tower models that consolidate multimodal execution under single accountability structures. XPO Logistics leverages its North American less-than-truckload footprint to anchor dedicated fleet capacity for enterprise accounts. C.H. Robinson competes through proprietary freight-matching algorithms that compress tender-to-acceptance cycles. DHL Supply Chain differentiates via pharmaceutical-certified cold chain infrastructure that sustains temperature-validated lane control.
Fourth-party logistics denotes an outsourced supply chain integrator that designs, manages, and optimizes a client's entire logistics ecosystem through technology platforms, vendor orchestration, and performance-based contracts rather than asset ownership. The operational core rests on API-connected visibility layers that ingest telemetry from tier-two and tier-three carriers to generate predictive ETAs and inventory positioning signals. Transportation Management services dominate current contract values, while Supply Chain Consulting commands premium pricing as shippers seek network redesigns following pandemic-era disruption. Inventory Management is gaining share among consumer electronics brands managing semiconductor availability volatility.
FDA track-and-trace mandates and FMCSA hours-of-service rules shape compliance architectures that 4PL providers must embed into platform workflows. The EPA SmartWay program influences carrier selection criteria and emissions reporting obligations across contracted fleets. Stakeholders must evaluate whether their 4PL partner's data infrastructure can adapt to pending SEC climate disclosure requirements without service degradation.
Market Dynamics
Cloud-native control tower architectures are compressing contract cycles as pharmaceutical manufacturers abandon legacy ERP modules for API-orchestrated visibility layers that ingest tier-three carrier telemetry in real time.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialization mandates compel pharmaceutical manufacturers to outsource track-and-trace orchestration to 4PL platforms with validated cold chain documentation.
- Semiconductor inventory volatility:Consumer electronics brands are delegating buffer stock positioning to external supply chain integrators to navigate foundry allocation uncertainty.
- Port-adjacent distribution clusters:California and Texas logistics hubs anchor transcontinental freight flows, concentrating demand for multimodal control tower services.
Market Restraints
- Carrier capacity fragmentation:The long-tail of tier-two and tier-three trucking operators creates data standardization friction that degrades predictive ETA accuracy.
- Platform integration costs:Legacy WMS and TMS architectures require expensive middleware development to connect with cloud-based 4PL control towers.
- Cyber liability exposure:API-connected visibility layers multiply attack surfaces, elevating insurance premiums and contractual indemnification burdens.
Strategic Opportunities
- SEC climate disclosure rules:Pending Scope 3 emissions reporting mandates create advisory revenue streams for 4PL providers with validated carrier emissions databases.
- Battery supply chain localization:Inflation Reduction Act domestic content requirements are pulling lithium-ion logistics away from Asia-Pacific toward North American 4PL networks.
- Autonomous freight matching:Convergence of telematics data lakes and machine learning models enables dynamic capacity pricing that captures margin from spot market volatility.
Industry Challenges
- Control tower engineer scarcity:The intersection of supply chain operations and API architecture expertise commands salary premiums that compress provider margins.
- Multi-tenant data segregation:Pharmaceutical and defense clients impose conflicting security protocols that complicate platform architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fourth-Party Logistics (4PL) Market |
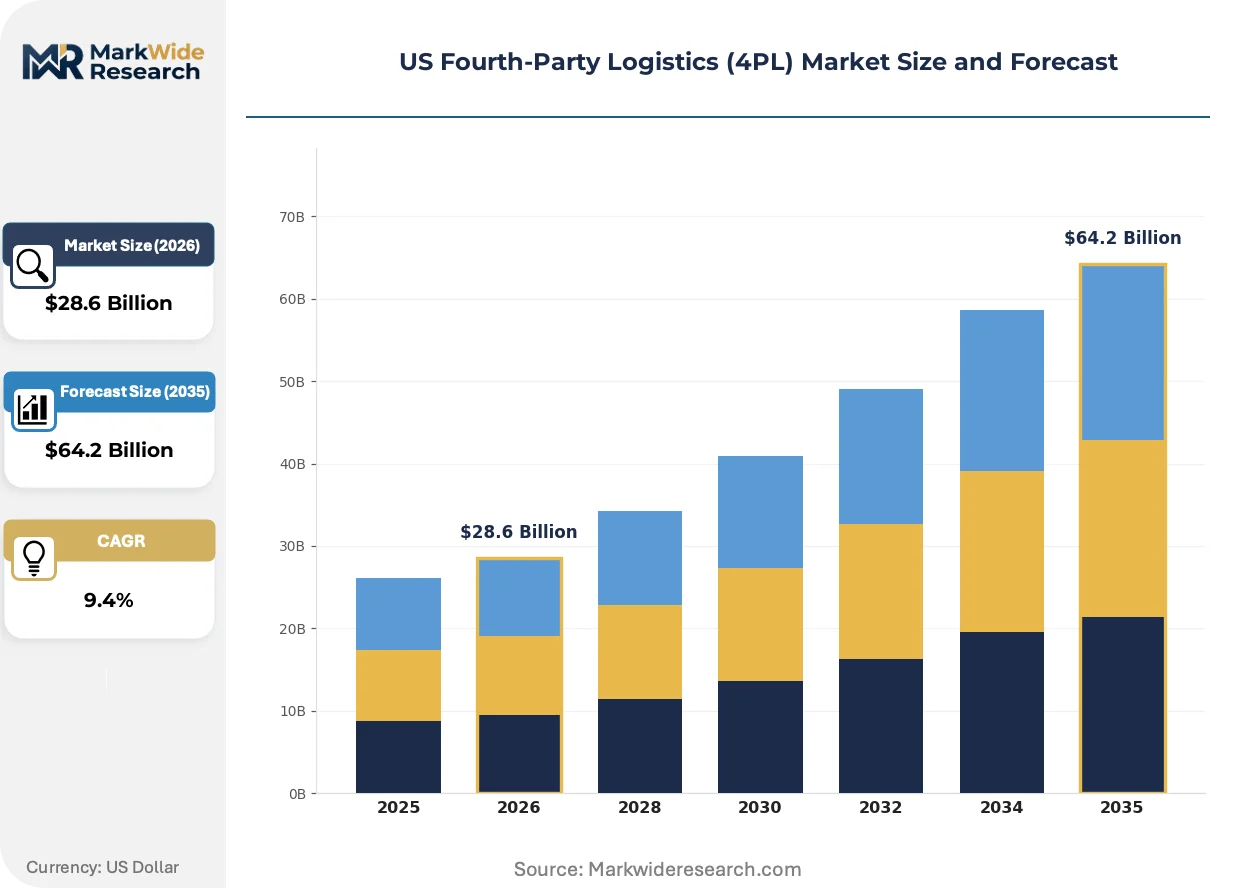
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation Management, Inventory Management, Order Fulfillment, Supply Chain Consulting Industry Vertical: Automotive, Consumer Electronics, Pharmaceuticals, Retail Delivery Model: Direct Delivery, Cross-Docking, Pool Distribution, Integrated Logistics Client Type: SMEs, Large Enterprises, E-commerce Companies, Startups |
| Companies Covered | XPO Logistics, C.H. Robinson, DHL Supply Chain, DB Schenker, Kuehne + Nagel, UPS Supply Chain Solutions, GEODIS, DSV, FedEx Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fourth-Party Logistics (4PL) Market Trends and Innovations
Real-time visibility infrastructure is redefining competitive differentiation as buyers prioritize predictive exception management over historical performance metrics in vendor selection.
Digital freight matching platforms leveraging machine learning is rendering obsolete the traditional broker-mediated tendering process that dominated spot market transactions. Large retail shippers are adopting these systems within eighteen-month implementation windows. The structural consequence is compressing gross margins for asset-light intermediaries while rewarding data-rich 4PL operators.
FMCSA hours-of-service rule amendments are forcing route optimization engines to recalibrate dwell time assumptions and driver scheduling algorithms. The industrial consequence is elevating the value of 4PL providers with embedded regulatory compliance modules. Pharmaceutical cold chain operators in the Midwest and Southeast are responding by consolidating lane control under single accountability structures.
Performance-based contracting is displacing unit-rate pricing as the dominant commercial framework for enterprise logistics relationships. Consumer packaged goods manufacturers are shifting toward gain-share arrangements tied to inventory velocity and working capital metrics. This pattern is most visible among California-based brands with direct-to-consumer fulfillment obligations.
US Fourth-Party Logistics (4PL) Market Segmentation
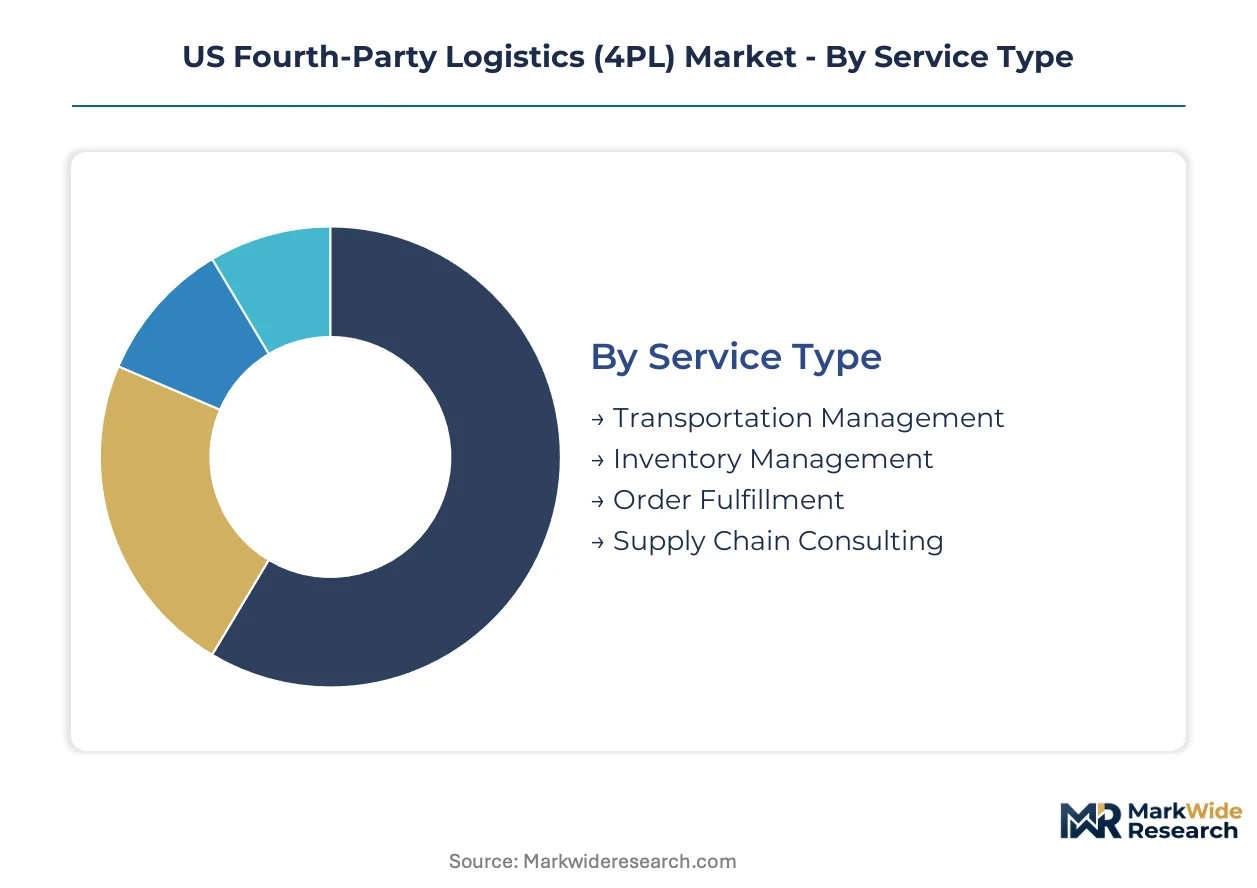
Segmentation in the US 4PL market reveals how service intensity, regulatory exposure, and delivery velocity create distinct commercial profiles. Pharmaceutical cold chain mandates and semiconductor inventory volatility pull providers toward specialized configurations rather than generic platform offerings.
Service Type:
After-sales-service intensity varies dramatically across service categories, with pharmaceutical track-and-trace obligations demanding 24/7 exception management while transportation execution operates on scheduled optimization cycles.
- Transportation Management:Core service orchestrating multimodal freight execution through API-connected carrier networks. Demand concentrates among California and Texas port-adjacent shippers managing transcontinental freight flows, where predictive ETA accuracy determines contract renewal rates.
- Supply Chain Consulting:Advisory services redesigning network topology and inventory positioning strategies. Pharmaceutical manufacturers facing FDA serialization mandates drive premium pricing as they outsource compliance architecture design to external integrators.
- Inventory Management:Buffer stock positioning and demand sensing across tiered distribution nodes. Consumer electronics brands navigating foundry allocation uncertainty delegate semiconductor availability forecasting to 4PL control towers.
- Order Fulfillment:Last-mile execution and reverse logistics coordination for direct-to-consumer channels. E-commerce volume spikes require elastic capacity contracts with regional parcel carriers.
By volume, Transportation Management leads. By growth pace, Supply Chain Consulting is climbing the fastest.
Industry Vertical:
Cost tier differentiation separates verticals, with pharmaceutical certified cold chain commanding 3-4x the platform fees of standard retail freight orchestration due to validated lane documentation requirements.
- Pharmaceuticals:Temperature-validated logistics with FDA track-and-trace compliance embedded in platform workflows. Serialization mandates compel outsourcing to 4PL providers with pharmaceutical-certified infrastructure.
- Consumer Electronics:High-velocity fulfillment managing semiconductor availability volatility and direct-to-consumer delivery obligations. California-based brands with omnichannel distribution networks anchor demand.
- Retail:Seasonal volume surges and reverse logistics complexity drive gain-share contracting tied to inventory velocity metrics.
- Automotive:Inbound parts sequencing and finished vehicle logistics requiring just-in-time coordination with assembly plant schedules.
Pharmaceuticals generates the highest revenue per contract. Consumer Electronics is expanding most quickly.
Delivery Model:
Customer type segmentation shapes delivery architecture, with large enterprises demanding integrated single-accountability structures while SMEs accept modular service components.
- Integrated Logistics:End-to-end supply chain orchestration under unified performance contracts. Large enterprise accounts in Texas and California consolidate fragmented carrier relationships under single 4PL accountability.
- Cross-Docking:Flow-through distribution minimizing inventory dwell time through synchronized inbound-outbound scheduling. Retail consolidation centers near Midwest population corridors exploit this model.
- Pool Distribution:Shared consolidation networks aggregating LTL shipments from multiple shippers into optimized delivery routes.
- Direct Delivery:Point-to-point freight movement bypassing intermediate handling for time-critical pharmaceutical and electronics shipments.
Integrated Logistics dominates enterprise procurement. Cross-Docking is gaining share fastest among mid-market retail shippers.
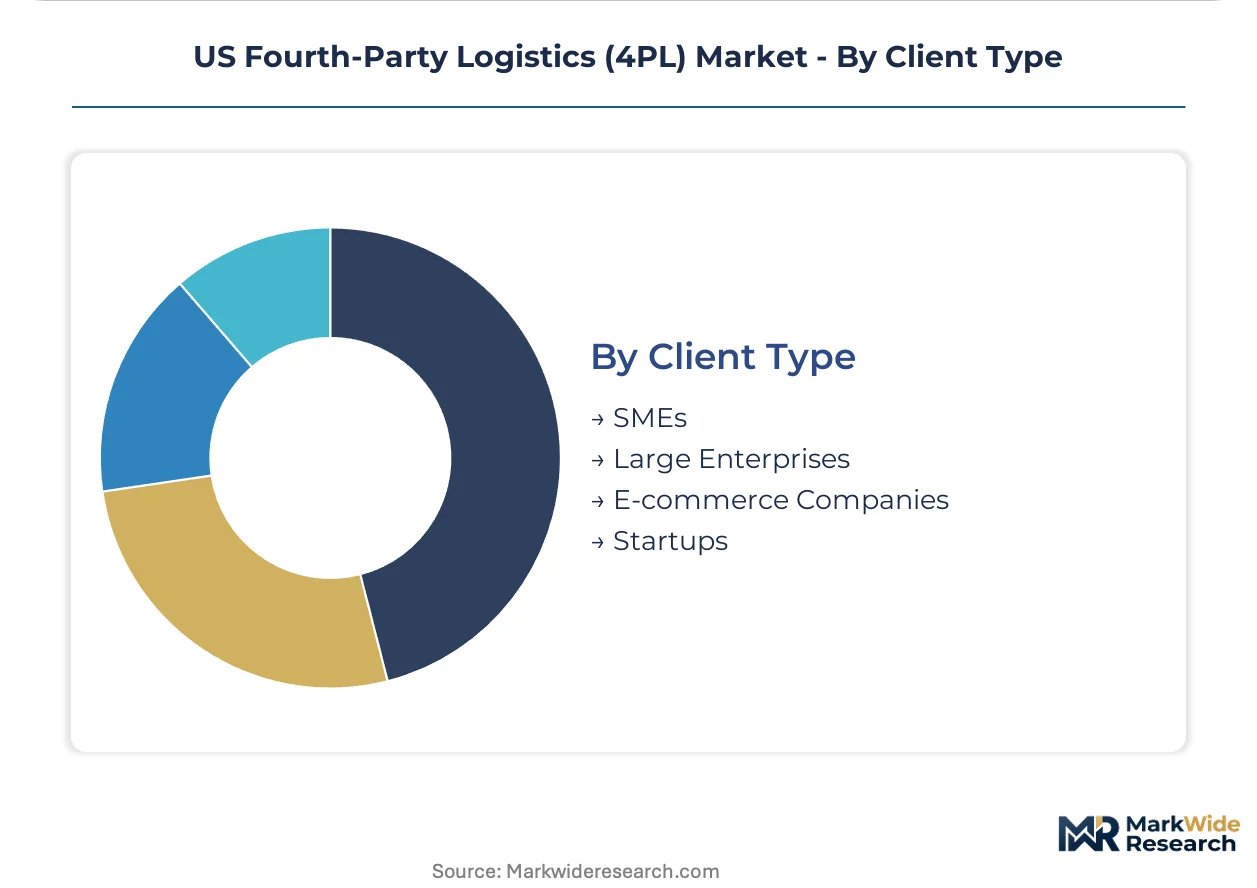
Client Type:
Volume concentration determines platform economics, with large enterprises subsidizing control tower infrastructure that SMEs access through standardized API tiers.
- Large Enterprises:Complex multi-node networks requiring dedicated control tower engineering and custom compliance module development. Pharmaceutical manufacturers and consumer electronics brands anchor this segment.
- E-commerce Companies:Elastic fulfillment capacity with seasonal surge protection and returns processing automation. Direct-to-consumer obligations drive real-time inventory visibility requirements.
- SMEs:Standardized platform access through self-service API configurations with limited customization scope.
- Startups:Venture-backed companies prioritizing speed-to-market over supply chain optimization, often migrating to full 4PL services post-Series B funding.
Large Enterprises account for the majority of contract value. E-commerce Companies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and Texas logistics corridors, where port-adjacent distribution clusters command premium rates for multimodal control tower services, while inland markets absorb margin compression from carrier capacity fragmentation.
California
Los Angeles and Long Beach port complexes anchor transcontinental freight flows for consumer electronics brands managing semiconductor availability volatility. EPA SmartWay program compliance shapes carrier selection criteria for enterprises seeking emissions reporting alignment. The Inland Empire distribution cluster concentrates pharmaceutical cold chain facilities serving West Coast pharmaceutical manufacturers under FDA track-and-trace mandates.
Texas
Dallas-Fort Worth and Houston logistics hubs consolidate fragmented carrier relationships under single 4PL accountability structures for large enterprise accounts. FMCSA hours-of-service rules force route optimization engines to recalibrate dwell time assumptions for cross-border freight movements. The Laredo-Nuevo Laredo corridor anchors nearshoring freight flows pulling lithium-ion battery logistics toward North American networks under Inflation Reduction Act domestic content requirements.
Illinois
Chicago's intermodal rail terminals synchronize inbound-outbound scheduling for retail consolidation centers exploiting cross-docking models. FDA Drug Supply Chain Security Act serialization mandates compel pharmaceutical manufacturers to outsource track-and-trace orchestration to 4PL platforms with validated cold chain documentation. The I-55 corridor distribution cluster serves Midwest pharmaceutical cold chain operators consolidating lane control under single accountability structures.
Georgia
Atlanta's airport-adjacent logistics parks anchor time-critical pharmaceutical and electronics shipments requiring direct delivery bypassing intermediate handling. SEC pending climate disclosure requirements create advisory revenue opportunities for 4PL providers with validated carrier emissions databases. The Savannah port hinterland concentrates e-commerce fulfillment capacity with seasonal surge protection and returns processing automation.
New Jersey
Port Newark-Elizabeth distribution networks serve pharmaceutical manufacturers facing FDA serialization mandates with 24/7 exception management requirements. Cyber liability exposure from API-connected visibility layers elevates insurance premiums and contractual indemnification burdens for control tower operators. The Meadowlands logistics cluster supports New York Metro direct-to-consumer fulfillment obligations driving real-time inventory visibility requirements.
US Fourth-Party Logistics (4PL) Market Competitive Landscape
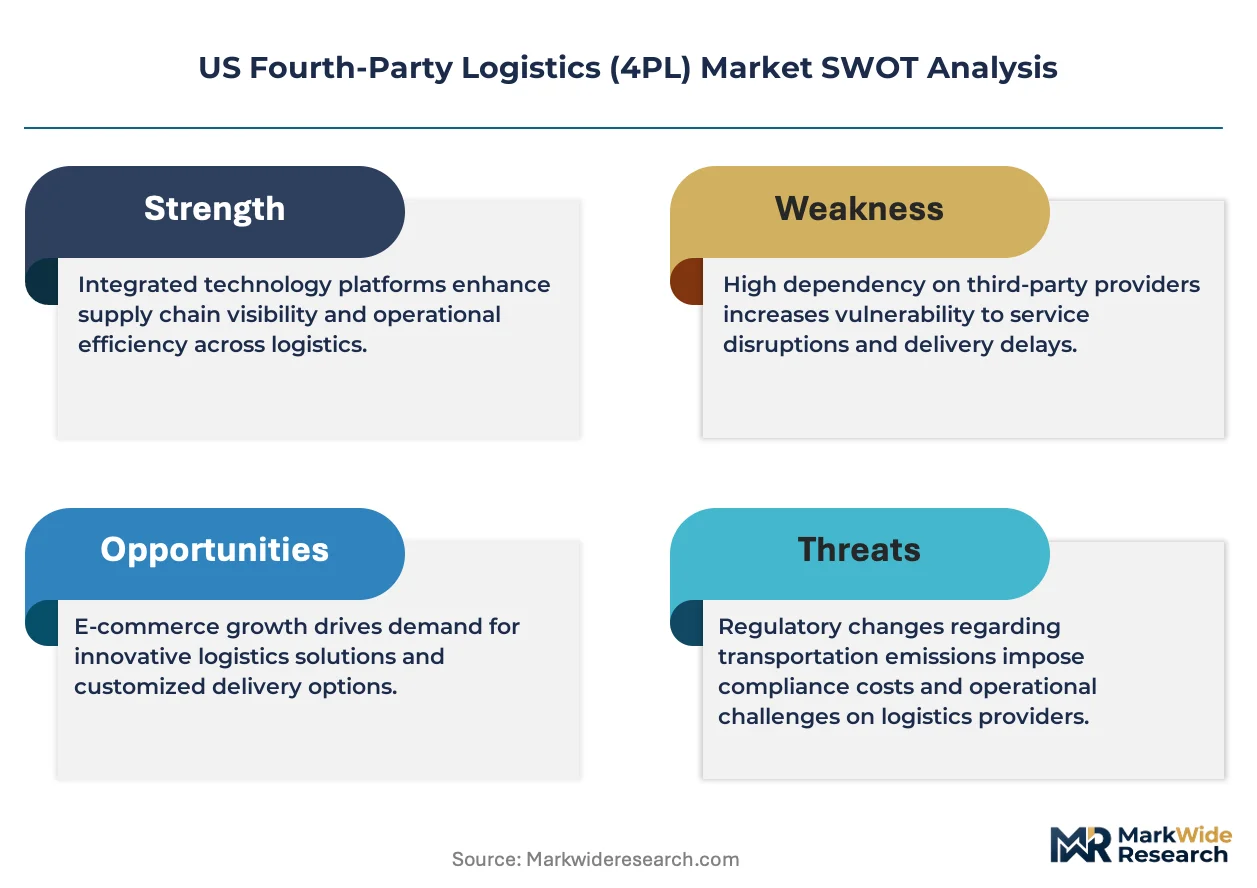
Platform integrators command the system tier; component specialists sit upstream executing discrete functions under orchestrated contracts. The vendor base concentrates among asset-light intermediaries and asset-heavy integrators competing through data infrastructure depth rather than fleet scale alone. Three archetypes dominate: pharmaceutical-certified cold chain operators, freight-matching algorithm specialists, and multimodal control tower architects. M&A activity targets telemetry data lakes and machine learning capabilities, while strategic partnerships embed compliance modules directly into client ERP architectures.
Within the pharmaceutical-certified tier, DHL Supply Chain and UPS Supply Chain Solutions exemplify infrastructure-heavy positioning through temperature-validated lane control capabilities. C.H. Robinson occupies a distinct position among algorithm-driven intermediaries compressing tender-to-acceptance cycles through proprietary freight-matching platforms. XPO Logistics anchors the dedicated fleet vector, leveraging North American less-than-truckload footprints to secure enterprise account capacity commitments. These three patterns illustrate how competitive differentiation increasingly rests on data architecture depth rather than physical asset scale.
| Leading Market Players |
|---|
| XPO Logistics |
| C.H. Robinson |
| DHL Supply Chain |
| DB Schenker |
| Kuehne + Nagel |
| UPS Supply Chain Solutions |
| GEODIS |
| DSV |
| FedEx Logistics |
| Others |
Pricing and Supply Chain Analysis
The Inland Empire distribution cluster concentrates pharmaceutical cold chain capacity that commands premium platform fees for FDA-validated lane control, while Texas logistics hubs absorb margin compression from carrier capacity fragmentation in cross-border freight corridors. California port-adjacent shippers managing semiconductor availability volatility drive pricing power through predictive ETA accuracy guarantees embedded in multimodal contracts.
Pricing Analysis
The customization-premium spread separates pharmaceutical-certified cold chain orchestration from standard transportation management, with temperature-validated documentation and 24/7 exception management commanding three to four times baseline platform fees. Price differentiation hinges on FDA certification tier and geographic delivery velocity, with Midwest and Southeast pharmaceutical operators least sensitive to unit-rate increases due to compliance risk exposure. Pricing pressure stems from digital freight matching platforms compressing tender-to-acceptance cycles, eroding margins for asset-light intermediaries lacking telemetry data depth. SME shippers exhibit highest price sensitivity, gravitating toward self-service API tiers with limited customization scope.
Supply Chain Analysis
Supplier-financing facilities through supply-chain finance programs anchor working capital arrangements between 4PL platforms and tier-two carrier networks, extending payment terms to match cash conversion cycles. Component dependencies center on cloud infrastructure services from domestic hyperscalers, telematics hardware from Taiwan and South Korea, and specialized cold chain equipment from Germany and Japan. Single-source vulnerability concentrates in API architecture talent pools, where control tower engineer scarcity commands salary premiums that compress provider margins. Distribution runs through California and Texas port-adjacent clusters anchoring transcontinental freight flows, with inland markets dependent on fragmented tier-three trucking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of professionals bridging supply chain operations and API architecture expertise constrains platform scalability, forcing buyers to compete for limited integration engineering capacity. This capability gap rewards early movers who lock in specialized talent through dedicated control tower development programs.
For Market Incumbents: Entrench market position by acquiring telemetry data lakes and machine learning capabilities that power predictive ETA engines, while embedding FDA compliance modules directly into client ERP architectures to raise switching costs. DHL Supply Chain and UPS Supply Chain Solutions demonstrate infrastructure-heavy positioning through pharmaceutical-certified cold chain investments that competitors cannot replicate without multi-year capital deployment. Backward integration into proprietary freight-matching algorithms compresses tender-to-acceptance cycles and captures margin from spot market volatility. For New Entrants and Emerging Players: Mid-market retail shippers in the Midwest and Southeast represent the most penetrable entry point, as these segments lack dedicated control tower engineering and accept modular service components through standardized API configurations. Battery supply chain localization under Inflation Reduction Act domestic content requirements creates white-space opportunity in lithium-ion logistics pulled from Asia-Pacific toward North American networks. A gain-share contracting model tied to inventory velocity metrics differentiates against incumbent unit-rate pricing and aligns incentives with working capital optimization. For Investors and Strategic Acquirers: Long-term, this sits as a data-infrastructure play because competitive differentiation increasingly rests on telemetry ingestion depth and predictive analytics capability rather than physical asset scale. Acquisition targets should display validated carrier emissions databases positioned for SEC climate disclosure advisory revenue streams. The signal to watch is autonomous freight matching convergence, where telematics data lakes and machine learning models enable dynamic capacity pricing that captures margin from spot market volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-connected visibility layers displace legacy ERP modules through real-time tier-three carrier telemetry ingestion. |
| Acquisition of Specialist Firm | Telemetry data lakes and machine learning capabilities compress tender-to-acceptance cycles in digital freight matching. |
| Strategic Partnership | FDA compliance module embedding directly into client ERP architectures raises switching costs and secures renewal rates. |
| Geographic Expansion | Texas and California port-adjacent distribution clusters anchor transcontinental freight flows for enterprise accounts. |
| Product Launch | Cloud-native control tower platforms with predictive exception management redefine vendor selection criteria for pharmaceutical manufacturers. |
Research Methodology
A spread of perspectives from 4PL platform engineers, pharmaceutical supply chain directors, freight brokerage operations heads, and carrier fleet managers converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from FMCSA regulatory filings, EPA SmartWay program databases, FDA Drug Supply Chain Security Act guidance documents, and SEC climate disclosure proposal records. Bottom-up contract value aggregation across service type and industry vertical segments triangulated against top-down market sizing from logistics infrastructure investment flows.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling Transportation Management, Supply Chain Consulting, Inventory Management, and Order Fulfillment service categories alongside Pharmaceutical, Consumer Electronics, Retail, and Automotive industry verticals. Deployment model segmentation captured Integrated Logistics, Cross-Docking, Pool Distribution, and Direct Delivery configurations. CAGRs derived from historical contract value trajectories adjusted for regulatory mandate acceleration and cloud platform displacement rates, with semiconductor inventory volatility and FDA serialization compliance timelines as key forecast inputs.
Practitioners should monitor carrier capacity fragmentation trends, cybersecurity incident frequencies affecting API-connected visibility layers, and SEC climate disclosure finalization timing for early signals of forecast deviation. Macroeconomic contraction compressing enterprise logistics outsourcing budgets, regulatory delay in pharmaceutical track-and-trace mandates, or technological breakthrough in autonomous freight matching would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Digital Freight Matching Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Hong Kong Freight and Logistics Market