
 Shipping Container Market | 2026-2036
Shipping Container Market Size, Share, and Industry Trends Forecast 2026-2036
Shipping Container Market Analysis
The Convention for Safe Containers (CSC) plate certification is reorganizing the competitive landscape for new container procurement, as carriers and leasing firms now prioritize suppliers with sustained compliance records. CIMC leverages its integrated steel supply and massive production campuses to dominate standard dry container output. Maersk Container Industry anchors the refrigerated segment through proprietary cooling technology and direct fleet ownership. CXIC Group Containers competes aggressively on price in the secondary market for regional shipping lines.
A shipping container is a standardized intermodal freight transport unit, typically constructed from corrugated Corten steel with corner castings designed to ISO 668 dimensional and stacking-load specifications, engineered to move seamlessly across vessel, rail, and truck without cargo handling. Dry containers occupy the mature volume core of the market, where margin compression has pushed manufacturers toward high-throughput automation. Refrigerated containers command premium pricing due to complex refrigeration machinery and tighter testing protocols. Steel remains the dominant material by tonnage, though composite panels are gaining traction in lightweight specialty designs for weight-restricted road corridors.
The International Maritime Organization enforces container weight verification rules under the SOLAS convention, forcing shippers to invest in certified weighing equipment or face port loading bans. ISO 668 and ISO 1496 structural standards govern dimensional interchangeability and test-loading requirements, directly determining which fabricators qualify for carrier and lessor procurement lists. China's Ministry of Transport and the US Coast Guard both mandate periodic inspection regimes that sustain aftermarket service demand. Stakeholders must track how EU Green Deal emissions benchmarks and emerging carbon border adjustments reshape container lifecycle economics and manufacturing location decisions.
Market Dynamics
The shipping container market is being fundamentally restructured by tightening safety inspection regimes under the CSC Convention, which now mandate digital traceability for every container's fatigue history and repair record.
Growth Catalysts
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics shipments from Indian and Swiss manufacturers are pulling demand for advanced refrigerated units with real-time telemetry.
- EU Green Deal carbon border adjustments:The emerging carbon accounting framework for imported steel products is accelerating lifecycle tracking investments across European lessor fleets.
- Port automation integration:Automated stacking cranes at Singapore and Rotterdam terminals require ISO 668 precision tolerances that only newer container generations satisfy.
Market Restraints
- Corten steel price volatility:Raw material input swings tied to Chinese blast furnace output cycles compress fabricator margins unpredictably.
- Manufacturing concentration risk:Over 80% of global box production sits within three Chinese coastal provinces, exposing supply chains to single-point weather and policy disruptions.
- Refrigerant phase-down constraints:The EU F-Gas Regulation is restricting hydrofluorocarbon availability for container cooling systems before viable alternatives achieve scale.
Strategic Opportunities
- Secondary market digitization:Blockchain-based title registries for used containers in Southeast Asian transshipment hubs reduce fraud and accelerate resale velocity.
- Lightweight composite penetration:Glass-reinforced polymer panels for weight-restricted German and Austrian alpine road corridors open premium niche positioning.
- Retrofit service bundling:CSC recertification combined with IoT sensor installation creates recurring revenue streams from aging fleets in Brazilian and South African markets.
Industry Challenges
- Welding technician scarcity:Certified Corten repair specialists are aging out of the workforce faster than apprenticeship programs in Polish and Turkish shipyards can replenish them.
- Multi-standard compliance complexity:Simultaneous adherence to ISO 1496, CSC, and SOLAS VGM rules extends new container qualification timelines by 15-20% for smaller fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipping Container Market |
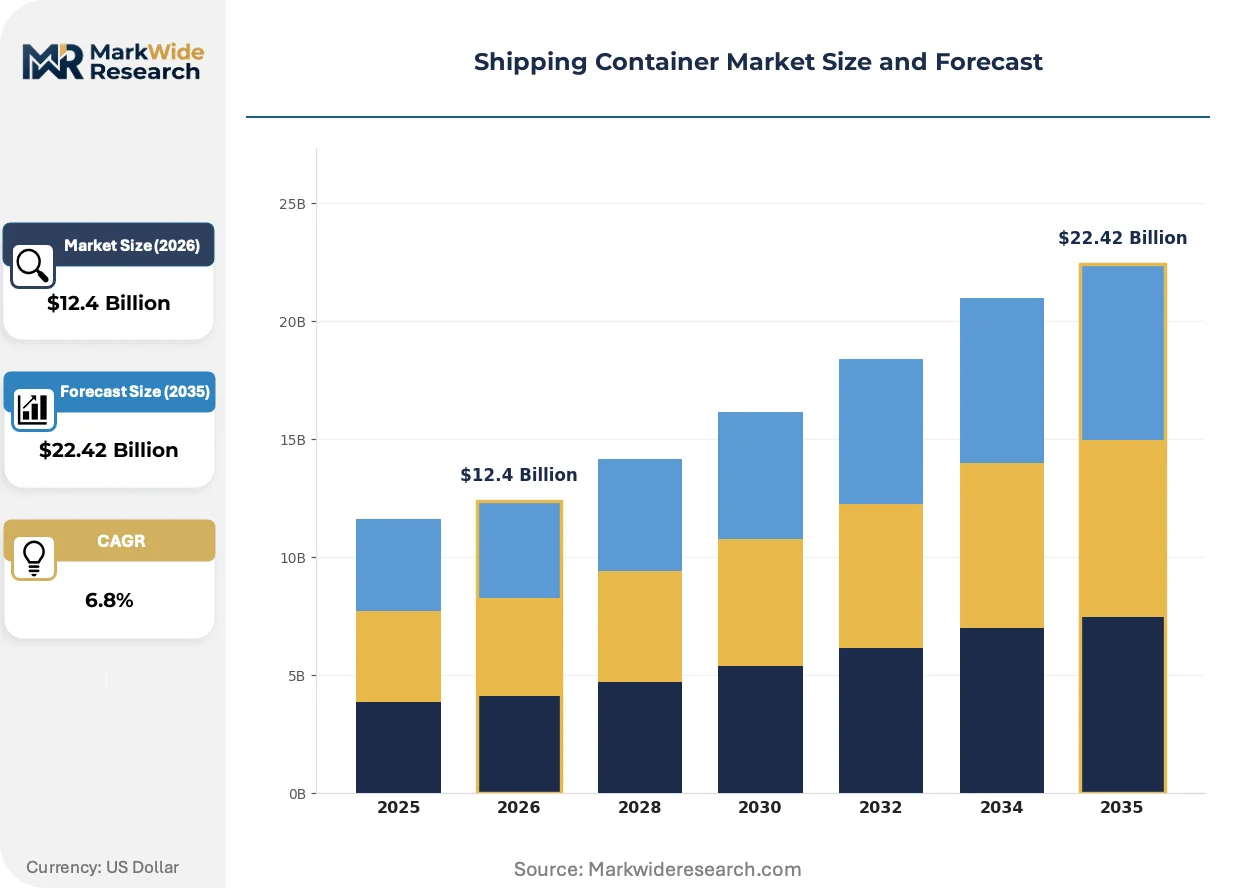
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Dry Container, Refrigerated Container, Open Top Container, Flat Rack Container Material: Steel, Aluminum, Composite, Others End User: Manufacturers, Retailers, Freight Forwarders, Logistics Companies Application: Food & Beverages, Chemicals, Pharmaceuticals, Automotive Parts |
| Companies Covered | CXIC Group Containers, Container Corporation of India, CIMC, Tricon International, Maersk Container Industry, China International Marine Containers, BSL Containers, Textainer Group, Singamas Container Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipping Container Market Emerging Trajectories
Container intelligence is migrating from passive metal boxes to active data nodes, with embedded sensors now standard on premium refrigerated units and spreading into dry cargo monitoring.
Telematics integration is fragmenting the traditional lessor-carrier information asymmetry. Refrigerated containers now ship with factory-installed GPS, door sensors, and temperature loggers that transmit via cellular or satellite to cloud platforms. Pharmaceutical shippers and fresh produce traders are demanding this visibility as a baseline procurement condition. The technology is fragmenting fleet management into granular, per-container subscription services rather than bulk equipment leases.
REACH chemical registration requirements are tightening surface coating specifications for containers entering European ports. Manufacturers must now document full substance inventories for anti-corrosion paints and timber floor treatments. Dry container fabricators serving North European routes are reformulating coating systems to exclude restricted phthalates and heavy metals. The regulation is compressing supplier qualification lists to those with dedicated EU compliance laboratories.
Leasing contract structures are compressing duration and unbundling maintenance obligations. Carriers are shifting from decade-long full-service leases toward shorter operating leases with separate service agreements. This fragmentation lets asset-light shipping lines match container capacity to volatile trade lane demand. The shift is most pronounced on Asia-Europe and transpacific corridors where freight rate volatility has spiked.
Shipping Container Market Segmentation
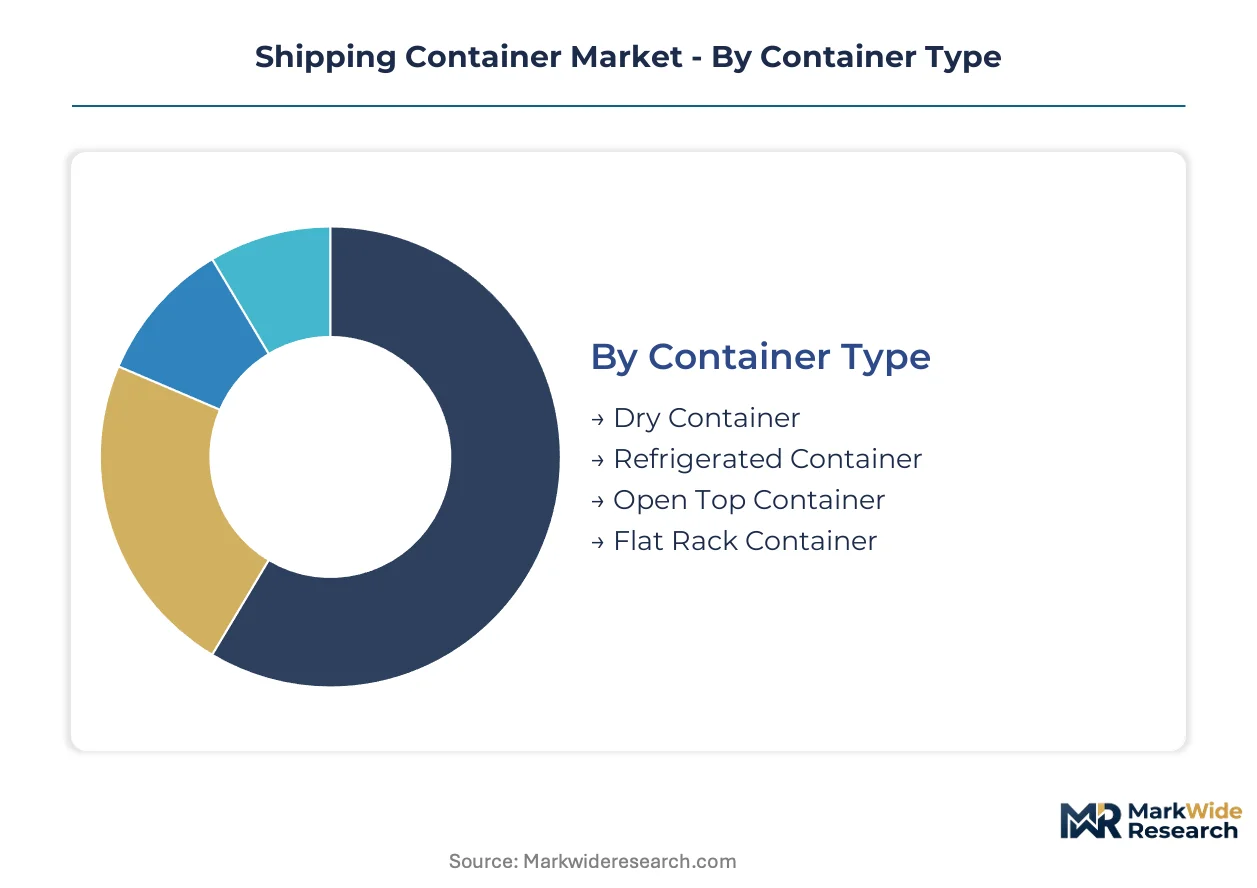
Container segmentation reveals how margin pools concentrate in temperature-controlled equipment and premium-grade materials. Procurement patterns diverge sharply between asset-heavy carriers seeking standardization and specialized operators chasing niche payload economics.
Container Type:
Margin pools concentrate in refrigerated units where complex machinery sustains premium pricing, while dry containers compete on throughput automation.
- Dry Container:Corrugated Corten steel construction with ISO 668 corner castings handles general cargo across intermodal networks. Demand clusters with Chinese export manufacturers and Southeast Asian transshipment hubs where volume throughput compresses per-unit margins. SOLAS VGM weight verification rules force shippers toward newer fleets with certified tare precision.
- Refrigerated Container:Integrated cooling machinery with real-time telemetry monitors temperature-sensitive biologics and fresh produce. Indian pharmaceutical exporters and Swiss vaccine manufacturers pull demand for units with GPS tracking and cellular data transmission. EU F-Gas Regulation refrigerant phase-downs constrain cooling system refurbishment economics.
- Open Top Container:Removable tarpaulin roof accommodates heavy machinery and bulk minerals loading from above.
- Flat Rack Container:Collapsible end walls transport oversized cargo including construction equipment and yacht hulls.
The dominant share belongs to dry containers, while refrigerated containers are closing the gap fastest.
Material:
Cost tiers separate commodity steel from lightweight composites where road weight restrictions create premium positioning.
- Steel:Corten weathering steel dominates tonnage with anti-corrosion properties and weld-repair compatibility. Chinese blast furnace output cycles drive raw material price volatility that compresses fabricator margins unpredictably. REACH chemical registration tightens coating specifications for European port entry.
- Composite:Glass-reinforced polymer panels reduce tare weight for German and Austrian alpine corridors with strict axle load limits. Freight forwarders serving Central European road networks absorb material premiums to maximize legal payload capacity.
- Aluminum:Corrosion resistance suits coastal chemical shipments with aggressive salt exposure.
- Others:Experimental materials including fiber-metal laminates test durability in niche military and aerospace logistics.
Steel commands volume leadership, with composites expanding most quickly in weight-restricted corridors.
End User:
Customer type determines contract structure, from manufacturers seeking equipment ownership to logistics companies preferring operating leases.
- Logistics Companies:Third-party providers manage container fleets across multiple carrier clients with flexible lease terms. Singapore and Rotterdam port automation drives demand for ISO 668 precision tolerances that integrate with automated stacking cranes.
- Freight Forwarders:Intermediaries coordinate multimodal shipments requiring rapid container repositioning across inconsistent trade lanes. Blockchain-based title registries in Southeast Asian hubs reduce fraud and accelerate resale velocity for aging assets.
- Manufacturers:Exporters of machinery and electronics favor owned equipment for predictable capacity.
- Retailers:Fast-fashion and consumer goods importers prioritize speed over asset control.
Logistics companies hold the dominant share, while freight forwarders are gaining share fastest through digital platform integration.
Application:
Application segmentation tracks cargo value density and regulatory intensity, from commodity food shipments to validated pharmaceutical cold chains.
- Pharmaceuticals:Temperature-sensitive biologics require continuous cold chain documentation for FDA and EMA compliance. Real-time telemetry with door sensors and temperature loggers transmits via satellite to cloud platforms as baseline procurement conditions.
- Food & Beverages:Fresh produce and frozen proteins demand refrigerated capacity with shorter lease durations matching seasonal harvest cycles. Brazilian and South African markets sustain retrofit service demand for CSC recertification combined with IoT sensor installation.
- Chemicals:Hazardous material classifications mandate specific container integrity testing under IMO dangerous goods codes.
- Automotive Parts:Just-in-time manufacturing networks require precise delivery windows with minimal container detention.
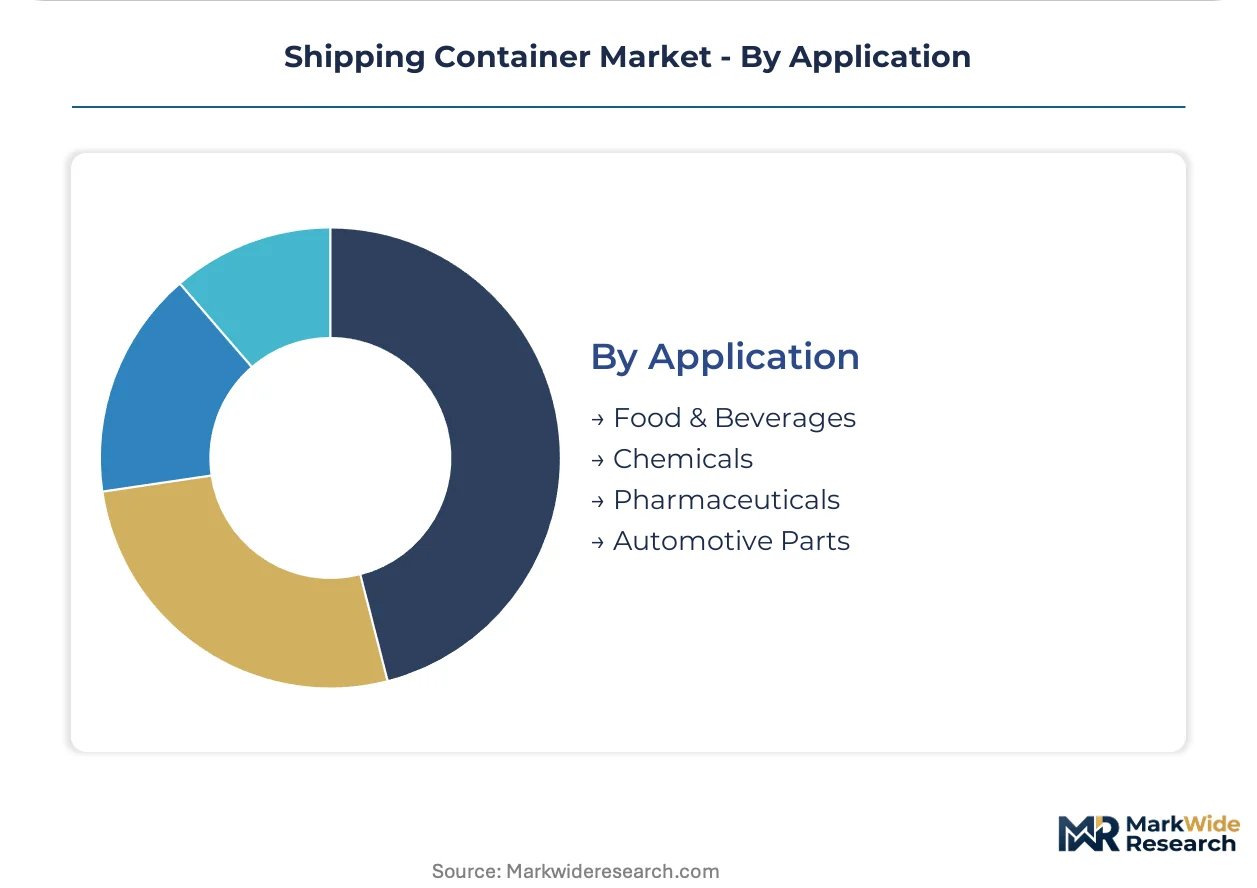
Food and beverages dominates by volume, while pharmaceuticals shows the steepest expansion trajectory on cold chain investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors China's dominance in container throughput, processing over 47 million TEU annually and underwriting the country's manufacturing-export nexus. This infrastructure concentration shapes procurement patterns across major trading economies.
China
Container fabrication clusters in Jiangsu, Zhejiang, and Guangdong provinces supply over 80% of global dry box output. MIIT production quotas and dual carbon goals are forcing blast furnace efficiency upgrades that compress steel input costs unpredictably. Qingdao and Ningbo port automation drives demand for ISO 668 precision tolerances in new fleet orders.
United States
Long Beach and Los Angeles port complexes sustain refrigerated container demand for pharmaceutical cold chains serving Midwest distribution hubs. US Coast Guard inspection regimes under CSC Convention mandate digital traceability for fatigue history tracking. Savannah and Charleston port expansions are absorbing transshipment volume from congested Pacific gateways.
Germany
Hamburg and Bremerhaven terminals require containers meeting strict axle load limits for alpine corridor road feeders into Austria and Switzerland. EU F-Gas Regulation refrigerant phase-downs constrain cooling system refurbishment economics for refrigerated fleets. REACH chemical registration tightens surface coating specifications for anti-corrosion paints entering North European routes.
India
JNPT and Mundra ports handle pharmaceutical exports from Gujarat and Maharashtra manufacturing clusters pulling refrigerated container demand. CDSCO cold chain documentation requirements for temperature-sensitive biologics mandate real-time telemetry as baseline procurement. Chennai and Visakhapatnam container terminals are expanding capacity for Southeast Asian transshipment.
Singapore
The Tuas mega-port automation program demands ISO 668 precision tolerances compatible with automated stacking cranes. Maritime and Port Authority certification protocols align with SOLAS VGM weight verification enforcement. The city-state's lessor headquarters concentration shapes regional lease contract standardization across Southeast Asian hubs.
Shipping Container Market Vendor Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The vendor base concentrates among Chinese state-affiliated manufacturers and European leasing conglomerates with integrated fleet management platforms. Three archetypes dominate: scale-driven fabricators with captive steel supply, technology-anchored refrigerated specialists, and asset-light regional lessors competing on repositioning efficiency. Capacity expansion and strategic partnerships represent the dominant competitive moves as carriers seek supply security.
Among Chinese fabricators, CIMC and CXIC Group Containers exemplify scale-driven archetypes with integrated production campuses. Maersk Container Industry anchors the refrigerated segment through proprietary cooling technology positioning. These three entities represent distinct strategic postures—integrated manufacturing, price-aggressive secondary market presence, and premium machinery differentiation—without overlapping capability claims.
| Leading Market Players |
|---|
| CXIC Group Containers |
| Container Corporation of India |
| CIMC |
| Tricon International |
| Maersk Container Industry |
| China International Marine Containers |
| BSL Containers |
| Textainer Group |
| Singamas Container Holdings |
| Others |
Supply Flow & Price Mechanics
Ninety-day order-to-delivery windows for refrigerated containers from Jiangsu province compress pricing power for regional lessors while amplifying margin capture for integrated fabricators with captive steel supply. This lead-time concentration rewards carriers and leasing firms that lock multi-year offtake agreements with CIMC and CXIC Group, while spot buyers absorb volatility from Chinese blast furnace output cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CSC-certified newbuilds from refurbished units and secondary-market distressed assets. Price differentiation rests on ISO 1496 structural certification grade and real-time telemetry integration for pharmaceutical cold chains. Pricing pressure stems from Corten steel input volatility tied to MIIT production quotas, compressing fabricator margins unpredictably. Asset-light freight forwarders exhibit highest price sensitivity, while pharmaceutical shippers absorbing premium for validated cold chain documentation show lowest elasticity.
Supply Chain Analysis
Inbound logistics costs from Shanghai Yangshan port congestion and Red Sea route disruptions amplify working capital requirements for European lessors sourcing from Chinese fabrication clusters. Supply concentrates in Jiangsu, Zhejiang, and Guangdong provinces, drawing from Australian iron ore and domestic coking coal. Single-source vulnerability pervades the 80%-plus production concentration within three coastal provinces. Distribution runs through Singapore and Rotterdam transshipment hubs before final positioning at destination terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among top-ten container leasing conglomerates, fragmenting procurement leverage for mid-tier regional carriers and forcing supplier consolidation responses.
For Market Incumbents: Shield core fleet relationships by embedding IoT telemetry and CSC recertification into long-term service contracts before CXIC Group captures secondary-market share through aggressive price positioning. Prioritize backward integration into Corten steel supply through offtake agreements with Chinese blast furnace operators, insulating margin compression from MIIT quota volatility. For New Entrants and Emerging Players: Retrofit service bundling for aging Brazilian and South African refrigerated fleets represents the most penetrable white-space target, where welding technician scarcity has incumbents retreating from aftermarket support. Enter through digital platform partnerships offering blockchain-based title registries that accelerate resale velocity for used containers in Southeast Asian hubs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized container leasing subsidiaries lacking integrated fleet management platforms. Long-term viability favors refrigerated specialists with proprietary cooling technology and pharmaceutical cold chain certification. Watch EU F-Gas Regulation enforcement intensity as inflection signal for cooling system refurbishment economics.| Strategic Initiative | Industry Significance |
|---|---|
| CSC Digital Traceability Investment | MIIT mandates fatigue-history tracking that rewards compliant fabricators with carrier procurement access. |
| Refrigerated Fleet Expansion | Indian pharmaceutical exporters pull demand for units with GPS and cellular data transmission capabilities. |
| Lightweight Composite Manufacturing | Glass-reinforced polymer panels address German and Austrian alpine corridor axle load restrictions. |
| Retrofit Service Platform Buildout | Brazilian and South African markets sustain recurring revenue from CSC recertification combined with IoT installation. |
| Blockchain Title Registry Deployment | Southeast Asian transshipment hubs reduce fraud and accelerate resale velocity for aging container assets. |
Methodological Framework
Desk research of customs trade data, ISO certification registries, and carrier fleet disclosure filings preceded structured interviews with container lessor procurement directors, shipyard operations managers, and refrigerated container service technicians. Primary fieldwork across Jiangsu and Guangdong fabrication clusters validated production capacity assumptions against MIIT output disclosures. Bottom-up unit economics triangulated with top-down trade flow analysis across the projection horizon.
Variance decomposition across container type, material grade, end-user category, and application segment informed volume and value outputs throughout the forecast period. CAGRs derived from regression against port throughput trajectories at Shanghai Yangshan, Singapore Tuas, and Rotterdam Maasvlakte, cross-referenced with pharmaceutical cold chain investment disclosures and EU Green Deal carbon border adjustment implementation timelines.
Material uncertainties — Chinese dual carbon policy acceleration, EU F-Gas refrigerant phase-down enforcement, and Red Sea route stability — sit outside the modeled envelope. Forecasts reflect assumptions around Corten steel input cost normalization and CSC digital traceability adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Europe Logistics Automation Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Freight and Logistics Market