
 Moving Services (Mover and Packers) Market | 2026-2036
Moving Services (Mover and Packers) Market Size, Share, and Industry Trends Forecast 2026-2036
Moving Services (Mover and Packers) Market Insights
DOT hours-of-service regulations is expanding the cost-of-entry calculus for new fleet operators, forcing capital commitments to electronic logging devices and driver scheduling infrastructure. United Van Lines leverages its agent network to sustain coverage density across North American corridors. Atlas Van Lines differentiates through specialized corporate relocation services that anchor its enterprise customer base.
Moving services encompass the physical transport, packing, loading, and unpacking of household or commercial goods using motorized vehicles with gross vehicle weight ratings typically exceeding 10,000 pounds, coordinated through centralized dispatch and inventory tracking systems. The primary commercial purpose is reducing relocation friction for individuals and organizations undergoing geographic transitions. Residential moving dominates transaction volume while commercial moving commands higher per-job margins due to complexity and liability exposure. Full-service delivery leads revenue pools as customers prioritize turnkey convenience over self-service alternatives.
FAA regulations govern air freight segments of international relocation chains, while FMCSA safety standards dictate driver qualification and vehicle maintenance protocols across interstate operations. EPA emissions tiers are forcing fleet turnover toward cleaner diesel and alternative-fuel platforms, raising capital intensity for smaller operators. Stakeholders must monitor how state-level labor classification disputes reshape contractor versus employee cost structures before committing to network expansion.
Market Dynamics
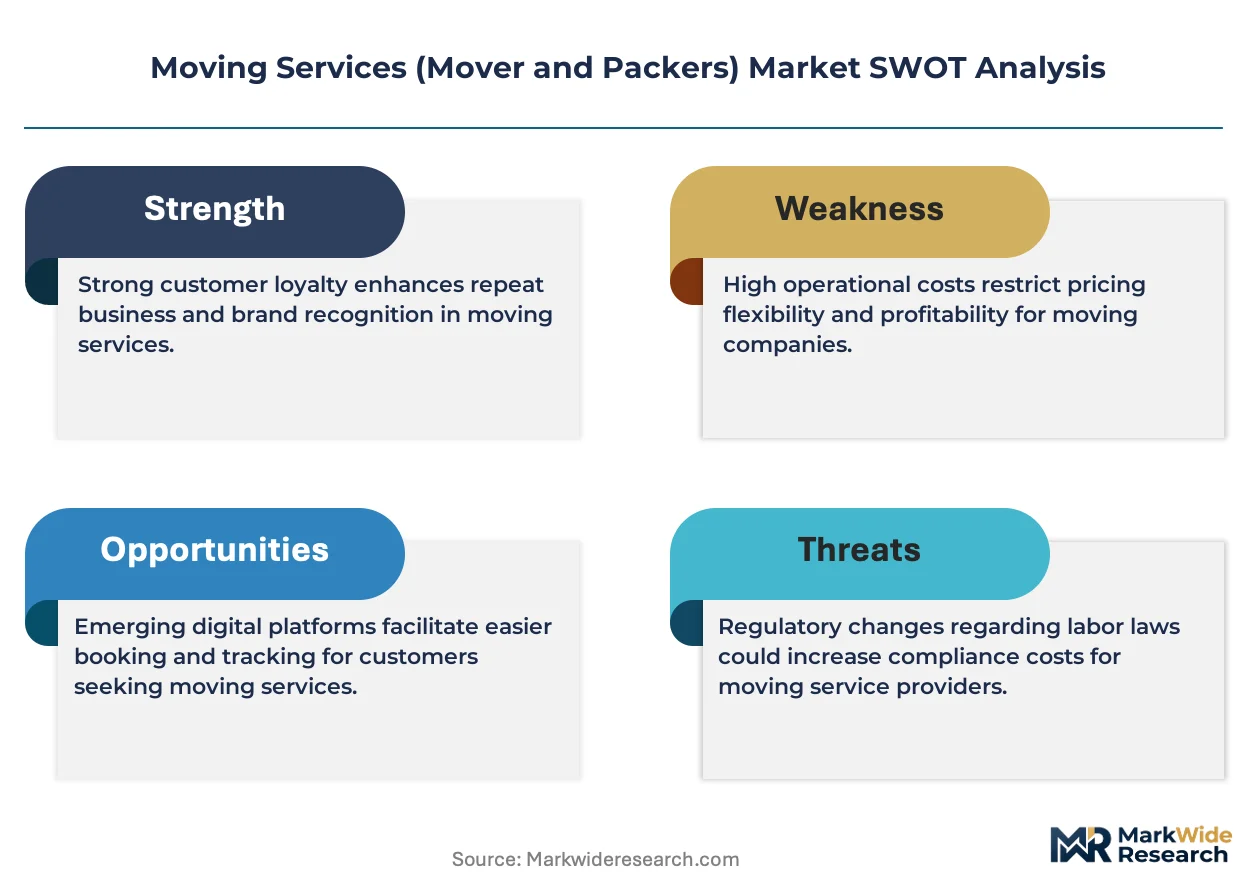
Fleet economics are compressing under the weight of EPA emissions tiers and DOT hours-of-service mandates, forcing operators to recalibrate capital deployment toward electronic logging infrastructure and cleaner diesel or alternative-fuel platforms.
Growth Catalysts
- Corporate Relocation Velocity:Multinational firms expanding distributed workforces across Germany, Australia, and the United States are sustaining cross-border talent mobility volumes that anchor commercial moving demand.
- FAA Air Freight Integration:International relocation chains incorporating regulated air freight segments are compressing delivery windows for high-value household goods shipments.
- Urbanization Density:Metropolitan clustering in Dallas, Sydney, and Frankfurt is generating repeat residential turnover that feeds transaction volume for full-service providers.
Market Restraints
- Driver Availability Squeeze:FMCSA safety standards and DOT hours-of-service rules are tightening qualified labor pools, elevating wage pressure across interstate corridors.
- Fleet Capital Intensity:EPA emissions compliance is forcing accelerated turnover toward cleaner diesel and alternative-fuel platforms, raising barrier-to-entry calculus for smaller operators.
- Insurance Liability Escalation:Commercial moving's higher per-job exposure to damage claims is compressing margin structures relative to residential segments.
Strategic Opportunities
- Last-Mile Unbundling:Self-storage facility partnerships in Texas and Florida are creating hybrid service models that capture customers seeking modular moving solutions.
- State Labor Classification Clarity:Pending regulatory resolution of contractor-versus-employee disputes in California and New York will unlock network expansion capital currently held in abeyance.
- Inventory Tracking Convergence:Centralized dispatch systems merging with IoT-enabled container monitoring are enabling premium service tiers for high-net-worth relocations.
Industry Challenges
- Electronic Logging Device Integration:DOT-mandated ELD infrastructure requires capital commitments that strain smaller fleet operators' balance sheets.
- Driver Scheduling Complexity:Hours-of-service optimization demands specialized dispatch software expertise that concentrates operational capability among larger networks.
- Cross-Regulatory Compliance:Interstate operators must simultaneously satisfy FMCSA safety protocols, FAA air freight rules, and state-level motor carrier regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moving Services (Mover and Packers) Market |
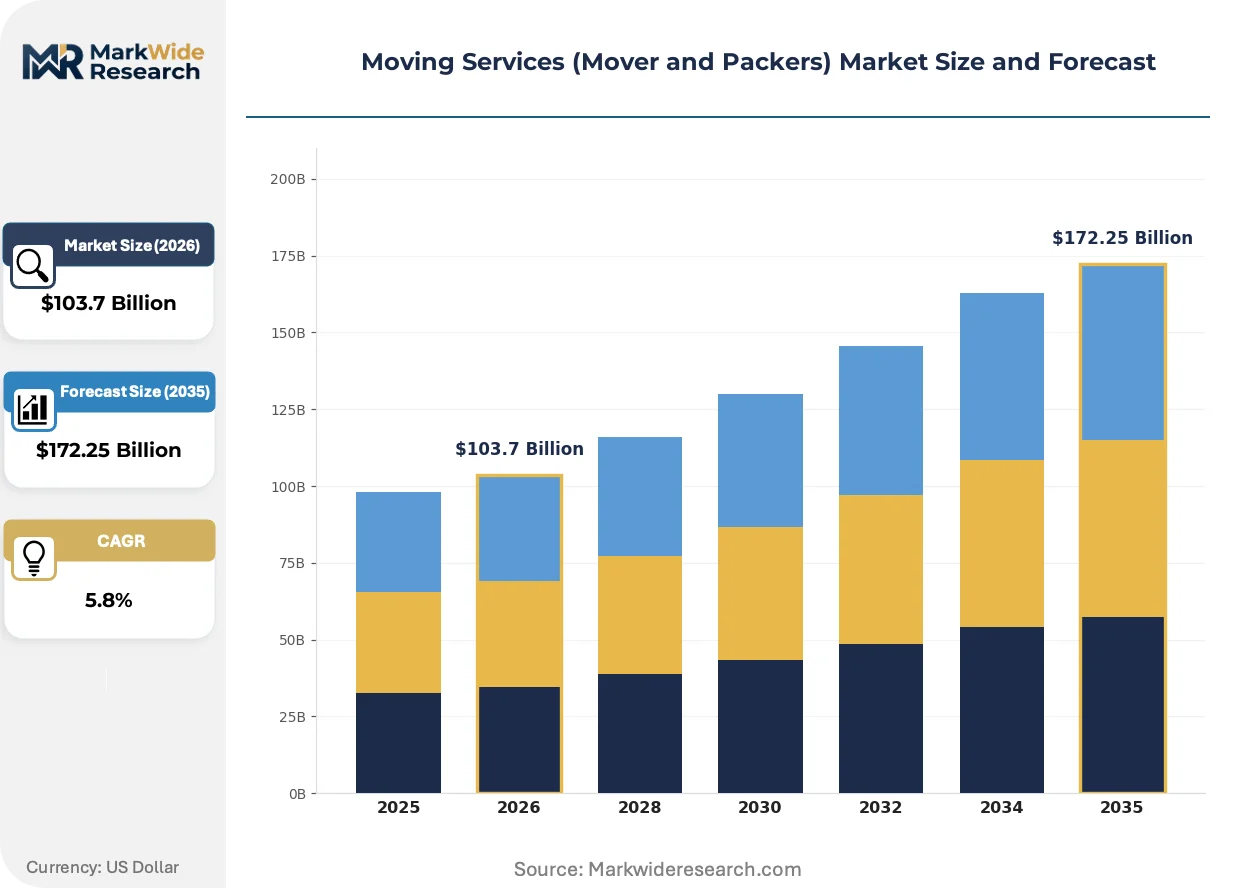
| Market Size in 2026 | $103.7 Billion |
| Market Size in 2035 | $172.25 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Moving, Commercial Moving, International Relocation, Local Moves Packaging Type: Boxes, Bubble Wrap, Crates, Packing Paper Delivery Mode: Full-Service Delivery, Self-Service Delivery, Scheduled Delivery, Express Delivery Customer Type: Individuals, Businesses, Government Agencies, Nonprofits |
| Companies Covered | United Van Lines, Allied Van Lines, Atlas Van Lines, Mayflower Transit, North American Van Lines, Armstrong Relocation and Companies, AGS Worldwide Movers, Arpin Van Lines, Wheaton World Wide Moving, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moving Services (Mover and Packers) Market Trends and Innovations
Operational technology is compressing coordination friction across fragmented supply chains while regulatory pressure and shifting buyer expectations are redefining service delivery architectures.
Internet-of-Things sensors embedded in shipping containers are integrating real-time location and condition monitoring into centralized dispatch platforms. Corporate relocation managers and high-value residential customers are adopting these visibility tools at accelerating rates. The technology is integrating inventory accountability directly into contract structures, compressing dispute resolution cycles and enabling outcome-based pricing mechanisms.
EPA emissions tiers are forcing fleet turnover toward cleaner diesel and alternative-fuel platforms with accelerating capital intensity. Operators face compressed replacement cycles and elevated compliance documentation burdens. Long-haul interstate segments serving corporate relocation accounts are absorbing the steepest cost adjustments through rate renegotiation.
Buyer preferences are fragmenting away from turnkey full-service contracts toward modular unbundling of packing, transport, and unpacking functions. Digital marketplace platforms connecting consumers with independent labor and vehicle providers are capturing share in metropolitan corridors. This disintermediation is most visible in Sun Belt cities where younger demographics prioritize cost transparency over single-vendor convenience.
Moving Services (Mover and Packers) Market Segmentation
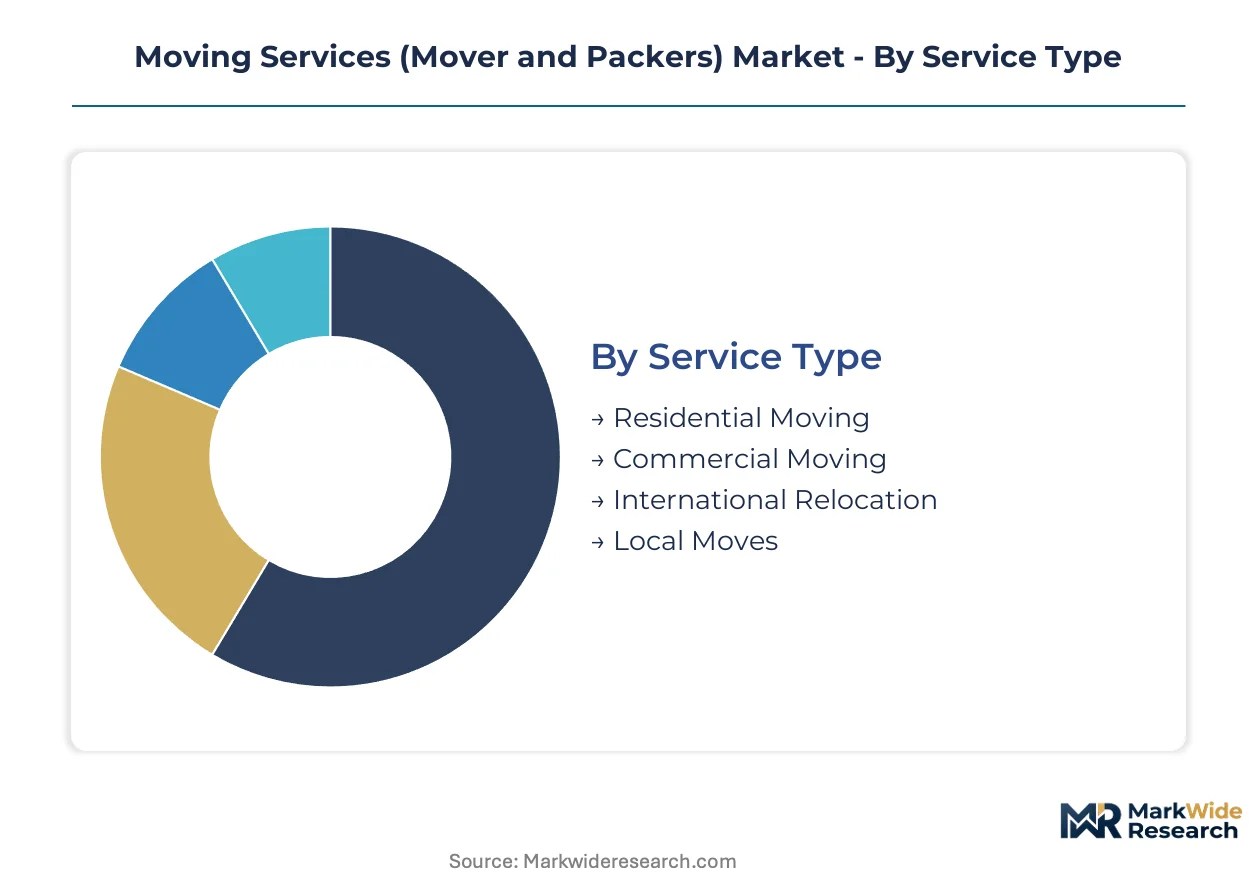
Moving services fragment across service intensity, physical materials, delivery coordination, and client risk profiles. Each segmentation axis carries distinct margin structures and capital requirements that reshape operator positioning.
Service Type:
Customization intensity spans from standardized local transport to highly orchestrated international chains requiring multi-modal coordination and customs brokerage.
- Residential Moving:Household goods transport within single metropolitan areas or across state lines using straight trucks and tractor-trailers. Volume concentrates in Sun Belt cities including Dallas, Phoenix, and Atlanta where housing turnover feeds repeat demand. FMCSA safety standards govern driver qualification and vehicle maintenance across these interstate corridors.
- Commercial Moving:Office equipment, industrial machinery, and institutional assets requiring specialized rigging, crating, and liability coverage. Demand anchors in corporate relocation accounts across Germany, Australia, and the United States where multinational firms sustain cross-border talent mobility. Per-job margins exceed residential segments due to complexity and damage exposure.
- International Relocation:Multi-modal coordination combining ocean freight, air cargo, and final-mile ground transport across customs jurisdictions.
- Local Moves:Same-day or short-haul transport within single metropolitan statistical areas using smaller straight trucks and crewed labor.
Most installed capacity flows through Residential Moving. Expansion is steepest in Commercial Moving.
Packaging Type:
Material selection tracks asset value sensitivity and transport mode, with premium protection commanding price multiples over standard commodity options.
- Boxes:Corrugated fiberboard containers in standardized dimensions for general household goods. Volume dominance in residential segments across Texas and Florida where self-packing remains prevalent.
- Bubble Wrap:Polyethylene air-cushioning sheeting for fragile electronics, glassware, and artwork. Demand concentrates in high-value residential relocations and corporate IT equipment moves.
- Crates:Rigid wooden or plastic containers for industrial machinery, fine art, and sensitive instruments requiring custom dimensions.
- Packing Paper:Unprinted newsprint for surface protection and void fill in cost-sensitive residential applications.
Boxes carry the highest throughput volume. Crates are gaining share fastest in premium corporate relocation contracts.
Delivery Mode:
Service architecture ranges from turnkey coordination to unbundled labor-marketplace models, with buyer preferences fragmenting toward modular solutions.
- Full-Service Delivery:End-to-end coordination encompassing packing, loading, transport, unloading, and unpacking through single-vendor accountability. Revenue concentration in corporate relocation accounts and high-net-worth residential segments where time scarcity outweighs cost sensitivity. EPA emissions compliance costs flow through rate structures on long-haul interstate segments.
- Self-Service Delivery:Customer-managed packing and loading with purchased transport-only services. Growth accelerates in metropolitan corridors where digital platforms connect buyers with independent vehicle operators.
- Scheduled Delivery:Date-specific coordination with guaranteed arrival windows for corporate relocation policies.
- Express Delivery:Compressed timeline transport with premium pricing for urgent household goods or critical business assets.
Full-Service Delivery anchors revenue pools. Self-Service Delivery is expanding most quickly among younger demographics in Sun Belt metros.
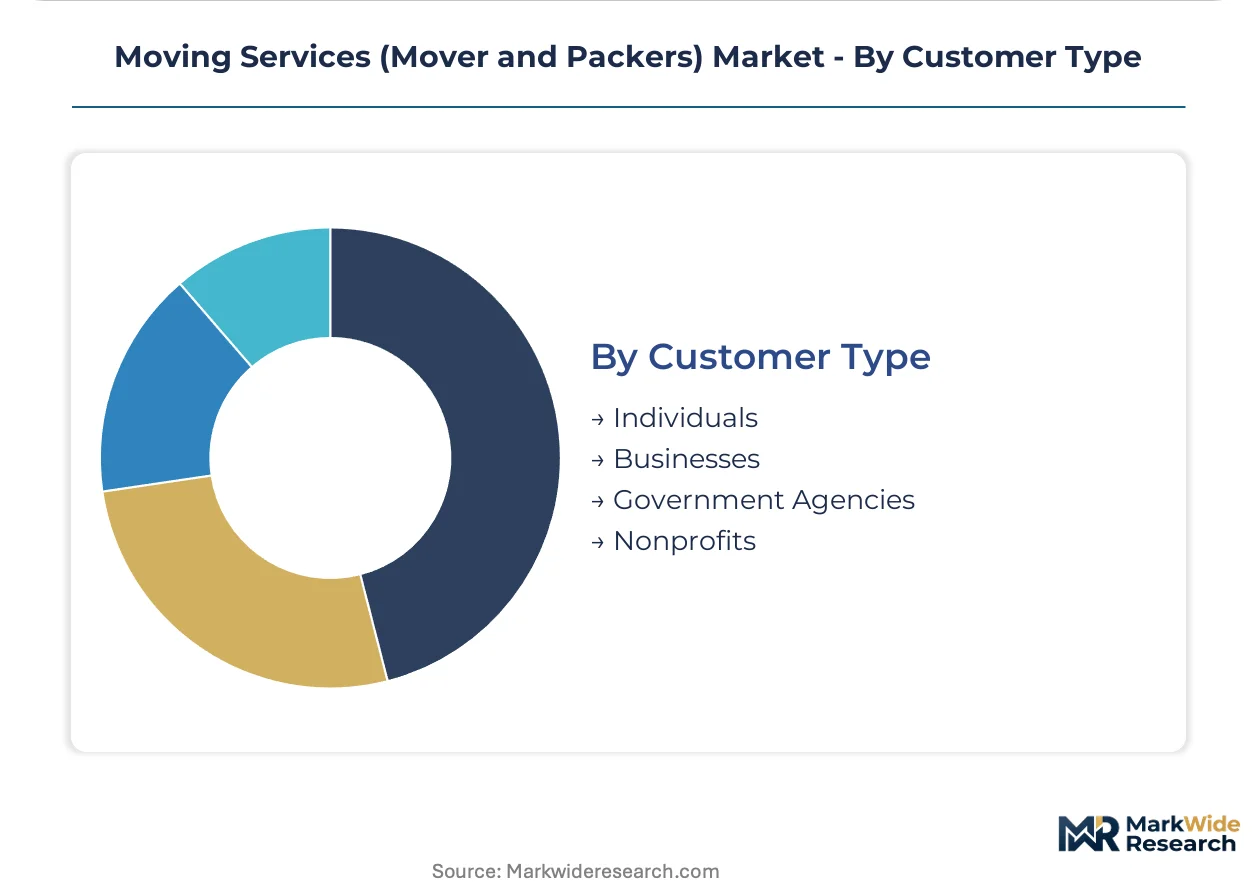
Customer Type:
Risk tolerance and procurement sophistication vary sharply across individual, institutional, and public-sector accounts.
- Individuals:Household decision-makers purchasing relocation services through direct-to-consumer channels. Price transparency demands intensify through digital marketplace comparison tools.
- Businesses:Corporate procurement functions managing employee relocation benefits and office moves. Contract structures increasingly incorporate IoT-enabled inventory tracking and outcome-based pricing mechanisms.
- Government Agencies:Federal, state, and municipal procurement subject to competitive bidding and prevailing wage requirements.
- Nonprofits:Mission-driven organizations with constrained budgets and donated asset transport needs.
Businesses command the highest per-transaction value. Individuals generate the steepest volume expansion through repeat residential turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The moving services industry traces its modern operational lineage to post-war United States interstate highway expansion, which established the long-haul fleet infrastructure and agent-network business models that now dominate cross-border relocation corridors across multiple continents.
United States
Corporate relocation velocity and Sun Belt residential turnover sustain transaction density across Dallas, Phoenix, and Atlanta metropolitan corridors. FMCSA safety standards and DOT hours-of-service regulations govern interstate fleet operations, compressing driver scheduling flexibility. EPA emissions tiers are accelerating fleet turnover toward alternative-fuel platforms along California-to-Texas freight corridors.
Germany
Multinational corporate talent mobility and industrial machinery relocation anchor commercial demand across Frankfurt, Munich, and Hamburg logistics clusters. KBA vehicle certification requirements and EU emissions standards reshape fleet procurement economics. The Rhine-Ruhr industrial corridor concentrates specialized rigging capacity for precision equipment moves.
Australia
Cross-border executive relocation and mining camp logistics sustain volume across Perth, Sydney, and Brisbane. TGA-equivalent transport regulations and state-level heavy vehicle accreditation govern interstate operations. Urbanization density in Greater Sydney generates repeat residential turnover for full-service providers.
United Kingdom
London-based financial services relocation and EU trade corridor adjustments drive commercial moving demand. DVSA operator licensing and post-Brexit customs documentation requirements complicate international relocation chains. The M4 corridor concentrates corporate relocation service capacity for technology sector clients.
Canada
Interprovincial resource sector mobility and Toronto-Vancouver residential turnover sustain fleet utilization across the Trans-Canada Highway network. Transport Canada commercial vehicle standards and provincial weight restrictions govern cross-border operations with US corridors. Calgary and Edmonton anchor energy sector relocation demand.
Moving Services (Mover and Packers) Market Competitive Landscape
The competitive structure tilts toward agent-network federations with distributed geographic coverage rather than centralized corporate ownership. Fleet-based operators coexist with labor-marketplace platforms that unbundle service components. Two dominant archetypes prevail: legacy van-line networks with established corporate relocation accounts, and technology-enabled platforms connecting consumers with independent vehicle operators. Consolidation through agent-network acquisitions and strategic partnerships with self-storage operators represent the primary competitive moves reshaping market structure.
Within the legacy van-line tier, United Van Lines and Atlas Van Lines exemplify the agent-network federation model, while Allied Van Lines occupies a comparable structural position with distributed coverage density. These entities represent the established competitive archetype against which digital marketplace platforms are now positioning modular service alternatives.
| Leading Market Players |
|---|
| United Van Lines |
| Allied Van Lines |
| Atlas Van Lines |
| Mayflower Transit |
| North American Van Lines |
| Armstrong Relocation and Companies |
| AGS Worldwide Movers |
| Arpin Van Lines |
| Wheaton World Wide Moving |
| Others |
Pricing and Supply Chain Analysis
Electronic logging device mandates and alternative-fuel fleet transitions are compressing operating cost structures while concentrating procurement leverage among capitalized networks across interstate corridors. This dual pressure reshapes how service tiers are priced and which supply chain configurations survive margin compression.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across residential and commercial segments. Full-service contracts command premiums through single-vendor accountability and guaranteed delivery windows, while self-service marketplace models compete on labor-hour transparency and vehicle-only rates. Price differentiation hinges on liability coverage tiers and IoT-enabled tracking integration. Cost compression in long-haul interstate segments is intensifying because EPA emissions compliance flows through to rate renegotiation. Individual residential buyers exhibit highest price sensitivity, while corporate relocation accounts prioritize outcome certainty over cost minimization.
Supply Chain Analysis
FMCSA driver qualification standards and DOT vehicle maintenance protocols act as certification gating that filters fleet operator participation. Vehicle manufacturing concentrates in the United States, Germany, and China. Diesel powertrains, electronic logging infrastructure, and specialized rigging equipment constitute core input dependencies. Single-source vulnerability in semiconductor-dependent telematics systems creates procurement risk. Distribution runs through agent-network federations rather than centralized corporate ownership, with final-mile coordination handled by licensed motor carriers under interstate authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The moving services market functions as a stable compounder anchored by recurring residential turnover and sustained corporate relocation velocity across talent mobility corridors.
For Market Incumbents: Extend coverage density through strategic self-storage partnerships in high-turnover Sun Belt metros. Consolidate agent-network positions to defend against labor-marketplace disintermediation. Invest in IoT-enabled inventory tracking to capture premium pricing from high-net-worth residential and corporate accounts. For New Entrants and Emerging Players: Modular service unbundling technology offers entry into metropolitan corridors where younger demographics prioritize cost transparency. White-space concentrates in hybrid storage-moving solutions across Texas and Florida. A direct-to-consumer digital platform with independent vehicle operator matching provides viable go-to-market positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fleet operators facing capital intensity from emissions compliance yet holding established interstate authority. Long-term viability favors agent-network federations with dense corporate relocation account books. Watch state-level labor classification resolution in California and New York as inflection signal for network expansion capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Agent-Network Acquisition | Consolidates geographic coverage density against digital marketplace entrants. |
| Self-Storage Partnership | Captures modular service demand in Dallas, Phoenix, and Atlanta corridors. |
| Alternative-Fuel Fleet Transition | Positions operators ahead of EPA emissions tier enforcement on interstate routes. |
| IoT Tracking Integration | Enables outcome-based pricing for high-value corporate relocation contracts. |
| ELD Infrastructure Deployment | Satisfies DOT hours-of-service mandates while concentrating dispatch capability. |
Research Methodology
Direct dialogue with fleet operations directors, corporate relocation managers, driver dispatch supervisors, and self-storage facility partners grounded qualitative findings. Secondary validation drew from FMCSA safety data, EPA emissions compliance filings, interstate commerce statistics, and motor carrier financial disclosures. Bottom-up service volume estimates triangulated against top-down addressable market sizing across the analysis window.
Top-down macroeconomic drivers and bottom-up segment-level transaction data shaped the analytical lens. Modeled dimensions spanned service intensity, delivery coordination architecture, customer risk profiles, and regional regulatory clusters. CAGRs derived from historical volume trajectories adjusted for fleet turnover cycles and labor availability constraints. Forecast inputs incorporated DOT hours-of-service enforcement intensity and state-level labor classification dispute resolution timelines.
The model holds under stable regulatory enforcement and corporate relocation policy continuity; deviation in driver availability or emissions compliance cost acceleration would shift trajectory. Forecasts reflect documented assumptions about interstate commerce growth and urbanization density patterns. A model refresh is warranted upon material change in FMCSA safety standard enforcement or federal labor classification precedent.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
Europe Logistics Automation Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market