
 United Kingdom Cold Chain Logistics Market | 2026-2036
United Kingdom Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Cold Chain Logistics Market Analytics
Buyer concentration among UK supermarket chains is pivoting toward direct control of temperature-sensitive produce flows. Reed Boardall leverages its Yorkshire-based frozen distribution network to serve consolidated retail procurement. Lineage Logistics anchors multi-temperature capacity at key port locations. DHL Supply Chain competes through integrated pharmaceutical and foodservice lanes.
United Kingdom cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods, maintaining precise thermal parameters typically between minus 25 degrees Celsius and plus 15 degrees Celsius through refrigerated vehicles, insulated containers, and climate-managed warehouses. The sector preserves product integrity across pharmaceutical, food, and chemical supply chains where thermal deviation compromises safety, efficacy, or shelf life. Refrigerated transport dominates service type revenue due to fuel and fleet asset intensity, while warehousing captures margin from automated high-bay frozen storage. Pharmaceutical product types command premium handling protocols under Good Distribution Practice standards. IoT solutions within technology segments are displacing manual temperature logging with real-time cloud telemetry.
The UK's Medicines and Healthcare products Regulatory Agency enforces GDP compliance for pharmaceutical cold chains, while the Environment Agency implements F-Gas phasedown schedules affecting refrigeration equipment replacement cycles. Food Standards Agency temperature control requirements under EC Regulation 852/2004 shape operational protocols across food manufacturing and retail distribution. Stakeholders must monitor ammonia refrigeration retrofit timelines and carbon border adjustment preparations affecting import cold chain energy accounting.
Market Dynamics
Supermarket procurement consolidation is forcing cold chain operators to surrender lane control to retail-owned networks while absorbing capital-intensive fleet renewal obligations under F-Gas phasedown mandates.
Growth Catalysts
- Pharmaceutical GDP enforcement:The Medicines and Healthcare products Regulatory Agency mandates temperature documentation across biologic distribution, expanding validated cold storage demand from vaccine and cell therapy manufacturers.
- Net-zero refrigeration retrofits:The Environment Agency's F-Gas Regulation is accelerating ammonia and CO2 system conversions in frozen warehousing, creating replacement demand for legacy HFC infrastructure.
- English Midlands distribution clustering:Birmingham-Leicester-Derby logistics corridors concentrate temperature-controlled fulfillment capacity within four-hour drive time of 90% of UK population.
Market Restraints
- Refrigerant supply concentration:Natural refrigerant compressor manufacturing concentrates in German and Danish industrial bases, exposing UK operators to euro-denominated procurement volatility and extended lead times.
- Electric grid capacity constraints:Rural warehouse locations in Lincolnshire and East Anglia face distribution network operator delays for high-amperage connections needed by electrified refrigeration plants.
- Driver qualification scarcity:The Driver and Vehicle Standards Agency's CPC certification requirements for refrigerated vehicle operation create persistent recruitment bottlenecks across temperature-controlled transport fleets.
Strategic Opportunities
- Scottish seafood export corridors:Aberdeen and Peterhead landing ports lack integrated cold chain infrastructure for direct continental EU routing, bypassing English transhipment.
- Carbon border adjustment preparation:HM Treasury's developing carbon border mechanism will require import cold chain energy accounting, creating first-mover advantage for operators with verified Scope 3 refrigeration emissions data.
- Automated high-bay frozen warehousing:Crane-based storage systems converging with warehouse management software enable 40% footprint reduction against conventional racking, unlocking brownfield site redevelopment in Greater Manchester.
Industry Challenges
- Refrigeration engineer skills gap:Industrial ammonia system maintenance requires F-Gas Category I certification combined with pressure equipment competency, with training pipeline output below replacement rate.
- Multi-temperature trailer complexity:Tri-compartment vehicles serving retail distribution centers demand precise zone calibration across frozen, chilled, and ambient specifications, increasing maintenance intervals and downtime costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Cold Chain Logistics Market |
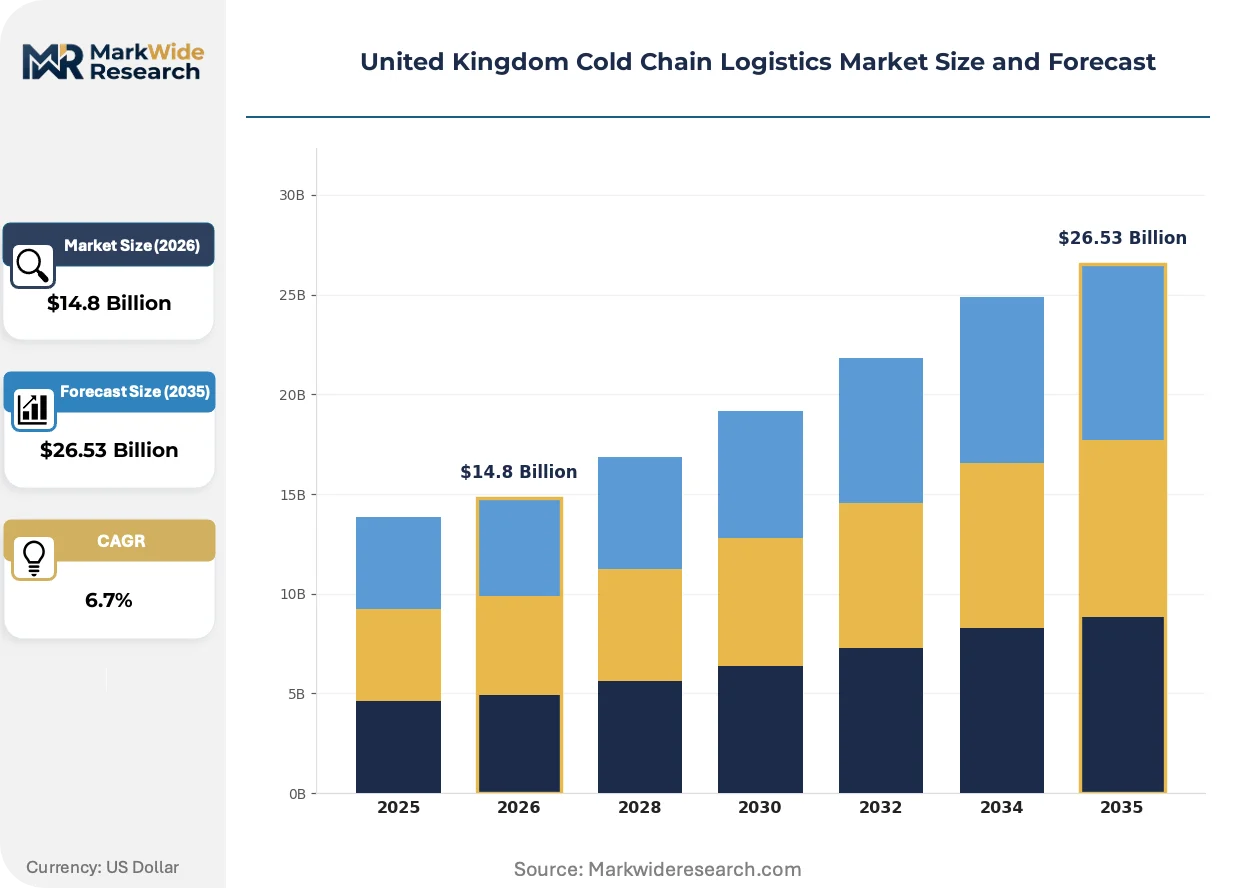
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Refrigerated Transport, Warehousing, Packaging Solutions, Monitoring Systems Product Type: Fruits, Vegetables, Pharmaceuticals, Dairy Products Technology: IoT Solutions, Temperature Control Systems, Blockchain Technology, RFID Tracking End User: Retailers, Distributors, Food Manufacturers, Healthcare Providers |
| Companies Covered | Reed Boardall, Chiltern Cold Storage Group, Lineage Logistics, DHL Supply Chain, Americold Logistics, NewCold, Gist Ltd, Turners (Soham) Ltd, Culina Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Cold Chain Logistics Market Evolving Landscape
Digital telemetry and natural refrigerant chemistry are compressing operational tolerances while fragmenting asset ownership models across pharmaceutical and food verticals.
IoT-enabled temperature logging is modularizing compliance documentation for pharmaceutical shipments. Cell therapy manufacturers and hospital pharmacies are adopting cloud-connected data loggers that transmit minute-by-minute thermal records to MHRA-auditable databases. This distributed sensor architecture is modularizing what previously required centralized quality control departments, compressing headcount at third-party logistics providers while raising technical service contract values.
The Environment Agency's F-Gas phasedown schedule is compressing equipment replacement cycles for operators with HFC-dependent infrastructure. Industrial refrigeration contractors report 18-month order backlogs for ammonia and CO2 packaged systems as warehouse operators accelerate depreciation schedules. Food manufacturing facilities in the West Midlands are most exposed, with many operating 15-year-old R404A plants now subject to escalating refrigerant reclamation costs.
Consolidated retail procurement is concentrating lane volume under direct supermarket control. Tesco, Sainsbury's, and Morrisons are internalizing primary distribution for temperature-sensitive produce, displacing traditional wholesaler intermediaries. Yorkshire-based frozen food distributors report contract compression as these retailers establish captive regional consolidation centers, with the pattern most advanced in fresh meat and dairy categories serving London and South East consumption basins.
United Kingdom Cold Chain Logistics Market Segmentation
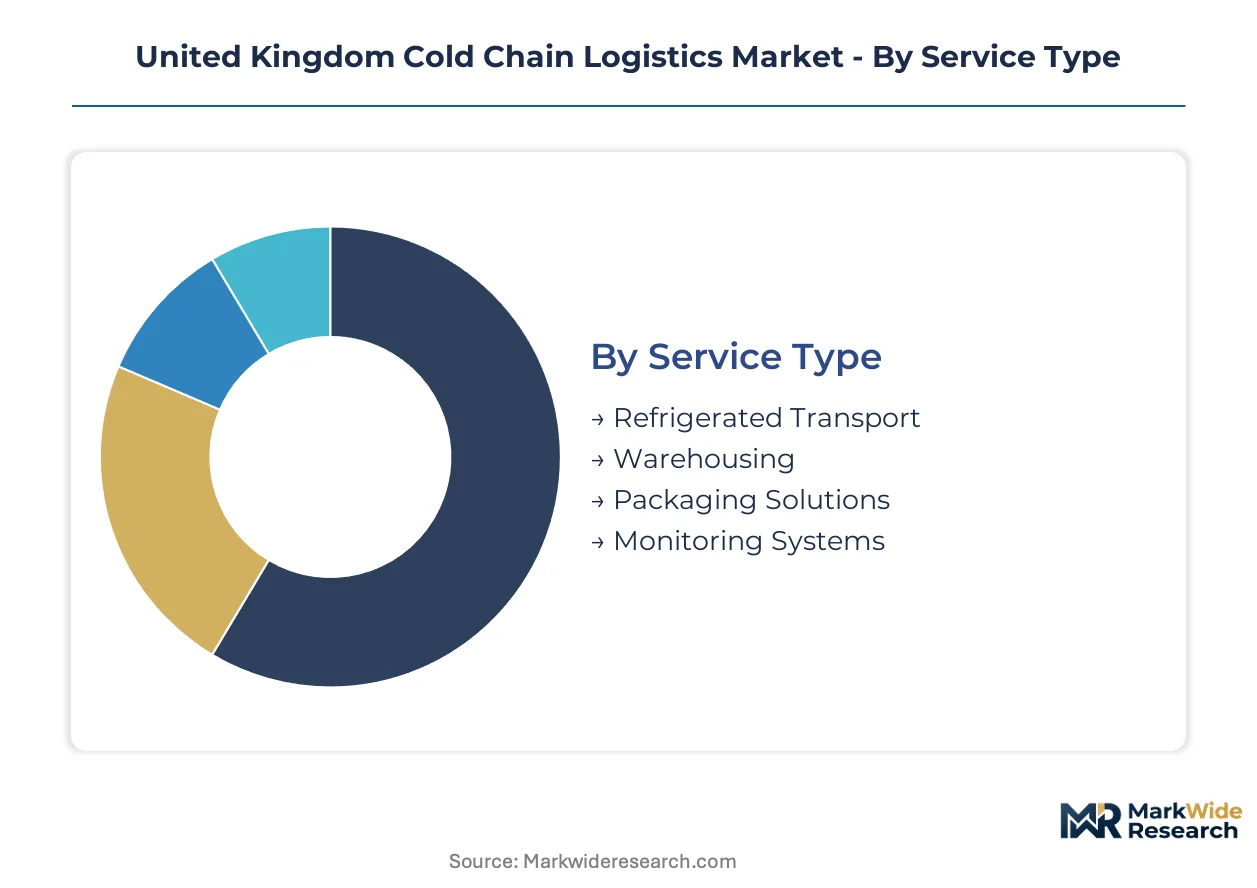
Cold chain logistics operators in the United Kingdom configure service portfolios around thermal risk profiles and compliance documentation intensity. Segment selection determines capital allocation between fleet assets, warehouse automation, and sensor infrastructure.
Service Type:
Equipment replacement cycles under the F-Gas Regulation are reshaping capital deployment across service categories, with ammonia conversion timelines favoring warehousing over transport.
- Refrigerated Transport:Diesel-powered and electric refrigerated vehicles maintain thermal corridors between minus 25 and plus 15 degrees Celsius across pharmaceutical and food lanes. Fleet operators in the English Midlands corridor absorb escalating refrigerant reclamation costs for aging HFC systems while awaiting electric chassis availability.
- Warehousing:Automated high-bay frozen storage and multi-temperature distribution centers capture margin from pharmaceutical GDP validation requirements. Yorkshire and Greater Manchester brownfield sites are converting to CO2 transcritical systems ahead of Environment Agency phasedown deadlines.
- Packaging Solutions:Insulated shippers and phase-change materials protect temperature-sensitive biologics during last-mile delivery to hospital pharmacies.
- Monitoring Systems:Cloud-connected telemetry platforms transmit minute-by-minute thermal data to MHRA-auditable databases for cell therapy distribution.
Volume placements concentrate in Refrigerated Transport; the faster expansion belongs to Warehousing.
Product Type:
Customer procurement patterns split segment demand between supermarket consolidation centers and pharmaceutical manufacturing campuses.
- Pharmaceuticals:Vaccines, biologics, and cell therapies demand validated cold storage under GDP standards with continuous temperature documentation. AstraZeneca and GSK distribution networks in England are expanding dedicated frozen and ultra-low temperature capacity.
- Dairy Products:Fresh milk, cheese, and yogurt require chilled distribution between two and eight degrees Celsius from processing plants to retail consolidation centers. English Midlands dairy processors are internalizing primary distribution lanes previously served by third-party operators.
- Fruits:Temperature-controlled ripening and ethylene management for bananas and avocados transiting through Portsmouth and Felixstowe ports.
- Vegetables:Leafy greens and brassicas from Lincolnshire and East Anglia farms move through regional distribution centers under Food Standards Agency temperature protocols.
Revenue concentration sits with Pharmaceuticals; Dairy Products are gaining share fastest through retail network consolidation.
Technology:
Margin extraction from compliance automation is driving technology adoption sequencing across operator tiers.
- IoT Solutions:Distributed sensor architectures transmit real-time temperature, humidity, and location data to centralized quality management platforms. Pharmaceutical third-party logistics providers are modularizing compliance documentation through cloud telemetry, compressing quality control headcount.
- Temperature Control Systems:Ammonia and CO2 refrigeration plants with variable-speed compression maintain precise thermal setpoints in frozen warehousing. West Midlands food manufacturers face 18-month order backlogs for natural refrigerant packaged systems.
- Blockchain Technology:Immutable ledger systems record custody transfers and temperature excursions across multi-party pharmaceutical supply chains.
- RFID Tracking:Passive and active radio-frequency tags enable pallet-level location and condition monitoring within warehouse management systems.
Deployment density is highest for Temperature Control Systems; IoT Solutions are climbing the fastest amid MHRA documentation mandates.
End User:
Direct network control strategies are fragmenting traditional wholesaler relationships across end-user categories.
- Retailers:Tesco, Sainsbury's, and Morrisons are establishing captive regional consolidation centers for temperature-sensitive produce, displacing Yorkshire-based frozen food distributors from primary lanes.
- Healthcare Providers:Hospital pharmacies and cell therapy infusion centers require validated last-mile delivery with continuous temperature documentation. NHS trusts are contracting directly with specialized pharmaceutical logistics operators.
- Food Manufacturers:West Midlands and East of England processing facilities are retrofitting ammonia refrigeration plants under F-Gas Regulation compliance timelines.
- Distributors:Traditional wholesale intermediaries are retreating to secondary consolidation and cross-dock functions as retailers internalize primary distribution.
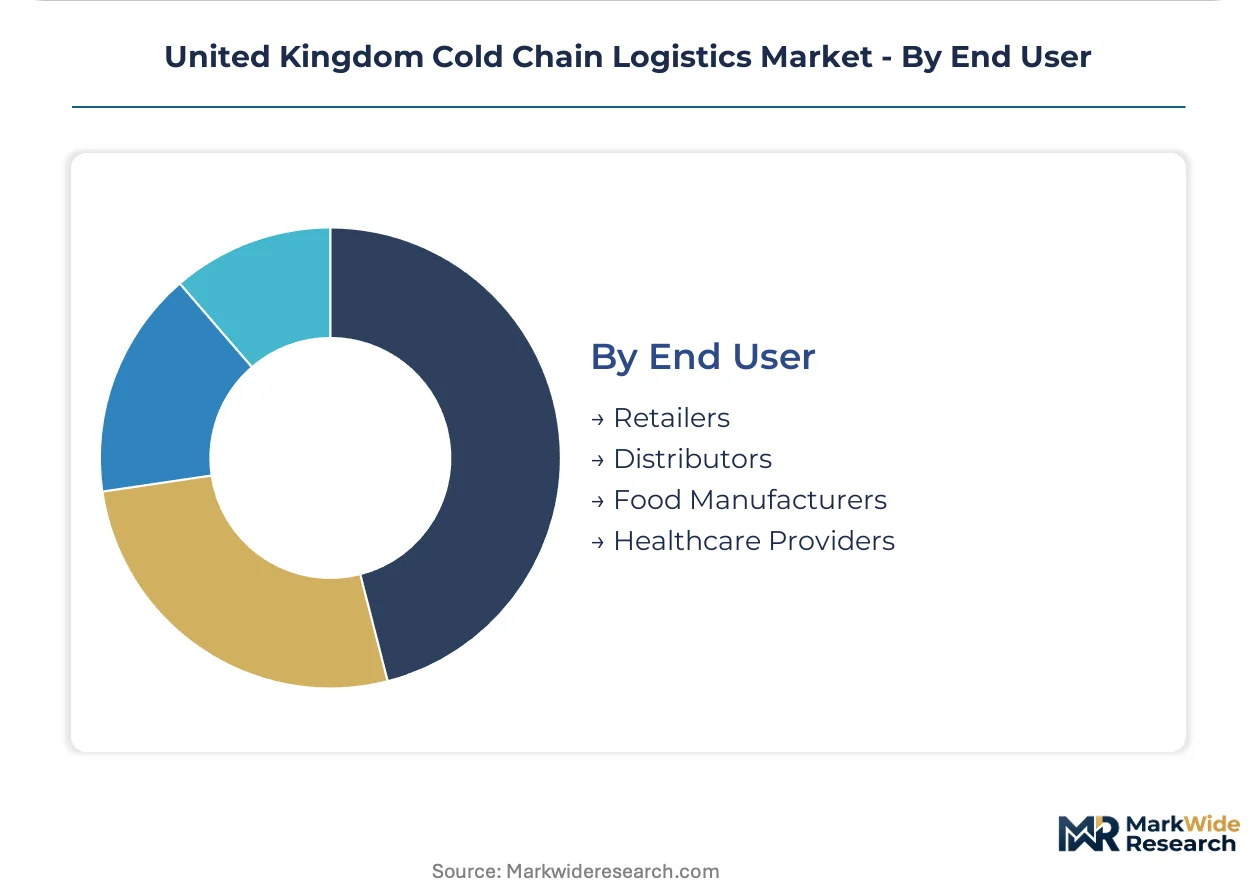
Contract value concentrates with Retailers; Healthcare Providers are expanding most quickly through biologics distribution requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
English Midlands logistics corridors concentrate temperature-controlled capacity within four-hour reach of ninety percent of UK population. Pharmaceutical manufacturing campuses and supermarket consolidation centers anchor demand across distinct regional clusters. Sub-national analysis reveals divergent infrastructure pressures and regulatory enforcement intensity.
English Midlands
Birmingham-Leicester-Derby distribution clusters host the densest frozen and chilled warehousing capacity outside Greater London. The Environment Agency enforces F-Gas phasedown schedules most intensively across West Midlands manufacturing facilities. Food processing plants in Wolverhampton and Stoke-on-Trent face eighteen-month order backlogs for ammonia refrigeration retrofits.
Greater London and Southeast
Port-centric cold storage at Felixstowe and Dover handles temperature-sensitive produce imports from continental Europe. The Medicines and Healthcare products Regulatory Agency maintains headquarters inspection capacity for pharmaceutical GDP compliance in this corridor. Heathrow pharmaceutical logistics zones are expanding ultra-low temperature capacity for cell therapy distribution.
Yorkshire and North England
Frozen food distribution networks serving retail consolidation centers concentrate around Bradford and Wakefield. Rural warehouse electrification faces distribution network operator delays for high-amperage grid connections. Reed Boardall anchors multi-temperature capacity across this corridor for consolidated supermarket procurement.
Scotland
Aberdeen and Peterhead landing ports lack integrated cold chain infrastructure for direct continental EU seafood routing. Marine Scotland regulations govern temperature control for fresh catch exports. Scottish seafood processors currently tranship through English cold storage, adding cost and transit time.
Wales and West England
Dairy processing clusters in Pembrokeshire and Gloucestershire require chilled distribution to retail networks. Natural Resources Wales implements parallel environmental permitting for refrigeration plant upgrades. Bristol port facilities are expanding multi-temperature capacity for Irish Sea trade routes.
United Kingdom Cold Chain Logistics Market Competitive Landscape
Established operators occupy the standard tier; emerging entrants pursue pharmaceutical specialization and automated warehousing. The market structures around three tiers: integrated global logistics networks, regional frozen food specialists, and pharmaceutical GDP-certified operators. Strategic archetypes include port-centric multi-temperature providers, retail-captive distribution networks, and biologics-focused cold storage specialists. Competitive moves concentrate on ammonia refrigeration retrofits under F-Gas mandates and automated high-bay warehouse deployment.
Among UK-based cold storage specialists, Reed Boardall and Chiltern Cold Storage Group exemplify regional frozen distribution archetypes anchored in Yorkshire and Home Counties corridors respectively. Lineage Logistics represents the global network tier with multi-temperature port positioning. These three occupy distinct competitive spaces: Reed Boardall serves consolidated retail procurement, Chiltern Cold Storage Group focuses on food manufacturing contract logistics, and Lineage Logistics anchors international trade lane connectivity.
| Leading Market Players |
|---|
| Reed Boardall |
| Chiltern Cold Storage Group |
| Lineage Logistics |
| DHL Supply Chain |
| Americold Logistics |
| NewCold |
| Gist Ltd |
| Turners (Soham) Ltd |
| Culina Group |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up cold storage specialists anchor UK temperature-controlled logistics, compressing pricing discipline through scale economies while concentrating procurement leverage across Yorkshire and Midlands warehouse networks. Their consolidated ownership structures synchronize fleet renewal timelines with F-Gas Regulation compliance windows, tightening margin tolerance for independent operators lacking captive capital access.
Pricing Analysis
High-volume refrigerated transport competes on lane density while pharmaceutical warehousing extracts premium margins through GDP certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates MHRA-validated biologics storage from conventional frozen food handling. Cost compression in standard-tier dairy distribution is intensifying because supermarket chains are internalizing primary lanes. Small food manufacturers show highest price sensitivity; cell therapy manufacturers accept premium rates for continuous temperature documentation.
Supply Chain Analysis
Reverse logistics for temperature-controlled pharmaceutical returns and refrigerant reclamation flows create specialized handling requirements distinct from forward distribution. Natural refrigerant compressor manufacturing draws from German and Danish industrial bases, exposing UK operators to euro-denominated procurement volatility. Critical inputs include ammonia refrigeration plants, electric chassis platforms, and F-Gas Category I certified engineering labor. Single-source vulnerability concentrates in natural refrigerant component supply. Distribution runs through English Midlands consolidation corridors serving retail and pharmaceutical end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where F-Gas Regulation compliance costs are forcing sub-scale operators toward exit or acquisition by better-capitalized competitors.
For Market Incumbents: Cement ammonia refrigeration retrofit leadership across West Midlands manufacturing clusters before Environment Agency enforcement windows tighten. Acquire distressed cold storage assets in Greater Manchester brownfield zones to lock in automated high-bay capacity. Vertical integration into electric fleet procurement hedges against driver qualification scarcity and diesel chassis phaseout risks. For New Entrants and Emerging Players: IoT-enabled temperature telemetry platforms offer a technology-first wedge into pharmaceutical last-mile distribution currently served by legacy quality control departments. Target Scottish seafood export corridors where Aberdeen and Peterhead landing ports lack direct continental EU cold chain infrastructure. Pursue NHS trust direct contracting for cell therapy validated delivery as established wholesalers retreat from biologics complexity. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional frozen food specialists with Yorkshire distribution network density and pending F-Gas retrofit liabilities. Five-to-ten-year viability hinges on ammonia conversion completion and supermarket consolidation center contract retention. Monitor Environment Agency enforcement intensity and electric grid connection approval timelines for UK warehouse electrification as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Refrigeration Retrofit | West Midlands food manufacturers face eighteen-month order backlogs for Environment Agency compliance. |
| Automated High-Bay Deployment | Crane-based storage systems unlock brownfield redevelopment in Greater Manchester logistics zones. |
| Pharmaceutical GDP Certification | MHRA validation requirements expand margin extraction from biologics and cell therapy distribution. |
| Electric Fleet Transition | Driver and Vehicle Standards Agency CPC bottlenecks favor early movers securing qualified refrigerated vehicle operators. |
| Scottish Seafood Corridor Development | Aberdeen and Peterhead port cold chain infrastructure bypasses English transhipment for continental EU routing. |
Research Methodology
Trade association filings, Environment Agency enforcement records, and NHS procurement databases formed the secondary backbone for UK cold chain logistics sizing. Primary interviews with fleet operations directors, pharmaceutical quality assurance managers, and refrigeration engineering contractors combined with customs data and refrigerated warehouse capacity registries. Bottom-up lane volume analysis and top-down sector expenditure estimates were triangulated to anchor market segmentation.
Historical trendline analysis of refrigerated transport fleet registrations and cold storage construction permits informed projection modeling across the analysis window. Segmentation dimensions included service type, product thermal risk profile, refrigeration technology chemistry, and end-user procurement structure. CAGRs were derived from equipment replacement cycle compression under F-Gas Regulation timelines and pharmaceutical biologics distribution expansion rates.
Several conditions sit outside the modeled scope, including potential carbon border adjustment mechanism implementation details and electric grid distribution network operator connection approval delays. Forecasts reflect assumptions around ammonia refrigeration contractor capacity and natural refrigerant compressor manufacturing lead times. Practitioners should monitor Environment Agency enforcement intensity and supermarket internalization pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Pharmaceutical Logistics Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market