
 United States FTL Freight Brokerage Market | 2026-2036
United States FTL Freight Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
United States FTL Freight Brokerage Market Analytics
Digital freight matching platforms are recalibrating how shippers connect with carriers, compressing traditional broker margins while expanding market liquidity. C.H. Robinson Worldwide leverages its proprietary Navisphere platform to sustain North America's largest freight brokerage network. J.B. Hunt Transport Services anchors its position through integrated 360Box container assets, while XPO, Inc. competes via its digital brokerage marketplace focused on mid-market shippers.
United States FTL freight brokerage encompasses intermediaries that contract entire truck capacity for single-origin, single-destination shipments, typically moving loads exceeding ten thousand pounds across distances of two hundred fifty to three thousand miles. These brokers coordinate carrier procurement, rate negotiation, and shipment execution without taking physical possession of cargo, functioning as asset-light orchestrators of domestic surface transportation. Standard truckload services dominate transaction volume, though temperature-controlled freight commands premium margins due to specialized equipment scarcity and food safety compliance burdens. Load matching platforms represent the fastest-expanding technology segment, displacing legacy phone-and-email dispatch workflows among small and mid-sized brokerages.
The Federal Motor Carrier Safety Administration enforces hours-of-service regulations and broker surety bond requirements that determine market entry thresholds, while the Surface Transportation Board retains oversight of rate reasonableness disputes and carrier licensing. State-level weight limits and emissions standards, particularly California's Advanced Clean Trucks regulation, fragment operational compliance across interstate lanes. Stakeholders must monitor how autonomous truck pilot programs and federal infrastructure spending reshape lane economics and broker value propositions.
Market Dynamics
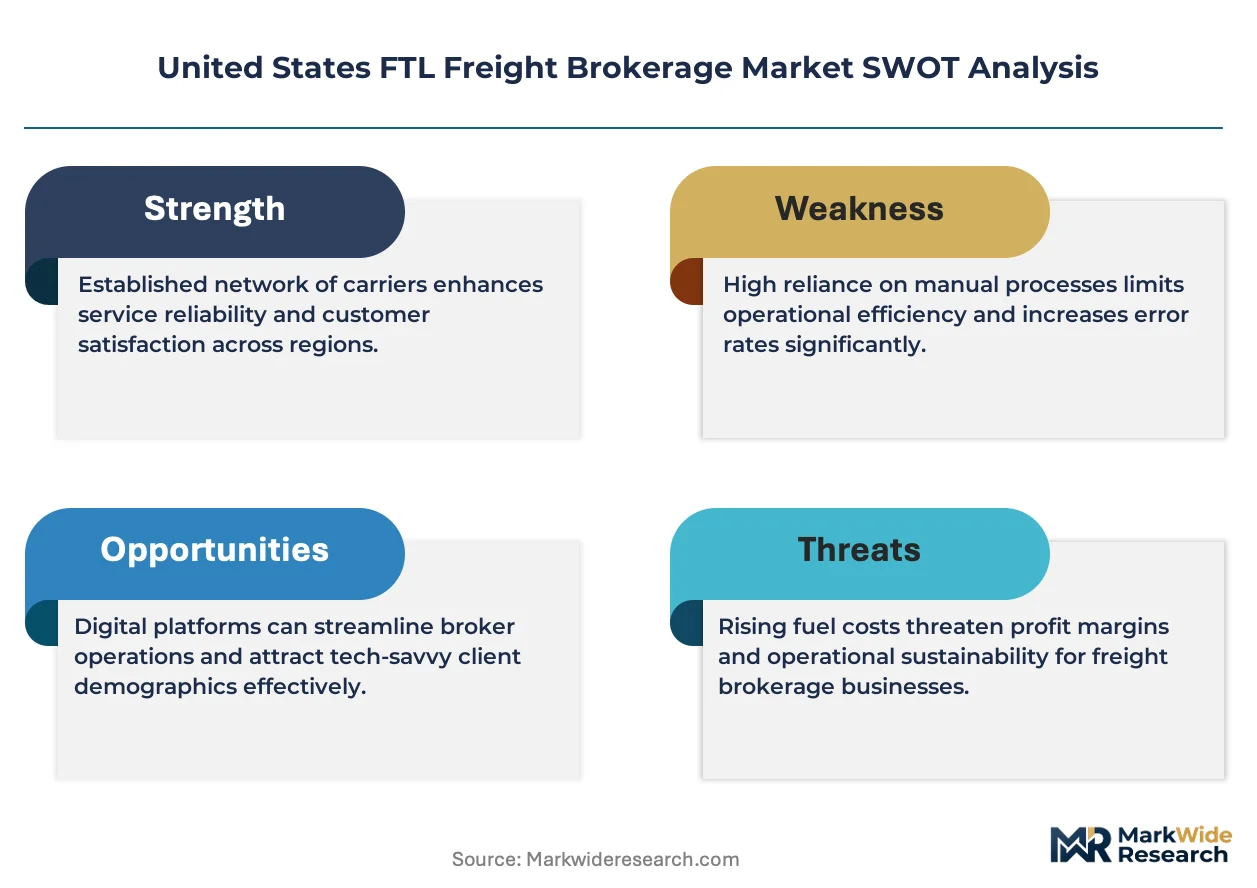
Digital freight matching platforms are compressing traditional broker margins while expanding market liquidity, forcing intermediaries to restructure around technology-enabled service differentiation rather than pure rate arbitrage.
Growth Catalysts
- E-commerce fulfillment networks:Major retailers are expanding dedicated full truckload capacity to support next-day delivery promises, creating sustained demand for broker-coordinated capacity.
- FMCSA electronic logging device mandate:Hours-of-service compliance requirements have tightened carrier availability, elevating the value of brokers with real-time capacity visibility.
- Texas freight corridor concentration:The Dallas-Fort Worth to Houston lane generates disproportionate transaction volume, rewarding brokers with dense carrier networks in this specific geography.
Market Restraints
- Carrier supply concentration:Small trucking fleets dominate capacity provision, creating fragmentation that complicates broker procurement scale and reliability.
- Diesel price volatility:Fuel represents thirty to forty percent of carrier operating costs, injecting unpredictability into rate negotiations and margin stability.
- California emissions standards:The Advanced Clean Trucks regulation fragments interstate operational compliance, raising equipment costs for carriers serving cross-border lanes.
Strategic Opportunities
- Autonomous truck pilot programs:Brokerages that secure partnerships with self-driving truck developers can capture first-mover positioning in lane-specific automation corridors.
- Temperature-controlled freight expansion:Food safety compliance burdens and specialized equipment scarcity create premium margin opportunities for brokers with refrigerated carrier networks.
- Mid-market shipper digitization:Small and mid-sized enterprises remain underserved by legacy phone-and-email dispatch workflows, creating white space for platform-enabled intermediaries.
Industry Challenges
- Carrier relationship management:Driver retention crises and fleet bankruptcies force continuous broker investment in carrier onboarding and credit monitoring systems.
- Legacy system integration:Transportation management system interoperability gaps complicate data exchange between shipper ERP platforms and broker dispatch software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States FTL Freight Brokerage Market |
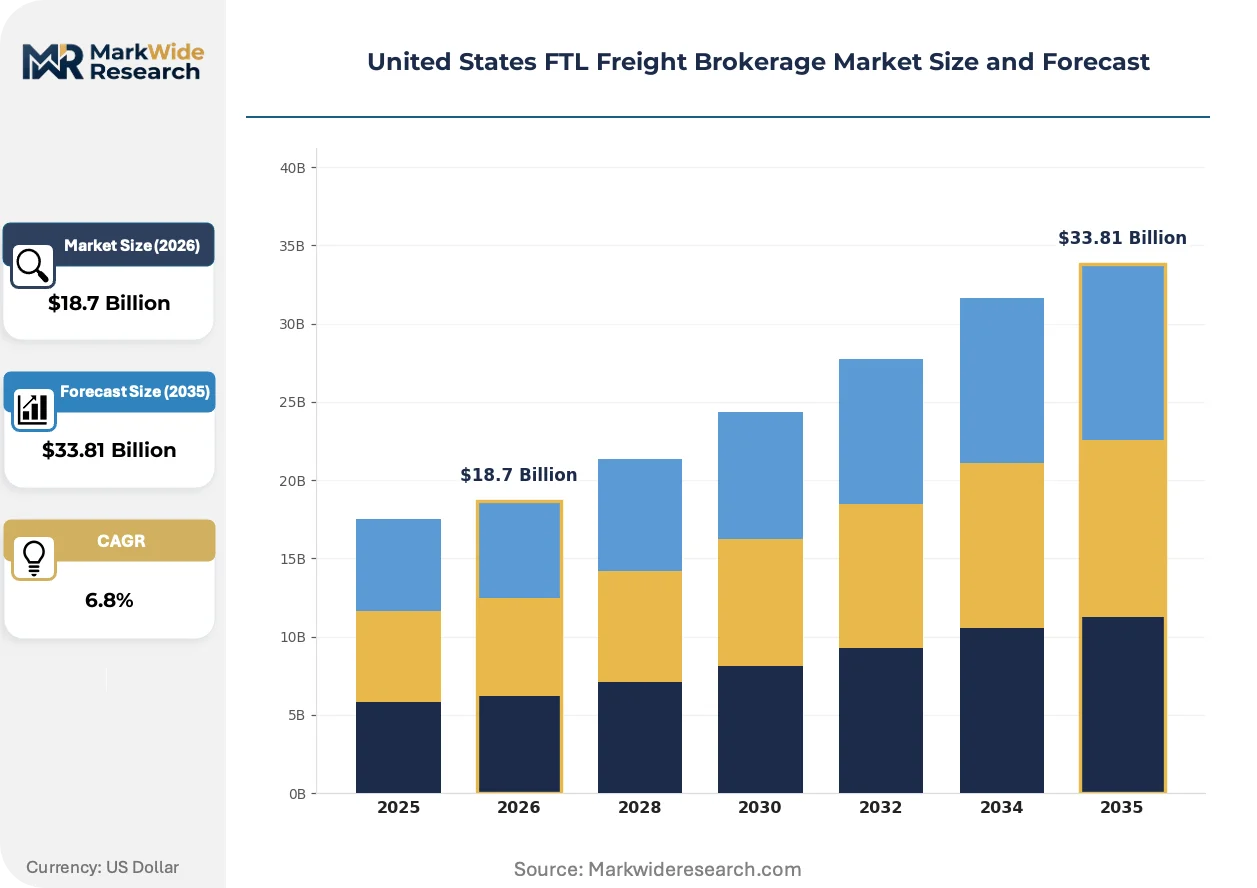
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Truckload, Expedited Freight, High-Value Cargo, Temperature-Controlled Freight Client Type: Manufacturers, Retailers, 3PL Providers, Importers Technology: Transportation Management Systems, Freight Tracking Solutions, Load Matching Platforms, Mobile Applications Delivery Model: Spot Rates, Contract Rates, Hybrid Pricing, Transactional Fees |
| Companies Covered | WWEX Group, Schneider National, C.H. Robinson Worldwide, XPO, Inc., Knight-Swift Transportation, J.B. Hunt Transport Services, RXO, Echo Global Logistics, Total Quality Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States FTL Freight Brokerage Market Evolving Landscape
Technology-enabled visibility and automation are restructuring how freight intermediaries create value, shifting competitive advantage from personal relationships toward algorithmic matching and predictive analytics capabilities.
Real-time visibility platforms are electrifying broker operations by integrating GPS, ELD, and weather data into unified shipment tracking dashboards. Large shippers now mandate this transparency as a contractual requirement. The technology is compressing the information advantage that historically protected incumbent brokers with dense personal networks.
The FMCSA broker surety bond requirement and hours-of-service enforcement continue tightening market entry thresholds and operational constraints. Carriers face escalating compliance costs that reduce available capacity during peak periods. Temperature-controlled freight segments bear disproportionate burden from food safety audits and equipment certification timelines.
Shippers are consolidating vendor relationships toward integrated logistics providers capable of spanning truckload, intermodal, and final-mile execution. Procurement teams now evaluate brokers on technology platform maturity rather than rate competitiveness alone. This pattern concentrates most visibly among retail and consumer packaged goods verticals with complex omnichannel distribution requirements.
United States FTL Freight Brokerage Market Segmentation
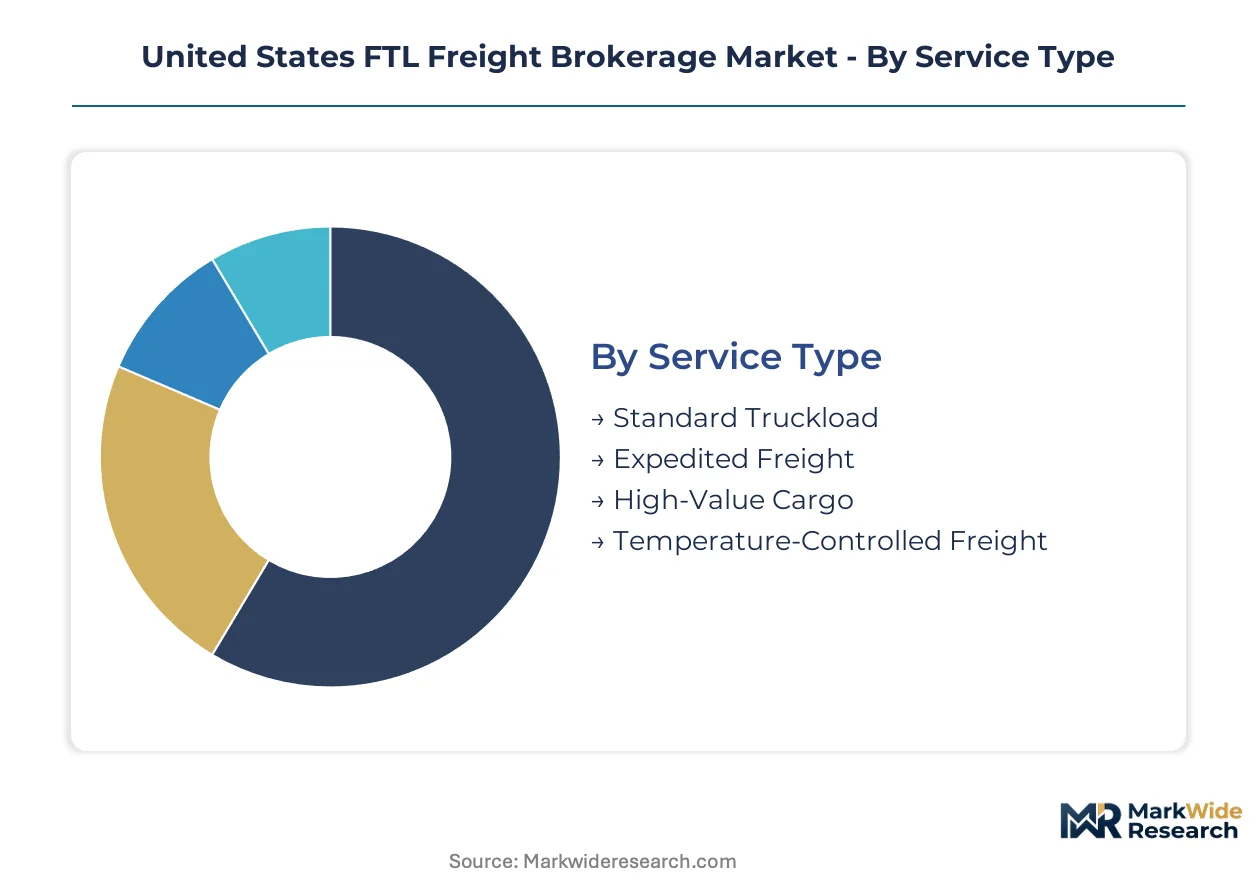
FTL freight brokerage segmentation reveals how intermediaries structure service portfolios around cargo characteristics, client sophistication, and technology deployment. Each dimension carries distinct margin profiles and carrier network requirements that determine competitive positioning.
Service Type:
Standalone brokerage services operate independently from integrated logistics suites, while embedded offerings bundle with warehousing or intermodal coordination.
- Standard Truckload:Dry van capacity coordination for non-specialized cargo constitutes the transaction volume foundation. Demand clusters with retail replenishment networks across the Dallas-Fort Worth to Houston corridor, where broker density enables rapid carrier matching.
- Temperature-Controlled Freight:Refrigerated and frozen cargo intermediation requires certified carrier relationships and food safety audit compliance. Pharmaceutical cold chain expansion and perishable e-commerce fulfillment are driving specialized equipment scarcity premiums.
- Expedited Freight:Time-definite truckload services leverage team-driver configurations and dedicated lane commitments for urgent manufacturing supply chains.
- High-Value Cargo:Specialized handling protocols and enhanced insurance requirements apply to electronics, pharmaceuticals, and luxury goods movements.
Volume placements concentrate in Standard Truckload; the faster expansion belongs to Temperature-Controlled Freight.
Client Type:
Cost tier stratification separates enterprise procurement teams with transportation management system integration from smaller shippers relying on phone-based dispatch.
- Retailers:Omnichannel distribution networks generate continuous full truckload demand for store replenishment and direct-to-consumer fulfillment. Amazon, Walmart, and Target vendor compliance programs mandate real-time visibility integration.
- 3PL Providers:Third-party logistics firms subcontract capacity through broker networks to extend geographic coverage without asset ownership. Their procurement scale commands preferential rate structures and dedicated account management.
- Manufacturers:Industrial production schedules create predictable lane density that supports contract rate negotiations and backhaul optimization.
- Importers:Port drayage coordination and inland distribution from Los Angeles-Long Beach and Savannah gateway markets require specialized broker expertise.
Revenue concentration sits with Retailers; 3PL Providers are gaining share fastest through vendor consolidation mandates.
Technology:
Maturity differentiation separates legacy phone-and-email workflows from API-connected automation platforms.
- Load Matching Platforms:Algorithmic carrier-shipper pairing compresses procurement cycles from hours to minutes. Digital freight brokers like Convoy and Uber Freight built market position through automated tender acceptance and dynamic pricing engines.
- Transportation Management Systems:Enterprise software integration enables shipment planning, execution, and settlement within unified workflows. Large shippers now require TMS interoperability as a contractual precondition.
- Freight Tracking Solutions:GPS-ELD fused visibility dashboards provide predictive arrival windows and exception management capabilities.
- Mobile Applications:Driver-facing apps streamline document upload, detention reporting, and payment acceleration for small fleet operators.
Deployment density peaks with Transportation Management Systems; Load Matching Platforms show the steepest adoption trajectory.
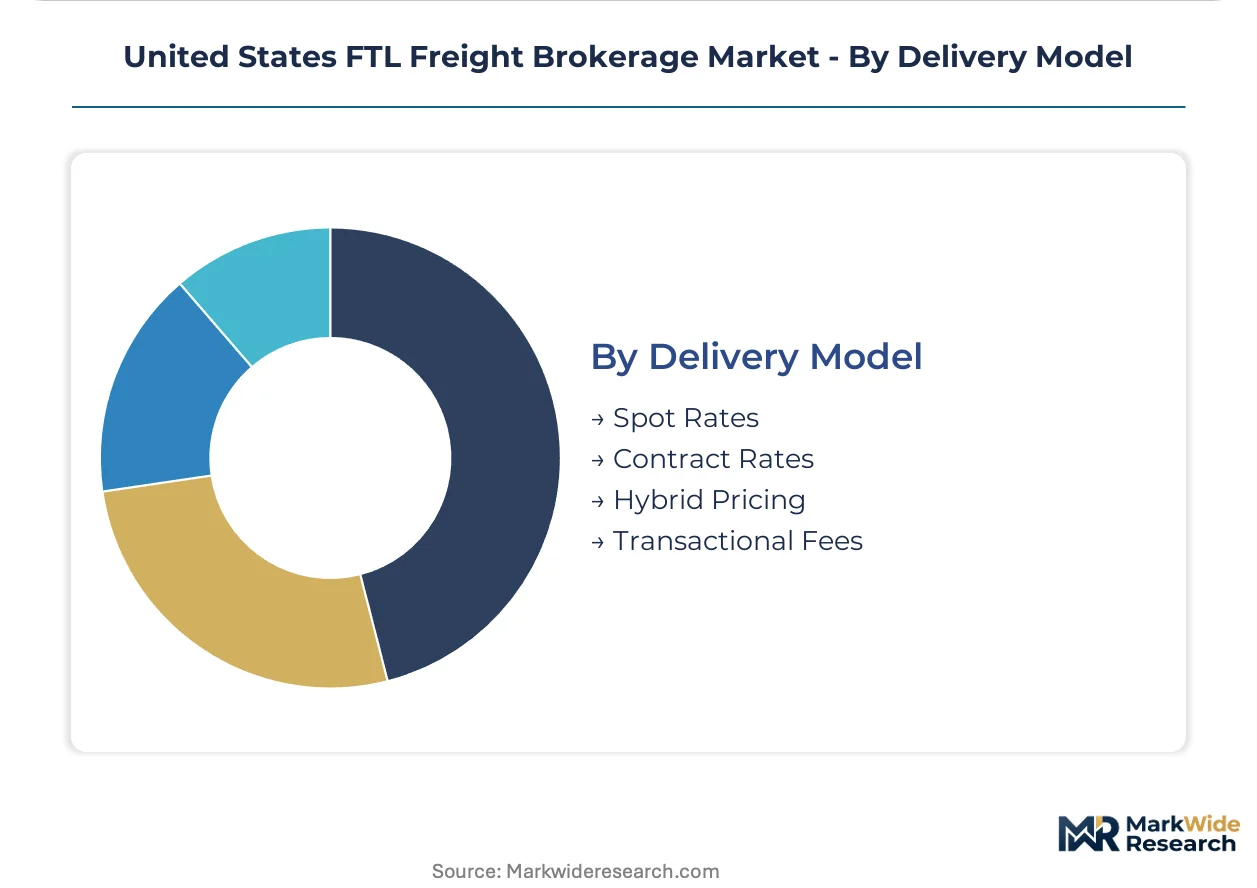
Delivery Model:
Margin structure varies between transactional spot exposure and contract rate stability commitments.
- Contract Rates:Annual or multi-year committed capacity agreements provide price certainty for shippers and revenue predictability for brokers. These arrangements dominate manufacturing and retail replenishment lanes with steady volume profiles.
- Spot Rates:Market-priced capacity procurement responds to surge demand, equipment imbalances, and seasonal peaks. Broker margins expand during tight capacity periods but compress abruptly when truck availability loosens.
- Hybrid Pricing:Blended contract-spot structures allocate baseline volume to committed rates while flexing overflow to market pricing.
- Transactional Fees:Per-shipment brokerage commissions apply to irregular shippers without volume commitments or TMS integration.
Contract Rates anchor revenue stability; Spot Rates demonstrate the most volatile expansion pattern tied to freight cycle amplitude.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Texas freight corridor linking Dallas-Fort Worth to Houston, generating disproportionate transaction volume for full truckload intermediaries. E-commerce fulfillment networks are expanding dedicated capacity to support next-day delivery promises. The Federal Motor Carrier Safety Administration's electronic logging device mandate continues reshaping carrier compliance requirements across state boundaries.
Texas
The Dallas-Fort Worth to Houston lane anchors domestic truckload density, with major retailers operating dedicated fulfillment networks between these metros. The Texas Department of Transportation maintains weight limit enforcement and infrastructure investment programs that affect lane economics. The Dallas-Fort Worth metroplex hosts dense broker-carrier matching activity, while Houston's port complex drives inland distribution demand.
California
Los Angeles-Long Beach port drayage and inland distribution create specialized brokerage requirements for import-heavy supply chains. The California Air Resources Board enforces Advanced Clean Trucks regulations that fragment interstate operational compliance and raise equipment costs for cross-border carriers. The Inland Empire warehousing cluster generates continuous full truckload demand for retail replenishment and e-commerce fulfillment.
Illinois
Chicago's intermodal hub status and manufacturing base produce predictable lane density supporting contract rate negotiations. The Illinois Commerce Commission oversees motor carrier regulations and broker licensing requirements that determine market entry thresholds. The Joliet-Rockford corridor concentrates distribution center development, driving broker-coordinated capacity for automotive and consumer goods supply chains.
Georgia
Savannah's rapidly expanding port gateway generates specialized broker expertise for container drayage and inland distribution to Southeast manufacturing. The Georgia Department of Transportation coordinates freight infrastructure investments affecting truck routing efficiency. The Atlanta metroplex serves as a distribution hub for retail networks, with brokers maintaining dense carrier relationships for regional and long-haul movements.
Pennsylvania
Philadelphia and Pittsburgh manufacturing schedules create backhaul optimization opportunities for brokers with established carrier networks. The Pennsylvania Department of Transportation enforces weight limits and bridge restrictions that affect routing decisions. The Lehigh Valley warehousing cluster drives continuous truckload demand for East Coast retail replenishment and e-commerce fulfillment networks.
United States FTL Freight Brokerage Market Competitive Landscape
Branded specialists and asset-light brokers split share differently across segments, with integrated logistics providers capturing enterprise accounts while digital platforms penetrate mid-market shippers. The market exhibits tiered consolidation, where a handful of national networks coordinate substantial transaction volume alongside thousands of regional intermediaries. Three archetypes dominate: technology-enabled platforms with algorithmic matching, integrated carriers with captive brokerage arms, and specialized intermediaries focused on temperature-controlled or expedited verticals. Competitive dynamics center on transportation management system interoperability partnerships and carrier network density investments in high-volume corridors.
Within the technology-enabled tier, C.H. Robinson Worldwide and XPO, Inc. exemplify platform-centric positioning, while J.B. Hunt Transport Services represents integrated carrier-broker hybrids. These entities anchor distinct strategic approaches to capacity coordination, with some emphasizing proprietary digital marketplaces and others leveraging container asset control to secure lane commitments. Each occupies a position shaped by technology deployment depth and geographic carrier network concentration rather than rate arbitrage alone.
| Leading Market Players |
|---|
| WWEX Group |
| Schneider National |
| C.H. Robinson Worldwide |
| XPO, Inc. |
| Knight-Swift Transportation |
| J.B. Hunt Transport Services |
| RXO |
| Echo Global Logistics |
| Total Quality Logistics |
| Others |
Value Network & Pricing Analysis
Horizontal consolidation among digital freight platforms anchors both supply positioning and pricing power in the United States FTL freight brokerage market. Asset-light intermediaries that control carrier matching algorithms without owning tractors capture margin premiums through real-time capacity visibility, while traditional phone-based brokers face compression from automated tender acceptance engines.
Pricing Analysis
Volume concentrates in contract rate arrangements while margin expansion belongs to spot rate exposure during capacity tightening cycles. Three-tier pricing structure across premium refrigerated, standard dry van, and economy backhaul tiers reflects equipment scarcity and lane density differentials. Cost compression in standard truckload is intensifying because digital freight matching platforms eliminate information asymmetries that historically protected incumbent broker margins. Small and mid-sized shippers without transportation management system integration demonstrate highest price sensitivity, whereas enterprise retailers with omnichannel compliance mandates accept premium pricing for real-time visibility integration.
Supply Chain Analysis
Direct-to-shipper digital channels handle hyperscale enterprise demand while phone-based dispatch relationships serve fragmented small fleet procurement. Carrier capacity draws from the United States, with cross-border Mexican trucking providing supplemental dry van availability during peak agricultural seasons. Diesel fuel, driver labor, and equipment financing constitute the primary cost inputs. Single-source vulnerability concentrates in specialized refrigerated equipment pools serving California's food safety audit requirements. Distribution runs through broker-carrier matching platforms that displace legacy dispatch workflows with algorithmic tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States FTL freight brokerage market sits in a technology-transition phase where load matching platforms displace phone-and-email dispatch workflows. Legacy relationship-based intermediation gives way to algorithmic carrier-shipper pairing.
For Market Incumbents: Hedge against margin compression by deepening proprietary transportation management system interoperability partnerships with enterprise shippers. Secure captive capacity through dedicated carrier development programs in the Dallas-Fort Worth to Houston corridor before autonomous truck pilot programs reshape lane economics.
For New Entrants and Emerging Players: Begin with mid-market shippers lacking TMS integration, where white space persists for platform-enabled intermediaries. Target temperature-controlled freight verticals where food safety compliance burdens and specialized equipment scarcity sustain premium margin structures unavailable in commoditized dry van segments.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated logistics providers seeking technology platform capabilities. Long-term viability favors brokerages with dense carrier networks in high-volume corridors and API-connected automation infrastructure. Monitor FMCSA regulatory shifts on autonomous vehicle deployment as the critical inflection signal for lane-specific automation corridor valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Load Matching Platform Deployment | Algorithmic tender acceptance compresses procurement cycles from hours to minutes for mid-market shippers. |
| Refrigerated Carrier Network Expansion | Food safety audit compliance and equipment scarcity create defendable margin premiums in perishable logistics. |
| TMS Interoperability Partnership | Enterprise shippers mandate real-time visibility integration as contractual precondition for vendor selection. |
| Texas Corridor Density Investment | Dallas-Fort Worth to Houston lane concentration generates disproportionate transaction volume for matching efficiency. |
| Autonomous Truck Pilot Participation | First-mover positioning in lane-specific automation corridors secures future capacity coordination advantages. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this United States FTL freight brokerage market analysis. Primary interviews with freight brokerage operations executives, carrier fleet managers, shipper procurement directors, and transportation management system vendors combined with FMCSA enforcement databases, Surface Transportation Board rate filings, and American Trucking Associations operational statistics. Bottom-up transaction volume estimates and top-down macroeconomic freight demand indicators underwent cross-validation.
Data-stream reconciliation across shipper expenditure surveys, carrier operating cost reports, and broker revenue disclosures shaped the analytical framework. Segmentation dimensions modeled include service type, client vertical, technology deployment maturity, and delivery pricing structure across the analysis window. CAGRs derived from trend extrapolation of digital freight platform adoption curves, ELD mandate compliance cost trajectories, and e-commerce fulfillment network expansion patterns.
Underlying measurement precision varies by segment; standard truckload transaction volume carries tighter precision than temperature-controlled freight due to equipment certification reporting gaps. Forecasts reflect assumptions on autonomous vehicle regulatory timelines, diesel price volatility bands, and carrier bankruptcy frequencies. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Asia Pacific Event Logistics Market