
 Qatar Courier, Express, and Parcel (CEP) Market | 2026-2036
Qatar Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Courier, Express, and Parcel (CEP) Market Insights
E-commerce merchants are collapsing the distinction between domestic and cross-border fulfillment expectations, forcing CEP providers to unify inventory positioning and last-mile density. Qatar Airways Cargo leverages its belly-hold and freighter network to anchor premium express lanes into Europe and Asia. DHL Express sustains dedicated customs brokerage capacity at Hamad International Airport, reducing dwell times for time-sensitive shipments. Aramex competes through ground transportation integration with Saudi and UAE corridors, extending its Gulf reach from Doha.
Courier, express, and parcel services encompass the collection, sorting, transport, and delivery of documents and packages with defined service-level commitments, typically measured by transit-time guarantees, tracking granularity, and proof-of-delivery protocols. These services function as the circulatory infrastructure for trade, enabling just-inventory replenishment, direct-to-consumer fulfillment, and cross-border commerce. Same-day delivery and next-day delivery command premium positioning among customer type segments, with B2C and e-commerce buyers driving volume expansion while B2B accounts retain higher per-shipment value. Last-mile delivery absorbs disproportionate cost concentration across delivery method categories, creating margin pressure that ground transportation providers address through route optimization and localized micro-fulfillment.
Qatar's communications regulator and customs authority enforce data localization requirements for shipment tracking systems, while the Ministry of Transport oversees commercial licensing for logistics operators. These frameworks elevate compliance costs for foreign entrants but fortify domestic incumbents with established regulatory relationships. Stakeholders must weigh infrastructure partnerships against captive fleet investments as parcel volumes scale toward air and ground capacity thresholds.
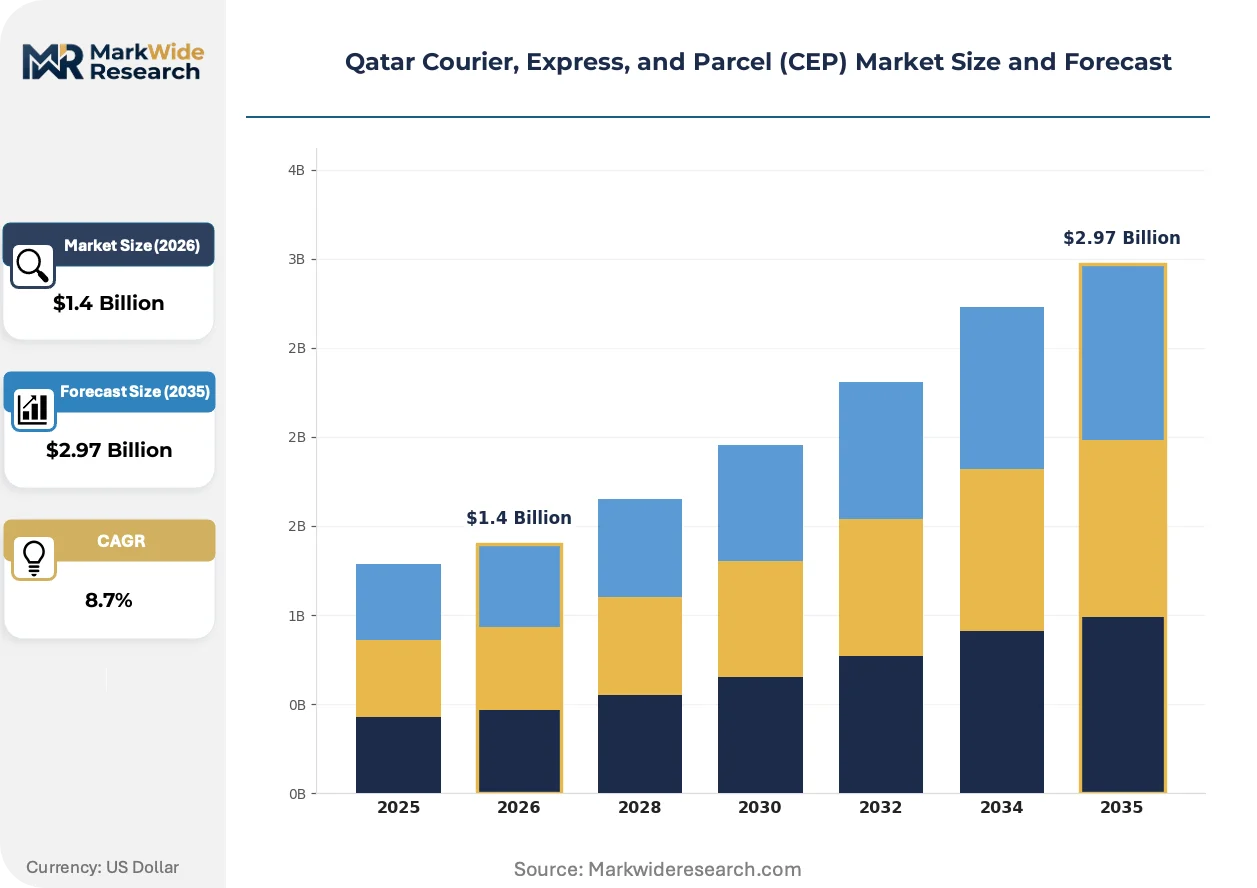
Market Dynamics
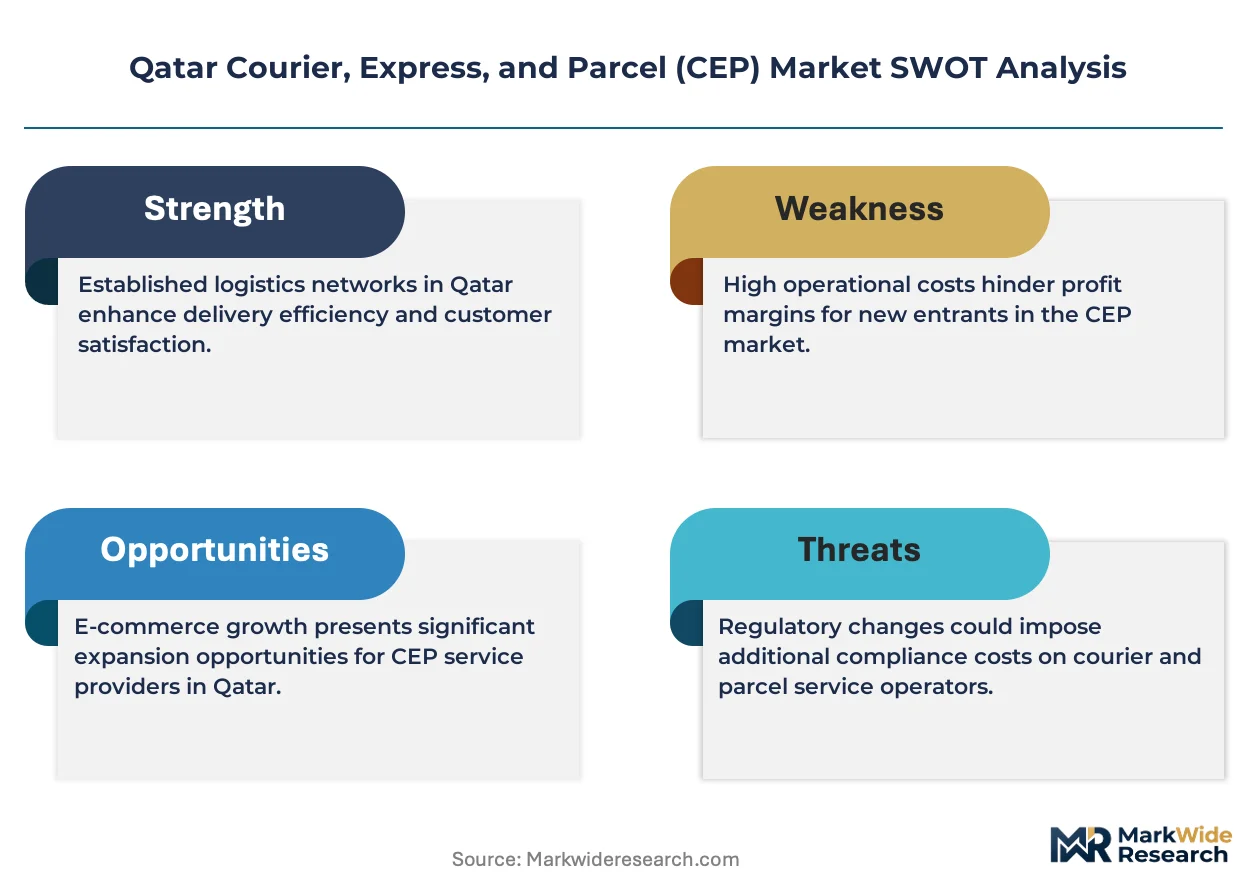
Scheduled and same-day delivery windows from e-commerce merchants are compressing transit-time expectations, forcing CEP providers to densify last-mile networks around Doha while integrating cross-border customs brokerage into unified fulfillment flows.
Growth Catalysts
- Customs Modernization:Qatar's single-window trade platforms streamline cross-border parcel clearance, reducing dwell times at Hamad Port and accelerating B2C fulfillment velocity.
- E-commerce Density:B2C merchants cluster fulfillment infrastructure near Hamad International Airport, creating route-optimization economies for express lane operators.
- Scheduled Delivery Windows:Time-definite service commitments pull inventory positioning closer to end consumers, expanding demand for localized micro-fulfillment nodes in Doha's industrial zones.
Market Restraints
- Data Localization Mandates:Qatar's communications regulator enforces domestic hosting requirements for shipment tracking systems, elevating compliance costs for foreign platform entrants.
- Last-Mile Cost Concentration:Ground transportation absorbs disproportionate margin pressure as delivery density thins beyond Doha's urban core toward surrounding emirates.
- Air-Ground Capacity Thresholds:Belly-hold and freighter network constraints at Hamad International Airport limit peak-season express volume expansion without dedicated fleet investment.
Strategic Opportunities
- Saudi Corridor Integration:Ground transportation linkages through the Salwa border crossing enable CEP providers to extend Gulf reach from Doha into the Eastern Province.
- Micro-Fulfillment Localization:Industrial zone clustering near Hamad Port supports captive warehousing strategies for cross-border inventory positioning.
- Premium Express Lanes:Dedicated customs brokerage capacity at Hamad International Airport creates service differentiation for time-sensitive B2B document and parcel flows.
Industry Challenges
- Regulatory Licensing Complexity:The Ministry of Transport's commercial licensing frameworks for logistics operators require established local relationships, slowing foreign market entry timelines.
- Route Optimization Talent Scarcity:Last-mile density algorithms and dynamic dispatch systems demand specialized data science capabilities that concentrate among incumbent technology teams.
- Legacy System Integration:Unified inventory positioning requires API connectivity between merchant platforms, customs brokers, and carrier tracking systems, creating implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Courier, Express, and Parcel (CEP) Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Standard Delivery Delivery Method: Air Freight, Ground Transportation, Rail Services, Last-Mile Delivery Customer Type: B2B, B2C, E-Commerce, International Shipping Package Size: Small Parcels, Medium Parcels, Large Parcels, Oversized Packages |
| Companies Covered | FedEx, QExpress, Qatar Post, Snoonu, Qatar Airways Cargo, Aramex, UPS, Gulf Warehousing Company, DHL Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital freight matching and predictive analytics are reshaping how CEP providers allocate capacity across scheduled, same-day, and next-day service tiers, compressing the gap between demand signals and fleet deployment.
Dynamic route optimization algorithms is bifurcating carrier competitive positioning. E-commerce merchants with high shipment frequency adopt real-time dispatch systems within eighteen-month procurement cycles. This technology is bifurcating market share between asset-light platform operators and legacy fleet owners unable to retrofit legacy dispatch infrastructure.
Qatar's customs authority mandates data localization for shipment tracking systems under communications regulator oversight. Industrial consequence includes elevated compliance infrastructure investment for foreign entrants. B2C express segments respond by partnering with domestic license holders to satisfy Ministry of Transport commercial licensing requirements.
B2C buyers now collapse domestic and cross-border fulfillment expectations into unified service-level agreements. Direct-to-consumer channels displace traditional freight forwarder intermediation for parcel flows under thirty kilograms. This behavioral shift concentrates most visibly among Doha-based e-commerce merchants sourcing inventory through UAE and Saudi distribution hubs.
Qatar Courier, Express, and Parcel (CEP) Market Segmentation
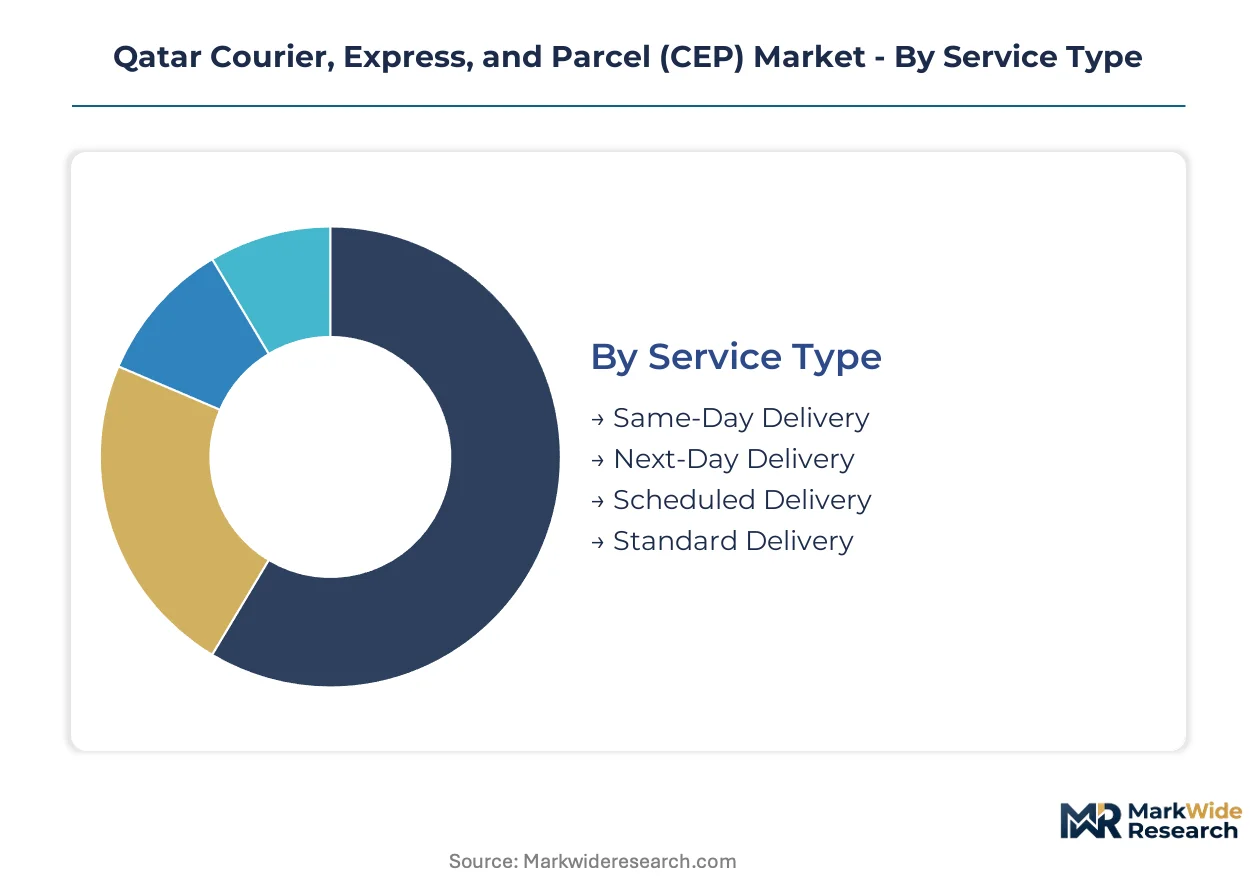
CEP providers in Qatar configure service portfolios around transit-time guarantees and customs integration depth. Segment boundaries blur as e-commerce merchants demand unified domestic and cross-border fulfillment flows. Doha's industrial clustering near Hamad International Airport and Hamad Port concentrates infrastructure investment across all service tiers.
Service Type:
Domestic express lanes anchor volume in Doha's urban core, while cross-border premium tiers leverage Qatar Airways Cargo belly-hold capacity into Europe and Asia.
- Same-Day Delivery:Ultra-time-definite service with real-time dispatch algorithms and localized micro-fulfillment nodes. Demand concentrates among Doha-based e-commerce merchants serving high-value B2C segments, constrained by last-mile density requirements beyond the capital's industrial zones.
- Next-Day Delivery:Premium express tier integrating air freight capacity with dedicated customs brokerage at Hamad International Airport. B2B document flows and time-sensitive parcels drive adoption, supported by DHL Express's established clearance infrastructure.
- Scheduled Delivery:Time-window commitments for inventory replenishment and subscription commerce. Aramex and domestic operators deploy route-optimization systems to defend margin position against rising fuel and labor costs.
- Standard Delivery:Economy tier utilizing ground transportation networks and deferred air capacity. Cross-border B2C parcels from UAE and Saudi distribution hubs populate this segment, with dwell times at Hamad Port compressing through single-window customs platforms.
Next-day delivery commands the established base. The steepest expansion runs through same-day delivery.
Delivery Method:
Air-ground modal splits reflect cost-velocity tradeoffs, with belly-hold constraints at Hamad International Airport forcing peak-season capacity allocation decisions.
- Air Freight:Premium express backbone utilizing Qatar Airways Cargo freighter and passenger belly-hold networks. Perishables, pharmaceuticals, and high-value electronics dominate cargo profiles, with dedicated cold chain infrastructure differentiating carrier positioning.
- Ground Transportation:Cost-optimized domestic distribution and Saudi corridor integration through the Salwa border crossing. Fleet ownership versus third-party logistics partnerships determines margin structure for Doha-Al Khor-Dukhan route networks.
- Rail Services:Emerging intermodal option for bulk parcel consolidation, currently limited by Gulf Cooperation Council rail network completion timelines. Future connectivity to Saudi Arabia's Eastern Province could reshape long-haul economics.
- Last-Mile Delivery:Highest cost-concentration point across all service tiers, absorbing disproportionate margin pressure through dynamic dispatch systems and localized courier density. Micro-fulfillment nodes in Doha's industrial zones address urban core efficiency.
Air freight secures premium positioning. Ground transportation captures volume scale.
Customer Type:
Procurement patterns diverge between enterprise accounts demanding API-integrated visibility and consumers collapsing domestic-cross-border expectations into unified service-level agreements.
- B2B:Document express, spare parts logistics, and just-in-time manufacturing replenishment with defined transit-time guarantees. Per-shipment value retention exceeds B2C tiers, though volume growth lags e-commerce expansion.
- B2C:Direct-to-consumer parcel flows under thirty kilograms displacing traditional freight forwarder intermediation. Qatar's data localization mandates for shipment tracking systems elevate compliance costs, favoring partnerships with domestic license holders.
- E-Commerce:Platform-integrated fulfillment with real-time inventory positioning and returns management. Scheduled and same-day windows compress procurement cycles to eighteen-month technology refresh timelines.
- International Shipping:Cross-border customs brokerage integration with single-window trade platforms. Ministry of Transport commercial licensing requirements slow foreign entrant timelines, fortifying incumbent regulatory relationships.
B2B accounts retain value concentration. E-commerce buyers drive volume acceleration.
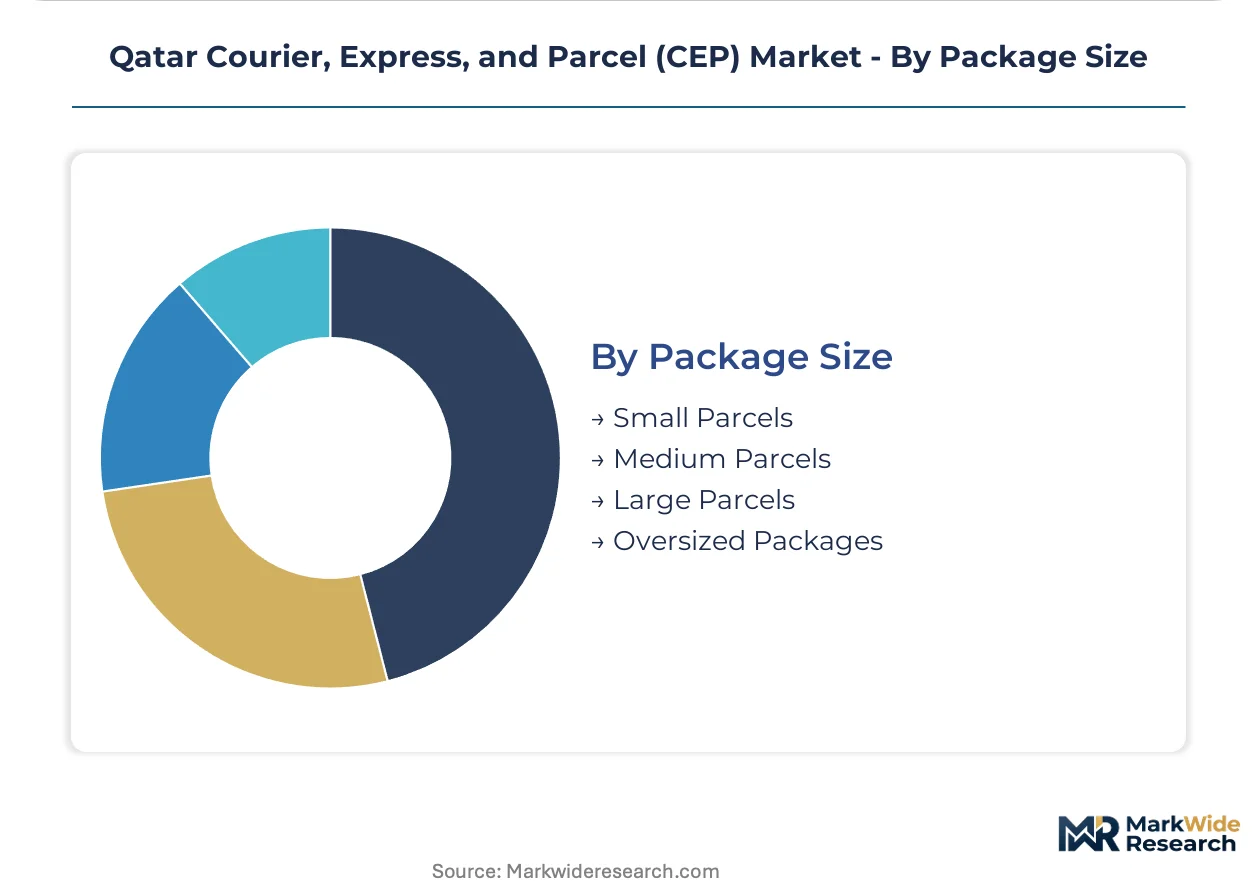
Package Size:
Dimensional weight pricing and sortation automation economics shape carrier infrastructure investment across parcel categories.
- Small Parcels:Documents, electronics accessories, and fashion items dominating B2C express flows. Automated sortation at Hamad International Airport express facilities handles high-throughput, low-touch processing.
- Medium Parcels:Consumer electronics, home goods, and multi-item e-commerce orders requiring manual handling intervention. Ground transportation networks optimize cubic capacity utilization for this tier.
- Large Parcels:Furniture, appliances, and bulk retail shipments stretching standard courier fleet capabilities. Specialized last-mile handling and appointment-based delivery windows add service complexity.
- Oversized Packages:Industrial equipment, automotive parts, and construction materials falling outside standard CEP service parameters. Project logistics and dedicated trucking arrangements supplement express network coverage.
Small parcels anchor automated throughput. Medium parcels expand with e-commerce basket growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's CEP corridors feed Gulf demand through Saudi Arabia's Eastern Province and UAE distribution hubs, with Doha serving as the primary consolidation point for premium express flows into Europe and Asia.
United Arab Emirates
Dubai's Jebel Ali Port and Al Maktoum International Airport anchor transshipment volumes for Qatar-bound parcels. The UAE's customs modernization programs under the Federal Customs Authority accelerate cross-border clearance. Industrial clustering in Dubai South supports last-mile densification for e-commerce merchants serving the Qatar market.
Saudi Arabia
The Salwa border crossing enables ground transportation linkages between Doha and Saudi Arabia's Eastern Province manufacturing zones. SFDA regulations govern pharmaceutical express shipments transiting through Saudi corridors. Dammam's King Fahd Industrial City hosts fulfillment infrastructure that feeds Qatar consumer demand.
India
Indian e-commerce exporters route parcel flows through Qatar Airways Cargo belly-hold capacity into Doha. The Directorate General of Foreign Trade mandates documentation standards for cross-border shipments. Mumbai's Chhatrapati Shivaji International Airport serves as the primary Indian origin point for Qatar-bound express volumes.
Germany
German automotive and industrial component manufacturers utilize Qatar as a Gulf distribution node for spare parts logistics. CE marking requirements under EU regulations standardize product compliance for express shipments. Frankfurt's cargo cluster connects through Qatar Airways freighter networks into Hamad International Airport.
China
Chinese consumer electronics and fashion merchants dominate B2C parcel flows into Qatar through consolidated air freight. SAMR product safety standards govern cross-border e-commerce shipments. Shenzhen's manufacturing belt feeds express volumes through Guangzhou Baiyun International Airport into Doha.
Qatar Courier, Express, and Parcel (CEP) Market Competitive Landscape
Listed leaders compete with private specialists across fleet ownership models, with publicly traded global integrators facing off against state-affiliated and privately held Gulf operators. The market structure concentrates around three tiers: global integrators with dedicated customs brokerage, regional specialists with Saudi corridor integration, and domestic last-mile platforms with micro-fulfillment density. Strategic moves center on captive warehousing investments and dynamic dispatch technology licensing.
Within the global integrator tier, DHL Express and FedEx exemplify premium customs brokerage positioning at Hamad International Airport. Aramex represents the regional specialist archetype with ground transportation integration across Saudi and UAE corridors. Among domestic last-mile platforms, Snoonu anchors Qatar-based fulfillment density for same-day service windows.
| Leading Market Players |
|---|
| FedEx |
| QExpress |
| Qatar Post |
| Snoonu |
| Qatar Airways Cargo |
| Aramex |
| UPS |
| Gulf Warehousing Company |
| DHL Express |
| Others |
Pricing and Supply Chain Analysis
Ministry of Transport commercial licensing requirements gate both carrier qualification and service tier differentiation, forcing foreign entrants into domestic partnerships that compress margin flexibility across same-day and scheduled delivery windows.
Pricing Analysis
Legacy dispatch infrastructure versus real-time algorithmic platforms versus predictive analytics systems stratifies carrier pricing power across three performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects customs brokerage depth, last-mile density, and API integration sophistication. Cost compression in standard delivery intensifies as Aramex and domestic operators deploy route-optimization systems to defend margin position. E-commerce merchants with eighteen-month procurement cycles exhibit lowest price sensitivity, while cross-border B2C parcels through UAE distribution hubs face highest buyer price sensitivity.
Supply Chain Analysis
Qatar and the United Arab Emirates anchor Gulf CEP infrastructure, with Saudi Arabia feeding corridor volumes through the Salwa border crossing. Express networks draw from Qatar Airways Cargo belly-hold capacity, DHL Express customs brokerage infrastructure, and Aramex ground transportation fleet. Single-source vulnerability concentrates in Hamad International Airport peak-season capacity allocation. Distribution runs through Doha's industrial zone clustering near Hamad Port and Hamad International Airport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat structure where Ministry of Transport licensing and data localization mandates create switching costs that entrench established customs brokerage relationships.
For Market Incumbents: Fortify captive warehousing positions in Doha's industrial zones near Hamad Port to preempt micro-fulfillment localization by emerging platform operators. Deepen API connectivity with merchant platforms to raise integration switching costs. Priority lever rests on dynamic dispatch technology licensing to asset-light competitors seeking rapid deployment without legacy system retrofit. For New Entrants and Emerging Players: Domestic license holder certification fast-track partnerships offer the most penetrable path through Ministry of Transport commercial licensing barriers. Target same-day delivery density gaps beyond Doha's urban core toward Al Khor and Dukhan. Go-to-market angle centers on Saudi corridor integration through Salwa border ground transportation linkages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional logistics platforms possessing established Qatari regulatory relationships but lacking technology modernization capital. Long-term viability frames around five-to-ten year e-commerce volume acceleration and customs modernization tailwinds. Signal to watch: single-window trade platform API standardization that would lower compliance infrastructure barriers for foreign platform entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Localization | Industrial zone clustering near Hamad Port supports captive inventory positioning for cross-border B2C flows. |
| Dynamic Dispatch Technology Licensing | Real-time algorithm platforms bifurcate market share between asset-light operators and legacy fleet owners. |
| Saudi Corridor Integration | Salwa border crossing ground linkages extend Gulf reach from Doha into Eastern Province manufacturing zones. |
| Premium Customs Brokerage Capacity | Dedicated clearance infrastructure at Hamad International Airport differentiates time-sensitive B2B document flows. |
| Domestic License Partnership Structure | Ministry of Transport commercial licensing requirements favor alliances with established Qatari operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs authority filings, Ministry of Transport licensing registries, and Qatar Airways Cargo capacity disclosures. Interviews with CEP operations directors, e-commerce logistics procurement managers, customs brokerage leads, and last-mile platform engineers inform demand-side validation. Secondary sources include Qatar's single-window trade platform documentation, Hamad International Airport cargo throughput statistics, and GCC logistics operator SEC filings. Bottom-up parcel volume modeling triangulates against top-down market sizing from macro trade flow analysis.
Segmentation dimensions modeled span service type, delivery method, customer type, and package size across the projection horizon. Analytical framework derives CAGRs from e-commerce penetration trajectories, customs modernization implementation timelines, and industrial zone infrastructure investment patterns. Industry-specific forecast inputs incorporate Qatar Airways Cargo freighter network expansion schedules and Salwa border crossing capacity upgrades.
Decision-makers should treat outputs as directional under sustained e-commerce merchant demand for scheduled and same-day windows; material deviation in belly-hold capacity constraints or data localization enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in customs single-window platform adoption and last-mile density algorithm deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
India Cold Chain Logistics Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Logistics Outsourcing Market