
 North America Same Day Delivery Market | 2026-2036
North America Same Day Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Same Day Delivery Market Insights
Asset-light fleet leasing and third-party driver marketplace models are reshaping competitive entry in North American same-day delivery. OnTrac leverages its West Coast density to sustain regional cost advantages against national carriers. FedEx anchors its position through integrated air-ground networks that compress transit times for premium parcel segments.
Same-day delivery denotes logistics fulfillment completing order receipt, picking, transport, and handoff within a single calendar day, typically requiring real-time inventory visibility and dynamic route optimization across distances under 100 miles. The service type dimension spans personal, retail, food, and package delivery, with food delivery occupying the highest frequency tier due to perishability constraints and consumer willingness to pay convenience premiums. Customer type splits across B2B, B2C, e-commerce, and local business channels, where B2C e-commerce orders dominate volume but B2B medical and industrial parts sustain superior unit economics through contractual SLAs.
The U.S. Department of Transportation governs commercial driver hours-of-service limits, while the EPA regulates last-mile vehicle emissions through Tier 3 standards and California Air Resources Board waivers that propagate zero-emission zone requirements. The Federal Aviation Administration oversees emerging drone delivery trials that could reshape exurban access economics. Stakeholders must monitor regulatory fragmentation between federal DOT rules and state-level gig-worker classification statutes that threaten cost structures in California, New York, and Illinois.
Market Dynamics
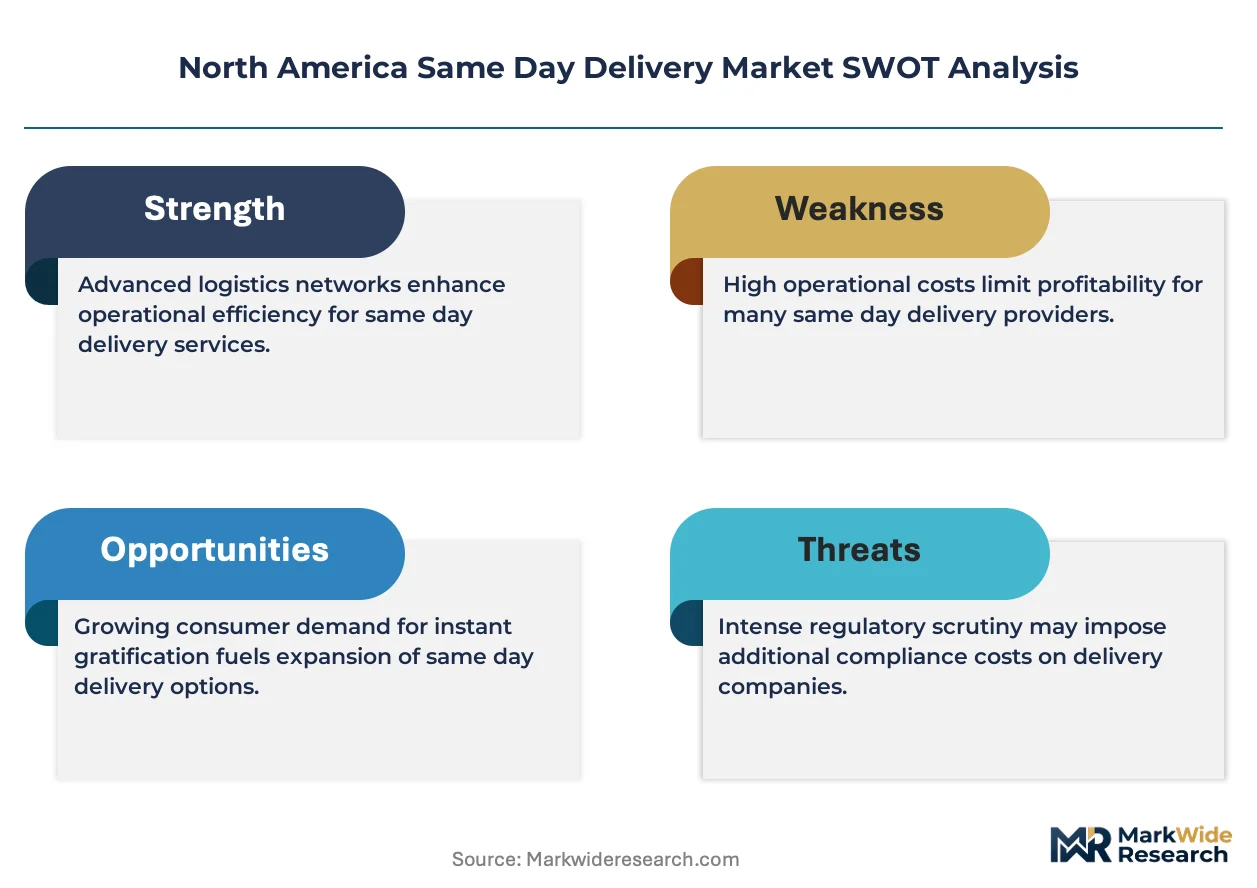
Fleet electrification mandates and urban congestion pricing are compressing operating margins across North American same-day networks, forcing operators to reconfigure hub placement and vehicle mix.
Growth Catalysts
- EPA Tier 3 Emissions Standards:Federal tailpipe regulations are accelerating zero-emission van procurement across California, New York, and Illinois distribution fleets.
- Perishable Food Networks:Grocery chains are deploying micro-fulfillment centers within 10 miles of dense urban cores to sustain sub-two-hour cold chain handoffs.
- Urban Density Corridors:The U.S. Northeast megalopolis from Boston to Washington D.C. sustains route density economics that rural and exurban zones cannot replicate.
Market Restraints
- Lithium-Ion Battery Supply:Cathode material concentration in Asian processing facilities exposes fleet operators to input cost volatility and procurement delays.
- Hours-of-Service Limits:DOT regulations cap driver availability at 11 hours daily, constraining peak-period capacity expansion without proportional labor cost increases.
- Last-Mile Labor Classification:State-level gig-worker statutes in California and New York threaten variable-cost workforce models with reclassification to W-2 employment structures.
Strategic Opportunities
- Drone Delivery Corridors:FAA Part 135 certification pathways for autonomous aerial systems could unlock exurban access economics previously excluded from same-day networks.
- Healthcare Logistics Contracts:B2B medical parts delivery commands premium pricing through contractual SLAs that retail e-commerce cannot match.
- Canadian Urban Expansion:Toronto and Vancouver density profiles support replication of U.S. Northeast hub-and-spoke models with lower regulatory fragmentation.
Industry Challenges
- Route Optimization Talent Scarcity:Operations research specialists capable of dynamic fleet dispatching command compensation premiums that mid-size carriers struggle to absorb.
- Real-Time Inventory Integration:Legacy warehouse management systems require capital-intensive API redevelopment to synchronize with consumer-facing delivery promise engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Same Day Delivery Market |
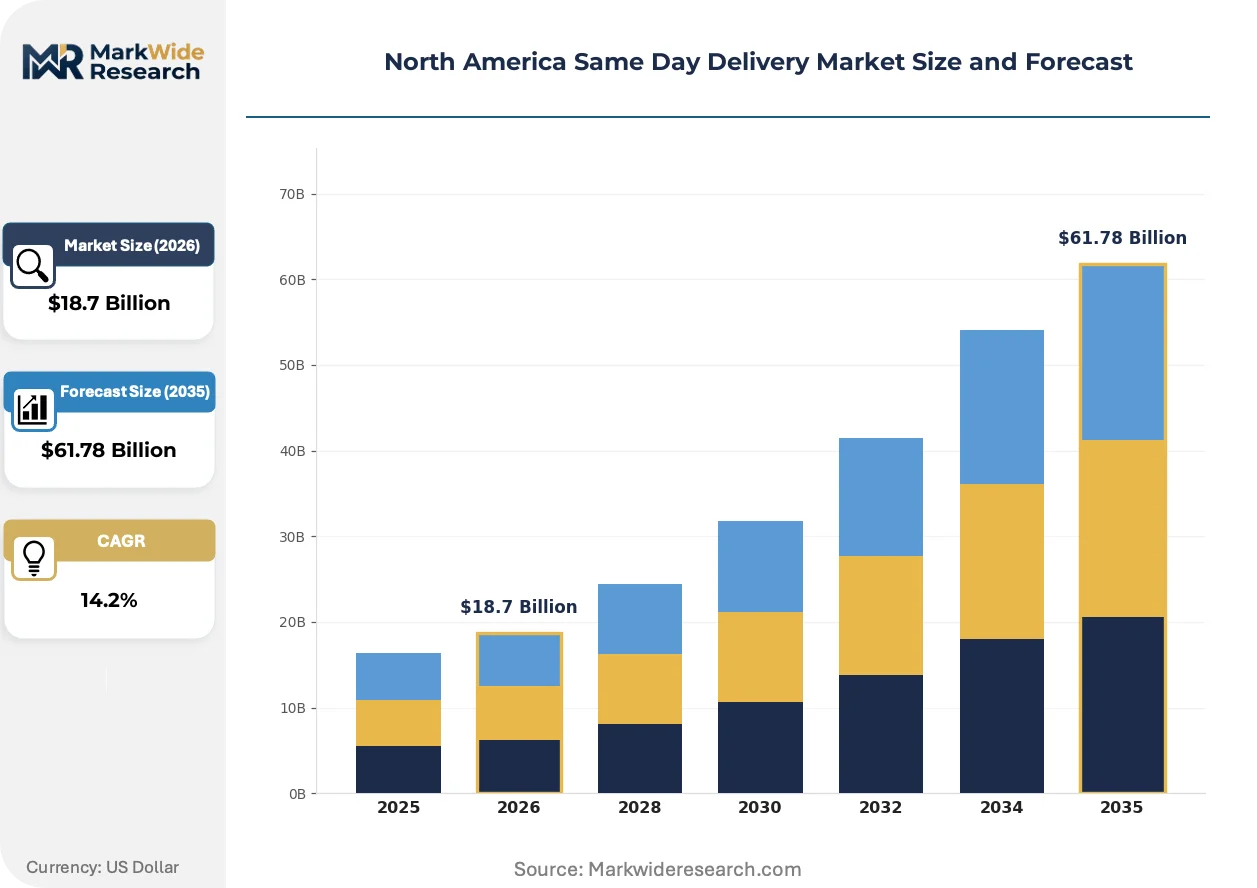
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Delivery, Retail Delivery, Food Delivery, Package Delivery Customer Type: B2B, B2C, E-commerce, Local Businesses Technology: Mobile Apps, Web Platforms, GPS Tracking, Automated Dispatching Delivery Method: Curbside Pickup, Bicycle Delivery, Motorcycle Delivery, Van Delivery |
| Companies Covered | OnTrac, USPS, FedEx, Spee-Dee Delivery Service, Inc., Jet Delivery Inc., United Parcel Service of America, Inc. (UPS), Amazon, Instacart, DHL Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Same Day Delivery Market Trends and Innovations
Operational technology convergence is collapsing the latency between order capture and dispatch, while regulatory pressure on emissions and labor classification forces business model reinvention across the value chain.
Dynamic route optimization software is hybridizing deterministic algorithms with machine learning demand forecasting. Third-party logistics providers and captive retail fleets are adopting these platforms within 18-24 month procurement cycles. The technology is hybridizing static hub-and-spoke networks into adaptive mesh configurations that reallocate capacity hourly based on order flow patterns.
The EPA's evolving last-mile emissions standards and California Air Resources Board zero-emission zone waivers are mandating electric van deployment timelines. Fleet operators face accelerated asset replacement schedules and charging infrastructure capex requirements. Cold chain and pharmaceutical delivery segments are responding earliest due to temperature-controlled vehicle premium pricing that absorbs electrification costs.
Buyer procurement patterns are compressing delivery promise windows from next-day to same-day as a baseline expectation. E-commerce platforms are unbundling free shipping thresholds from speed guarantees, creating explicit convenience pricing tiers. This shift is most visible in apparel and consumer electronics verticals within the U.S. Northeast corridor, where density supports sustainable sub-two-hour economics.
North America Same Day Delivery Market Segmentation
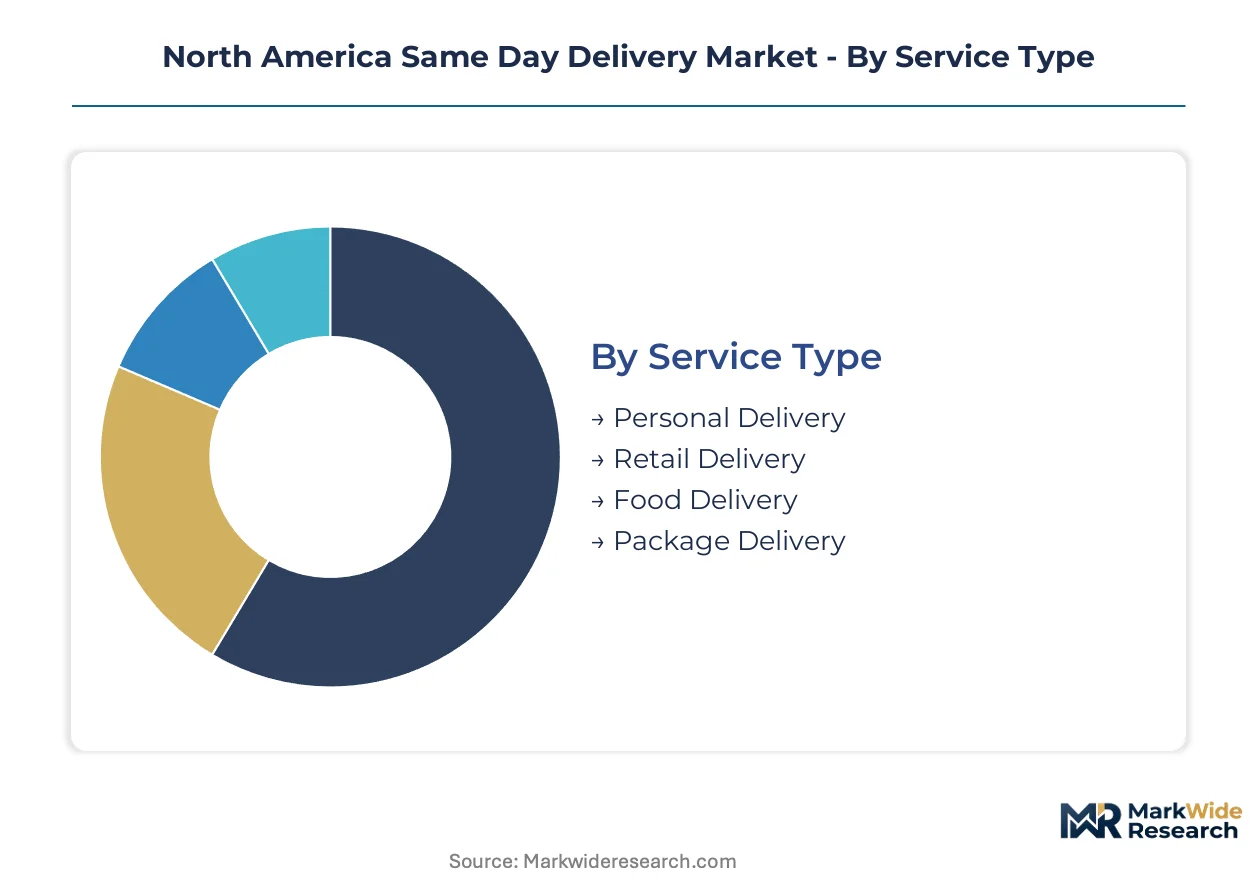
Same-day delivery economics collapse or survive based on how precisely operators match service configuration to demand density and perishability constraints. Segmentation reveals where route optimization investments yield margin expansion versus where asset-light models sustain viability.
Service Type:
Application type determines fleet composition, labor scheduling intensity, and cold chain infrastructure requirements across North American networks.
- Food Delivery:Temperature-controlled transport mandates specialized van fleets with dual-zone refrigeration units. Perishability windows compress handoff SLAs to under 60 minutes in dense urban cores like Manhattan and downtown Chicago.
- Retail Delivery:Apparel and electronics orders sustain higher fulfillment costs through convenience premiums. Micro-fulfillment center placement within 10 miles of customer clusters enables sub-two-hour economics in the Boston-Washington corridor.
- Package Delivery:Document and small parcel flows concentrate in B2B corridors with recurring route patterns. FedEx and UPS ground networks capture this segment through integrated air-ground handoffs.
- Personal Delivery:Ad hoc item transport commands spot pricing with limited volume predictability. On-demand driver marketplaces serve this niche through variable-cost workforce models.
Food delivery commands the established base. The steepest expansion runs through retail delivery as grocery chains deploy micro-fulfillment infrastructure.
Customer Type:
Contract structure and pricing power diverge sharply between recurring B2B relationships and transactional B2C volume.
- B2B:Medical parts and industrial component contracts carry penalty clauses for SLA breaches. Cleveland Clinic and Siemens Healthineers operations in the U.S. Midwest anchor this high-margin segment.
- E-commerce:Platform-integrated fulfillment absorbs last-mile costs into customer acquisition spend. Amazon Prime and Walmart+ subscriptions mask explicit delivery pricing through bundled membership fees.
- B2C:Individual order economics struggle without density or subscription offset. Standalone same-day premiums of $7-$12 apply to non-member transactions.
- Local Businesses:Restaurant and pharmacy networks rely on third-party logistics for capacity overflow. DoorDash Drive and Uber Direct white-label solutions serve this intermediary role.
B2B relationships command the established base. The steepest expansion runs through e-commerce as platform subscription models normalize same-day baselines.
Technology:
Technology deployment separates operators capable of dynamic dispatch from those locked into static route planning.
- Automated Dispatching:Machine learning algorithms ingest real-time traffic, weather, and order flow to reallocate fleet capacity hourly. Project44 and Wise Systems platforms command implementation fees that mid-size carriers struggle to justify.
- GPS Tracking:Consumer-facing visibility layers reduce failed delivery rates and customer service contact volume. Real-time location data feeds ETA refinement engines that compress promise windows.
- Mobile Apps:Driver-facing interfaces handle route navigation, proof-of-capture, and payment reconciliation. Gig-worker classification disputes in California and New York complicate app-based workforce management.
- Web Platforms:Merchant integration portals enable order injection and inventory synchronization. API redevelopment costs burden legacy warehouse management system operators.
Automated dispatching commands the established base. The steepest expansion runs through GPS tracking as consumer expectation for visibility hardens.
Delivery Method:
Vehicle selection trades speed against payload capacity and regulatory compliance cost across urban, suburban, and exurban zones.
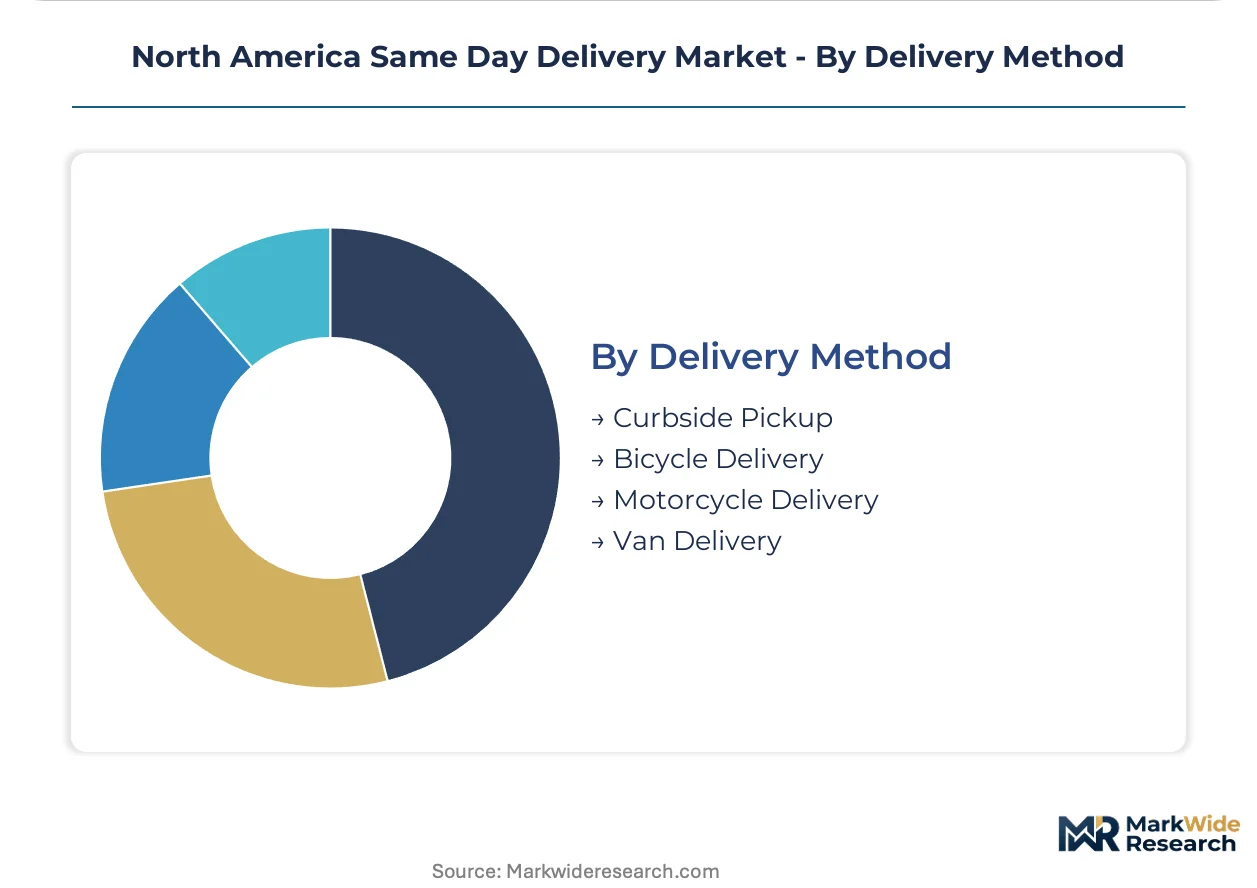
- Van Delivery:Electric Ford E-Transit and Rivian EDV units satisfy EPA Tier 3 and California Air Resources Board zero-emission mandates. Cold chain pharmaceutical deliveries absorb electrification capex through premium pricing.
- Bicycle Delivery:Zero-emission last-mile solution dominates Manhattan, San Francisco, and downtown Toronto cores where congestion pricing and parking scarcity constrain motorized access.
- Motorcycle Delivery:Intermediate payload and speed profile serves mid-density zones without full van economics. DOT hours-of-service limits apply equally, constraining driver utilization.
- Curbside Pickup:Customer collection eliminates last-mile transport cost entirely. Kroger and Target parking lot fulfillment models expand this segment through dedicated pickup bays.
Van delivery commands the established base. The steepest expansion runs through bicycle delivery as urban congestion pricing spreads beyond New York to Chicago and Los Angeles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands pricing power through Northeast corridor density, while Canadian operators absorb margin compression from lower urban concentration and cross-border regulatory friction.
United States
The Boston-Washington megalopolis sustains sub-two-hour delivery economics through route density unmatched elsewhere. EPA Tier 3 emissions standards and California Air Resources Board waivers mandate zero-emission van procurement timelines. Manhattan and downtown Chicago anchor bicycle delivery networks where congestion pricing eliminates motorized competition.
Canada
Toronto and Vancouver density profiles replicate U.S. Northeast hub-and-spoke models with reduced regulatory fragmentation. Health Canada and PMRA pharmaceutical transport guidelines impose cold chain standards that elevate compliance costs. The Greater Toronto Area concentrates grocery micro-fulfillment investment from Loblaw and Metro.
Mexico
Mexico City Metro generates demand through e-commerce platform expansion and informal retail digitization. The Secretariat of Economy and COFEPRIS regulate cross-border pharmaceutical and food logistics. Nuevo León industrial clusters near Monterrey attract last-mile fulfillment infrastructure for U.S. border-zone access.
North America Same Day Delivery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fleet leasing, route optimization software, and driver marketplace infrastructure. The North American same-day delivery structure concentrates around three strategic archetypes: national integrated carriers with air-ground networks, regional density specialists with cost-advantaged zone coverage, and asset-light platform operators aggregating third-party capacity. Competitive moves center on micro-fulfillment center placement within ten-mile urban radii and electric van fleet procurement accelerated by EPA mandates.
Among national integrated carriers, FedEx and United Parcel Service of America, Inc. occupy positions defined by air-ground network compression capabilities. OnTrac exemplifies the regional density specialist archetype, leveraging West Coast zone concentration against national carrier cost structures. Amazon represents platform-integrated captive fulfillment, absorbing last-mile costs into subscription economics that mask explicit delivery pricing.
| Leading Market Players |
|---|
| OnTrac |
| USPS |
| FedEx |
| Spee-Dee Delivery Service, Inc. |
| Jet Delivery Inc. |
| United Parcel Service of America, Inc. (UPS) |
| Amazon |
| Instacart |
| DHL Group |
| Others |
Pricing and Supply Chain Analysis
The I-95 freight corridor anchors cost dynamics across North American same-day networks, where hub concentration within ten-mile urban radii enables price premiums for sub-two-hour windows while sparse exurban zones force cost absorption or service exclusion.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term pricing with penalty clauses for SLA breaches, while B2C e-commerce absorbs last-mile costs into subscription bundles that mask explicit delivery fees. Price differentiation stems from geographic delivery cost and volume scale, with dense Northeast corridors supporting three-tier pricing structure across premium, standard, and economy levels. Cost compression in the B2C tier is intensifying because platform subscription models normalize same-day baselines without explicit convenience premiums. B2B medical and industrial parts buyers exhibit lowest price sensitivity due to contractual SLAs and downtime costs.
Supply Chain Analysis
Foxconn, Flex, and Jabil hold limited contract-manufacturing presence in electric van powertrain assembly, with vehicle production concentrated in the United States, Mexico, and Canada. Lithium-ion battery cells, electric drivetrain components, and telematics hardware feed from Asian processing facilities and North American assembly plants. Single-source vulnerability in cathode material supply exposes fleet operators to procurement delays. Distribution runs through captive retail fulfillment networks, third-party logistics partnerships, and gig-worker marketplace platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American same-day delivery is exiting a capital-intensive buildout phase into utilization-focused margin recovery, with fleet electrification capex cycles and subscription revenue stabilization as the cyclical pivot points.
For Market Incumbents: Build density moats through micro-fulfillment center placement within ten-mile radii of proven demand clusters. Consolidate position by acquiring regional specialists with zone coverage advantages against national carrier cost structures. Electric van fleet procurement accelerated by EPA Tier 3 mandates threatens margin compression without volume density to absorb charging infrastructure capex.
For New Entrants and Emerging Players: Canadian urban corridors outside Toronto and Vancouver offer underpenetrated density profiles with lower regulatory fragmentation than U.S. state-level gig-worker statutes. Target healthcare logistics contracts in the U.S. Midwest where Cleveland Clinic and Siemens Healthineers operations sustain premium pricing through SLA penalties. Pursue white-label B2B fulfillment partnerships as the go-to-market angle to bypass consumer acquisition costs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors route optimization software specialists with machine learning dispatch capabilities over asset-heavy fleet operators. Long-term viability hinges on subscription revenue retention and API integration depth with merchant inventory systems. Monitor quarterly fleet utilization rates and driver reclassification litigation outcomes as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Center Expansion | Loblaw and Metro deployments in Greater Toronto Area compress last-mile costs through ten-mile radius coverage. |
| Electric Van Fleet Procurement | Ford E-Transit and Rivian EDV orders satisfy California Air Resources Board zero-emission zone mandates ahead of compliance deadlines. |
| Route Optimization Platform Integration | Project44 and Wise Systems implementations enable hourly capacity reallocation based on real-time traffic and order flow. |
| Healthcare Logistics Contracting | B2B medical parts delivery commands premium pricing through penalty clauses that retail e-commerce cannot replicate. |
| Gig-Worker Marketplace Diversification | DoorDash Drive and Uber Direct white-label solutions buffer capacity overflow for restaurant and pharmacy networks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, logistics procurement managers, route optimization software vendors, and electric vehicle fleet managers; and secondary validation through DOT hours-of-service filings, EPA emissions compliance databases, FAA drone delivery trial records, and SEC 10-K disclosures from publicly traded carriers. Bottom-up triangulation of carrier capacity deployment and top-down demand modeling across service type and customer segments anchored volume estimates.
Forecast inputs spanned fleet electrification capex schedules, urban congestion pricing adoption curves, and gig-worker reclassification litigation timelines across the projection horizon. Segmentation dimensions modeled include service type, customer type, technology deployment, and delivery method, with electric van procurement timelines and micro-fulfillment center buildout rates as industry-specific demand drivers. CAGRs derived from logistic curve fitting of adoption phases and elasticity-adjusted price response functions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated entrants or regulatory arbitrage specialists would shift outcomes beyond modeled ranges. Supply chain disruptions in lithium-ion battery cathode processing, DOT hours-of-service rule revisions, or state-level gig-worker reclassification statutes could revise trajectory. Quarterly review of fleet utilization metrics, charging infrastructure deployment rates, and driver classification court rulings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Inland Container Depot and Dry Port Market