
 US Express Delivery Market | 2026-2036
US Express Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
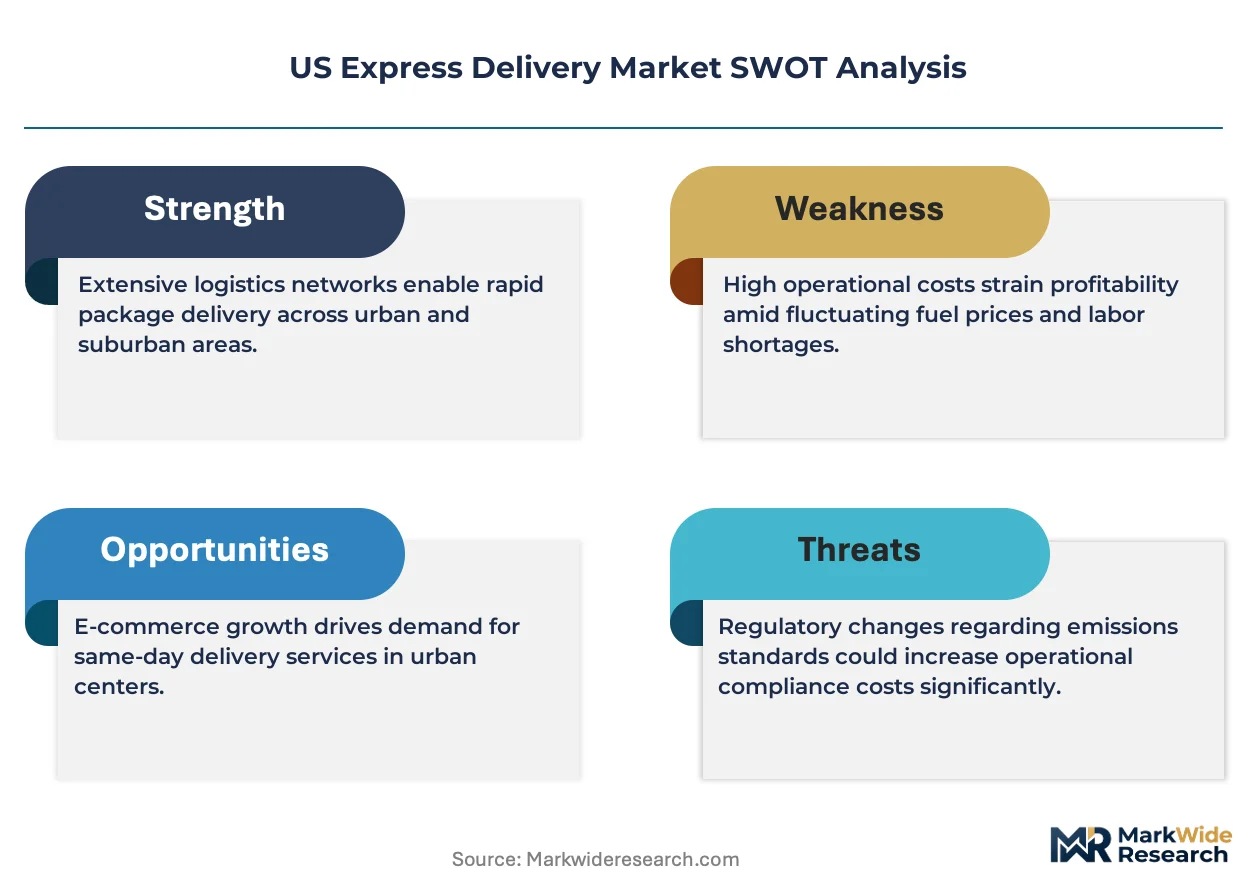
US Express Delivery Market Insights
California's Advanced Clean Trucks regulation is recalibrating fleet procurement timelines across the US express delivery sector, forcing carriers to accelerate zero-emission vehicle deployments ahead of federal mandates. United Parcel Service (UPS) anchors its sustainability strategy through extensive alternative fuel and electric vehicle investments across its ground network. FedEx differentiates via carbon-neutral shipping pledges and sustainable aviation fuel commitments in its air express operations. Amazon Logistics competes through dense last-mile station networks and proprietary routing algorithms that compress delivery windows.
US express delivery encompasses time-definite transportation of parcels, documents, and freight through integrated ground, air, and emerging drone networks, operating within service level agreements that specify delivery windows from same-day to standard two-to-five-day transit. The service type dimension shows next-day delivery commanding premium pricing power while same-day delivery captures the fastest expansion as urban fulfillment nodes proliferate. Customer type segmentation reveals B2C e-commerce flows driving volume growth, though B2B accounts retain superior yield per package through contracted rate structures and specialized handling requirements.
The Federal Aviation Administration (FAA) governs commercial drone operations through Part 135 certification requirements, while the Department of Transportation (DOT) and Federal Motor Carrier Safety Administration (FMCSA) regulate driver hours and vehicle safety standards that directly constrain network capacity. The Environmental Protection Agency (EPA) Phase 3 standards and California Air Resources Board (CARB) waivers create a bifurcated compliance landscape that elevates capital requirements for national operators. Stakeholders must monitor drone integration rulemaking and state-level zero-emission zone designations as these will determine the next phase of infrastructure investment and competitive positioning.
Market Dynamics
Fleet electrification timelines are compressing across the US express delivery sector as California's Advanced Clean Trucks regulation forces carriers to front-load zero-emission vehicle procurement ahead of federal Phase 3 standards, reshaping capital allocation and network design simultaneously.
Growth Catalysts
- Healthcare cold-chain reliability:Pharmaceutical distributors demand temperature-controlled last-mile infrastructure as biologics and vaccines expand their share of prescription volumes.
- EPA Phase 3 standards:Heavy-duty vehicle greenhouse gas rules accelerate fleet modernization investments, pulling forward electrification roadmaps for national operators.
- Texas-California-Florida corridor density:Overlapping same-day coverage radii in these population centers create network effects that reduce per-delivery cost structures.
Market Restraints
- Battery supply concentration:Lithium-ion cell production concentrates in Asian manufacturing hubs, exposing carriers to input cost volatility and geopolitical sourcing risk.
- Charging infrastructure gaps:Depot electrification requires utility interconnection timelines that lag fleet deployment schedules, constraining vehicle utilization rates.
- Driver availability constraints:FMCSA hours-of-service regulations limit network capacity expansion even as e-commerce volumes rise, tightening labor markets in key corridors.
Strategic Opportunities
- Midwestern fulfillment node expansion:Secondary markets in Ohio and Illinois offer lower real estate costs for same-day coverage extension beyond coastal density zones.
- Drone integration under FAA Part 135:Beyond-visual-line-of-sight certification unlocks rural and suburban delivery economics previously unprofitable for ground networks.
- Renewable natural gas infrastructure:RNG fueling corridors along interstate highways provide interim decarbonization pathways for long-haul linehaul operations ahead of full electrification.
Industry Challenges
- Telematics integration complexity:Legacy dispatch systems require substantial retrofitting to coordinate electric vehicle range management with dynamic routing algorithms.
- Technician skill scarcity:High-voltage powertrain maintenance demands certifications that current diesel mechanic workforces lack, slowing fleet uptime recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Express Delivery Market |
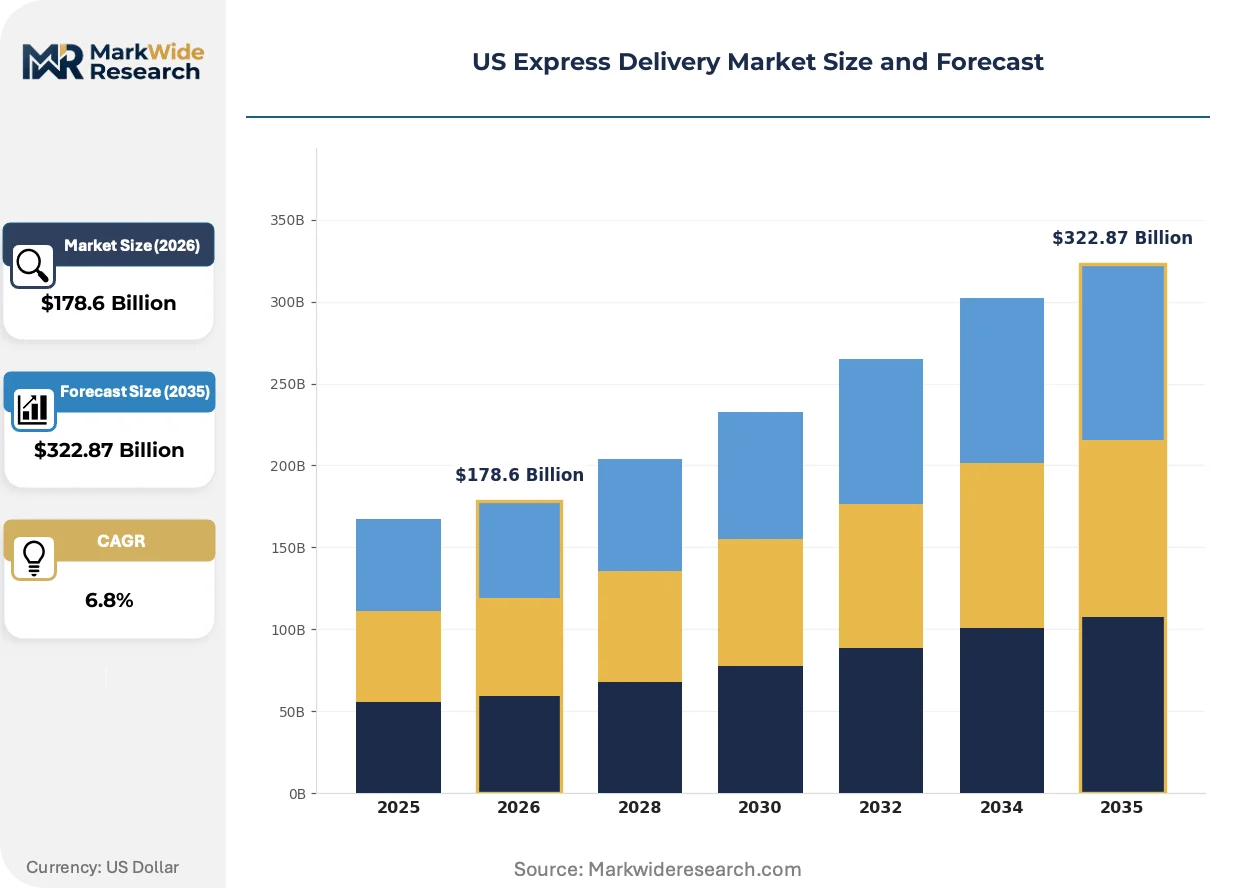
| Market Size in 2026 | $178.6 Billion |
| Market Size in 2035 | $322.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, International Delivery Customer Type: B2B, B2C, E-commerce, Retailers Delivery Mode: Ground, Air, Sea, Drone Package Type: Documents, Parcels, Freight, Special Handling |
| Companies Covered | United Parcel Service (UPS), FedEx, United States Postal Service (USPS), DHL Group, OnTrac, Amazon Logistics, Spee Dee Delivery Service, Lone Star Overnight (LSO), Dropoff, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Express Delivery Market Trends and Innovations
Artificial intelligence is compressing delivery window promises from next-day to same-hour through predictive inventory positioning and dynamic route optimization that anticipates demand before orders materialize.
Autonomous middle-mile platforms are unifying warehouse-to-hub transfers with hub-to-station movements through self-driving truck deployments on designated interstate corridors. Kroger and Walmart are piloting these systems between distribution centers and last-mile facilities in Arizona and Texas. This technology is unifying previously fragmented linehaul economics under single-platform control, reducing handoff costs and transit variability.
California's CARB waivers are creating a bifurcated compliance landscape that elevates capital requirements for national operators serving multiple state jurisdictions. Carriers must maintain separate fleet pools or over-specify zero-emission vehicles to satisfy the strictest standard. The California-anchored operators face accelerated procurement timelines that strain supplier relationships and financing structures.
Healthcare procurement teams are consolidating express delivery contracts around temperature-assurance certifications rather than speed metrics alone. Pharmaceutical distributors now prioritize validated cold-chain handoffs over nominal transit times, displacing generic parcel carriers with specialized logistics providers. This shift concentrates volume with operators holding GDP-compliant infrastructure, particularly visible in the Northeast and West Coast biotech corridors.
US Express Delivery Market Segmentation
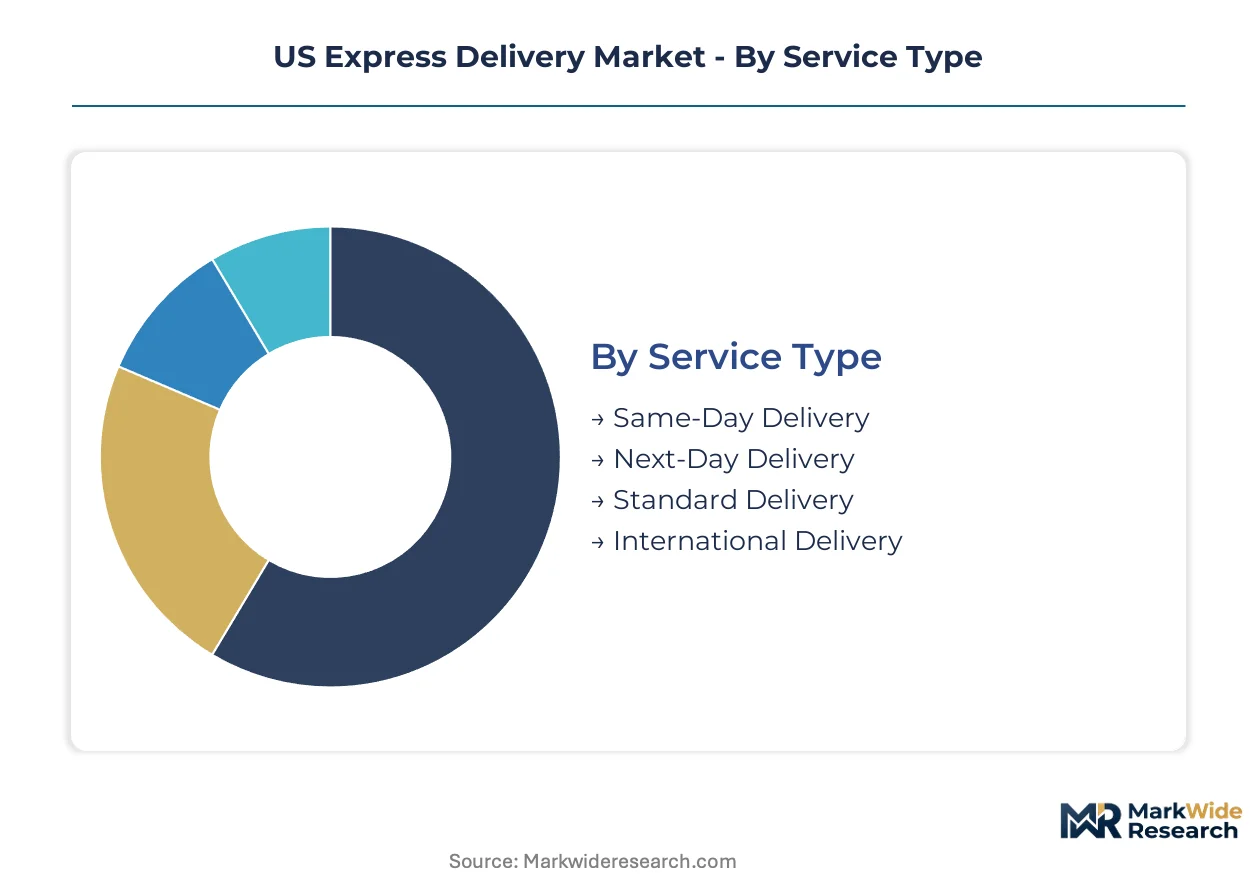
Express delivery segmentation reveals how carriers allocate capital across speed tiers and customer profiles. Service level commitments, vehicle fleet composition, and facility networks all derive from these category boundaries.
Service Type:
Upgrade cycles accelerate as e-commerce platforms compress delivery promises from next-day to same-day windows, forcing infrastructure reinvestment across fulfillment node density and last-mile vehicle fleets.
- Same-Day Delivery:Urban fulfillment stations position inventory within 50-mile radii of dense population centers, enabling two-hour to four-hour windows. Texas, California, and Florida corridor overlaps concentrate demand where station density justifies per-unit economics.
- Next-Day Delivery:Hub-and-spoke air and ground networks guarantee morning or afternoon delivery through time-definite sorting commitments. B2B accounts retain contracted rate premiums for this tier despite B2C volume expansion.
- Standard Delivery:Two-to-five-day ground transit optimizes linehaul utilization through deferred sorting schedules. Secondary markets in Ohio and Illinois extend coverage at lower real estate cost per square foot.
- International Delivery:Customs brokerage integration and bonded warehouse networks manage cross-border complexity. Air freight forwarding dominates time-sensitive lanes while ocean consolidation serves cost-optimized flows.
Volume placements concentrate in Standard Delivery; the faster expansion belongs to Same-Day Delivery.
Customer Type:
Margin structures diverge sharply between contracted B2B relationships and variable B2C transaction economics, reshaping sales force deployment and pricing system architecture.
- B2B:Contracted rate structures with specialized handling requirements yield superior yield per package. Pharmaceutical distributors and industrial manufacturers drive demand for temperature-assurance and security protocols.
- B2C:Transactional e-commerce flows dominate volume growth through platform-integrated checkout experiences. Residential delivery density challenges last-mile cost efficiency despite aggregate scale.
- E-commerce:Marketplace sellers and direct-to-consumer brands require returns processing infrastructure alongside outbound fulfillment. Amazon Logistics and proprietary retailer networks compete for this segment.
- Retailers:Omnichannel inventory positioning demands ship-from-store and distribution center flexibility. Big-box chains in Arizona and Texas pilot autonomous middle-mile transfers to compress replenishment cycles.
Revenue yield concentrates in B2B; the steepest expansion trajectory belongs to E-commerce.
Delivery Mode:
Capital allocation shifts as EPA Phase 3 standards and California CARB waivers force fleet electrification timelines that favor ground network reinvestment over air capacity expansion.
- Ground:Diesel and electric vehicle fleets handle last-mile and linehaul movements through depot-based dispatch systems. Fleet procurement compresses as California Advanced Clean Trucks regulation accelerates zero-emission deployment schedules.
- Air:Integrated express carriers operate dedicated freighter fleets and belly cargo contracts for next-day coverage. Sustainable aviation fuel commitments address carbon-neutral pledges without full fleet replacement.
- Sea:Ocean freight consolidation serves deferred international lanes with customs brokerage integration. Port congestion variability limits reliability for time-definite commitments.
- Drone:FAA Part 135 certification requirements govern beyond-visual-line-of-sight operations for rural and suburban delivery economics. Battery supply concentration in Asian manufacturing hubs constrains deployment scale.
Capacity investment concentrates in Ground; the emerging expansion pathway belongs to Drone.
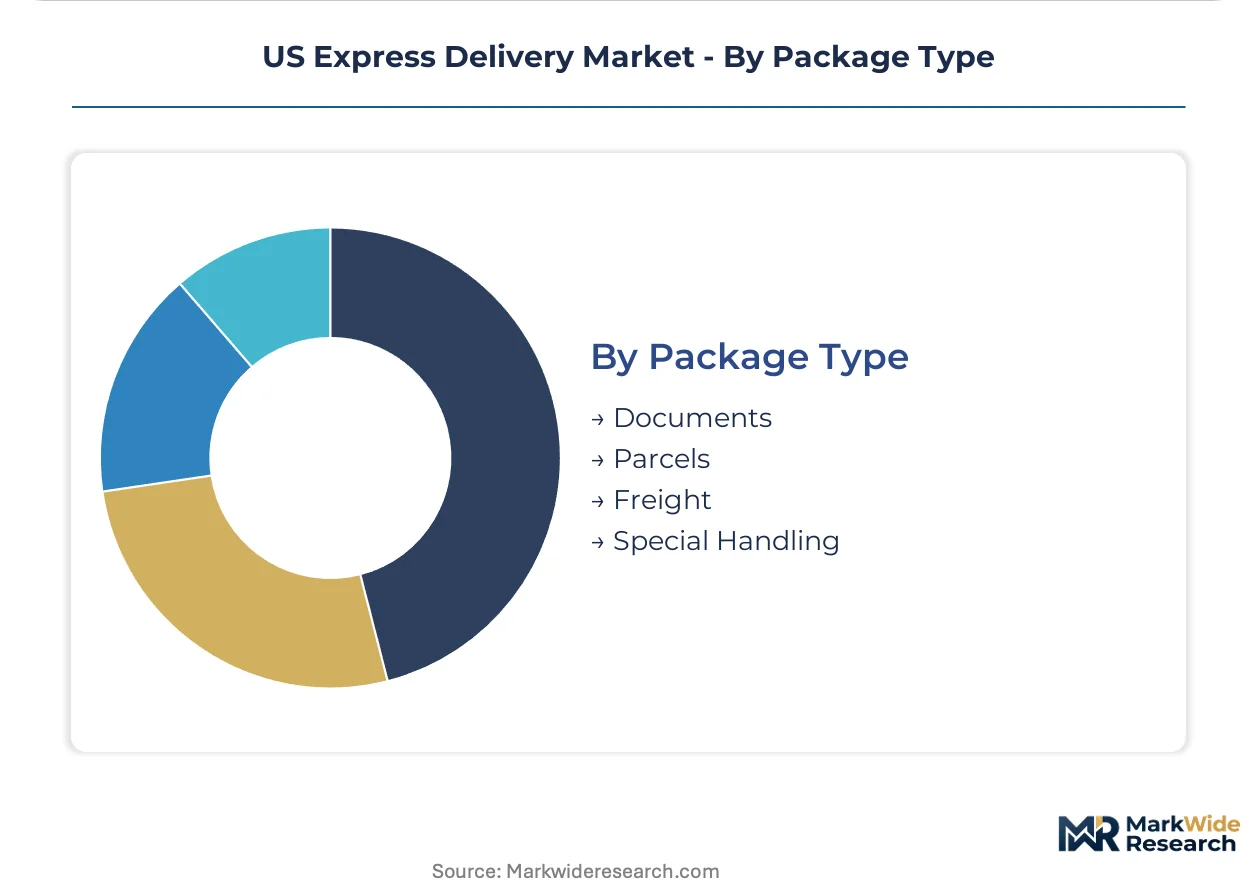
Package Type:
Handling infrastructure specialization separates commodity parcel flows from premium service tiers requiring validated protocols or oversized capacity.
- Documents:Lightweight envelopes and small packets move through automated sorting systems with minimal dimensional weight penalties. Digital substitution erodes volume in legal and financial verticals.
- Parcels:Standardized box dimensions optimize trailer cube utilization and conveyor belt throughput. E-commerce SKU proliferation challenges sortation efficiency.
- Freight:LTL and truckload express movements require liftgate equipment and dock-height trailer access. Midwestern fulfillment nodes in Illinois extend heavy goods coverage beyond coastal density zones.
- Special Handling:Temperature-controlled and high-security protocols demand GDP-compliant infrastructure and chain-of-custody documentation. Healthcare procurement teams consolidate contracts around cold-chain reliability certifications.
Sortation volume concentrates in Parcels; the premium expansion rate belongs to Special Handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Texas, California, and Florida corridor networks where overlapping same-day coverage radii achieve density economics, while consumption spreads across coastal population centers and emerging Midwestern fulfillment nodes seeking lower real estate costs per square foot.
Texas
E-commerce fulfillment demand from healthcare distributors and oilfield equipment suppliers drives volume growth through Dallas-Fort Worth and Houston metro areas. The Texas Commission on Environmental Quality enforces emissions standards that complement federal EPA Phase 3 timelines for heavy-duty fleet modernization. The Dallas-Fort Worth-Arlington corridor anchors autonomous middle-mile pilot programs between distribution centers and last-mile stations.
California
Biotech and pharmaceutical cold-chain requirements from San Francisco Bay Area and San Diego clusters elevate demand for GDP-compliant temperature-assurance infrastructure. The California Air Resources Board Advanced Clean Trucks regulation accelerates zero-emission vehicle procurement timelines ahead of federal mandates. The Los Angeles-Long Beach-Anaheim metro sustains the densest last-mile station network west of the Mississippi.
Florida
Tourism-related retail replenishment and aging population healthcare logistics generate express volume through Miami and Tampa corridors. The Florida Department of Transportation coordinates with federal FMCSA hours-of-service enforcement that constrains driver availability in peak season. The Miami-Fort Lauderdale-West Palm Beach cluster specializes in international express flows through customs-bonded warehouse networks.
Illinois
Midwestern manufacturing supply chains and agricultural equipment distribution create B2B express demand through Chicago and Rockford hubs. The Illinois Environmental Protection Agency implements diesel emissions testing programs that filter older vehicles from state highway networks. The Chicago-Naperville-Elgin metro extends same-day coverage into secondary markets at lower fulfillment node real estate costs than coastal alternatives.
Ohio
Automotive parts logistics and healthcare distribution from Cleveland Clinic and Cincinnati Children's networks sustain express volume growth. The Ohio Environmental Protection Agency administers vehicle emissions programs that align with federal heavy-duty greenhouse gas standards. The Columbus metro emerges as a fulfillment node expansion target connecting East Coast and Midwest corridor networks.
US Express Delivery Market Competitive Landscape
The competitive structure tilts toward integrated national carriers with dense ground networks and dedicated air capacity. Three distinct archetypes occupy the field: legacy integrated carriers with freighter fleets and hub-and-spoke infrastructure, e-commerce-native logistics platforms with proprietary last-mile station networks, and regional specialists concentrating on high-yield B2B corridors. Consolidation pressure intensifies as capital requirements for fleet electrification and autonomous technology licensing favor scaled balance sheets over fragmented regional operations.
Within the integrated carrier tier, United Parcel Service and FedEx anchor national coverage through combined ground and air networks. Amazon Logistics occupies the e-commerce-native position with dense urban fulfillment station deployment. Regional specialists such as OnTrac and Lone Star Overnight exemplify corridor-focused strategies targeting premium B2B yields in Texas and Southwest markets. These three archetypes represent the structural options available to market participants navigating EPA Phase 3 compliance timelines and California CARB waiver requirements.
| Leading Market Players |
|---|
| United Parcel Service (UPS) |
| FedEx |
| United States Postal Service (USPS) |
| DHL Group |
| OnTrac |
| Amazon Logistics |
| Spee Dee Delivery Service |
| Lone Star Overnight (LSO) |
| Dropoff |
| Others |
Pricing and Supply Chain Analysis
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles gate qualified fleet supply and premium-tier pricing access for carriers demonstrating compliance ahead of federal timelines. California's Advanced Clean Trucks regulation further stratifies the market, forcing national operators to absorb elevated capital costs or cede volume to CARB-compliant competitors.
Pricing Analysis
Time-definite delivery guarantees anchor value-based pricing across same-day, next-day, and standard service tiers. Three-tier pricing structure across premium, standard, and economy levels reflects vehicle fleet composition, with zero-emission deployments commanding rate premiums. Cost compression in standard ground services is intensifying because e-commerce volume growth outpaces yield expansion. B2C residential delivery exhibits highest price sensitivity, while B2B pharmaceutical contracts retain inelastic demand for GDP-certified cold-chain handling.
Supply Chain Analysis
Hub-and-spoke distribution networks handle linehaul consolidation through depot-based dispatch systems feeding last-mile stations. Lithium-ion cell production concentrates in China, South Korea, and Japan, exposing carriers to input cost volatility and geopolitical sourcing risk. Electric vehicle powertrains, charging infrastructure, and battery management systems constitute critical component dependencies. Single-source vulnerability in Asian battery supply creates fleet deployment bottlenecks. Distribution runs through integrated ground networks with air express overlay for time-definite commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US express delivery market operates as a cost-of-compliance story where EPA Phase 3 standards and California CARB waivers erect barrier-to-entry moats favoring scaled operators with balance sheet capacity for accelerated fleet electrification.
For Market Incumbents: Extend zero-emission vehicle procurement timelines to capture CARB-compliant fleet pools before federal mandates tighten supply. Consolidate technician certification programs to address high-voltage powertrain maintenance scarcity that threatens fleet uptime. Defend against Amazon Logistics' station density expansion by locking long-term real estate in Texas-California-Florida corridor overlaps where same-day coverage radii achieve network effects.
For New Entrants and Emerging Players: FAA Part 135 certification progress in rural and suburban airspace opens a window for drone-native delivery platforms to bypass ground network capital intensity. Target Midwestern fulfillment node expansion in Ohio and Illinois where secondary market real estate costs undercut coastal density zones. Penetrate through specialized cold-chain contracts with pharmaceutical distributors prioritizing GDP-compliant infrastructure over speed metrics alone.
For Investors and Strategic Acquirers: Autonomous middle-mile pilot program announcements between distribution centers and last-mile facilities are the leading indicator that linehaul economics are shifting toward platform unification. Five-to-ten year viability favors operators with integrated ground-air networks and demonstrated compliance pathways through bifurcated state-federal regulatory landscapes. Acquisition target archetype: regional specialists with dense B2B corridor presence and established EPA Phase 3 compliance roadmaps. Monitor FAA beyond-visual-line-of-sight rulemaking progress as inflection signal for drone delivery scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Acceleration | EPA Phase 3 compliance locks in carrier competitive positioning ahead of federal enforcement timelines. |
| Autonomous Middle-Mile Deployment | Self-driving truck pilots between Arizona and Texas distribution centers unify fragmented linehaul economics. |
| Cold-Chain Infrastructure Certification | GDP-compliant temperature-assurance capabilities capture pharmaceutical distributor contract consolidation. |
| Drone Integration Under Part 135 | FAA beyond-visual-line-of-sight certification unlocks rural delivery economics previously unprofitable for ground networks. |
| Midwestern Fulfillment Node Expansion | Ohio and Illinois station deployment extends same-day coverage at lower real estate cost per square foot than coastal alternatives. |
Research Methodology
Multi-period observation of fleet electrification procurement timelines, e-commerce volume trajectories, and regulatory compliance milestones anchored the trend analysis, supplemented by interviews with fleet operations directors, pharmaceutical logistics procurement managers, EPA regulatory affairs specialists, and last-mile station network planners. Secondary validation drew from FMCSA hours-of-service enforcement data, FAA Part 135 certification filings, CARB waiver documentation, and carrier sustainability disclosures. Bottom-up segment sizing triangulated against top-down market value estimates.
Input-output matrices modeled volume and value flows across service type, customer type, delivery mode, and package type dimensions throughout the forecast period. CAGRs derived from logistic curve fitting to technology adoption S-cycles, with electric vehicle fleet penetration rates and autonomous middle-mile deployment timelines as industry-specific forecast inputs. Cross-segment elasticity captured substitution effects between same-day and next-day service tiers.
The model assumes a particular technology adoption path; alternative pathways for battery-electric versus renewable natural gas long-haul propulsion would alter the outlook for carrier capital allocation and infrastructure investment. Forecasts reflect assumptions regarding FAA drone integration rulemaking pace, utility interconnection timelines for depot electrification, and lithium-ion supply chain stability. Practitioners should monitor state-level zero-emission zone designations and battery supply contract announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Australia Mining Logistics Market