
 Global Navigation Beacon Buoys Market | 2026-2036
Global Navigation Beacon Buoys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Navigation Beacon Buoys Market Outlook
Marine equipment distribution through port authority procurement consortia is reconfiguring as centralized buying pools replace fragmented municipal tenders. Sealite leverages its solar LED specialization to anchor long-term service contracts with Australian and Southeast Asian harbor authorities. Xylem competes through integrated water analytics platforms that bundle buoy telemetry with broader port infrastructure monitoring.
Navigation beacon buoys are floating or fixed marine markers engineered with photometric output measured in candela, constructed from UV-stabilized polyethylene or steel hulls, and designed to transmit position, status, and environmental data to vessels and shore stations for safe channel transit. Smart buoys incorporating GPS and AIS transponders are capturing the fastest expansion as ports automate vessel traffic management and reduce manual inspection rounds. Solar buoy configurations dominate new installations where grid connectivity is absent, while radar-reflective fixed buoys retain stable replacement demand from legacy coastal networks.
The International Maritime Organization enforces SOLAS Convention visibility and color-coding standards that mandate minimum luminous range and battery autonomy for all commercial shipping lane markers. The EU Marine Strategy Framework Directive and national regulators such as the Norwegian Maritime Authority impose additional ecological compatibility requirements on buoy materials and mooring systems. Stakeholders must monitor how autonomous deployment models reshape capital-expenditure-to-operating-expenditure ratios and whether integrated platform offerings from water technology conglomerates squeeze standalone buoy specialists out of major port modernization programs.
Market Dynamics
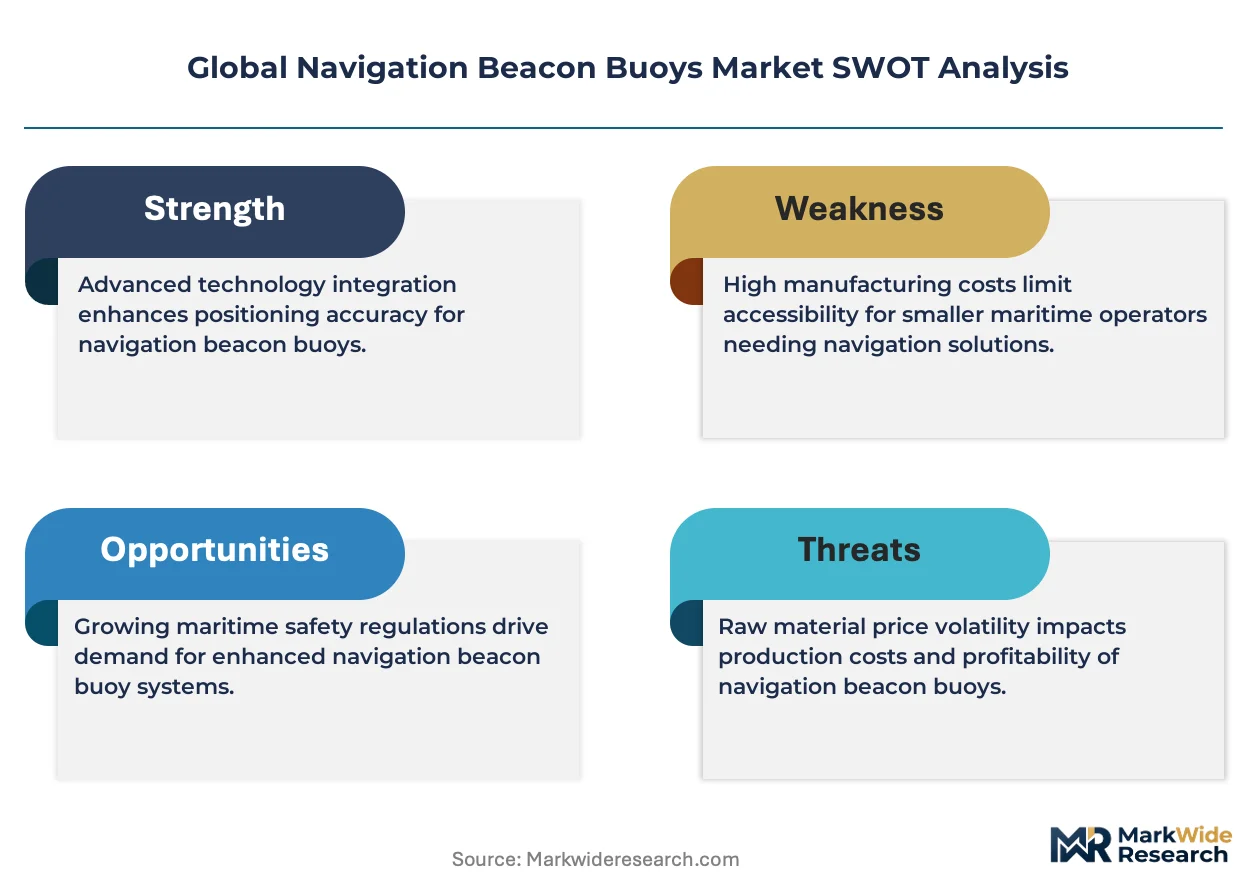
Offshore wind farm developers are consolidating procurement around smart beacon buoys with integrated AIS and GPS transponders, compressing replacement cycles for legacy marker systems and forcing standalone buoy manufacturers to bundle telemetry services or exit major port modernization tenders.
Growth Catalysts
- SOLAS Convention Updates:The International Maritime Organization's revised visibility standards mandate higher luminous range and extended battery autonomy, compelling port authorities across Norway and Japan to accelerate beacon replacement schedules.
- Offshore Wind Expansion:Developers in the North Sea corridor require precision-positioned smart buoys with real-time environmental monitoring to protect turbine arrays from vessel traffic.
- Solar LED Maturation:Photovoltaic-powered beacon systems now deliver multi-year autonomy without grid connection, unlocking deployment in remote archipelagos and Pacific island territories previously dependent on diesel generators.
Market Restraints
- Polymer Feedstock Volatility:UV-stabilized polyethylene hull production faces input cost pressure from ethylene derivative markets, squeezing margin structures for volume buoy fabricators.
- Mooring System Concentration:Specialized anchor and chain suppliers cluster in Scandinavian maritime engineering hubs, creating geographic single-source vulnerability for large-scale coastal modernization programs.
- Steel Hull Corrosion Limits:Traditional metal-construction buoys require cathodic protection and periodic dry-dock maintenance, elevating lifetime operating expenditure versus polymer alternatives.
Strategic Opportunities
- Japanese Coastal Modernization:METI-funded port automation initiatives create demand for integrated buoy-telemetry platforms that feed vessel traffic management systems with real-time positioning and sea-state data.
- Water Analytics Convergence:Buoy-mounted sensors for turbidity, salinity, and current velocity enable port authorities to bundle navigation safety with environmental compliance monitoring under single procurement contracts.
- Autonomous Deployment Models:Self-positioning buoy systems reduce installation vessel charter costs and shift capital expenditure toward subscription-based operating expenditure structures attractive to municipal harbor budgets.
Industry Challenges
- Photometric Calibration Expertise:Certified candela measurement and SOLAS compliance documentation require specialized optical engineering talent scarce outside established marine aids-to-navigation manufacturers.
- Legacy System Integration:Smart buoy telemetry protocols must interface with decades-old port radar and vessel traffic service architectures, extending commissioning timelines and elevating customization costs.
- Type-Approval Bottlenecks:National maritime authorities in Germany, South Korea, and Australia operate non-harmonized certification processes, fragmenting product validation pathways and delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Navigation Beacon Buoys Market |
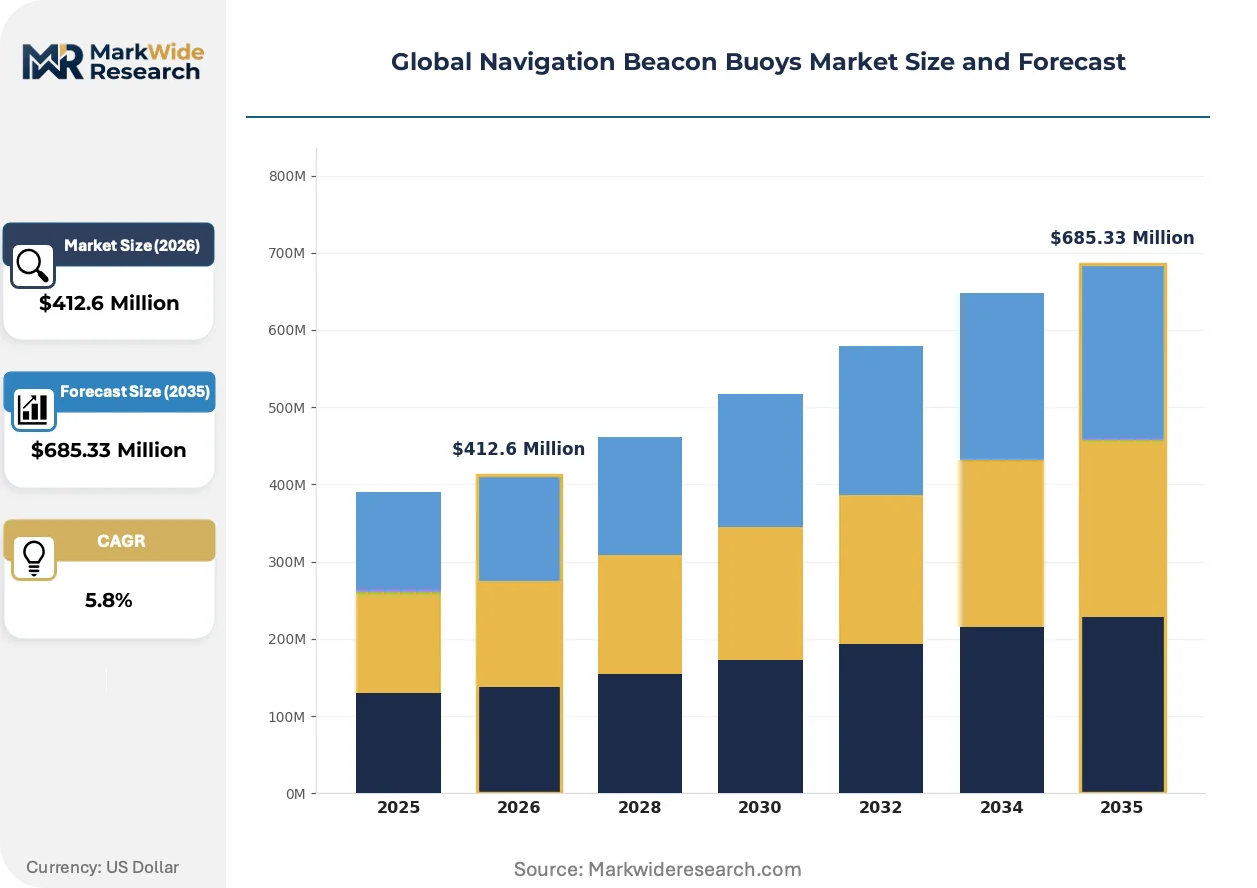
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Floating Buoys, Fixed Buoys, Smart Buoys, Solar Buoys Application: Marine Navigation, Research, Rescue Operations, Fishing Support Technology: GPS, AIS, Radar, Sonar Deployment Model: Autonomous, Remote Operated, Manual, Integrated |
| Companies Covered | Sealite, FenderCare, Xylem, Ryokuseisha, Meritaito, Resinex, Almarin, Mobilis, Carmanah Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Navigation Beacon Buoys Market Strategic Shifts
Digital positioning technologies and autonomous marine platforms are compressing the traditional boundary between navigation hardware and port infrastructure software, reshaping how beacon systems are specified, procured, and monetized.
Solid-state LED beacon arrays with programmable intensity profiles are rendering obsolete incandescent and halogen lamp assemblies that dominated marine aids-to-navigation for decades. Norwegian and Japanese port authorities now specify these systems as baseline requirements in tender documents. The technology is rendering obsolete the legacy maintenance model of scheduled lamp replacement and manual intensity verification.
REACH restrictions on heavy metals and persistent organic pollutants are compelling buoy manufacturers to reformulate hull coatings and battery chemistries across European installations. The regulation forces substitution of cadmium-based photovoltaic cells and certain anti-fouling paints in products destined for EU member state waters. Baltic Sea port authorities have moved fastest, with Stockholm and Copenhagen harbor boards now requiring full material disclosure documentation in procurement evaluations.
Consolidated buying pools organized through port authority associations are displacing fragmented municipal tender processes that historically governed beacon procurement. Australian harbor boards and Southeast Asian maritime clusters have pioneered centralized framework agreements that bundle buoy supply with decade-long telemetry service contracts. This concentration is most visible in Queensland and New South Wales, where Transport for NSW now manages navigation aid procurement for seventeen previously independent port facilities.
Global Navigation Beacon Buoys Market Segmentation
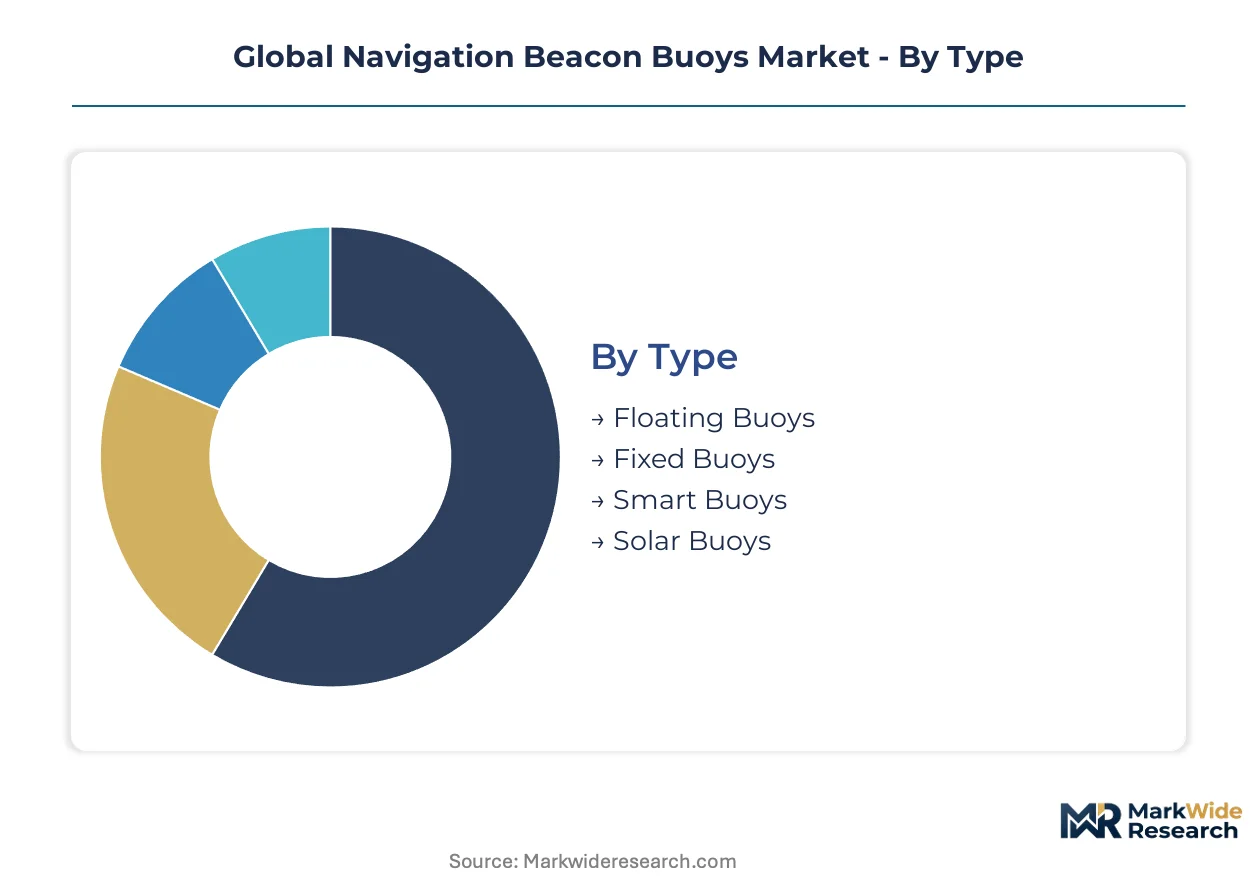
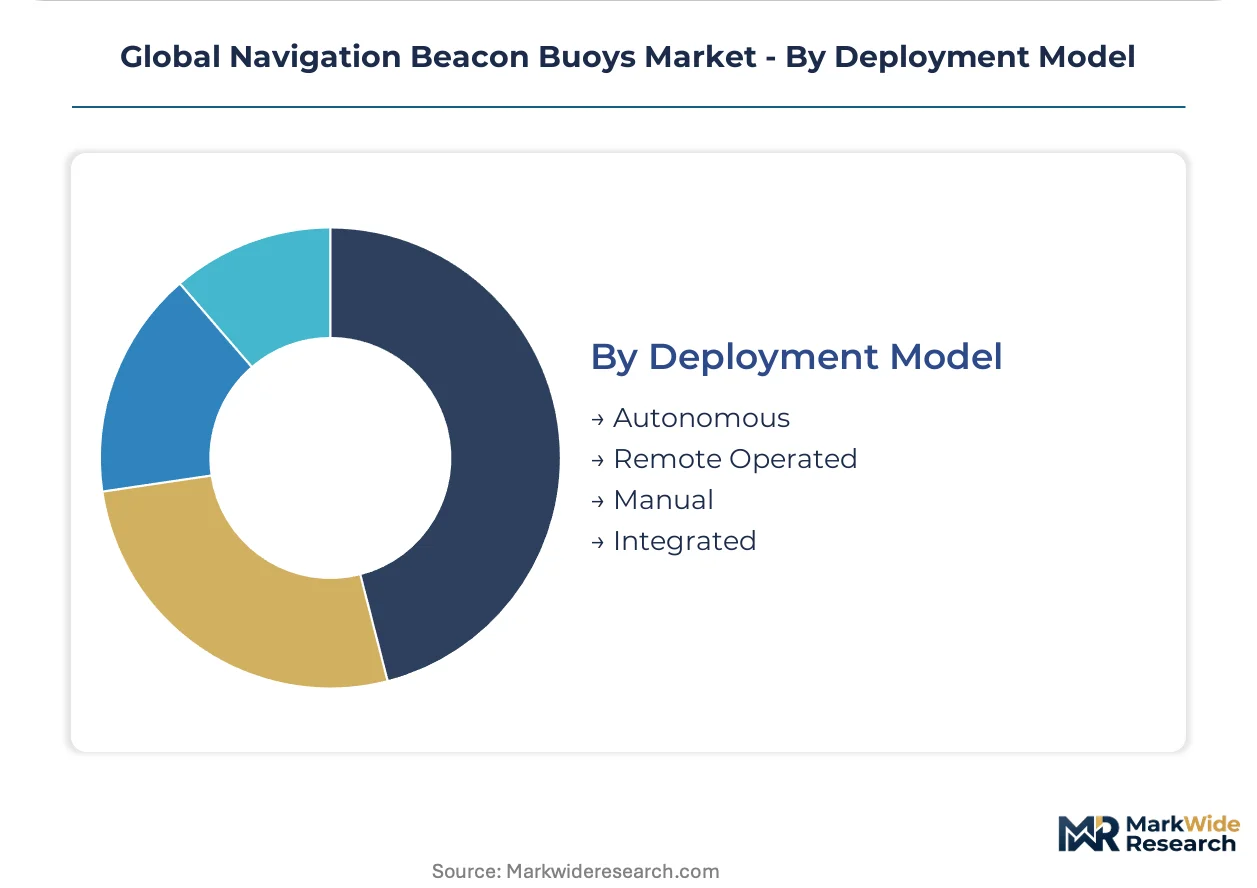
Beacon buoy procurement patterns diverge sharply across deployment contexts, with offshore wind developers favoring integrated telemetry platforms while coastal municipalities prioritize capital-efficient solar configurations. Understanding these segment boundaries clarifies where technology convergence accelerates and where legacy specifications persist.
Type:
Cost tier differentiation separates polymer-hull commodity supply from steel-construction premium positioning and smart-system subscription revenue models.
- Smart Buoys:GPS-AIS transponder integration enables real-time position reporting and automated vessel traffic coordination. Norwegian North Sea wind farm developers specify these for turbine array protection, compressing replacement cycles for legacy marker systems.
- Solar Buoys:Photovoltaic LED arrays deliver multi-year autonomy without shore power connection. Pacific island territories and remote archipelagos deploy these where diesel generator maintenance proves logistically prohibitive.
- Floating Buoys:UV-stabilized polyethylene hulls anchor in dynamic mooring configurations for channel marking and harbor entrance delineation.
- Fixed Buoys:Steel-construction permanent installations with cathodic protection serve legacy coastal networks requiring radar reflectivity.
Fixed buoys hold installed capacity. Smart buoys are rotating up the share rankings.
Application:
End-use concentration tracks maritime traffic density, with commercial shipping lanes commanding specification rigor that recreational or research deployments rarely require.
- Marine Navigation:SOLAS-mandated luminous range and color-coding standards govern commercial shipping lane markers. Japanese coastal modernization programs and Australian harbor authority consortia drive specification upgrades here.
- Rescue Operations:Rapid-deployment beacon systems support search-and-rescue coordination with strobe intensity profiles optimized for helicopter visibility.
- Research:Oceanographic sensor platforms combine positioning telemetry with turbidity, salinity, and current velocity measurement.
- Fishing Support:Cost-optimized marker buoys delineate gear boundaries and marine protected area perimeters for artisanal fleet coordination.
Marine navigation absorbs the dominant procurement volume. Research applications are climbing the fastest.
Technology:
Integration depth determines whether beacon systems operate as standalone hardware or feed unified port infrastructure platforms.
- AIS:Automatic Identification System transponders broadcast vessel-position data to shore stations and neighboring ships. Offshore wind developers mandate AIS integration for turbine array proximity alerting.
- GPS:Satellite positioning enables sub-meter location accuracy for precision channel marking and dynamic repositioning.
- Radar:Passive radar reflectors and active radar beacons serve legacy vessel traffic service architectures.
- Sonar:Underwater acoustic positioning supports subsea construction and pipeline route marking.
GPS holds baseline penetration. AIS is rotating up the share rankings.
Deployment Model:
Capital-to-operating-expenditure ratios shift dramatically across installation methodologies, reshaping how port authorities budget navigation infrastructure.
- Autonomous:Self-positioning buoy systems reduce installation vessel charter costs through robotic deployment and retrieval. Municipal harbor budgets favor subscription-based structures that shift capital expenditure to operating expenditure.
- Integrated:Bundled telemetry service contracts spanning decade-long terms consolidate buoy supply with maintenance and data analytics.
- Remote Operated:Tethered or radio-controlled systems enable repositioning without physical vessel intervention.
- Manual:Traditional crane-vessel installation and scheduled inspection rounds persist in budget-constrained jurisdictions.
Manual deployment holds residual volume. Autonomous systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian port authorities command 15-20% price premiums over Southeast Asian tenders for SOLAS-certified smart buoy systems. Japanese coastal municipalities absorb comparable premiums for integrated telemetry platforms. Australian harbor boards consolidate procurement through centralized frameworks that compress margins for standalone fabricators.
Norway
North Sea offshore wind developers drive demand for GPS-AIS integrated buoys protecting turbine arrays. The Norwegian Maritime Authority enforces supplementary ecological compatibility requirements on mooring systems. Bergen and Stavanger engineering clusters host specialized anchor and chain suppliers serving corridor modernization projects.
Japan
METI-funded port automation initiatives accelerate beacon replacement schedules across coastal municipalities. The country's national maritime regulator mandates extended battery autonomy under updated SOLAS implementation guidelines. Osaka Bay and Tokyo Bay harbor boards specify integrated buoy-telemetry platforms feeding vessel traffic management systems.
Australia
Queensland and New South Wales harbor authorities pioneer centralized framework agreements bundling buoy supply with decade-long service contracts. Transport for NSW now manages navigation aid procurement for seventeen previously independent port facilities. Sydney and Brisbane maritime clusters concentrate solar LED specialization among local service providers.
Germany
Baltic Sea port authorities require full material disclosure documentation under REACH-implementing regulations. The country's federal maritime administration operates non-harmonized type-approval processes that fragment product validation pathways. Hamburg and Rostock harbor boards lead Stockholm and Copenhagen in cadmium-free photovoltaic cell specifications.
United States
Pacific island territories and remote Alaskan installations deploy solar configurations where diesel generator maintenance proves logistically prohibitive. The Coast Guard maintains legacy radar-reflective fixed buoy networks requiring periodic replacement. Seattle and Honolulu maritime engineering offices specify multi-year autonomous systems for Arctic and Pacific deployments.
Global Navigation Beacon Buoys Market Competitive Environment
Marine aids-to-navigation specialists and integrated water technology conglomerates split the market between hardware-centric and platform-centric value capture. Consolidated buying pools organized through port authority associations favor vendors offering decade-long telemetry service contracts over standalone buoy fabricators. Three strategic archetypes dominate: solar LED specialists anchoring long-term harbor authority relationships, water analytics platforms bundling buoy telemetry with broader infrastructure monitoring, and regional engineering houses controlling mooring system supply. Competitive moves concentrate on backward integration into photovoltaic cell supply and geographic expansion through port authority framework agreements.
Among the named players in this study, Sealite exemplifies the solar LED specialist archetype through its Australian origin and harbor authority focus. Xylem occupies a position representing integrated water technology conglomerates competing through platform bundling. Carmanah Technologies Corporation anchors the North American technology integration tier. These three entities illustrate how vendor origin and corporate structure shape competitive positioning without specifying individual strategic actions or market shares.
| Leading Market Players |
|---|
| Sealite |
| FenderCare |
| Xylem |
| Ryokuseisha |
| Meritaito |
| Resinex |
| Almarin |
| Mobilis |
| Carmanah Technologies Corporation |
| Others |
Value Chain & Pricing Dynamics
North Sea freight corridors connecting Norwegian engineering clusters to Baltic installation sites impose vessel charter cost premiums that cascade through smart buoy pricing, concentrating margin pressure on fabricators lacking captive mooring component supply while enabling integrated suppliers to capture customization premiums from offshore wind developers.
Pricing Analysis
The customization-premium spread between configured-to-order smart buoys and standard solar LED units spans roughly 40-60 percent, with SOLAS certification grade and telemetry integration depth as primary differentiation drivers. Subscription-based service contracts bundling decade-long maintenance shift transactional hardware pricing toward recurring revenue models favored by Australian harbor authority consortia. Price erosion runs through commodity polymer-hull segments as Chinese and Southeast Asian fabricators expand export capacity, while Japanese and Norwegian port authorities show lowest price sensitivity due to METI and Norwegian Maritime Authority mandates for extended battery autonomy and ecological compatibility.
Supply Chain Analysis
Supplier-financing facilities extended by Scandinavian anchor and chain specialists to Norwegian and German port contractors have compressed payment cycles from 90 to 60 days, tightening working capital requirements for buoy assemblers. Manufacturing concentrates in Norway, Germany, and China, with UV-stabilized polyethylene feedstock and photovoltaic cell supply drawing from petrochemical complexes in Northeast Asia. Single-source vulnerability clusters around Bergen and Stavanger mooring system engineering, while distribution runs through centralized procurement frameworks pioneered by Australian state transport authorities and emerging Japanese coastal municipality consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification regimes and deployment methodologies creates specialist niches as consolidated buying pools displace fragmented municipal tenders, rewarding vendors with decade-long service contract capabilities.
For Market Incumbents: Pre-empt platform bundling moves by water technology conglomerates through backward integration into photovoltaic cell supply and captive mooring component production. Sealite's solar LED specialization and Australian harbor authority relationships demonstrate how regional service density defends position against Xylem-scale analytics platforms. Certification investment in Japanese and Australian type-approval pathways locks out later entrants.
For New Entrants and Emerging Players: Establish a beachhead in Pacific island territory solar buoy deployments where diesel generator logistics complexity deters incumbent volume players. Autonomous deployment subscription models offer lowest competitive density, with municipal harbor budgets in Queensland and New South Wales showing appetite for operating-expenditure structures. Partner with regional engineering houses controlling anchor supply to bypass Scandinavian single-source bottlenecks.
For Investors and Strategic Acquirers: Telemetry-integrated mid-tier specialists with proven AIS-GPS platform integration and existing port authority framework agreements represent the most defensible acquisition archetype. Long-term viability hinges on water analytics convergence trends across the analysis window. Watch for Japanese METI funding acceleration and Norwegian North Sea wind farm procurement consolidation as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photovoltaic Supply | Captive solar cell production insulates margin from ethylene derivative volatility affecting polyethylene hull costs. |
| Framework Agreement Expansion | Transport for NSW-style centralized procurement consolidation across Australian and Southeast Asian harbor authorities locks in decade-long revenue visibility. |
| Autonomous Deployment Platform Development | Self-positioning buoy systems reduce installation vessel charter costs and shift capital expenditure toward subscription structures attractive to municipal budgets. |
| REACH-Compliant Material Reformulation | Cadmium-free photovoltaic specifications and anti-fouling paint substitution satisfy Stockholm and Copenhagen harbor board procurement requirements. |
| Telemetry Service Bundling | Integrated buoy-telemetry platforms feeding vessel traffic management systems capture specification mandates from Osaka Bay and Tokyo Bay harbor boards. |
Study Parameters
Operator-level perspectives from port authority procurement directors, offshore wind farm development engineers, maritime aids-to-navigation manufacturers, and harbor maintenance contractors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through IMO SOLAS implementation guidelines, national maritime authority type-approval databases, and EU REACH regulatory filings. Customs trade data on UV-stabilized polyethylene and photovoltaic cell imports, alongside SEC filings from listed water technology conglomerates, provided quantitative grounding. Bottom-up segment sizing triangulated against top-down macroeconomic anchoring.
Scenario-bracketing across conservative, baseline, and expansion cases informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include buoy type, application context, technology integration depth, and deployment methodology, with regional regulatory cluster and port authority procurement structure as additional cross-cutting variables. CAGRs derived from fitted growth curves applied to base-year estimates, with offshore wind installation pipeline data and SOLAS replacement cycle schedules as industry-specific forecast inputs.
Stress conditions across polymer feedstock cost volatility, mooring system supply disruption, and type-approval timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pace and technology adoption curves. Macroeconomic contraction, accelerated autonomous deployment disruption, or harmonized international certification breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Passenger Ferries Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market