
 Lauramidopropyl Betaine Market | 2026-2036
Lauramidopropyl Betaine Market Size, Share, and Industry Trends Forecast 2026-2036
Lauramidopropyl Betaine Market Intelligence
The gap between premium cosmetic-grade Lauramidopropyl Betaine and commodity industrial grades is realigning procurement strategies across the value chain. BASF SE leverages its integrated oleochemicals platform to secure backward integration into lauric acid feedstocks. Croda International differentiates through RSPO-certified supply chains that anchor its position in clean-label personal care. Evonik Industries competes on R&D intensity in mild surfactant formulations for sensitive-skin applications.
Lauramidopropyl Betaine is an amphoteric surfactant synthesized from lauric acid and dimethylaminopropylamine, typically supplied at active concentrations of 30-35% in aqueous solution with a pH range of 4.5-7.5, functioning primarily as a foam booster, viscosity builder, and mildness enhancer in rinse-off formulations. The liquid product type dominates volume due to its ease of handling in continuous manufacturing processes, while paste variants command margin premiums in premium personal care compounding. Application demand in personal care leads value generation, though industrial cleaning applications sustain steady offtake from institutional buyers seeking low-irritancy profiles.
REACH registration requirements in Europe, EPA Safer Choice criteria in the United States, and China's GB standards for cosmetic raw materials collectively shape formulation choices and market access conditions for Lauramidopropyl Betaine suppliers. ECHA's scrutiny of 1,4-dioxane impurities in ethoxylated surfactants is redirecting formulator preference toward amphoteric alternatives with cleaner toxicological profiles. Stakeholders must monitor regulatory tightening on biodegradability thresholds and carbon intensity disclosures, as these criteria will determine which production assets retain commercial viability.
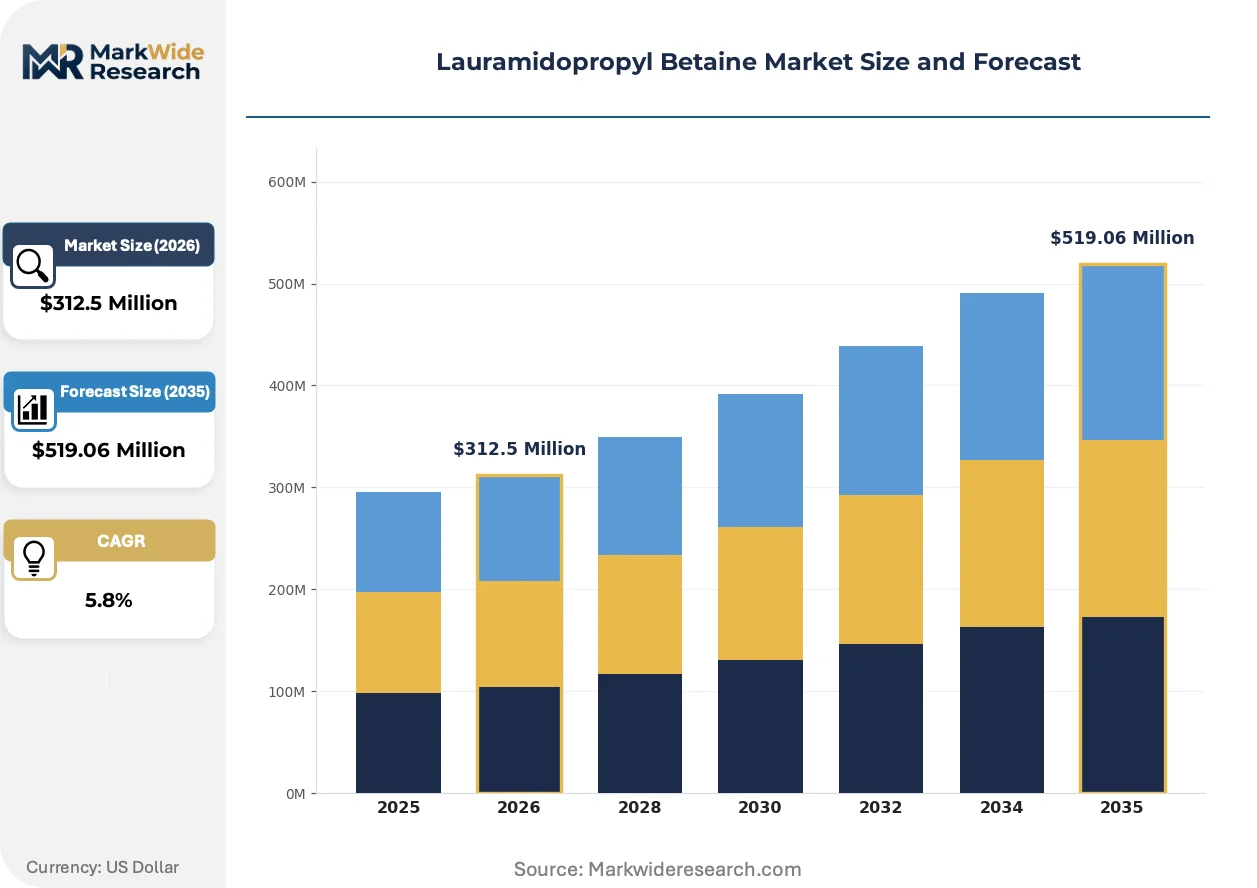
Market Dynamics
The Lauramidopropyl Betaine market is restructuring around REACH-driven substitution of ethoxylated surfactants, with ECHA's 1,4-dioxane scrutiny forcing formulators toward amphoteric alternatives that carry cleaner toxicological profiles and simpler regulatory dossiers.
Growth Catalysts
- Sulfate-free formulation mandates:Personal care brands in Germany and France are eliminating sodium lauryl sulfate from rinse-off products, creating immediate pull for Lauramidopropyl Betaine as a mildness-enhancing foam booster in shampoo and body wash applications.
- EU Green Deal compliance frameworks:The European Commission's carbon intensity disclosure requirements for chemical imports are favoring bio-based amphoteric surfactants with certified sustainable palm kernel oil feedstocks over petroleum-derived alternatives.
- Industrial cleaning safety protocols:Institutional buyers across healthcare and food service sectors are adopting low-irritancy surfactant systems to meet OSHA exposure limits and reduce workers' compensation liability.
Market Restraints
- Lauric acid feedstock volatility:Coconut and palm kernel oil price swings in Southeast Asian producing regions transmit directly to Lauramidopropyl Betaine manufacturing economics, compressing margin predictability for non-integrated compounders.
- Dimethylaminopropylamine supply concentration:This critical intermediate concentrates among a handful of Asian petrochemical producers, creating single-source vulnerability for European and North American surfactant manufacturers.
- Cocamidopropyl betaine substitution:The established amphoteric surfactant retains formulation familiarity and slightly lower unit costs in mass-market personal care, slowing premium-grade Lauramidopropyl Betaine penetration in price-sensitive segments.
Strategic Opportunities
- Chinese GB standard alignment:Cosmetic raw material regulations under NMPA are tightening purity and impurity specifications, creating entry windows for suppliers with pre-validated analytical packages against European pharmacopeial standards.
- Sensitive-skin pharmaceutical channels:Dermatological skincare lines targeting atopic dermatitis and pediatric applications are specifying ultra-low-impurity amphoteric surfactants, commanding formulation premiums unavailable in commodity personal care.
- Biodegradability certification leverage:The OECD 301B ready biodegradability test is becoming a procurement filter for institutional cleaning contracts, rewarding producers with pre-certified environmental fate data.
Industry Challenges
- RSPO Mass Balance audit complexity:Maintaining certified sustainable supply chain documentation across multiple toll manufacturers requires dedicated compliance personnel and IT systems that mid-scale producers often lack.
- Analytical method harmonization:Discrepancies between ECHA dossier requirements, EPA Safer Choice criteria, and Chinese GB testing protocols force redundant stability and impurity studies, extending product registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lauramidopropyl Betaine Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paste, Liquid, Powder, Granules Application: Personal Care, Household Cleaning, Industrial Cleaning, Agricultural End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Offline, Wholesale, Direct Sales |
| Companies Covered | BASF SE, Croda International, Evonik Industries, Solvay, Clariant, Kao Corporation, Stepan Company, Lubrizol, Kawaken Fine Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lauramidopropyl Betaine Market Strategic Shifts & Innovations
Formulation science and procurement patterns are diverging simultaneously. Technology is fragmenting production platforms while buyers consolidate supplier relationships, creating tension between customization economies and scale efficiency.
Enzymatic interesterification of lauric acid feedstocks is modularizing the upstream oleochemical value chain. Specialty chemical producers in Germany and the Netherlands are adopting these biocatalytic routes to reduce energy intensity and improve carbon footprint metrics for EU Green Deal reporting. The technology is modularizing how mid-scale compounders access certified sustainable feedstocks without captive plantation assets.
REACH registration dossier updates are compressing the acceptable impurity profile for amphoteric surfactants in European cosmetic applications. ECHA's consolidated screening assessment for 1,4-dioxane precursors is forcing reformulation away from ethoxylated intermediates toward direct amidation chemistries. German personal care formulators are responding by specifying Lauramidopropyl Betaine grades with sub-5 ppm 1,4-dioxane certificates of analysis.
Direct raw material sourcing from oleochemical producers is displacing traditional distributor intermediaries in North American procurement. Large personal care manufacturers are establishing annual volume contracts with Malaysian and Indonesian palm kernel oil fractionators, then toll-manufacturing Lauramidopropyl Betaine through contracted surfactant houses. This pattern is most visible among California-based clean beauty brands seeking supply chain transparency for Prop 65 compliance marketing.
Lauramidopropyl Betaine Market Segmentation
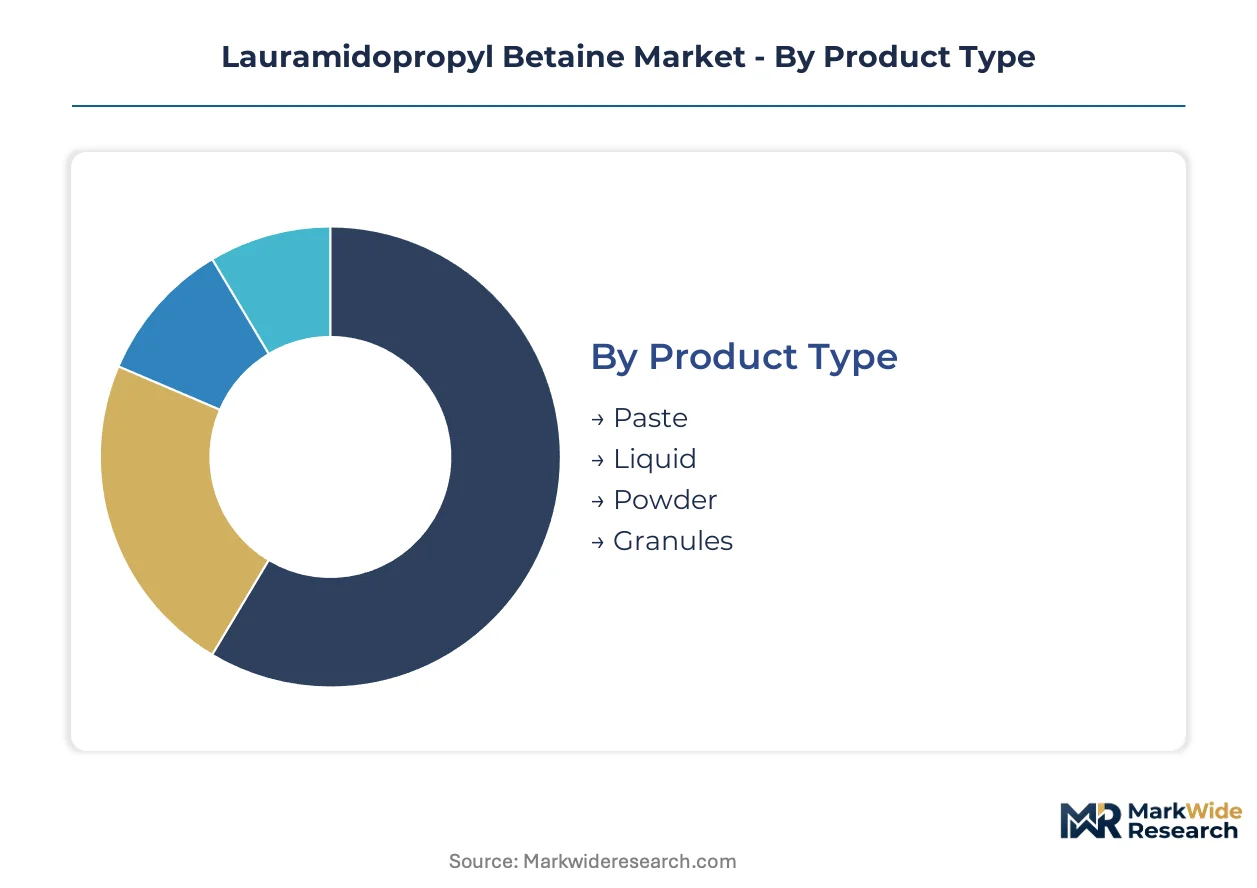
Lauramidopropyl Betaine procurement patterns diverge sharply across physical forms and downstream channels. Formulators select product types based on manufacturing equipment compatibility, while application-specific purity requirements create tiered supply relationships.
Product Type:
Upgrade cycles in continuous manufacturing equipment favor liquid formats, while batch compounding operations retain flexibility for paste and solid variants.
- Liquid:Supplied at 30-35% active concentration in aqueous solution with pH 4.5-7.5, liquid Lauramidopropyl Betaine integrates directly into automated shampoo and body wash production lines. Personal care manufacturers in Germany specify this format for sulfate-free formulation runs where viscosity building and foam boosting must occur without additional processing steps.
- Paste:Higher active content paste grades command formulation premiums in premium personal care compounding where concentrated mildness enhancers reduce water content in finished products. Specialty chemical distributors in France stock paste variants for boutique cosmetic brands seeking differentiated texture profiles in rinse-off applications.
- Powder:Solid-state Lauramidopropyl Betaine serves industrial cleaning compounders requiring extended shelf stability and reduced shipping weights for institutional contract deliveries.
- Granules:Free-flowing granular forms suit agricultural adjuvant manufacturers blending tank-mix surfactants for crop protection formulations.
Liquid sits at the top of the volume ranking, with paste climbing the fastest.
Application:
Cost tier differentiation separates pharmaceutical-grade specifications from commodity industrial contracts.
- Personal Care:Sulfate-free shampoo and body wash formulators specify sub-5 ppm 1,4-dioxane certificates of analysis to meet ECHA screening assessment requirements. German premium cosmetic brands anchor demand here through RSPO-certified supply chain mandates.
- Household Cleaning:Low-irritancy laundry and dish formulations for sensitive-skin positioning drive specification of amphoteric surfactants with documented OECD 301B biodegradability.
- Industrial Cleaning:Healthcare and food service institutional buyers adopt Lauramidopropyl Betaine to comply with OSHA exposure limits and reduce workers' compensation liability in high-frequency cleaning protocols.
- Agricultural:Tank-mix adjuvant formulators leverage amphoteric surfactant mildness profiles for crop protection products requiring reduced phytotoxicity in foliar applications.
Personal Care generates the highest value per kilogram, with Industrial Cleaning expanding most quickly on safety protocol adoption.
End User:
Customer type determines specification depth and certification burden.
- Manufacturers:Personal care and cleaning product compounders drive bulk volume through annual volume contracts with direct oleochemical sourcing arrangements.
- Retailers:Clean beauty retailers in California specify supply chain transparency documentation for Prop 65 compliance marketing to conscious consumers.
- Distributors:Regional chemical distributors maintain inventory positions across multiple concentration grades to serve mid-scale formulators without direct supplier relationships.
- Consumers:DIY cosmetic ingredient suppliers represent a niche channel for hobbyist formulators seeking small-quantity amphoteric surfactants.
Manufacturers dominate procurement volume, with Retailers gaining share fastest on clean-label positioning requirements.
Distribution Channel:
Supply concentration among Malaysian and Indonesian palm kernel oil fractionators reshapes channel economics.
- Direct Sales:Large personal care manufacturers establish annual contracts with oleochemical producers, then toll-manufacture through contracted surfactant houses to secure supply chain transparency.
- Wholesale:Institutional cleaning buyers purchase through chemical distributors offering blended surfactant systems and technical formulation support.
- Online:Specialty chemical marketplaces serve small-batch cosmetic formulators requiring certified sustainable grades without minimum order quantities.
- Offline:Traditional distributor relationships persist in industrial cleaning segments where technical service and local inventory matter more than price transparency.
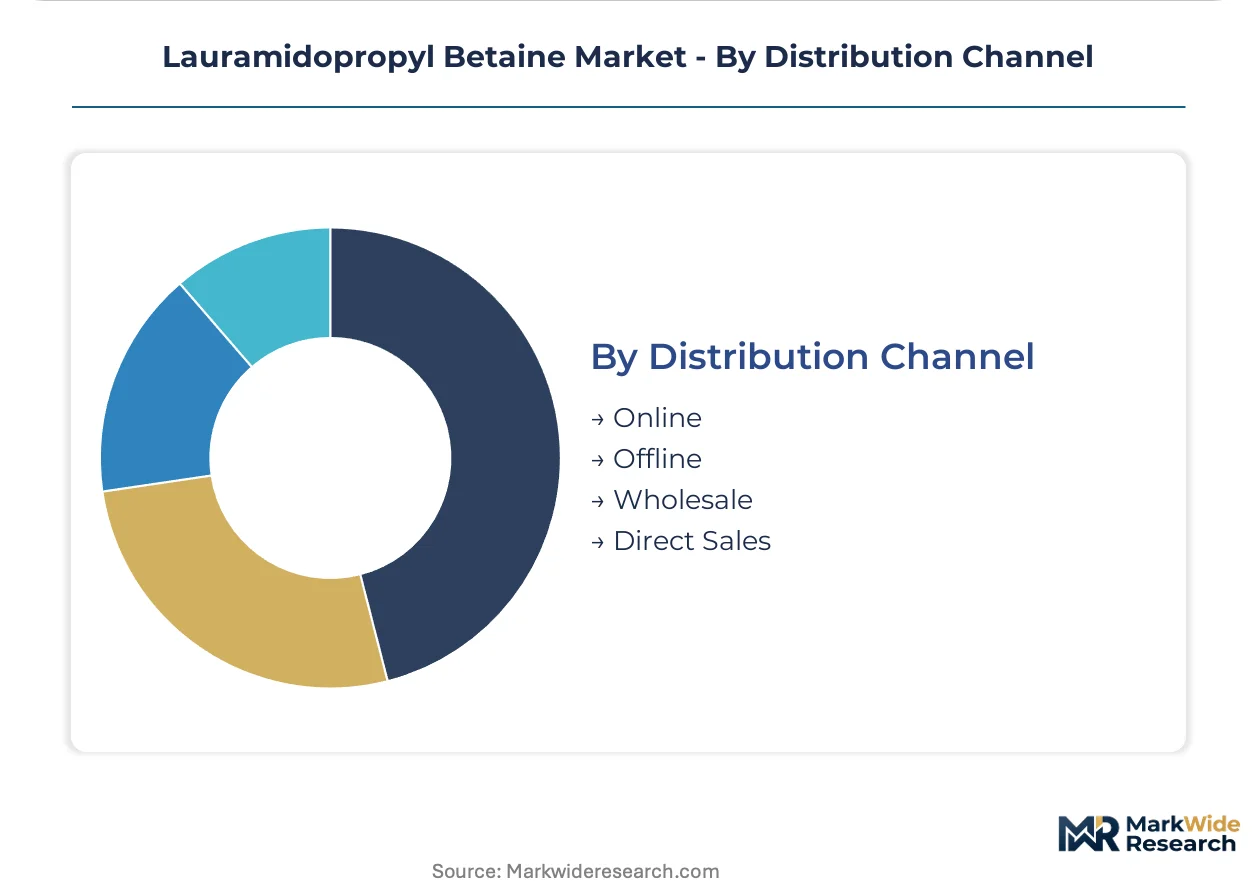
Direct Sales anchors volume leadership, with Online channels showing the steepest expansion trajectory on clean beauty ingredient access democratization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German formulators and Dutch oleochemical engineers anchor European technical leadership in amphoteric surfactant applications. Southeast Asian plantation managers and Malaysian fractionation specialists control upstream lauric acid flows. California clean beauty chemists and New York regulatory affairs professionals shape North American specification trends.
Germany
Specialty chemical producers in North Rhine-Westphalia serve premium cosmetic brands with RSPO-certified supply chains. REACH and EU Green Deal compliance requirements push manufacturers toward bio-based amphoteric surfactant alternatives. BASF SE leverages its integrated Ludwigshafen oleochemicals platform to secure backward integration into lauric acid feedstocks for domestic formulators.
United States
California-based clean beauty brands establish direct sourcing contracts with Malaysian palm kernel oil fractionators for Prop 65 compliance marketing. EPA Safer Choice criteria shape formulation choices for institutional cleaning buyers seeking low-irritancy profiles. Stepan Company maintains manufacturing positions in Illinois and Texas to serve domestic personal care compounders with regional supply security.
China
Cosmetic raw material regulations under NMPA tighten purity and impurity specifications for imported amphoteric surfactants. Yangtze River Delta formulators specify Lauramidopropyl Betaine grades with pre-validated analytical packages against European pharmacopeial standards. Kawaken Fine Chemicals operates production assets serving domestic sulfate-free shampoo manufacturers expanding mild surfactant systems.
Netherlands
Rotterdam-area toll manufacturers adopt enzymatic interesterification technologies to reduce energy intensity for EU Green Deal carbon reporting. Dutch distributors maintain inventory positions across multiple concentration grades to serve mid-scale European formulators without direct supplier relationships. ECHA's 1,4-dioxane scrutiny redirects local formulator preference toward direct amidation chemistries with cleaner toxicological profiles.
Japan
Kao Corporation anchors domestic demand through integrated personal care brands specifying ultra-low-impurity amphoteric surfactants for sensitive-skin applications. METI guidelines on chemical substance management influence procurement filters for institutional cleaning contracts requiring OECD 301B biodegradability certification. Osaka-based formulators concentrate on dermatological skincare lines targeting atopic dermatitis and pediatric segments.
Lauramidopropyl Betaine Market Key Industry Players
Capital-heavy producers compete with asset-light designers across differentiated positioning vectors. Integrated oleochemical majors with captive plantation assets and fractionation capacity battle independent surfactant houses reliant on spot feedstock markets. Three archetypes dominate: backward-integrated chemical conglomerates controlling upstream lauric acid supply, specialty surfactant specialists competing on RSPO certification and purity grades, and regional toll manufacturers serving local formulators with customized concentration blends. Competitive moves concentrate on strategic partnerships with cosmetic brands for supply chain transparency marketing and capacity expansion in Southeast Asian feedstock zones.
Among European-based integrated producers, BASF SE exemplifies the conglomerate archetype with oleochemical platform control, while Croda International occupies a position representing specialty certification leadership. Evonik Industries anchors the R&D-intensive tier focused on mild surfactant formulations. These three names illustrate how competitive positioning fragments across feedstock security, sustainability credentials, and technical formulation depth rather than converging on single-axis scale advantages.
| Leading Market Players |
|---|
| BASF SE |
| Croda International |
| Evonik Industries |
| Solvay |
| Clariant |
| Kao Corporation |
| Stepan Company |
| Lubrizol |
| Kawaken Fine Chemicals |
| Others |
Cost & Logistics Intelligence
Specialized oleochemical process engineers concentrated in Germany's North Rhine-Westphalia and the Netherlands' Rotterdam corridor command wage premiums that propagate through three-tier pricing spreads separating RSPO-certified pharmaceutical grades from commodity industrial lots.
Pricing Analysis
Bundled certification-and-testing packages versus unbundled base-material supply splits the pricing architecture for Lauramidopropyl Betaine. Three-tier pricing structure across premium, standard, and economy levels tracks RSPO Mass Balance documentation depth and 1,4-dioxane impurity thresholds. Cost compression in standard grades is intensifying because dimethylaminopropylamine supply bottlenecks from Asian petrochemical producers transmit feedstock volatility. Mass-market personal care compounders exhibit highest price sensitivity; dermatological skincare brands purchasing ultra-low-impurity pharmaceutical grades show lowest elasticity.
Supply Chain Analysis
Direct-to-manufacturer channels handle large personal care compounder demand, while wholesale distributors serve mid-scale institutional cleaning buyers. Supply concentrates in Malaysia, Indonesia, and Germany—Malaysian and Indonesian fractionators control lauric acid feedstocks, while German integrated producers command downstream amidation capacity. Manufacturing draws from coconut oil, palm kernel oil, and dimethylaminopropylamine inputs. Single-source vulnerability around dimethylaminopropylamine intermediates from concentrated Asian producers constitutes the dominant structural risk. Distribution runs through annual volume contracts with toll-manufacturing arrangements displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's 1,4-dioxane screening assessment mandates are forcing immediate formulation switches toward cleaner amphoteric surfactant alternatives.
For Market Incumbents: Lock in backward integration into lauric acid feedstocks through Malaysian and Indonesian fractionator partnerships before feedstock volatility worsens. Secure RSPO Mass Balance certification infrastructure now, as mid-scale competitors lack compliance personnel to match audit complexity. Prioritize R&D investment in enzymatic interesterification to reduce carbon intensity metrics for EU Green Deal reporting. For New Entrants and Emerging Players: Launch via online specialty chemical marketplaces serving California clean beauty brands seeking small-quantity certified sustainable grades without minimum order barriers. Target Chinese cosmetic formulators facing NMPA purity tightening by offering pre-validated European pharmacopeial analytical packages. Pursue toll-manufacturing partnerships with Rotterdam-area producers rather than greenfield capacity builds. For Investors and Strategic Acquirers: Specialty chemical conglomerates seeking surfactant platform expansion are the most active acquirer in this space. Long-term viability hinges on feedstock security and certification infrastructure rather than scale alone. Monitor RSPO Mass Balance audit pass rates as the inflection signal—falling certification success rates indicate tightening supply of compliant acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstocks | Captive lauric acid supply from Malaysian fractionators insulates margin from palm kernel oil price swings. |
| RSPO Mass Balance Certification | Certified sustainable supply chains unlock premium pricing from German cosmetic brands under EU Green Deal. |
| Enzymatic Interesterification Adoption | Biocatalytic routes reduce energy intensity for Rotterdam toll manufacturers' carbon disclosure requirements. |
| Direct-to-Manufacturer Distribution | Annual contracts with oleochemical producers displace distributor intermediaries for California clean beauty supply chains. |
| Ultra-Low-Impurity Grade Development | Sub-5 ppm 1,4-dioxane certificates access dermatological skincare premiums for atopic dermatitis applications. |
Research Approach
Bottom-up personal care and industrial cleaning formulation modeling reconciled against top-down lauric acid feedstock and surfactant production tracking forms the analytical core of this study. Primary interviews with plant managers at European oleochemical facilities, procurement leads at German cosmetic brands, technical R&D directors at specialty surfactant houses, and distribution channel partners in the Netherlands were cross-validated against secondary sources including ECHA registration dossiers, EU trade statistics, SEC filings from listed chemical producers, and RSPO supply chain certification databases.
Historical trendline analysis of lauric acid derivative pricing and amphoteric surfactant trade flows established baseline growth patterns. The projection framework segments by product type, application end-use, grade certification tier, and regional production hub, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements. Key inputs include REACH regulatory timeline assumptions, EU Green Deal carbon intensity disclosure trajectories, and NMPA cosmetic raw material standard evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained palm kernel oil price volatility or dimethylaminopropylamine supply disruptions. Projections reflect documented assumptions regarding regulatory enforcement intensity and certification adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Polyoxin Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Acetyl Tyrosine Market