
 Silicone Masterbatches Market | 2026-2036
Silicone Masterbatches Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Masterbatches Market Outlook
Specialty chemical producers in Germany and the United States is realigning capacity toward high-consistency silicone compounds for masterbatch integration. Dow leverages backward integration into siloxane feedstocks to secure cost positions across additive masterbatch lines. Wacker Chemie AG anchors its competitiveness through dedicated compounding facilities serving European automotive tiers. Shin-Etsu Chemical Co., Ltd. dominates ultra-high molecular weight silicone gum supply for premium filler masterbatch formulations.
Silicone masterbatches are concentrated dispersions of silicone polymers, oils, or resins within thermoplastic or elastomeric carrier matrices, typically processed via twin-screw extrusion or internal batch mixing to achieve uniform additive distribution at loadings of 5–50%. These formulations impart surface lubricity, flame retardancy, or processing aid functionality to host polymers in extrusion and molding operations. Additive masterbatch commands margin premiums due to specialized performance claims in automotive and electronics grades, while filler masterbatch sustains volume leadership in commodity packaging applications. Plastics processing absorbs the dominant share of silicone masterbatch offtake, though coatings applications are gaining traction as architectural and industrial formulations seek mar resistance and weatherability.
EPA regulations on volatile organic compound emissions from polymer processing constrain solvent-based carrier systems and favor melt-compounded silicone dispersions. REACH substance restrictions and the EU F-Gas Regulation shape silicone fluid selection and crosslinker chemistry for European market access. BIS certification requirements in India and GB standards in China add compliance layers for imported masterbatch formulations. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these intersect with silicone additive portfolios in food-contact and textile end uses.
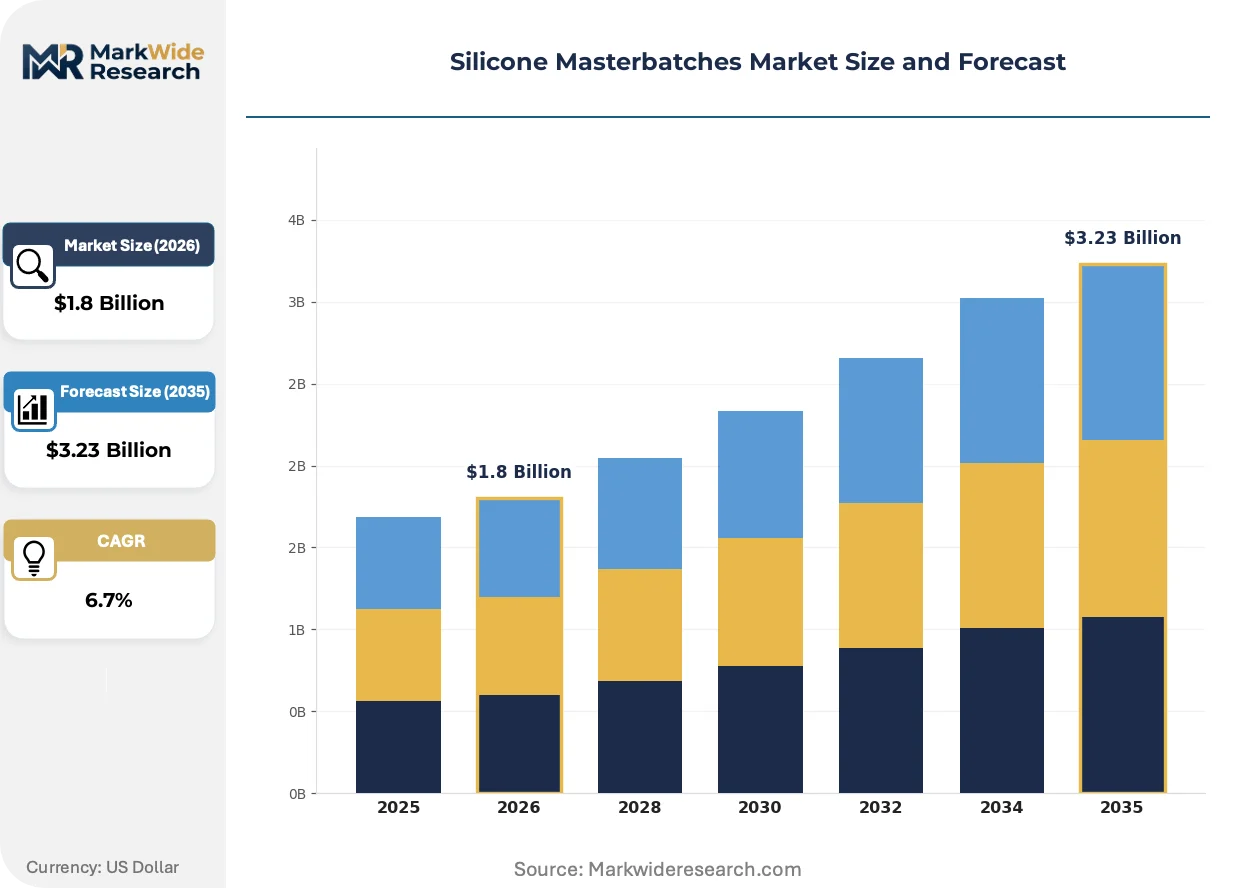
Market Dynamics
Automotive electrification is restructuring silicone masterbatch demand toward thermal management and flame-retardant grades, while polymer processors face escalating compliance costs under tightening volatile organic compound regimes across multiple jurisdictions.
Growth Catalysts
- EPA emission limits on solvent-based carriers:Melt-compounded silicone dispersions gain preference as processors abandon solvent-laden alternatives, creating pull for high-consistency silicone compounds in extrusion operations.
- Automotive interior component specifications:OEMs specify silicone masterbatches for surface lubricity in dashboard and door panel assemblies, particularly in electric vehicle platforms where thermal stability requirements intensify.
- China's polymer processing scale:Domestic compounding capacity expansion concentrates demand for localized masterbatch supply, drawing regional production investment and technical service infrastructure.
Market Restraints
- Siloxane feedstock concentration:Ultra-high molecular weight silicone gum supply remains dominated by a narrow supplier base in East Asia, creating vulnerability for premium filler masterbatch formulators.
- REACH substance restrictions:Crosslinker chemistry reformulation costs burden European market entrants, particularly for food-contact and textile additive portfolios intersecting with per- and polyfluoroalkyl substance scrutiny.
- Fluorosilicone substitution threat:High-performance sealing applications in aerospace and medical devices increasingly specify fluorosilicone compounds, compressing addressable market for standard silicone masterbatches in extreme-environment segments.
Strategic Opportunities
- India's BIS certification pathway:Import compliance layers for masterbatch formulations create first-mover advantage for suppliers establishing local technical relationships and testing partnerships.
- Coatings mar resistance demand:Architectural and industrial formulations seek weatherability additives, opening volume channels beyond traditional plastics processing dominance.
- EU F-Gas Regulation alignment:Silicone fluid selection protocols favor low-global-warming-potential carriers, rewarding early reformulators with preferential positioning in European automotive tier supply chains.
Industry Challenges
- Compounder talent scarcity:Twin-screw extrusion and internal batch mixing expertise for 5–50% loading uniformity remains concentrated among legacy specialists, constraining quality-scaled expansion.
- Multi-jurisdiction certification timelines:Sequential GB standard compliance in China, BIS requirements in India, and EPA registration in the United States extend product launch cycles and inflate working capital needs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Masterbatches Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Color Masterbatch, Filler Masterbatch, Additive Masterbatch, Black Masterbatch Application: Plastics, Coatings, Rubber, Textiles End User: Automotive, Consumer Goods, Electronics, Packaging Manufacturing Stage: Compounding, Injection Molding, Extrusion, Blow Molding |
| Companies Covered | Dow, Wacker Chemie AG, Momentive, Chengdu Silike, Javachem, Clariant, Elkem Silicones, Ampacet, Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Masterbatches Market Strategic Shifts
Reformulation chemistry and carrier system engineering are displacing legacy additive delivery methods as processors prioritize regulatory compliance alongside performance metrics in material selection.
Reactive silicone masterbatch technology is overtaking conventional physical blends in automotive under-the-hood applications. Tier suppliers specify covalently bonded additive systems for permanent surface modification in engine bay components exposed to thermal cycling. This chemistry is compressing warranty claim rates and enabling extended service intervals.
REACH authorization procedures and the EU F-Gas Regulation are restricting silicone fluid molecular weight distributions permissible in European market access. Compounders reformulate toward low-viscosity oligomer carriers that satisfy migration limits while maintaining processing aid functionality. Electronics-grade masterbatches face the steepest substitution pressure as RoHS intersects with substance restrictions.
Specification consolidation among automotive OEMs is compressing approved supplier lists and elongating qualification protocols. Tier-1 compounders now demand multi-year volume commitments and captive inventory arrangements before allocating technical resources to masterbatch co-development. This concentration is most visible in German and Japanese automotive supply chains where platform standardization dominates material selection.
Silicone Masterbatches Market Segmentation
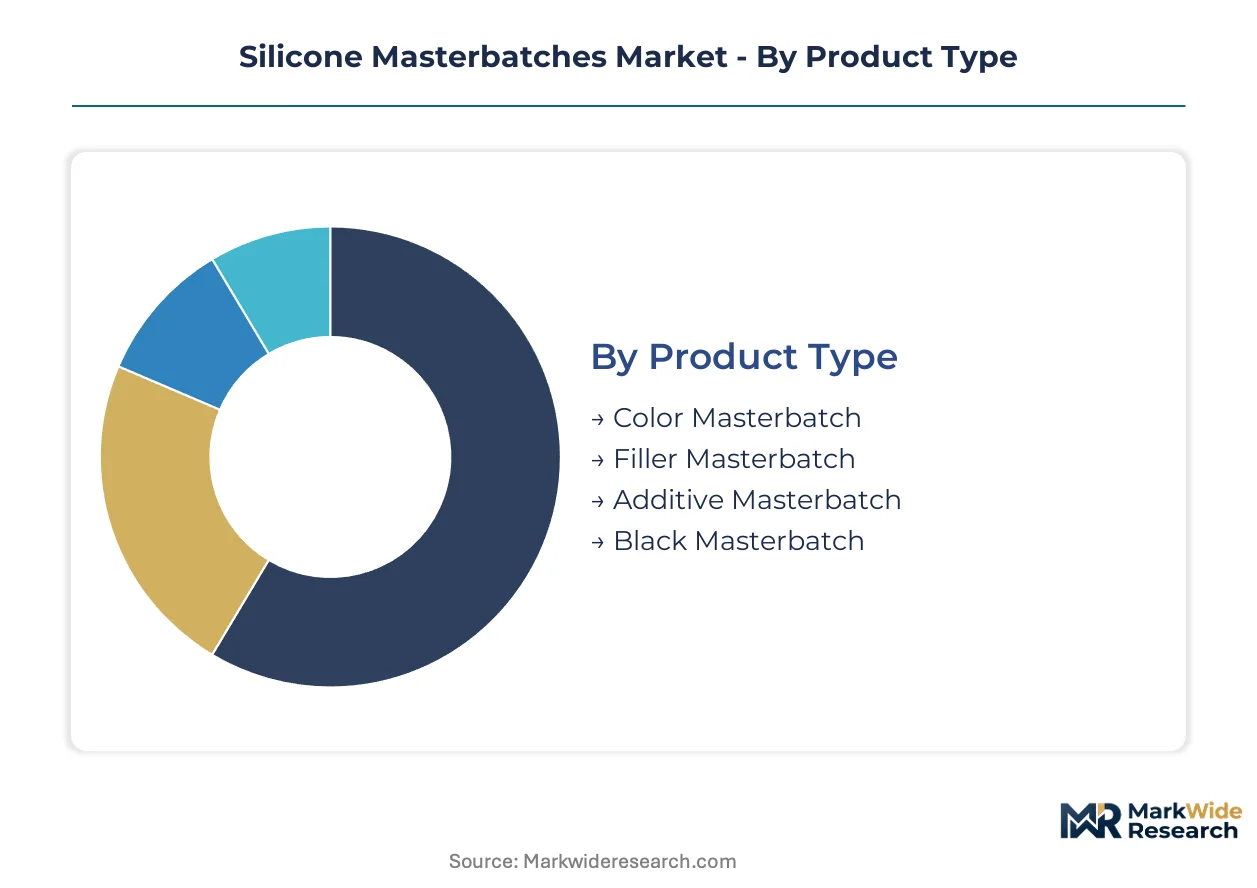
Silicone masterbatch specifications diverge sharply across end-use certifications, with automotive and electronics grades demanding REACH-compliant carrier systems while packaging applications prioritize cost-optimized filler loadings. Processors select masterbatch types based on migration limits, thermal stability thresholds, and OEM qualification protocols that vary by downstream industry.
Product Type:
Certification burdens stratify sharply across product categories, with electronics-grade additive masterbatches facing RoHS intersection and food-contact formulations requiring EFSA compliance for migration limits.
- Color Masterbatch:Pigment-dispersed silicone carriers achieve uniform coloration in thermoplastic elastomers at 5–20% loadings. Demand concentrates in German automotive interior programs where OEMs specify exacting color-matching protocols for dashboard assemblies.
- Filler Masterbatch:Ultra-high molecular weight silicone gum dispersions enhance mechanical properties and surface lubricity in commodity polymers. Volume leadership in Chinese packaging compounding reflects domestic polymer processing scale and localized technical service infrastructure.
- Additive Masterbatch:Functional dispersions impart flame retardancy, processing aid, or thermal stability properties. Electronics manufacturers in Japan specify these grades for RoHS-compliant connector housings.
- Black Masterbatch:Carbon black-loaded silicone systems serve under-the-hood automotive applications requiring UV resistance and thermal cycling durability. Tier suppliers in the United States specify these for electric vehicle battery enclosure components.
Filler Masterbatch sits at the top of the volume ranking, with Additive Masterbatch climbing the fastest.
Application:
Cost tiers separate commodity processors from specialty formulators, with coatings applications commanding formulation premiums for weatherability specifications while rubber compounding absorbs standardized filler grades.
- Plastics:Dominant absorption channel spanning injection-molded consumer goods to extruded construction profiles. Chinese processors drive volume through domestic compounding capacity expansion and polymer production scale.
- Coatings:Architectural and industrial formulations leverage silicone masterbatches for mar resistance and weatherability. Demand is expanding most quickly in German automotive refinish programs and Japanese industrial maintenance coatings.
- Rubber:Silicone dispersions enhance processing characteristics in high-consistency rubber compounds. Indian tire manufacturers specify these grades for BIS-certified commercial vehicle tread formulations.
- Textiles:Soft-touch and water-repellency applications in technical fabrics. REACH substance restrictions constrain silicone fluid selection for European apparel supply chains.
Plastics maintains volume leadership across all geographies, though Coatings demonstrates the steepest expansion trajectory as weatherability specifications tighten.
End User:
Customer procurement patterns diverge by qualification intensity, with automotive OEMs demanding captive inventory arrangements while packaging converters prioritize spot purchasing flexibility.
- Automotive:Specification consolidation among German and Japanese OEMs compresses approved supplier lists. Electric vehicle thermal management requirements are restructuring demand toward flame-retardant and high-heat grades.
- Consumer Goods:Household appliance and personal care packaging applications prioritize cost-optimized filler masterbatches. Chinese domestic brands drive volume through localized compounding partnerships.
- Electronics:RoHS intersection with REACH substance restrictions creates the steepest compliance burden. Japanese connector and housing manufacturers specify ultra-pure additive grades with full material disclosure.
- Packaging:Commodity film and container applications sustain filler masterbatch volume. Indian flexible packaging converters navigate BIS certification requirements for imported formulations.
Packaging commands the largest absolute volume, with Electronics gaining share fastest on semiconductor and electric vehicle component qualification.
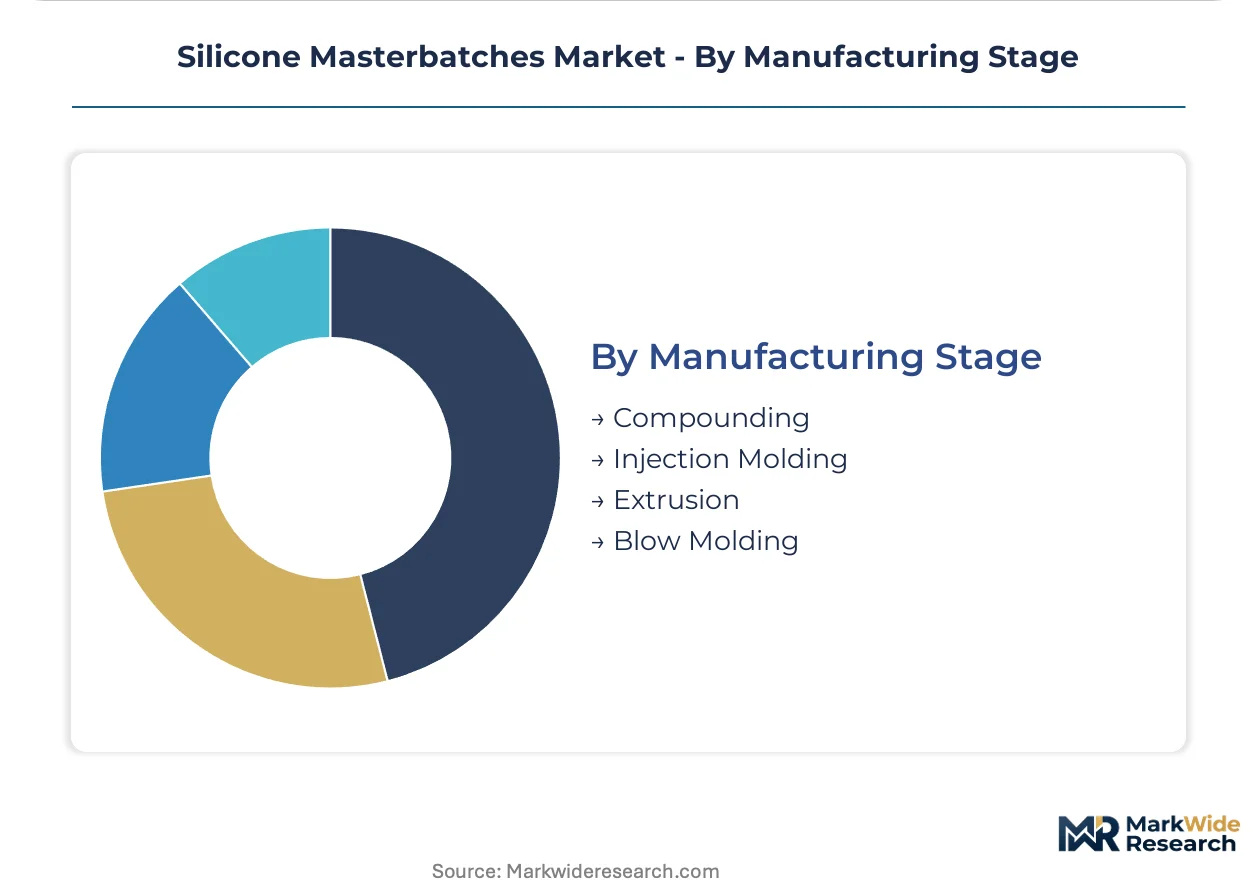
Manufacturing Stage:
Supply concentration in twin-screw extrusion expertise creates capability scarcity, with compounders possessing 5–50% loading uniformity technology commanding technical service premiums.
- Compounding:Primary masterbatch production via twin-screw extrusion or internal batch mixing. German and United States specialty chemical producers are realigning capacity toward high-consistency silicone compounds for this stage.
- Injection Molding:Direct let-down of masterbatch into molded automotive and electronics components. Japanese tier suppliers specify reactive silicone systems for permanent surface modification in engine bay applications.
- Extrusion:Film, sheet, and profile production absorbing the dominant share of masterbatch offtake. EPA emission limits on solvent-based carriers favor melt-compounded silicone dispersions in United States operations.
- Blow Molding:Container and hollow-part manufacturing utilizing color and filler grades. Chinese domestic processors drive localized supply chain development for this stage.
Extrusion dominates volume absorption, with Compounding representing the fastest-growing stage as backward integration into siloxane feedstocks reshapes competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting silicone masterbatch production toward jurisdictions with lower compliance costs, while REACH and EPA standards force reformulation investments in established markets. Manufacturers now weigh migration-limit stringency against polymer processing scale when siting compounding capacity.
China
Domestic polymer processing scale concentrates demand for localized masterbatch supply, with Yangtze River Delta compounders expanding twin-screw extrusion capacity. GB standards on additive migration create compliance layers distinct from REACH, rewarding domestic formulators with faster certification timelines. Shanghai and Jiangsu province host the densest clustering of silicone masterbatch technical service infrastructure.
Germany
Automotive OEM specification consolidation compresses approved supplier lists for dashboard and under-the-hood grades. ECHA REACH authorization procedures restrict silicone fluid molecular weight distributions, forcing reformulation toward low-viscosity oligomer carriers. Bavaria and Baden-Württemberg anchor European compounding expertise for high-consistency silicone compounds.
United States
EPA emission limits on solvent-based carriers favor melt-compounded silicone dispersions in extrusion operations. Electric vehicle battery enclosure specifications drive flame-retardant grade qualification among tier suppliers. Michigan and Ohio automotive clusters concentrate demand for thermal management masterbatches.
India
BIS certification requirements for imported masterbatch formulations create first-mover advantage for suppliers establishing local testing partnerships. Tire manufacturers specify silicone dispersions for commercial vehicle tread formulations. Maharashtra and Gujarat host the expanding domestic compounding capacity serving packaging converters.
Japan
RoHS intersection with substance restrictions creates steep compliance burdens for electronics-grade additive masterbatches. Connector and housing manufacturers specify ultra-pure grades with full material disclosure. Kanto and Kansai industrial corridors concentrate precision compounding expertise for semiconductor applications.
Silicone Masterbatches Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty additive formulations for electric vehicle and electronics qualifications. The supplier base stratifies between siloxane feedstock integrators and independent compounders lacking backward integration. Three archetypes dominate: chemical conglomerates with captive siloxane supply, regional compounding specialists with automotive tier relationships, and Asian ultra-high molecular weight gum suppliers. Competitive moves center on capacity realignment toward high-consistency compounds and multi-year volume commitments with OEMs.
Among chemical conglomerates, Dow and Wacker Chemie AG exemplify feedstock-integrated positioning, while Shin-Etsu Chemical Co., Ltd. occupies a specialist tier in premium gum supply. These entities represent contrasting responses to siloxane concentration risk: backward integration versus dedicated compounding facility investment. Their market presence anchors the competitive structure through which tier suppliers negotiate qualification protocols and captive inventory arrangements.
| Leading Market Players |
|---|
| Dow |
| Wacker Chemie AG |
| Momentive |
| Chengdu Silike |
| Javachem |
| Clariant |
| Elkem Silicones |
| Ampacet |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Siloxane feedstock costs cascade through three distinct pricing tiers as ultra-high molecular weight silicone gum moves from East Asian producers through European compounding facilities to automotive tier suppliers. REACH-compliant carrier reformulation and EPA emission constraints on solvent-based systems compress margins at each handoff, concentrating pricing power with backward-integrated siloxane producers.
Pricing Analysis
Distributor markups widen for electronics-grade additive masterbatches facing RoHS intersection, while direct-to-OEM contracts command volume discounts for flame-retardant grades in electric vehicle battery enclosures. Price differentiation rests on certification intensity—EFSA-compliant food-contact formulations trade at substantial premiums over commodity filler grades. Cost compression in standard silicone dispersions intensifies as Chinese domestic compounding capacity expands. Packaging converters exhibit highest price sensitivity, prioritizing spot purchasing flexibility over captive inventory arrangements.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese automotive OEMs mandate multi-supplier qualification for dashboard and under-the-hood grades, fragmenting procurement across Shin-Etsu Chemical, Dow, and Wacker Chemie. Geographic supply concentration centers on China, Germany, and the United States, with raw material dependencies spanning siloxane monomers, ultra-high molecular weight silicone gum, and low-viscosity oligomer carriers. Single-source vulnerability persists for premium gum supply anchored in East Asia. Distribution runs through technical service-intensive direct channels for automotive tiers and distributor networks for commodity packaging processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH authorization milestones and EPA emission limits on solvent-based carriers drive sustained reformulation demand across automotive and electronics supply chains.
For Market Incumbents: To counter fluorosilicone substitution in aerospace and medical sealing applications, anchor positioning through captive siloxane supply and dedicated compounding facilities serving European automotive tiers. Prioritize multi-year volume commitments with OEMs before allocating technical resources to masterbatch co-development.
For New Entrants and Emerging Players: Indian flexible packaging converters navigating BIS certification requirements represent the most penetrable buyer archetype. Establish local testing partnerships in Maharashtra and Gujarat to compress import compliance timelines. Target coatings mar resistance applications in German automotive refinish programs as a technical credibility-building wedge.
For Investors and Strategic Acquirers: Consolidation pressure builds where twin-screw extrusion expertise for 5–50% loading uniformity remains concentrated among legacy specialists. Long-term viability favors compounders with backward integration into siloxane feedstocks or automotive tier relationships in electric vehicle thermal management. Watch for qualification protocol elongation among Japanese connector manufacturers as an inflection signal for electronics-grade margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstocks | Dow leverages captive monomer supply to secure cost positions across additive masterbatch lines. |
| REACH-Compliant Carrier Reformulation | Low-viscosity oligomer protocols reward early movers with preferential access to European automotive tiers. |
| Indian BIS Certification Partnership | Local testing relationships create first-mover advantage for imported masterbatch formulations. |
| Reactive Silicone Masterbatch Development | Covalently bonded systems compress warranty claims in engine bay thermal cycling applications. |
| Coatings Technical Service Expansion | Architectural and industrial weatherability specifications open volume channels beyond plastics dominance. |
Study Parameters
Bottom-up polymer processing modeling reconciled against top-down siloxane feedstock tracking forms the analytical core of this study. Primary interviews with twin-screw extrusion specialists, automotive tier procurement leads, coatings formulators, and regulatory affairs directors at specialty chemical producers were validated against secondary sources including ECHA REACH authorization databases, EPA emission compliance filings, customs trade data, and GB standard certification records. Triangulation between demand-side volume absorption and supply-side capacity realignment ensures cross-verified outputs.
Input-output matrices map siloxane monomer flows through compounding, injection molding, extrusion, and blow molding stages across product type, application, end user, and manufacturing stage dimensions. CAGRs were derived from regression analysis of historical capacity expansion and qualification protocol timelines, calibrated against electric vehicle platform standardization and electronics RoHS intersection effects. Forecast sensitivity incorporates polymer processing scale trajectories in China and reformulation cost burdens under tightening migration limits.
Underlying measurement precision varies by segment; electronics-grade additive masterbatches with full material disclosure requirements carry tighter precision than commodity filler grades for packaging. Forecasts reflect assumptions around REACH authorization timelines, BIS certification pathway efficiency, and sustained automotive electrification investment. Deviation in siloxane feedstock concentration or fluorosilicone substitution rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Organoclay Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Propoxylates Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Polyoxin Market