
 Global Automotive Plastic Bumper Market | 2026-2036
Global Automotive Plastic Bumper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Plastic Bumper Market Analysis
Mexico is rewriting capacity maps as automakers expand North American bumper molding operations. Plastic Omnium leverages its injection molding footprint across multiple continents to serve regional OEM clusters. Magna International anchors bumper module assembly through integrated fascia and energy absorber lines. Toyoda Gosei competes on painted surface quality for premium vehicle programs.
Automotive plastic bumpers are exterior energy management systems molded from polypropylene blends, polyurethane foams, or ABS composites, designed to absorb low-speed collision forces while supporting pedestrian safety and aerodynamic performance. Polypropylene dominates material selection due to its recyclability and weight advantage over polyurethane in mass-market applications. Electric vehicle bumper demand is outpacing passenger car averages as battery platform architectures require unique cooling airflow and sensor integration designs. Injection molding captures the majority of value as OEMs specify larger, more complex single-piece fascias with Class A surface requirements.
EPA fuel economy standards in the United States push OEMs toward lighter bumper substrates, while ECHA REACH compliance in Europe restricts certain plasticizers and mandates recyclability disclosures. China's GB standards on vehicle exterior safety and MIIT new energy vehicle regulations collectively shape bumper design requirements across three major production zones. Stakeholders must track how pedestrian protection testing protocols evolve alongside autonomous vehicle sensor placement needs.
Market Dynamics
OEM platform consolidation for electric vehicles is compressing bumper design cycles while simultaneously expanding functional requirements for sensor integration and thermal management. This structural tension between standardization and customization is redrawing supplier relationships across the value chain.
Growth Catalysts
- EPA fuel economy standards:US regulatory pressure on vehicle weight reduction accelerates polypropylene adoption over denser polyurethane alternatives in mass-market bumper substrates.
- Electric vehicle platform proliferation:Battery architecture cooling requirements and aerodynamic optimization needs are generating specialized bumper designs with integrated airflow channels.
- China MIIT new energy vehicle regulations:Domestic production mandates for NEVs are concentrating bumper demand among local OEMs scaling manufacturing capacity.
Market Restraints
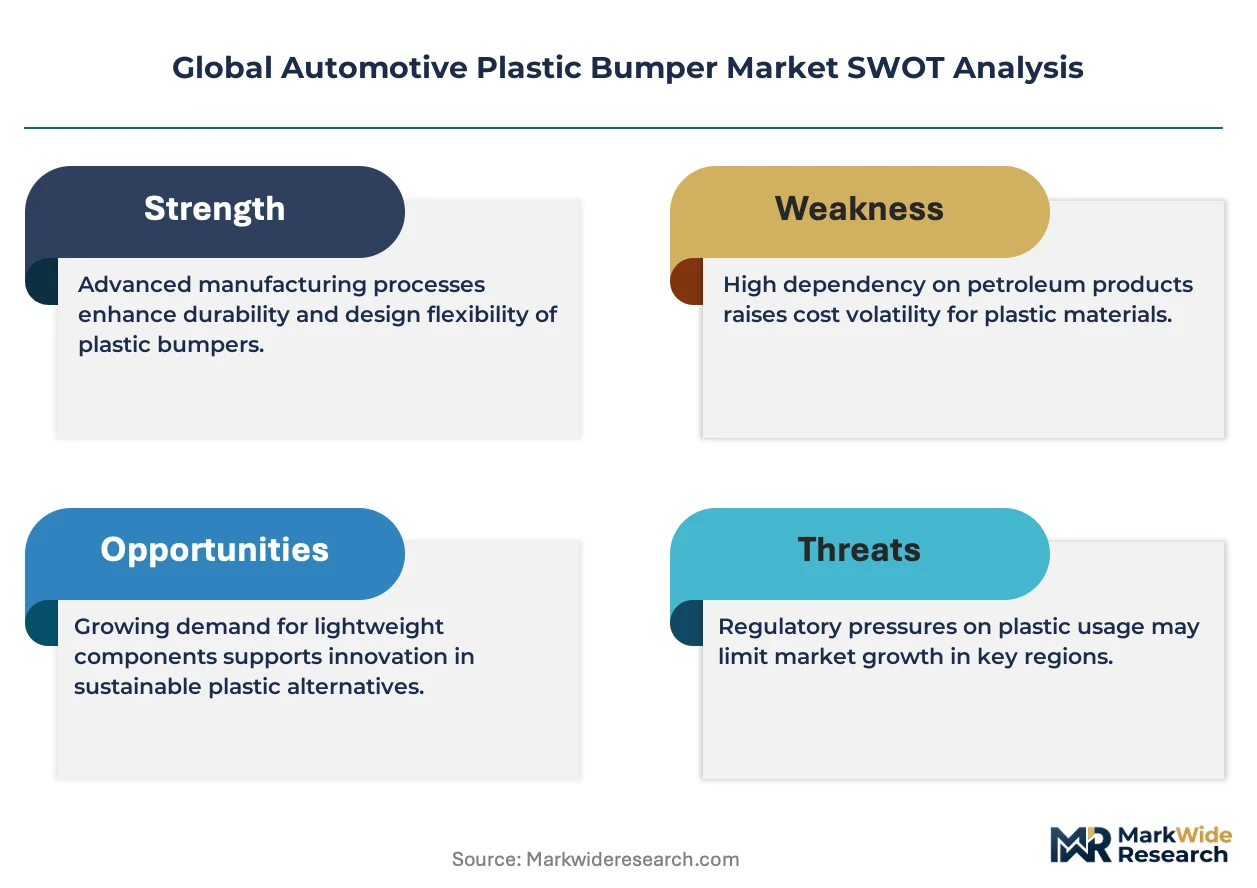
- Polypropylene feedstock volatility:Propylene monomer pricing swings tied to naphtha cracking economics compress molding margin stability for tier suppliers.
- ECHA REACH compliance costs:Recycled content verification and restricted substance documentation create administrative burden disproportionate to material value.
- Steel-aluminum hybrid substitution:Premium vehicle programs in Germany and Japan are reintroducing metal bumper beams for pedestrian protection performance.
Strategic Opportunities
- India PLI scheme for auto components:Localization incentives for advanced polymer processing equipment are opening greenfield capacity for export-competitive molding operations.
- Closed-loop recycling infrastructure:Post-industrial bumper regrind valorization aligns with EU Green Deal circular economy mandates and reduces virgin resin dependency.
- Autonomous vehicle sensor integration:Radar-transparent grille surfaces and lidar-compatible fascia designs command technology premiums from LiDAR and camera system suppliers.
Industry Challenges
- Class A surface finishing expertise:Painted bumper quality consistency requires specialized mold flow simulation and robotic paint application skills that concentrate in established manufacturing clusters.
- Multi-material bonding certification:Adhesive joining of polypropylene fascias to energy-absorbing foams must satisfy OEM crash test protocols with limited standardized test methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Plastic Bumper Market |
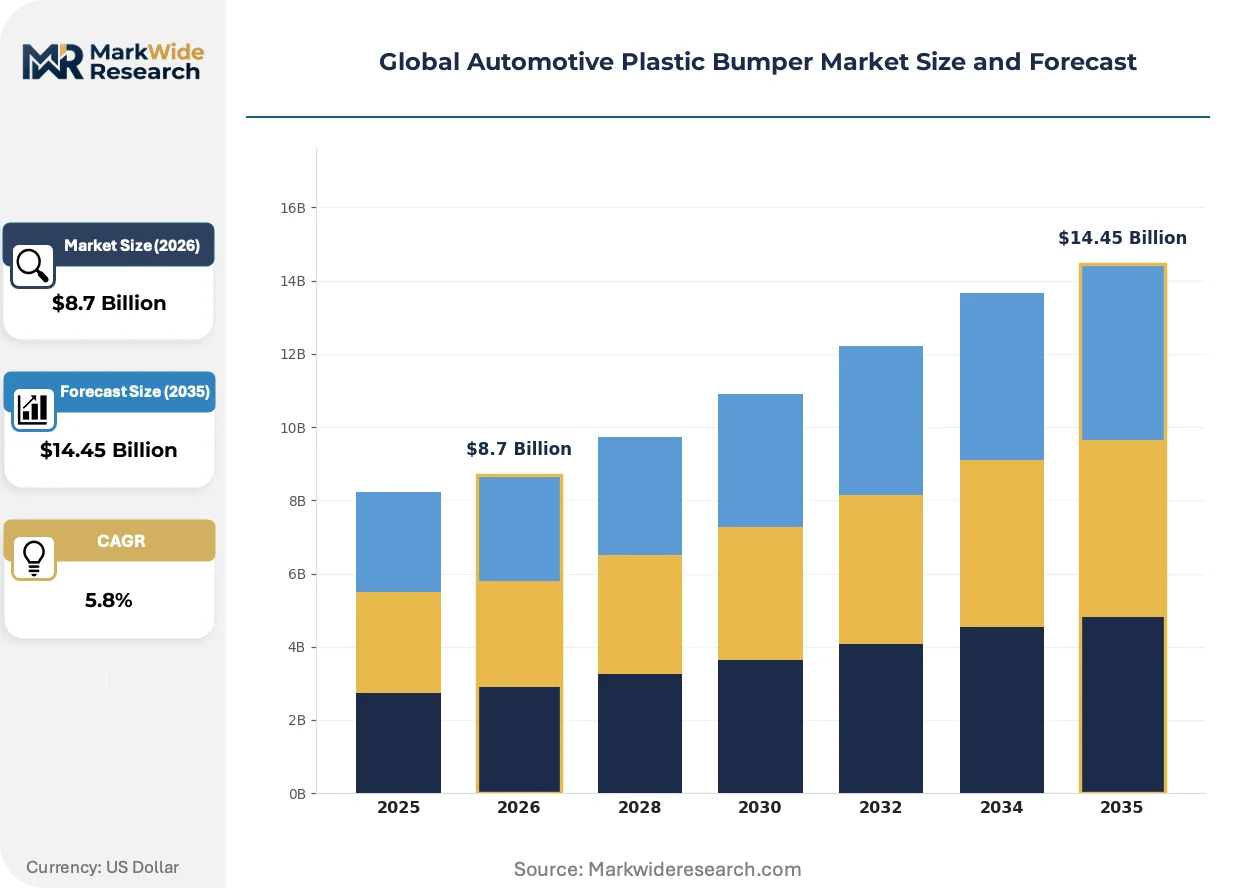
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyurethane, PVC, ABS Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Electric Vehicles Manufacturing Process: Injection Molding, Blow Molding, Compression Molding, Extrusion End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Distributors |
| Companies Covered | Plastic Omnium, Magna International, Toyoda Gosei, Futaba Industrial, Faurecia, Hyundai Mobis, SMP Deutschland GmbH, Flex-N-Gate Corporation, Toyota Boshoku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Plastic Bumper Market Emerging Trajectories
Material science advances and regulatory disclosure requirements are converging to transform how bumper systems are specified, validated, and recovered at end-of-life. Three interconnected developments are restructuring competitive advantage.
Long-fiber reinforced thermoplastic (LFRT) compounds are migrating from experimental applications to mainstream electric vehicle underbody protection and bumper beam substitution. European premium OEMs are specifying LFRT for battery pack surround structures that integrate with bumper crush zones. This migration from metal stampings to polymer composites is compressing tooling lead times while expanding design freedom for complex geometric energy absorption patterns.
REACH Article 33 disclosure obligations on Substances of Very High Concern are forcing material composition transparency down to the additive package level. Compounders must now certify flame retardant and UV stabilizer chemistries through the full supply chain. Tier-1 bumper suppliers serving Volvo and BMW programs are most affected, responding by qualifying alternative additive systems and locking in multi-year supply agreements with compliant resin producers.
Direct-to-OEM digital specification platforms are displacing traditional distributor-mediated material sampling workflows. Polypropylene compounders in Germany and South Korea are deploying cloud-based technical data rooms where OEM engineers access real-time rheology curves and impact test results. This channel shift is most visible in China, where domestic EV manufacturers bypass established trading houses to negotiate volume contracts with compounders for platform-specific material grades.
Global Automotive Plastic Bumper Market Segmentation
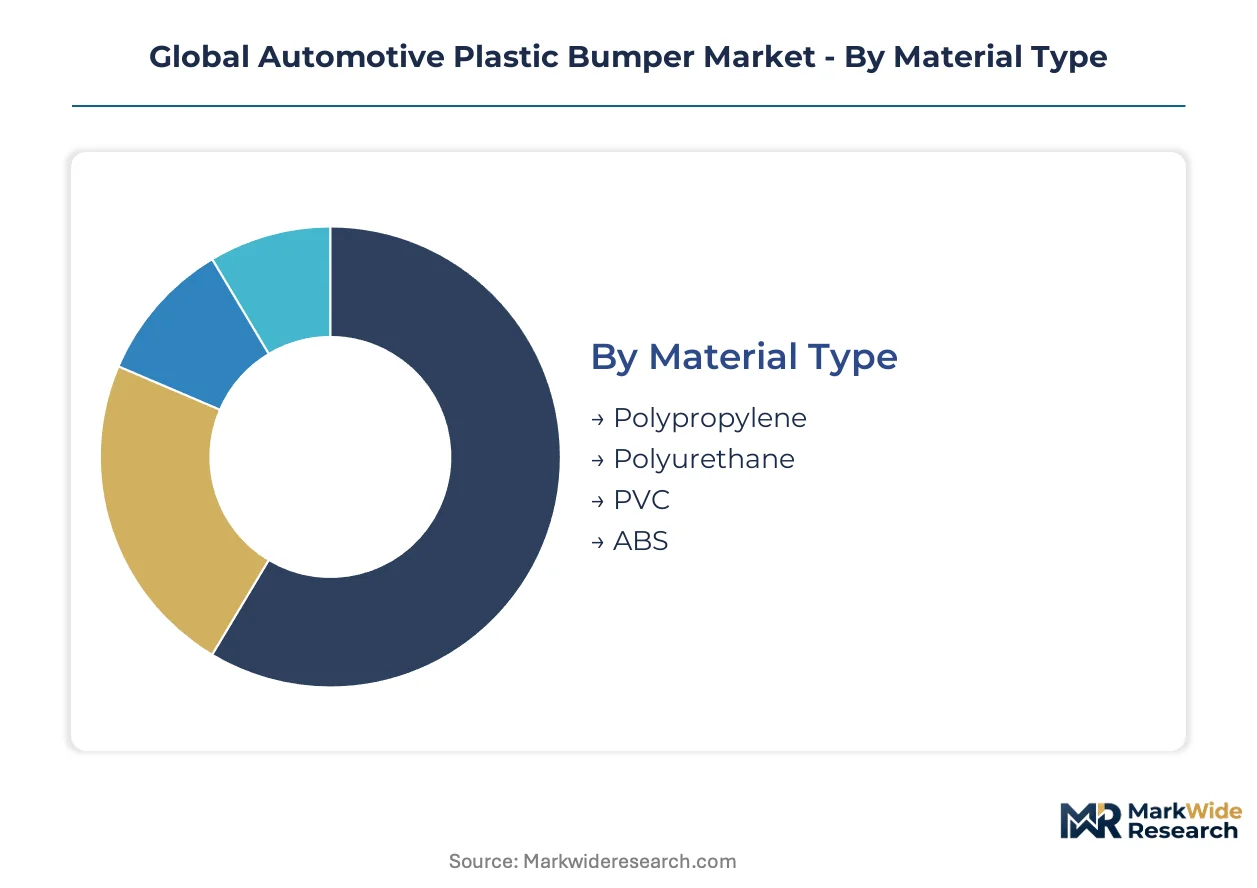
Material chemistry and manufacturing process choices determine cost structures, recyclability pathways, and regulatory compliance trajectories across bumper supply chains. Platform-specific requirements for electric vehicles are fragmenting what was historically a standardized component category.
Material Type:
Polypropylene compounds turn over fastest on specification sheets as compounders reformulate for recycled content mandates, while polyurethane maintains longer validation cycles due to crash-test certification requirements.
- Polypropylene:Dominant thermoplastic selection for fascia substrates, prized for density advantages and post-consumer recyclability. Demand concentrates in Chinese EV manufacturing clusters where MIIT regulations prioritize lightweighting for battery range optimization.
- Polyurethane:Energy-absorbing foam cores and self-skinning RIM applications retain share in premium pedestrian protection systems. German KBA testing protocols for impact absorption sustain specialized demand despite higher material costs and end-of-life recovery complexity.
- PVC:Limited to lower-cost aftermarket replacement fascias and select commercial vehicle applications where surface finish requirements are relaxed.
- ABS:Decorative trim integration and high-gloss unpainted applications in Japanese premium vehicle programs, constrained by heat distortion limitations underhood.
Polypropylene anchors the volume base while polyurethane gains share at the steepest rate in European premium electric vehicle platforms.
Vehicle Type:
Production cycle timing varies dramatically—passenger car bumpers refresh with annual model years, while commercial vehicle designs persist across decade-long platform lives.
- Passenger Cars:High-volume standardization drives injection molding economies, with fascia designs refreshing on compressed 24-month cycles. US EPA fuel economy standards push polypropylene substitution for weight reduction in Detroit Three compact and mid-size programs.
- Electric Vehicles:Specialized thermal management integration and sensor mounting requirements create bespoke bumper architectures. Chinese domestic OEMs including BYD and NIO are specifying unique airflow-optimized designs that diverge from legacy internal combustion layouts.
- SUVs:Larger fascia surface areas and elevated pedestrian protection requirements sustain demand for multi-material constructions with steel reinforcement beams.
- Commercial Vehicles:Durability-focused specifications prioritize impact resistance over aesthetics, with extended replacement cycles compressing aftermarket revenue potential.
Passenger cars generate the highest absolute unit volumes, though electric vehicles are climbing the fastest as a share of OEM procurement spend.
Manufacturing Process:
Capital intensity and tooling lead times create divergent competitive moats—injection molding rewards scale, while blow molding retains niche defensive positions.
- Injection Molding:Captures the majority of Class A fascia production through multi-cavity tooling and robotic surface finishing. Mexican manufacturing corridors serving US OEMs concentrate high-tonnage press capacity for large single-piece designs.
- Blow Molding:Hollow section fuel tank and fluid reservoir integration into bumper systems sustains limited automotive relevance, primarily in commercial vehicle applications.
- Compression Molding:Long-fiber reinforced thermoplastic bumper beams and underbody shields for battery protection in European electric vehicle platforms.
- Extrusion:Profile sections for bumper spoilers, air dam extensions, and aftermarket aerodynamic kits with lower tooling barriers to entry.
Injection molding commands the value pool while compression molding expands most quickly on LFRT compound adoption.
End User:
Procurement sophistication and technical specification authority separate direct OEM relationships from distributor-mediated aftermarket channels.
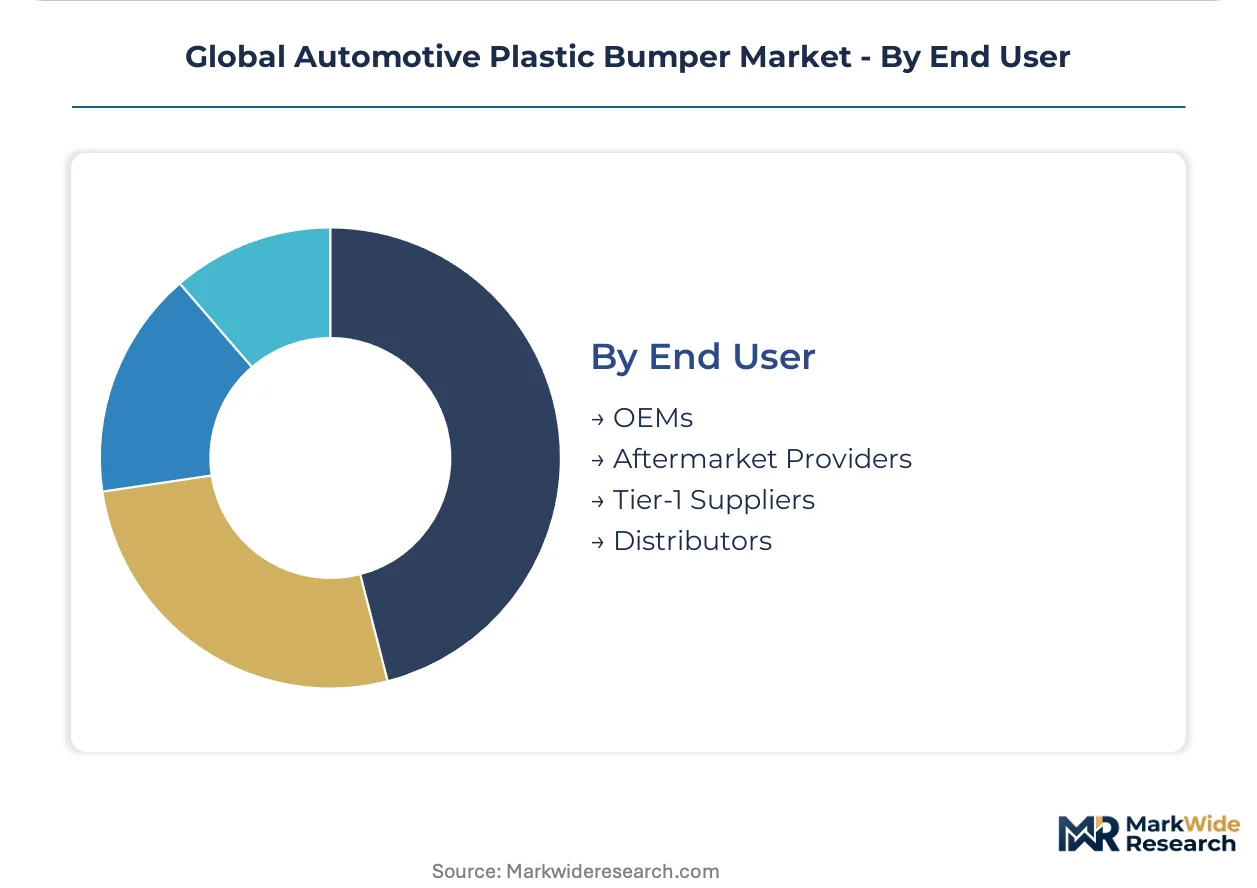
- OEMs:Direct platform engineering collaboration, multi-year volume agreements, and integrated module sourcing encompassing fascias, energy absorbers, and active grille shutters.
- Tier-1 Suppliers:Magna and Plastic Omnium anchor bumper module assembly through captive painting operations and just-in-sequence delivery to vehicle assembly plants.
- Aftermarket Providers:Crash replacement and insurance-driven demand with certified pre-painted fascia distribution through collision repair networks.
- Distributors:Fragmented wholesale channels for uncertified aftermarket bumpers, facing margin compression from direct-to-shop e-commerce platforms.
OEMs and Tier-1 suppliers capture the premium tier while aftermarket providers face pricing pressure from direct channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT regulations in China anchor the dominant geography, with domestic EV procurement driving bumper demand concentration. EPA standards in the United States and ECHA REACH mandates in Germany redirect material sourcing across secondary markets. Production clusters in Mexico, South Korea, and India complete the five-country map.
China
BYD and NIO scale manufacturing for battery platform architectures requiring specialized airflow-optimized bumper designs. MIIT new energy vehicle regulations mandate lightweighting for range optimization, accelerating polypropylene specification. Yangtze River Delta molding corridors concentrate capacity for domestic OEM procurement.
United States
Detroit Three compact and mid-size programs prioritize weight reduction for EPA fuel economy compliance. NHTSA pedestrian protection testing protocols shape energy absorber integration requirements. Mexican manufacturing corridors serving US OEMs expand high-tonnage injection molding capacity.
Germany
Premium OEMs specify LFRT compounds for battery pack surround structures integrating with bumper crush zones. ECHA REACH compliance mandates recycled content verification and restricted substance documentation. Bavarian and Baden-Württemberg supplier clusters anchor European module assembly.
South Korea
Domestic EV manufacturers source radar-transparent grille surfaces and lidar-compatible fascia designs. MFDS-equivalent automotive safety standards align with global pedestrian protection benchmarks. Seoul Capital Area compounders deploy cloud-based technical data rooms for direct OEM engagement.
India
Localization incentives under the PLI scheme for auto components attract advanced polymer processing equipment investment. BIS vehicle exterior safety standards converge with global crash test protocols. Gujarat and Maharashtra greenfield capacity targets export-competitive molding operations.
Global Automotive Plastic Bumper Market Vendor Landscape
Capability concentration sits with specialized compounders and surface finishing operations; scale advantage sits with integrated module assemblers with captive painting capacity. The vendor base stratifies across three tiers: global bumper module suppliers with just-in-sequence delivery networks, regional injection molding specialists serving single OEM clusters, and material compounders qualifying platform-specific grades. Dominant competitive moves include backward integration into resin compounding operations and geographic expansion through brownfield capacity acquisitions in Mexico and Eastern Europe.
Within the integrated module assembly tier, Plastic Omnium exemplifies multi-continental footprint leverage, while Magna International occupies a position anchored through fascia and energy absorber line integration. Among Japan-based specialists, Toyoda Gosei represents the premium surface quality archetype for luxury vehicle programs. These three entities collectively illustrate how supplier relationships are redrawing around platform consolidation pressures and sensor integration requirements.
| Leading Market Players |
|---|
| Plastic Omnium |
| Magna International |
| Toyoda Gosei |
| Futaba Industrial |
| Faurecia |
| Hyundai Mobis |
| SMP Deutschland GmbH |
| Flex-N-Gate Corporation |
| Toyota Boshoku Corporation |
| Others |
Supply Flow & Price Mechanics
Propylene monomer concentration in Middle Eastern and North American petrochemical corridors anchors margin distribution across bumper molding tiers. Compounders with captive resin supply capture downstream value pools that injection molders without backward integration forfeit to spot market volatility.
Pricing Analysis
Mexican manufacturing corridors command 15-20% cost advantages over Midwest US molding operations due to labor arbitrage and duty-free NAFTA access. Three-tier pricing structure across premium, standard, and economy levels separates OEM direct contracts with captive painting from Tier-2 distributor spot purchases. Cost compression in polypropylene feedstock tiers is intensifying because naphtha cracking economics swing with crude oil differentials. Aftermarket distributors exhibit highest price sensitivity, while premium OEM programs prioritize surface quality consistency over unit cost.
Supply Chain Analysis
ECHA REACH substance restrictions on plasticizers and flame retardants limit resin sourcing from non-compliant Asian compounders. Supply concentrates in China, Germany, and Mexico for injection-molded fascias, with South Korea anchoring radar-transparent grille specialty production. Raw material flows draw from Saudi propylene derivatives, US Gulf Coast polymer production, and German additive packages. Single-source vulnerability concentrates in long-fiber reinforced thermoplastic compounds qualified for European EV battery protection. Distribution runs through just-in-sequence module assembly at Tier-1 suppliers with captive painting capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-collision certified pre-painted fascia distribution represents a recurring-revenue layer expanding faster than virgin bumper hardware as insurance-driven replacement cycles compress. Digital specification platforms now attach subscription-based technical data access to compounder contracts.
For Market Incumbents: Build captive closed-loop recycling infrastructure to lock in OEM circular economy mandates. Secure multi-year resin supply agreements with REACH-compliant compounders before additive reformulation cycles accelerate. Defensive consolidation through brownfield capacity acquisition in Mexico and Eastern Europe counters emerging regional molders. For New Entrants and Emerging Players: Pursue radar-transparent grille surfaces for domestic Chinese EV manufacturers bypassing established trading houses. Target India's PLI scheme localization incentives for export-competitive molding operations. Go-to-market leverage rests on cloud-based technical data rooms enabling direct OEM engineer engagement without distributor intermediation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed injection molding specialists in Mexico lacking backward resin integration. Five-to-ten year viability hinges on EV platform standardization sustaining bumper design refresh rates. Watch for MIIT battery platform architecture shifts that would obsolete current airflow-optimized fascia tooling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates margins from naphtha cracking volatility affecting spot buyers. |
| Closed-Loop Recycling Infrastructure | Post-industrial regrind valorization aligns with EU Green Deal mandates and reduces virgin resin dependency. |
| Radar-Transparent Grille Development | LiDAR-compatible fascia designs command technology premiums from autonomous vehicle sensor suppliers. |
| Geographic Manufacturing Footprint Expansion | Mexican corridor capacity serves Detroit Three programs with NAFTA-compliant just-in-sequence delivery. |
| Digital Specification Platform Deployment | Cloud-based technical data rooms displace distributor-mediated workflows for direct OEM engagement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, customs trade records, and regulatory filing repositories. Interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and resin compounder technical directors informed demand segmentation. Bottom-up unit volume estimates triangulated against top-down material flow analysis from petrochemical derivative tracking.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the analysis window. CAGRs derive from modeled OEM procurement spend trajectories, platform lifecycle timing, and material substitution elasticity. Electric vehicle battery platform proliferation and REACH recycled content mandates represent primary demand-side and supply-side forecast drivers.
Sensitivities concentrate around propylene monomer price volatility, MIIT NEV production mandate adjustments, and pedestrian protection testing protocol revisions. Forecasts reflect documented assumptions on platform consolidation rates and sensor integration requirements. Material shifts in ECHA restricted substance lists or EPA fuel economy standard stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
UAE Automotive Composites Market
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
Europe Automotive AHSS Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
US Automotive Composites Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Global Automotive Cigarette Lighters Market