
 Metformin Hydrochloride Market | 2026-2036
Metformin Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Metformin Hydrochloride Market Outlook
China is fragmenting as new API capacity comes online in Shandong and Jiangsu provinces, altering traditional supply concentration patterns. Sun Pharmaceutical Industries anchors its position through backward integration into active pharmaceutical ingredient manufacturing. Teva Pharmaceutical Industries competes on regulatory dossier breadth across European and North American markets. Vistin Pharma differentiates via specialized metformin HCl production for highly regulated geographies.
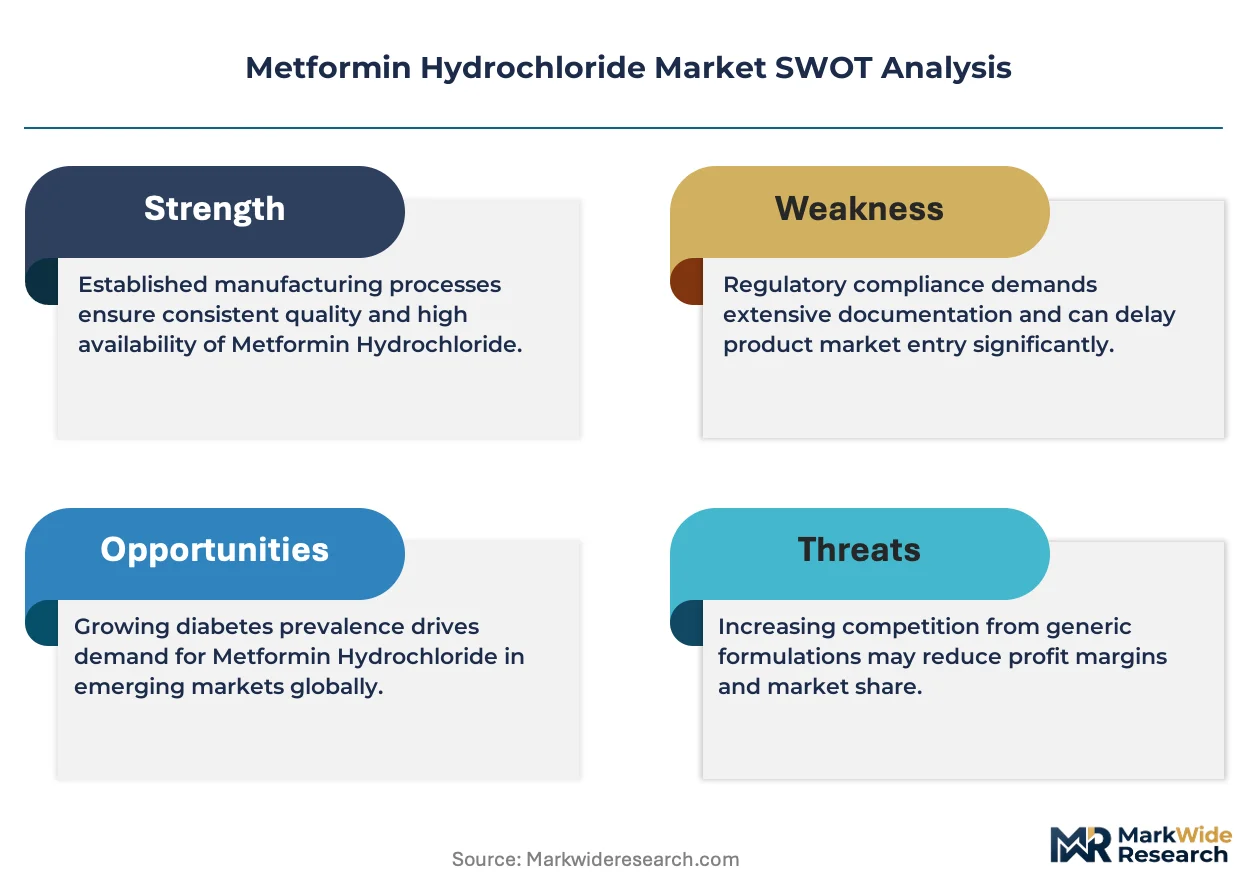
Metformin hydrochloride is a biguanide-class oral antihyperglycemic agent with the molecular formula C4H12ClN5, typically manufactured through direct synthesis from dimethylamine and cyanoguanidine followed by acid hydrolysis and crystallization. The compound primarily functions to suppress hepatic glucose production and improve peripheral insulin sensitivity in Type 2 diabetes management. Extended-release tablets command premium positioning due to improved gastrointestinal tolerability profiles and once-daily dosing adherence benefits. Hospital pharmacies represent the most concentrated procurement channel, while online pharmacies are gaining share as reimbursement frameworks adapt to direct-to-patient fulfillment models.
FDA enforces stringent bioequivalence requirements under 21 CFR 320 for generic metformin approvals, while USP dissolution methodology (USP <711>) governs batch release specifications for extended-release variants. EMA's revised bioequivalence guidelines for highly variable drugs create additional compliance layers for European market access. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards as divergence in impurity thresholds threatens cross-border formulation approvals.
Market Dynamics
Hospital procurement consolidation is reshaping metformin hydrochloride demand patterns as integrated delivery networks negotiate directly with API manufacturers, bypassing traditional wholesale intermediaries and compressing margin structures across the supply chain.
Growth Catalysts
- Extended-release formulation preference:Hospital formularies increasingly mandate once-daily dosing regimens to improve patient adherence metrics and reduce nursing administration burdens.
- FDA bioequivalence pathway refinement:Streamlined 21 CFR 320 approval processes for highly variable drugs accelerate generic entry and expand affordable supply.
- Shandong and Jiangsu capacity expansion:New API manufacturing facilities in these provinces increase global supply availability and moderate input cost volatility.
Market Restraints
- Dimethylamine feedstock concentration:Petrochemical derivative supply chains cluster around specific coastal refining corridors, exposing manufacturers to concentrated disruption risk.
- USP dissolution testing stringency:USP <711> methodology revisions for extended-release variants extend batch release timelines and elevate quality control expenditures.
- Fixed-dose combination substitution:SGLT2 inhibitor-metformin co-formulations capture prescribing preference in progressive diabetes management protocols.
Strategic Opportunities
- Indian domestic capacity scaling:PLI scheme incentives for API manufacturing attract investment toward regulated export market qualification.
- Online pharmacy channel emergence:Direct-to-patient fulfillment models bypass traditional retail pharmacy networks and capture reimbursement flow redirection.
- Continuous manufacturing technology adoption:Flow chemistry integration with real-time release testing compresses production cycle times and reduces solvent waste profiles.
Industry Challenges
- Analytical method transfer complexity:USP-to-EP-to-IP pharmacopeial divergence in impurity thresholds necessitates parallel validation studies for multi-jurisdiction filings.
- Specialized regulatory dossier expertise scarcity:Qualified personnel capable of navigating EMA revised bioequivalence guidelines command premium compensation and extend hiring timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metformin Hydrochloride Market |
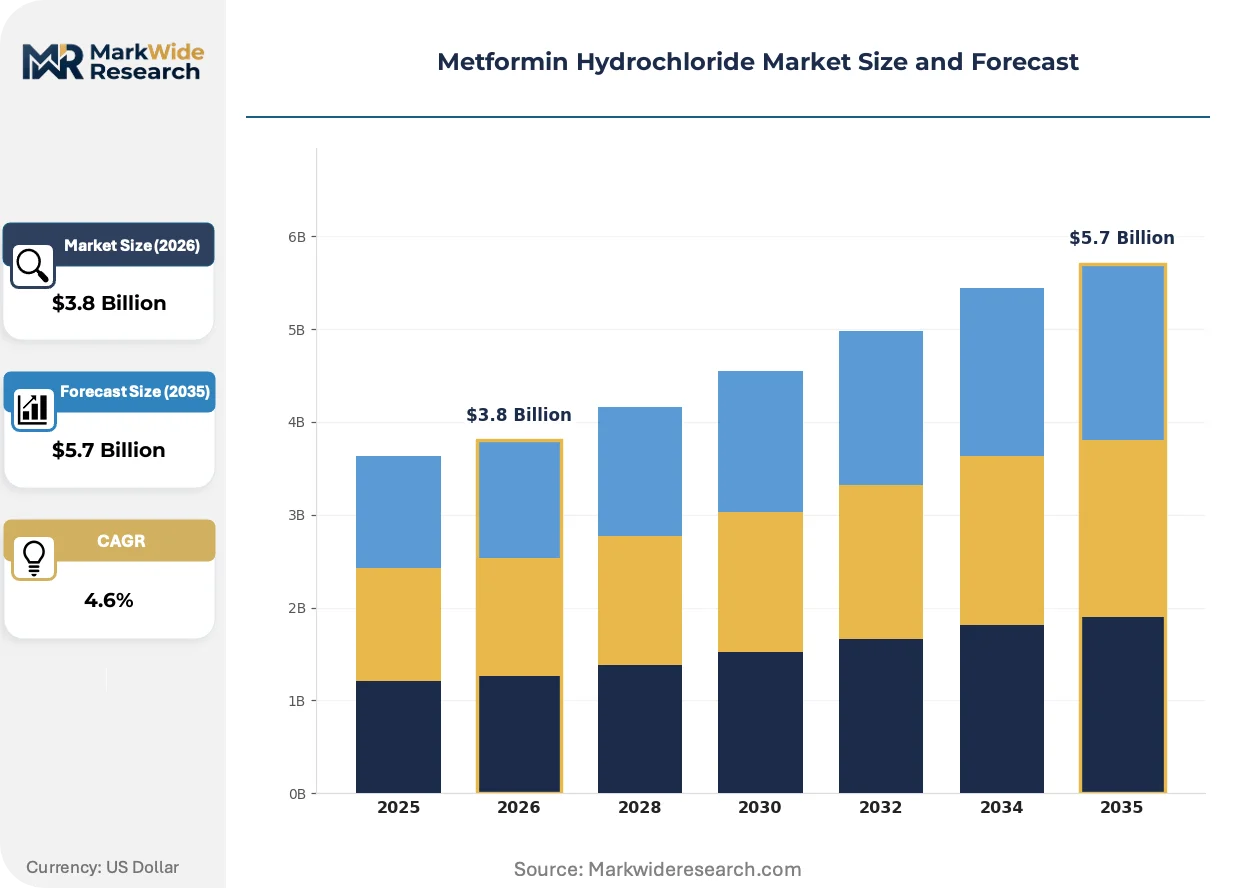
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Extended-Release Tablets, Liquid Solution, Oral Tablets Application: Type 2 Diabetes, Polycystic Ovary Syndrome, Insulin Resistance, Metabolic Syndrome End User: Hospitals, Clinics, Homecare, Pharmacies Distribution Channel: Direct Sales, Retail Pharmacies, Online Pharmacies, Hospital Pharmacies |
| Companies Covered | Sun Pharmaceutical Industries, Lupin Pharmaceuticals, Teva Pharmaceutical Industries, Aurobindo Pharma, Zydus Cadila, USV, Shouguang Fukang Pharmaceutical, Vistin Pharma, CR Double-Crane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metformin Hydrochloride Market Strategic Shifts
Manufacturing technology and regulatory science are converging to reshape competitive positioning in metformin hydrochloride supply, with quality-by-design principles and real-time analytics displacing traditional batch processing paradigms.
Continuous flow synthesis platforms are rendering obsolete conventional batch reactor operations for metformin HCl production. Mid-tier API manufacturers in India and China adopt these systems to reduce solvent consumption and improve mass transfer efficiency. The technology is rendering obsolete capital-intensive stainless-steel vessel farms and manual in-process sampling protocols.
EMA revised bioequivalence guidelines for highly variable drugs impose stricter statistical criteria on generic metformin extended-release approvals. European market access now requires expanded subject pools and replicated study designs, elevating clinical trial costs for dossier submission. Generic sponsors targeting Germany and France must budget additional validation batches to demonstrate dissolution profile consistency.
Hospital pharmacy centralization is consolidating procurement authority within integrated delivery networks and academic medical centers. Traditional wholesale distributors lose volume share as direct manufacturer contracts capture formulary placement. This concentration is most pronounced across United States health systems managing diabetes populations exceeding fifty thousand covered lives.
Metformin Hydrochloride Market Segmentation
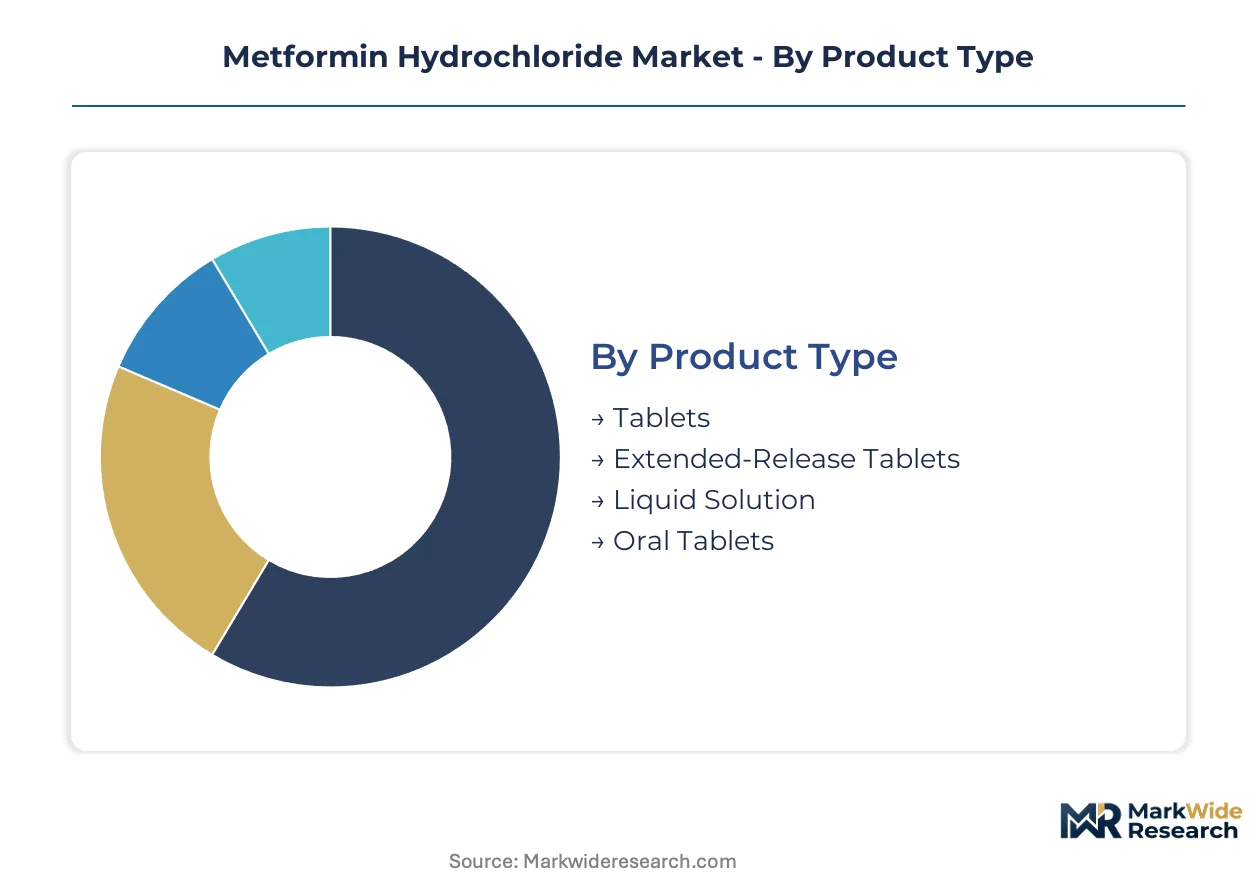
Metformin hydrochloride formulation heterogeneity creates distinct competitive arenas across delivery mechanisms, therapeutic indications, and procurement channels. Each segment carries unique regulatory burdens, margin structures, and customer concentration patterns that reshape supplier positioning.
Product Type:
Cost tier differentiation separates commodity oral tablets from premium extended-release variants with distinct manufacturing complexity and reimbursement profiles.
- Extended-Release Tablets:Matrix-based polymer systems enable controlled dissolution over 12-24 hours, improving gastrointestinal tolerability. Hospital formularies in the United States mandate these formulations for diabetes populations exceeding fifty thousand covered lives to reduce nursing administration burdens.
- Tablets:Immediate-release compressed dosage forms containing 500mg, 850mg, or 1000mg metformin HCl represent the volume foundation. Indian domestic manufacturers scale capacity for regulated export markets, capturing procurement flow from price-sensitive institutional buyers.
- Liquid Solution:Aqueous formulations with adjusted pH and palatability agents serve pediatric and geriatric populations with swallowing difficulties. CDSCO filing requirements in India govern stability testing protocols for these aqueous systems.
- Oral Tablets:Standard compressed dosage forms without modified-release technology occupy the economy tier. Shandong and Jiangsu province capacity expansions in China moderate input cost volatility for these commodity-grade products.
Extended-release tablets command the established base. The steepest expansion runs through liquid solution formats addressing unmet pediatric needs.
Application:
Therapeutic indication breadth extends metformin utility beyond glycemic control into metabolic and endocrine disorders with varying evidence requirements.
- Type 2 Diabetes:First-line oral antihyperglycemic therapy suppressing hepatic glucose production and improving peripheral insulin sensitivity. FDA 21 CFR 320 bioequivalence standards and USP dissolution testing protocols tighten quality benchmarks for generic API suppliers serving this indication.
- Polycystic Ovary Syndrome:Off-label use for insulin sensitization in reproductive endocrinology. EMA revised bioequivalence guidelines for highly variable drugs create additional compliance layers for European market access in this indication.
- Insulin Resistance:Prediabetic and metabolic syndrome management with emerging cardiovascular outcome data. Prescribing concentration occurs in United States academic medical centers with integrated diabetes prevention programs.
- Metabolic Syndrome:Multi-component risk factor modification alongside lipid and blood pressure agents. Clinical trial infrastructure in Germany and France supports dossier submissions for combination therapy positioning.
Type 2 diabetes anchors volume concentration. The steepest climb occurs in polycystic ovary syndrome as reproductive endocrinology formularies expand.
End User:
Customer type fragmentation distributes procurement authority across institutional, retail, and direct-to-patient channels with diverging contract structures.
- Hospitals:Integrated delivery networks negotiate directly with API manufacturers, bypassing traditional wholesale intermediaries. Centralized pharmacy operations in United States health systems compress margin structures across the supply chain.
- Clinics:Outpatient diabetes management centers with formulary committees balancing efficacy and acquisition cost. CDSCO and state-level pharmacy councils in India regulate dispensing permissions for these settings.
- Homecare:Long-term care and visiting nurse services managing stable diabetes patients. Reimbursement frameworks in Germany and France adapt to direct-to-patient fulfillment models for chronic medication supply.
- Pharmacies:Community and retail dispensaries with inventory turnover driven by prescription volume. Online pharmacy channel emergence in India captures reimbursement flow redirection from traditional retail networks.
Hospitals dominate procurement volume. Homecare delivery formats are gaining share fastest as reimbursement adapts to remote patient management.
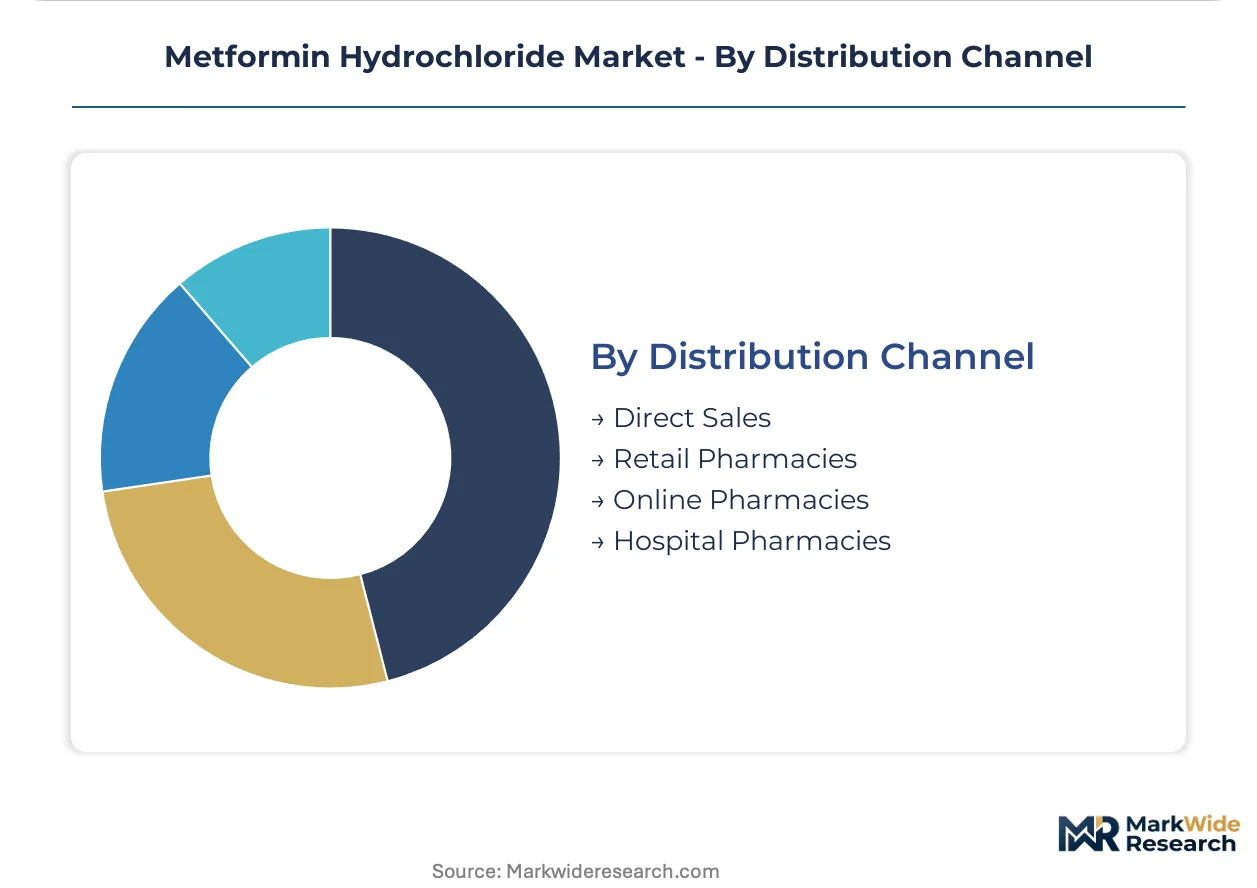
Distribution Channel:
Supply pathway configuration determines margin retention, customer access, and regulatory touchpoint density for manufacturers.
- Hospital Pharmacies:Centralized procurement within integrated delivery networks and academic medical centers captures formulary placement. Direct manufacturer contracts displace traditional wholesale distributors in United States health systems.
- Direct Sales:Manufacturer-to-institution agreements for high-volume diabetes populations. PLI scheme incentives for API manufacturing in India attract investment toward regulated export market qualification through this channel.
- Retail Pharmacies:Community-based dispensing with inventory managed through wholesale distribution. EMA pharmacovigilance requirements govern batch traceability for products flowing through this fragmented channel.
- Online Pharmacies:Direct-to-patient fulfillment platforms bypassing physical retail infrastructure. FDA DSCSA serialization mandates and state-level pharmacy licensure create compliance complexity for interstate distribution.
Hospital pharmacies retain the volume anchor. Online pharmacies show the steepest trajectory as digital health infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Mumbai anchors Indian pharmaceutical exports to regulated markets, while Rotterdam's Maasvlakte terminals handle European API transshipment. These maritime gateways underwrite divergent regional supply strategies for metformin hydrochloride distribution.
United States
Hospital procurement consolidation within integrated delivery networks drives demand for extended-release formulations. FDA 21 CFR 320 bioequivalence standards tighten quality benchmarks for generic API suppliers. New Jersey and Pennsylvania pharmaceutical clusters concentrate formulation manufacturing for domestic hospital pharmacy networks.
Germany
EMA revised bioequivalence guidelines for highly variable drugs elevate clinical trial costs for dossier submissions. Academic medical centers in Berlin and Munich anchor diabetes population management exceeding fifty thousand covered lives. Bavaria-based chemical processors supply dimethylamine feedstock to regional API manufacturers.
India
PLI scheme incentives attract investment toward regulated export market qualification. CDSCO filing requirements govern stability testing protocols for aqueous liquid formulations. Gujarat and Maharashtra pharmaceutical corridors scale capacity for FDA and EMA-compliant metformin HCl production.
China
Shandong and Jiangsu province capacity expansions increase global supply availability and moderate input cost volatility. NMPA alignment with USP dissolution methodology accelerates domestic batch release timelines. Qingdao port infrastructure supports API export consolidation to European and North American markets.
Metformin Hydrochloride Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base fragments across API manufacturers, formulation developers, and distribution intermediaries with divergent margin retention. Three archetypes dominate: backward-integrated pharmaceutical conglomerates, specialized API pure-plays, and generic formulation specialists. Capacity expansion and regulatory dossier breadth constitute the primary competitive vectors for market positioning.
Among India-based pharmaceutical conglomerates, Sun Pharmaceutical Industries and Lupin Pharmaceuticals exemplify backward-integrated structures with captive API production. Vistin Pharma occupies a position within the specialized API pure-play tier, differentiated by focused metformin HCl manufacturing for highly regulated geographies. Teva Pharmaceutical Industries anchors the generic formulation specialist archetype, competing on regulatory dossier breadth across European and North American markets.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries |
| Lupin Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Aurobindo Pharma |
| Zydus Cadila |
| USV |
| Shouguang Fukang Pharmaceutical |
| Vistin Pharma |
| CR Double-Crane |
| Others |
Value Chain & Pricing Dynamics
Dimethylamine feedstock concentration around Shandong and Jiangsu coastal refining corridors exposes manufacturers to concentrated disruption risk, compressing margin spreads between extended-release premium tiers and commodity immediate-release grades while forcing API producers toward dual-sourcing strategies and inventory buffer investments.
Pricing Analysis
Volume-discount tiering structures separate hospital procurement contracts for integrated delivery networks from spot-market transactions serving retail pharmacies. Pricing stratifies across FDA-certified extended-release formulations, USP-compliant standard tablets, and economy-grade immediate-release variants with narrower dissolution tolerances. Cost compression in the standard tier is intensifying because Shandong and Jiangsu capacity expansions flood commodity-grade supply. Hospital formularies demonstrate lowest price sensitivity due to adherence-mandate purchasing, while independent retail pharmacies face acute margin pressure from online pharmacy channel diversion.
Supply Chain Analysis
Export-control regime alignment with USP dissolution methodology and FDA bioequivalence standards limits API flow from non-validated facilities into regulated markets. Manufacturing gravity centers on India and China, with Gujarat and Maharashtra corridors scaling for FDA qualification and Shandong-Jiangsu hubs serving price-sensitive institutional buyers. Dimethylamine petrochemical derivatives, cyanoguanidine intermediates, and acid hydrolysis catalysts constitute critical input dependencies. Single-source vulnerability concentrates around coastal refining corridors for dimethylamine feedstock. Distribution runs through hospital pharmacy centralization and emerging direct-to-patient online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended-release formulation preference among United States hospital formularies signals early-cycle expansion, with once-daily dosing mandates penetrating diabetes populations exceeding fifty thousand covered lives and creating durable procurement lock-in for qualified suppliers.
For Market Incumbents: Pre-empt SGLT2 inhibitor-metformin fixed-dose combination substitution by deepening backward integration into dimethylamine feedstock production and securing captive API capacity in Gujarat and Maharashtra pharmaceutical corridors. Anchor hospital formulary placement through continuous manufacturing technology investments that compress batch release timelines under USP <711> protocols. For New Entrants and Emerging Players: Aqueous liquid solution formats for pediatric and geriatric populations with swallowing difficulties represent the most penetrable entry point, as CDSCO filing requirements create regulatory moats against commodity tablet competition. Target reproductive endocrinology formularies expanding polycystic ovary syndrome off-label positioning through insulin sensitization evidence development. For Investors and Strategic Acquirers: EMA revised bioequivalence guidelines for highly variable drugs reshape the acquisition landscape, elevating specialized regulatory dossier expertise to premium scarcity status. Position for five-to-ten year viability by targeting Indian API pure-plays with captive dimethylamine supply and existing FDA establishment inspections. Monitor NMPA alignment with USP dissolution methodology as the inflection signal for Chinese export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Technology Adoption | Flow chemistry integration with real-time release testing compresses USP <711> batch release timelines for extended-release variants. |
| Backward Integration into API Production | Captive dimethylamine supply from Shandong refining corridors insulates margin structures from petrochemical volatility. |
| Regulatory Dossier Expansion | Broad EMA and FDA filing portfolios unlock hospital formulary placement across European and North American markets. |
| Online Pharmacy Channel Partnership | Direct-to-patient fulfillment models capture reimbursement flow redirection from traditional retail pharmacy networks. |
| Pediatric Liquid Formulation Development | CDSCO-compliant aqueous systems address unmet needs in swallowing-difficulty populations with limited competition. |
Study Parameters
Operator-level perspectives from API manufacturing plant managers, hospital pharmacy procurement directors, regulatory affairs specialists, and CDSCO filing consultants anchored the qualitative base. Secondary validation drew from FDA 21 CFR 320 bioequivalence filings, EMA submission databases, USP dissolution methodology revisions, and Indian PLI scheme disclosure records. Bottom-up capacity assessments across Shandong, Jiangsu, Gujarat, and Maharashtra facilities triangulated against top-down demand modeling from hospital formulary placement data.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning dosage form technology, therapeutic indication breadth, procurement channel concentration, and regional regulatory cluster alignment. CAGRs derived from facility-level capacity expansion announcements, PLI incentive uptake trajectories, and dissolution profile consistency requirements under evolving pharmacopeial standards. Forecast inputs incorporated continuous manufacturing adoption curves and fixed-dose combination substitution elasticity estimates.
Practitioners should monitor NMPA harmonization with USP dissolution protocols, EMA bioequivalence guideline enforcement intensity, and SGLT2 inhibitor co-formulation prescribing trends for early signals of forecast deviation. Material shifts in dimethylamine feedstock corridor concentration or FDA inspection backlog severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Adamantane Antiviral Drugs Market