
 Hard Gelatin Capsules Market | 2026-2036
Hard Gelatin Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Hard Gelatin Capsules Market Foresight
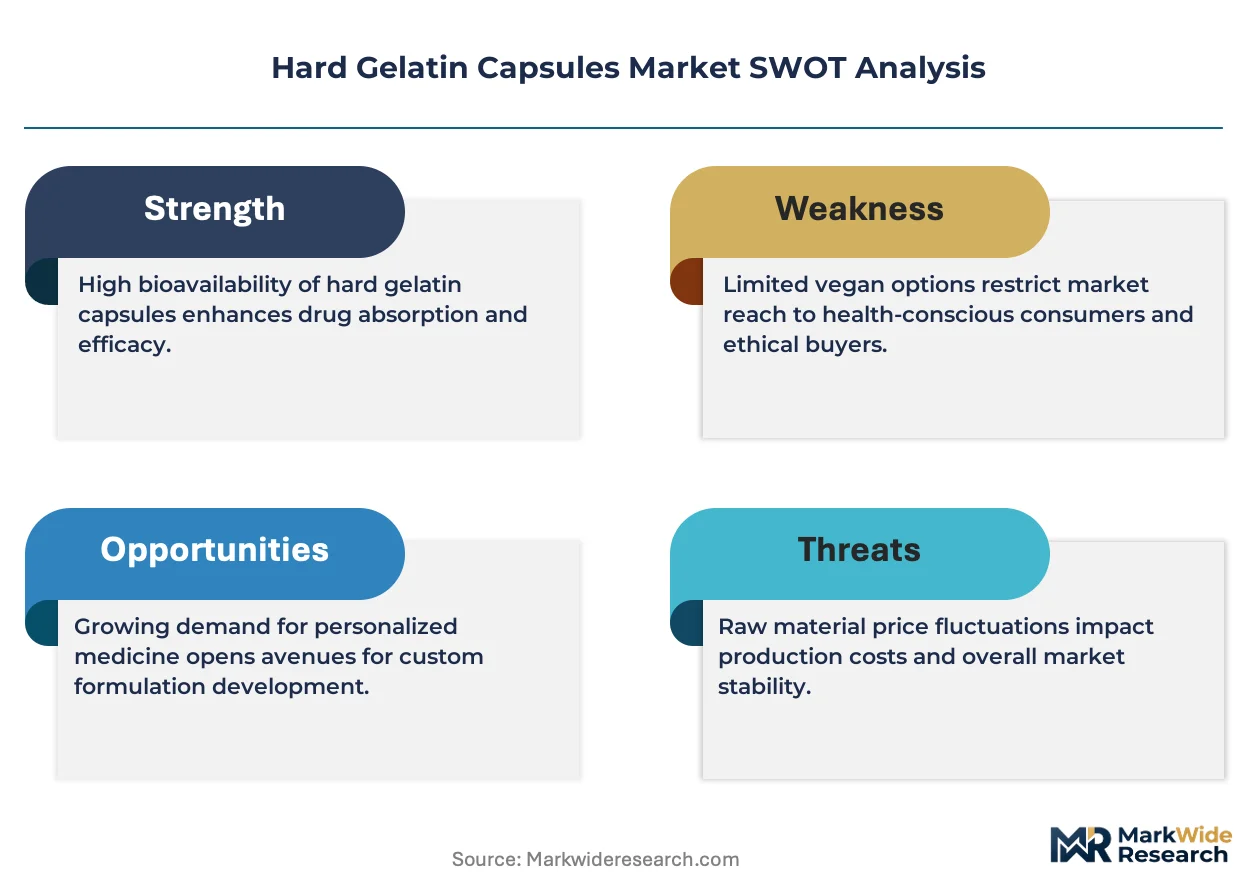
Pharmaceutical distribution through direct-to-manufacturer channels is fragmenting as generic drug makers build captive capsule supplies. Lonza leverages its integrated biopharma manufacturing network to secure long-term capsule supply contracts with European formulation houses. ACG Worldwide anchors South Asian demand through vertically integrated gelatin extraction and capsule molding operations across multiple Indian states. Catalent competes on high-containment capsule filling for potent compounds, differentiating its CDMO portfolio from commodity suppliers.
Hard gelatin capsules are two-piece cylindrical shells composed primarily of animal-derived collagen hydrolysate, typically bovine or porcine gelatin, formed through dip-molding processes into precisely dimensioned cap and body sections designed to encase powders, granules, or pellets for oral administration. Conventional capsules dominate volume shipments due to mature tooling infrastructure and universal compatibility with standard filling equipment, while liquid capsules capture expanding margin pools as lipid-based formulation pipelines grow for poorly soluble APIs. Powder capsules sustain steady nutraceutical uptake, though gelatin capsules face substitution pressure from plant-derived alternatives in dietary supplement channels where clean-label positioning commands shelf access.
The US FDA enforces dissolution profile consistency and extractable-leachable thresholds that elevate compliance costs for capsule shell suppliers seeking drug master file status. India's CDSCO aligns with ICH Q3D guidelines on elemental impurities, forcing domestic manufacturers to validate gelatin sourcing from certified tannery regions. The EU's EMA Medical Device Regulation and REACH restrictions on chromium VI in gelatin processing create dual compliance burdens for exporters. Stakeholders must monitor regulatory divergence between pharmacopeial standards as USP, EP, and IP monograph updates on disintegration times and residue limits proceed on independent timelines.
Market Dynamics
Pharmaceutical contract manufacturers are consolidating capsule-filling capacity around dedicated high-containment suites as potent compound pipelines expand and FDA dissolution testing guidelines tighten quality thresholds for immediate-release oral dosage forms.
Growth Catalysts
- Lipid-based formulation pipelines:Poorly soluble APIs drive demand for liquid-fill hard gelatin capsules as formulation scientists abandon conventional tablet approaches.
- India's PLI scheme for pharmaceuticals:Domestic API-to-finished-dose integration deepens across Gujarat and Hyderabad manufacturing clusters, reducing import dependency for capsule shells.
- CDSCO alignment with ICH Q3D:Elemental impurity standards force certified tannery sourcing, elevating compliant domestic suppliers above informal competitors.
Market Restraints
- Bovine gelatin price volatility:Tannery waste stream fluctuations and competing collagen demand from food and cosmetic sectors compress shell manufacturer margins.
- Plant-derived substitution threat:HPMC and pullulan capsules capture clean-label dietary supplement shelf space as nutraceutical buyers reject animal-derived inputs.
- REACH chromium VI restrictions:EU gelatin processing compliance burdens create dual certification requirements for exporters serving European formulation houses.
Strategic Opportunities
- Potent compound containment services:High-potency API handling capabilities differentiate CDMO offerings as oncology and hormone pipelines expand.
- Direct-to-manufacturer channel consolidation:Generic drug makers building captive capsule supplies create long-term contract opportunities for integrated gelatin-to-shell producers.
- WHO prequalification pathways:Emerging market procurement programs favor suppliers with validated dossiers for HIV, TB, and malaria combination therapies.
Industry Challenges
- Cross-functional containment engineering talent:Isolator design, HVAC validation, and occupational exposure banding expertise concentrates at a handful of specialized consultancies.
- Legacy dissolution equipment retrofitting:USP-NF and EP monograph divergence on disintegration time measurement forces parallel method development investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hard Gelatin Capsules Market |
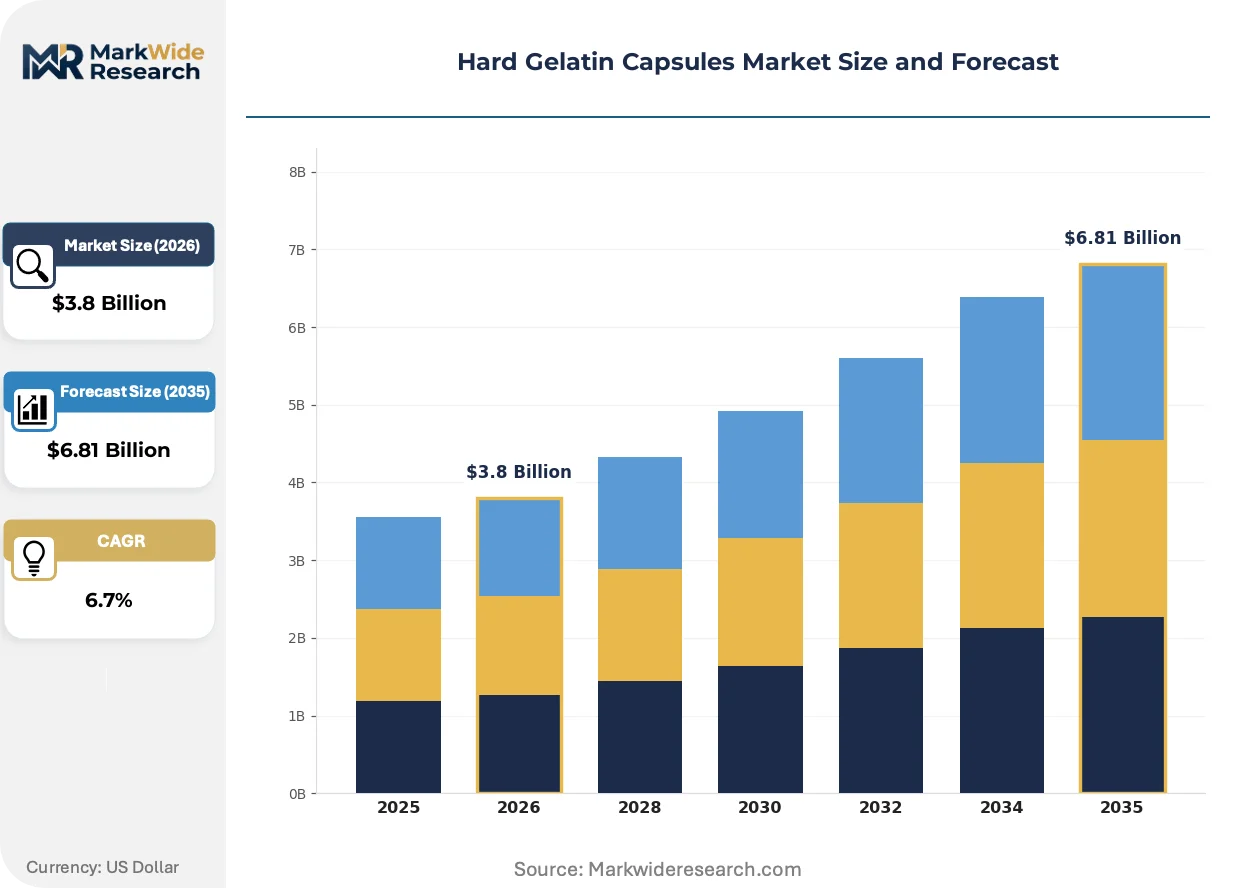
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Capsules, Liquid Capsules, Powder Capsules, Gel Capsules Application: Pharmaceuticals, Nutraceuticals, Dietary Supplements, Veterinary Products End User: Hospitals, Pharmacies, Home Care, Research Laboratories Size: Small, Medium, Large, Extra Large |
| Companies Covered | ACG Worldwide, Lonza, Qualicaps, CapsCanada Corporation, Suheung Co., Ltd., Catalent, Sunil Healthcare Ltd., Medi-Caps Ltd., Nector Lifesciences Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hard Gelatin Capsules Market Shifts & Advancements
Hard gelatin capsule manufacturing is bifurcating between commodity powder-fill volumes and specialized liquid-fill capabilities as formulation complexity rises and regulatory scrutiny intensifies across multiple pharmacopeial jurisdictions.
Automated vision inspection systems are migrating from post-fill quality control to real-time shell defect detection during dip-molding operations. European capsule molders deploy high-speed camera arrays at 0.1-millisecond capture rates to identify pinholes, wall thickness variations, and cap-body fit tolerances before shells reach filling lines. This shift compresses rework costs and reduces batch rejection rates at formulation houses.
EMA Medical Device Regulation reclassification of certain drug-device combination capsules imposes clinical evidence requirements previously reserved for standalone medical devices. Manufacturers of capsules incorporating built-in desiccants or modified-release inserts must now compile technical documentation under MDR Annex II. German and Swiss formulation houses report 18-month certification timelines for novel shell designs.
Formulation scientists increasingly specify capsule shell performance attributes rather than accepting standard pharmacopeial grades. Contract manufacturers in India and the United States now request dissolution profile matching, residual moisture customization, and extractables validation from shell suppliers. This specification elevation favors vertically integrated producers with in-house gelatin extraction and analytical capabilities.
Hard Gelatin Capsules Market Segmentation
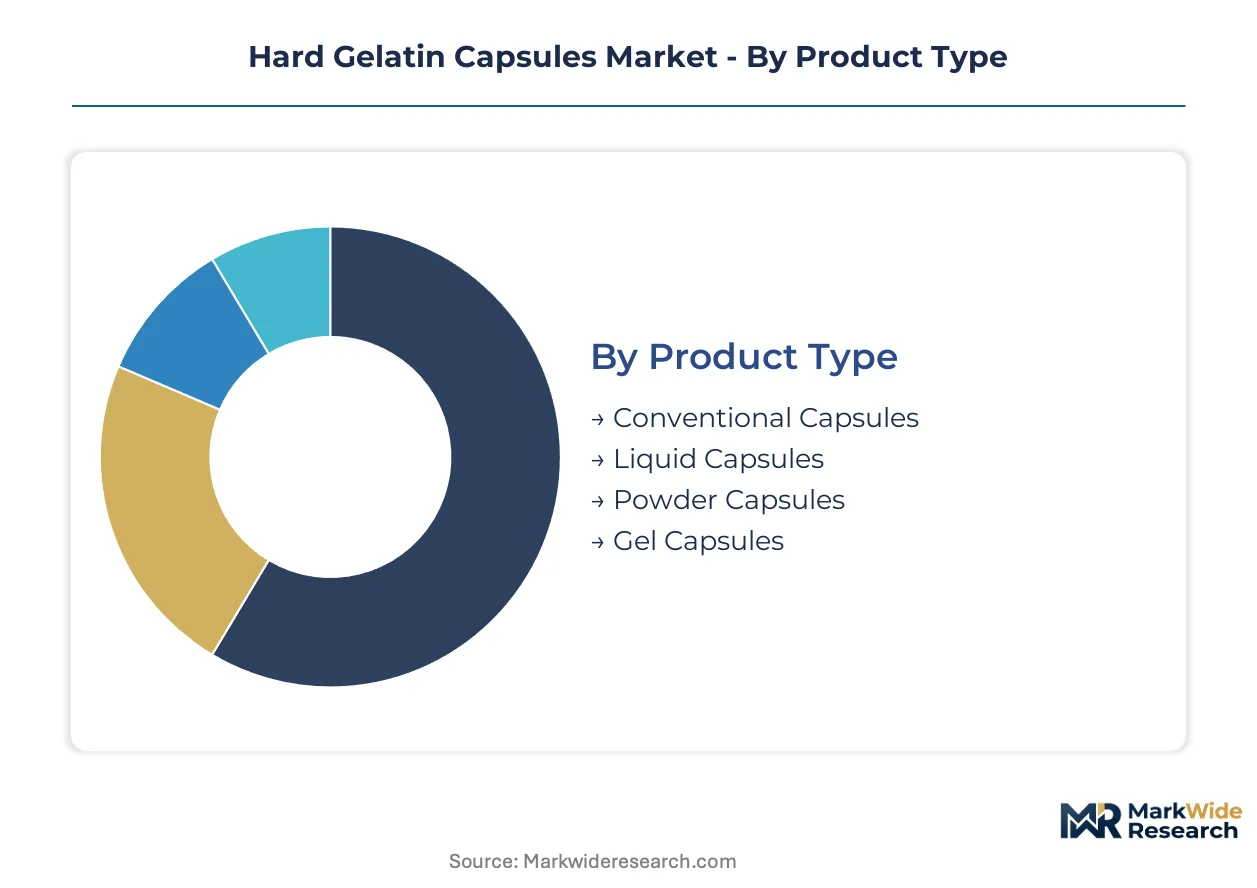
Hard gelatin capsule segmentation reflects divergent technical requirements across formulation types and end-use channels. Service intensity varies sharply between pharmaceutical contract manufacturing and retail nutraceutical distribution.
Product Type:
After-sales service intensity concentrates in liquid-fill and specialized capsule formats where formulation houses demand dissolution profile matching and extractables validation.
- Liquid Capsules:Lipid-filled shells accommodate poorly soluble APIs through lipid-based delivery systems. Demand concentrates in European oncology formulation pipelines as scientists abandon conventional tablet approaches for BCS Class II and IV compounds.
- Conventional Capsules:Two-piece powder-fill shells dominate volume shipments through mature tooling infrastructure and universal filling equipment compatibility. Pharmaceutical contract manufacturers across Gujarat and Hyderabad clusters source these for generic solid-dose production.
- Powder Capsules:Standard powder-fill formats sustain steady nutraceutical uptake despite clean-label substitution pressure from plant-derived alternatives in dietary supplement channels.
- Gel Capsules:Semi-solid fill variants occupy niche applications where thixotropic formulations require specialized shell moisture barriers.
By volume, Conventional Capsules leads. By growth pace, Liquid Capsules is ahead.
Application:
Cost tier stratification separates pharmaceutical-grade validation requirements from commodity nutraceutical sourcing.
- Pharmaceuticals:Prescription drug applications command premium pricing through FDA dissolution testing compliance and drug master file status requirements. CDMOs in India and Switzerland consolidate capacity around high-containment suites for potent compounds.
- Nutraceuticals:Clean-label positioning drives HPMC and pullulan substitution as buyers reject bovine and porcine gelatin inputs. This segment shows the steepest expansion trajectory for plant-derived alternatives.
- Dietary Supplements:Mass-market vitamin and mineral encapsulation favors conventional gelatin shells where price sensitivity outweighs origin labeling concerns.
- Veterinary Products:Animal health applications require modified shell formulations for palatability masking and rumen bypass delivery in ruminant dosing.
Pharmaceuticals captures the highest margin pool. Nutraceuticals faces the most rapid ingredient substitution.
End User:
Customer type determines packaging complexity and regulatory documentation depth.
- Hospitals:Institutional procurement favors unit-dose packaging with barcoded compliance tracking for medication administration safety.
- Pharmacies:Retail distribution channels demand bulk packaging flexibility and moisture-resistant secondary containers for shelf stability.
- Home Care:Direct-to-patient formats emphasize child-resistant closures and patient-friendly opening mechanisms for chronic therapy adherence.
- Research Laboratories:Clinical trial supply requires batch-level traceability and customizable fill weights for investigator-sponsored studies.
Pharmacies move the largest absolute volumes. Research Laboratories commands the highest per-unit service intensity.
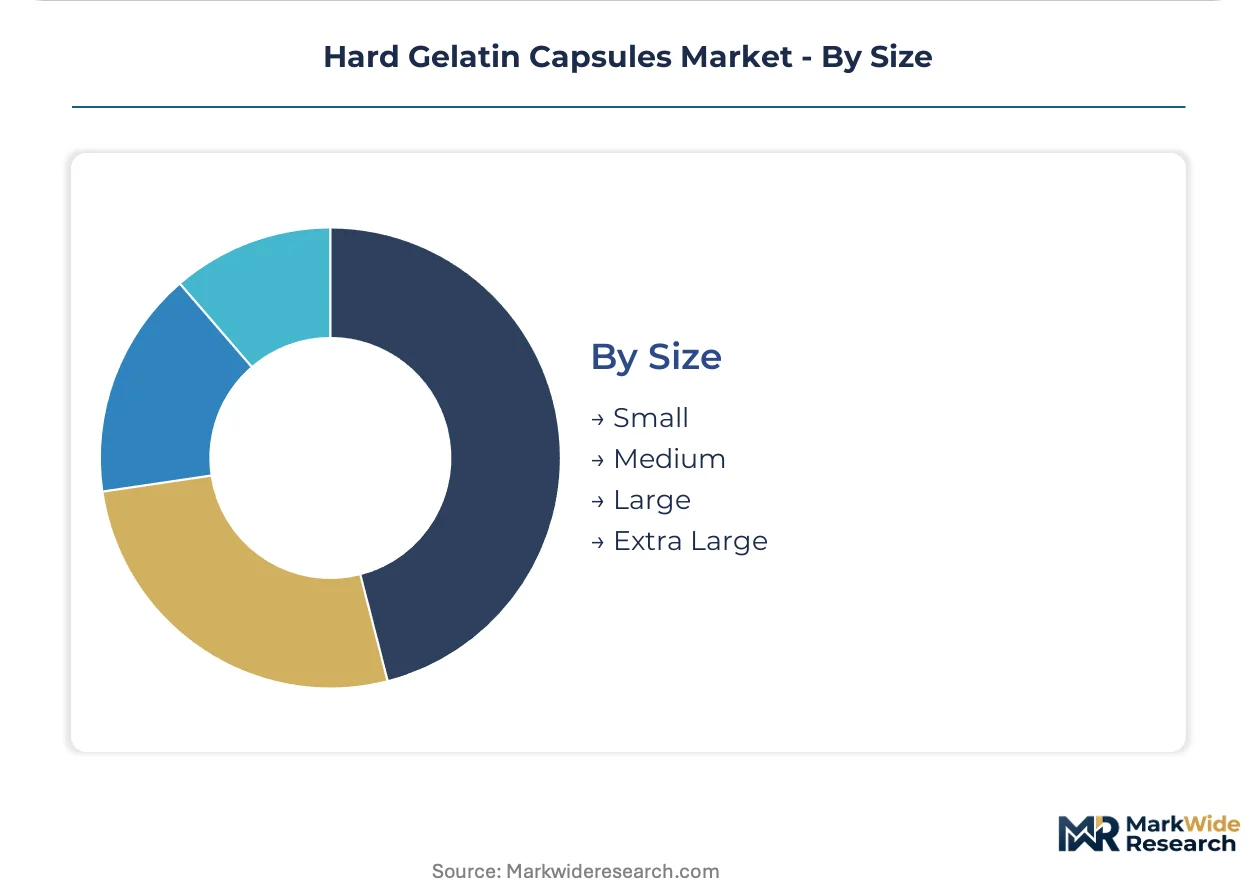
Size:
Volume scale inversely correlates with shell manufacturing complexity and tooling changeover frequency.
- Small:Sizes 3-5 accommodate high-potency APIs where milligram-level dosing precision is critical.
- Medium:Size 1 and 0 formats balance fill capacity with patient swallowability for most oral solid-dose applications.
- Large:Size 00 shells maximize powder volume for bulk nutraceutical formulations and veterinary bolus applications.
- Extra Large:Specialized size 000 and elongated formats serve unique veterinary and research compound requirements.
Medium sizes dominate prescription pharmaceutical volumes. Extra Large formats remain confined to niche veterinary and research channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for pharmaceuticals is redirecting API-to-finished-dose integration toward domestic capsule shell production. The United States FDA dissolution testing guidelines are tightening quality thresholds for immediate-release oral dosage forms. European REACH restrictions on chromium VI in gelatin processing are creating dual compliance burdens for exporters.
United States
Generic drug makers are building captive capsule supplies through direct-to-manufacturer channels. The FDA enforces dissolution profile consistency and extractable-leachable thresholds that elevate compliance costs for shell suppliers seeking drug master file status. Contract manufacturers in the Northeast and Midwest are consolidating capacity around high-containment suites for potent compound pipelines.
India
Domestic API-to-finished-dose integration is deepening across Gujarat and Hyderabad manufacturing clusters. The CDSCO aligns with ICH Q3D guidelines on elemental impurities, forcing manufacturers to validate gelatin sourcing from certified tannery regions. ACG Worldwide anchors South Asian demand through vertically integrated gelatin extraction and capsule molding operations across multiple states.
Germany
European oncology formulation pipelines are driving demand for liquid-fill hard gelatin capsules as scientists abandon conventional tablet approaches. The EMA Medical Device Regulation reclassification imposes clinical evidence requirements on drug-device combination capsules. German formulation houses report extended certification timelines for novel shell designs incorporating built-in desiccants.
Switzerland
High-containment capsule filling for potent compounds is differentiating CDMO portfolios from commodity suppliers. Swissmedic maintains stringent pharmacopeial standards that favor vertically integrated producers with in-house analytical capabilities. Basel and Zurich manufacturing clusters concentrate formulation houses demanding dissolution profile matching and residual moisture customization from shell suppliers.
China
Lipid-based formulation pipelines are expanding as poorly soluble APIs drive demand for liquid-fill capabilities. The NMPA enforces GB standards on gelatin processing that align with international pharmacopeial requirements. Yangtze River Delta manufacturing hubs are scaling automated vision inspection systems for real-time shell defect detection during dip-molding operations.
Hard Gelatin Capsules Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated gelatin-to-shell producers, specialized high-containment CDMOs, and regional commodity suppliers. The first tier captures margin through backward integration into certified tannery sourcing. The second tier commands premium pricing through potent compound handling capabilities. The third tier competes on volume for generic solid-dose production. Dominant competitive moves include capacity expansion in India and Switzerland, plus strategic partnerships between shell suppliers and European formulation houses.
Within the integrated producer tier, ACG Worldwide and Lonza exemplify contrasting geographic anchoring strategies. ACG Worldwide represents South Asian vertical integration through multi-state gelatin extraction and molding operations. Lonza occupies a position as a European-anchored network player securing long-term supply contracts through biopharma manufacturing integration. Catalent sits within the high-containment specialist archetype, differentiating on CDMO services for oncology and hormone pipelines rather than commodity shell production.
| Leading Market Players |
|---|
| ACG Worldwide |
| Lonza |
| Qualicaps |
| CapsCanada Corporation |
| Suheung Co., Ltd. |
| Catalent |
| Sunil Healthcare Ltd. |
| Medi-Caps Ltd. |
| Nector Lifesciences Ltd. |
| Others |
Supply & Pricing Matrix
The Mumbai-Rotterdam maritime corridor carries bovine gelatin feedstock and finished capsule shells, with freight cost volatility compressing margins for European formulation houses while amplifying price spreads between certified and uncertified suppliers. This logistics dynamic concentrates bargaining power with integrated producers controlling tannery-to-shell pipelines.
Pricing Analysis
Certification level creates the primary spread, with FDA drug master file status commanding premium positioning over uncertified commodity shells. Three-tier pricing structure separates pharmaceutical-grade validation from standard nutraceutical sourcing and economy veterinary grades. Cost compression in the commodity tier is intensifying because Indian PLI scheme recipients are scaling domestic gelatin extraction. Generic drug makers show highest price sensitivity; oncology CDMOs accept premium positioning for potent compound containment.
Supply Chain Analysis
REACH chromium VI restrictions limit gelatin processing equipment flows into European shell manufacturing, forcing dual certification investments from exporters. Supply concentrates in India, China, and Switzerland for pharmaceutical-grade production; Brazil and Argentina supply veterinary-grade gelatin. Raw material dependencies center on bovine hide collagen, porcine skin derivatives, and pharmaceutical-grade plasticizers. Single-source vulnerability runs through certified tannery regions in South Asia. Distribution runs through direct-to-manufacturer channels consolidating around captive capsule supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across formulation complexity tiers creates specialist niches as lipid-based pipelines diverge from commodity powder-fill demand. CDMOs, integrated producers, and regional suppliers now serve distinct buyer archetypes with incompatible capability requirements.
For Market Incumbents: Build regulatory moats through ICH Q3D-compliant tannery certification and drug master file status. ACG Worldwide and Lonza anchor positioning through backward integration into certified gelatin sourcing. Defend against HPMC substitution in nutraceuticals by securing pharmaceutical CDMO contracts with dissolution profile matching requirements. Prioritize high-containment suite investments for oncology pipeline capture.
For New Entrants and Emerging Players: Latin American veterinary capsule production offers white-space penetration with lower regulatory barriers than human pharmaceutical entry. Target Brazilian and Mexican animal health markets with modified-release rumen bypass formulations. Enter through toll manufacturing partnerships with established gelatin extractors rather than greenfield tannery investments. Capture margin in specialized sizes 3-5 for high-potency API precision dosing.
For Investors and Strategic Acquirers: High-containment CDMO specialists with isolator engineering capabilities represent priority acquisition targets as oncology pipelines expand. Long-term viability hinges on differentiation from commodity shell production through potent compound handling certification. Watch FDA dissolution testing guideline enforcement intensity as inflection signal for quality-tier repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Tannery Sourcing | CDSCO ICH Q3D alignment forces validated supply chains, elevating compliant domestic Indian suppliers. |
| High-Containment Suite Investment | Oncology and hormone pipeline expansion differentiates CDMO portfolios from commodity capsule fillers. |
| Liquid-Fill Capability Expansion | BCS Class II and IV API pipelines drive lipid-based formulation demand across European oncology houses. |
| Automated Vision Inspection Deployment | Real-time shell defect detection at 0.1-millisecond capture rates reduces batch rejection at formulation lines. |
| WHO Prequalification Pathway Pursuit | Emerging market procurement programs favor validated dossiers for HIV, TB, and malaria combination therapies. |
Research Methodology
The analysis maps liquid-fill, conventional powder-fill, and specialized containment capsule segments, each validated through interviews with pharmaceutical contract manufacturing executives, regulatory affairs directors at shell suppliers, formulation scientists at European oncology houses, and procurement managers at Indian generic drug makers. Secondary sources include FDA dissolution testing guidelines, CDSCO ICH Q3D implementation circulars, EMA Medical Device Regulation technical documentation requirements, and USP-NF monograph updates. Bottom-up capacity assessments triangulate against top-down prescription volume projections.
Assumptions held fixed include current regulatory enforcement intensity for elemental impurities and REACH chromium VI restrictions; varied parameters include lipid-based formulation pipeline growth rates and HPMC substitution velocity in nutraceutical channels. Segmentation dimensions span product type, application grade, end-user channel, and shell size tier. CAGRs derive from regression against pharmaceutical production indices and patent cliff timing for oral solid-dose conversions. Forecast inputs incorporate dissolution testing compliance cost trajectories and PLI scheme capacity addition schedules.
Practitioners should monitor FDA dissolution guideline amendment timing and CDSCO enforcement intensity for early signals of quality-tier repricing. Forecasts reflect these assumptions; material shifts in bovine gelatin price volatility or EMA MDR reclassification scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Traveler's Diarrhea Treatment Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market
Pharmaceuticals
Oncology Adjuvants Market