
 Prion Disease Treatment Market | 2026-2036
Prion Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Prion Disease Treatment Market Analytics
Hospital neurology departments is hardening as the dominant end-use channel for prion therapeutics amid expanding referral networks for Creutzfeldt-Jakob disease and variant CJD cases. Ionis Pharmaceuticals leverages antisense oligonucleotide platforms to target prion protein suppression at the genetic level. Biogen anchors its position through deep R&D intensity in neurodegenerative modalities, while F. Hoffmann-La Roche Ltd competes via global clinical trial infrastructure and biomarker integration.
Prion disease treatment encompasses therapeutic interventions targeting transmissible spongiform encephalopathies caused by misfolded prion protein (PrP^Sc) accumulation, primarily involving monoclonal antibodies that bind native prion protein, small-molecule inhibitors of protein aggregation, and gene-silencing technologies that reduce PrP^C expression to prevent pathological conversion. Antibodies command the largest current revenue pool due to established manufacturing scale and infusion infrastructure, while immunotherapies represent the fastest-expanding segment as bispecific constructs and CAR-T adaptations enter early-phase development. Intravenous delivery dominates hospital settings, though subcutaneous formulations are gaining traction for outpatient chronic administration in specialized clinics.
FDA orphan drug designation and EMA PRIME eligibility criteria shape trial enrollment strategies and accelerate review timelines for prion disease candidates. The EU AI Act and GDPR impose data governance requirements on neuroimaging and biomarker datasets used in predictive diagnostics. WHO prion disease surveillance guidelines harmonize case reporting standards across national reference laboratories. Stakeholders must monitor regulatory precedent for adaptive trial designs in ultra-rare neurodegenerative indications.
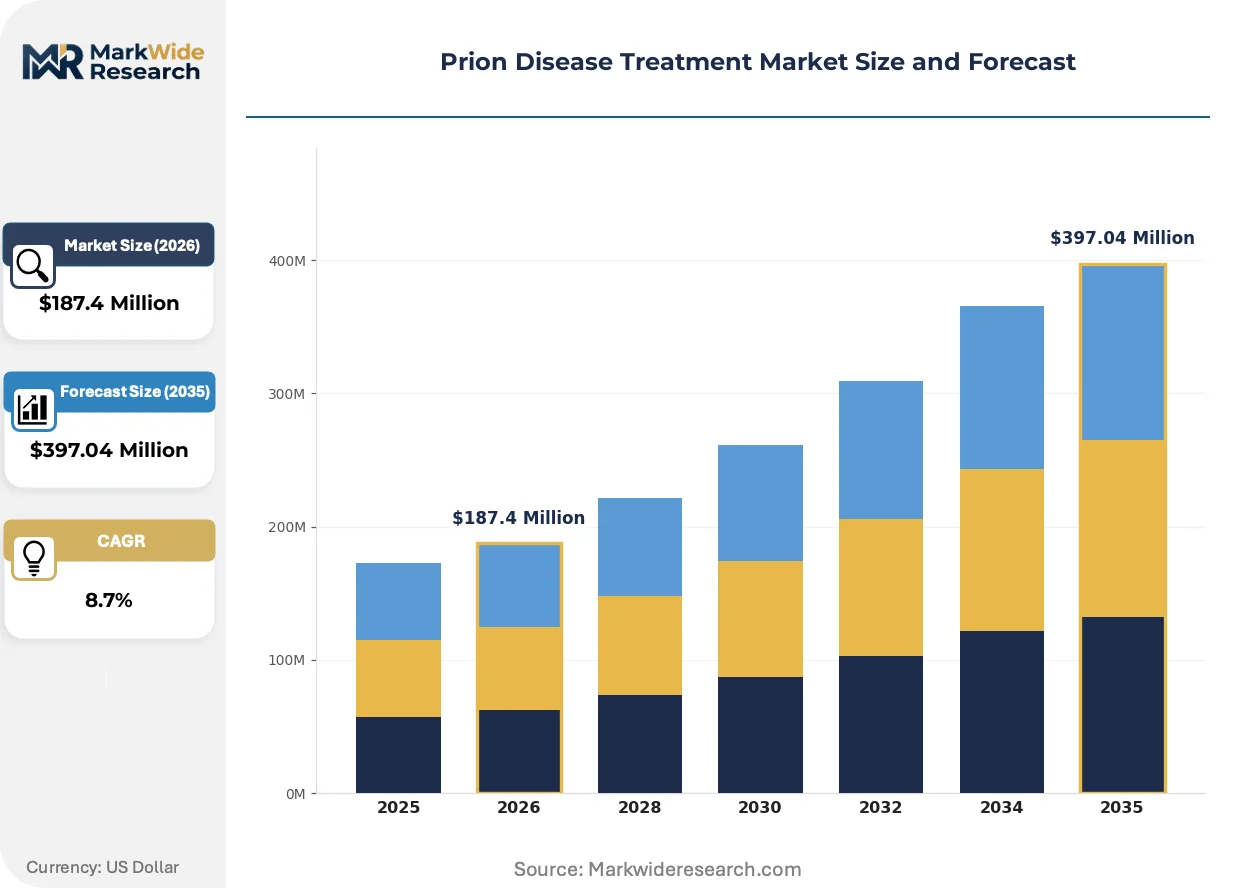
Market Dynamics
FDA orphan drug incentives and EMA accelerated assessment pathways are compressing development timelines for ultra-rare neurodegenerative therapeutics, while hospital neurology departments consolidate procurement authority through specialized Creutzfeldt-Jakob disease referral networks.
Growth Catalysts
- Orphan drug frameworks:FDA designation and EMA PRIME eligibility reduce regulatory friction for prion protein suppression therapies. Developers gain tax credits and waived user fees.
- Antisense oligonucleotide platforms:Gene-silencing technologies targeting PrP^C expression are advancing through clinical pipelines with validated biomarker endpoints.
- Japan's prion surveillance infrastructure:The country's national brain bank network and PMDA consultation pathways accelerate patient identification and trial enrollment.
Market Restraints
- Ultra-rare disease economics:Creutzfeldt-Jakob disease incidence of approximately one case per million population limits commercial scalability for therapeutic developers.
- Biomaterial supply concentration:High-purity prion protein reagents and specialized cerebrospinal fluid collection media depend on German and Swiss specialty chemical suppliers.
- Blood screening deferrals:FDA and EMA precautionary deferral policies for variant CJD create permanent exclusion of certain donor populations, constraining research biosample availability.
Strategic Opportunities
- Germany's academic medical center networks:Underpenetrated referral pathways in Bavaria and Baden-Württemberg offer expansion potential for specialized prion disease clinics.
- Subcutaneous formulation development:Outpatient administration models for chronic prion protein suppression therapies could displace hospital-centric infusion dependencies.
- EU AI Act compliance infrastructure:Predictive diagnostic platforms using neuroimaging biomarkers require governed data architectures, creating service revenue for certified analytics providers.
Industry Challenges
- Neurodegenerative clinical trial expertise:Principal investigators with prion disease protocol experience are concentrated at fewer than twelve academic medical centers across the United States, Germany, and Japan.
- Adaptive trial design validation:Regulatory precedent for seamless phase transitions in rapidly fatal conditions remains underdeveloped, requiring extensive agency negotiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prion Disease Treatment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Enzyme Inhibitors, Antiviral Agents, Immunotherapies Therapy Area: Neurodegenerative Disorders, Inflammatory Conditions, Infectious Diseases, Protein Misfolding Disorders Delivery Mode: Intravenous, Oral, Subcutaneous, Intra-thecal End User: Hospitals, Research Institutions, Specialized Clinics, Home Care |
| Companies Covered | Ionis Pharmaceuticals Inc, Prionics AG, Biogen Inc, Pfizer Inc, Novartis AG, Amgen Inc, F. Hoffmann-La Roche Ltd, CureVac AG, Sangamo Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prion Disease Treatment Market Evolving Landscape
Antisense oligonucleotide delivery systems and bispecific antibody constructs are displacing first-generation monoclonal approaches in prion therapeutic development, while regulatory frameworks evolve to accommodate ultra-rare disease trial designs.
Gene-silencing technologies targeting prion protein messenger RNA are integrating lipid nanoparticle delivery systems to achieve sustained central nervous system penetration. Hospital-based neurology departments in the United States and Germany are prioritizing these platforms for early-phase trials. The technology is integrating with established infusion infrastructure while compressing development timelines through biomarker-guided adaptive protocols.
EMA PRIME eligibility criteria and FDA breakthrough therapy designation are converging to create harmonized accelerated pathways for prion disease candidates. Developers gain parallel scientific advice and rolling review privileges that compress regulatory lag. European sponsors are responding by centralizing quality management systems to satisfy both GDPR neuroimaging data requirements and EU AI Act algorithmic transparency mandates.
Hospital procurement committees are consolidating therapeutic evaluation authority through specialized neurodegenerative disease formulary carve-outs. Academic medical centers in Japan and Germany are displacing general neurology purchasing with dedicated prion disease program budgets. This concentration is most visible in the United States, where National Prion Disease Pathology Surveillance Center affiliations determine institutional access to investigational therapies.
Prion Disease Treatment Market Segmentation
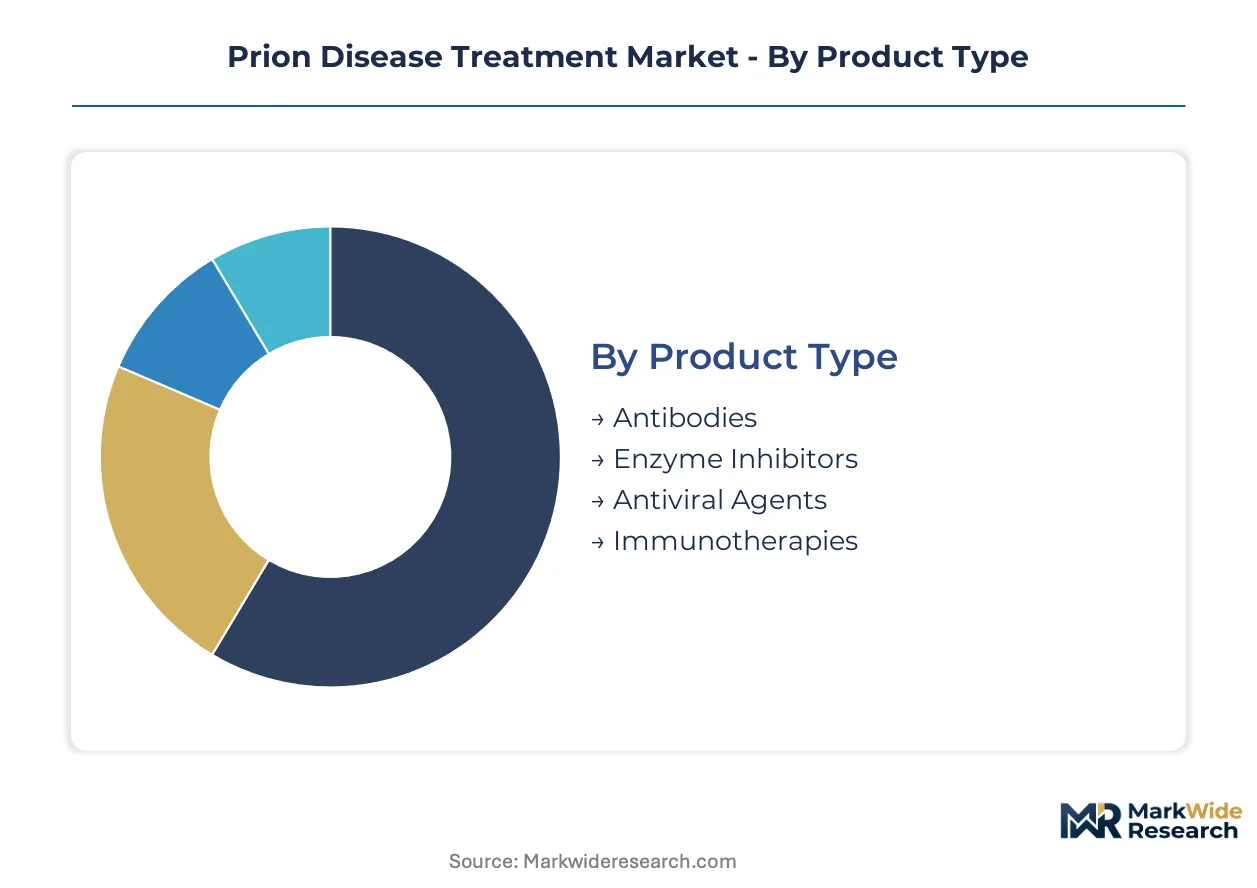
Prion disease treatment modalities span distinct technical platforms and care settings, each commanding differentiated development priorities and procurement pathways. Therapeutic developers align pipeline investments with specific delivery constraints and end-user infrastructure capabilities.
Product Type:
Replacement of first-generation protein-binding agents with gene-silencing platforms is redrawing competitive boundaries across therapeutic categories.
- Antibodies:Monoclonal constructs targeting native prion protein (PrP^C) leverage established biologics manufacturing scale and hospital infusion infrastructure. Demand concentrates in United States academic medical centers with National Prion Disease Pathology Surveillance Center affiliations, where referral networks for Creutzfeldt-Jakob disease cases drive protocol enrollment.
- Immunotherapies:Bispecific constructs and CAR-T adaptations represent emerging modalities with potential for enhanced blood-brain barrier penetration. Japanese hospital neurology departments are prioritizing these platforms for early-phase trials through PMDA consultation pathways.
- Enzyme Inhibitors:Small-molecule compounds targeting protein aggregation pathways require specialized formulation expertise from German and Swiss specialty chemical suppliers.
- Antiviral Agents:Repurposed nucleoside analogs with demonstrated prion protein suppression activity in preclinical models.
Volume placements concentrate in Antibodies; the faster expansion belongs to Immunotherapies.
Therapy Area:
Cost tier differentiation separates premium genetic intervention approaches from established symptomatic management protocols.
- Neurodegenerative Disorders:Creutzfeldt-Jakob disease and variant CJD represent the primary addressable population, with antisense oligonucleotide platforms advancing through clinical pipelines. Germany's national brain bank network accelerates patient identification for these trials.
- Protein Misfolding Disorders:Broader mechanistic category encompassing Alzheimer's and Parkinson's disease adjacencies where prion protein propagation hypotheses inform therapeutic design. Research institutions in Bavaria and Baden-Württemberg are expanding specialized clinic capacity for these indications.
- Inflammatory Conditions:Neuroinflammatory pathways secondary to prion protein accumulation.
- Infectious Diseases:Iatrogenic and variant CJD transmission prevention protocols.
Revenue concentration sits with Neurodegenerative Disorders; Protein Misfolding Disorders are climbing the fastest as platform technologies expand addressable mechanisms.
Delivery Mode:
Application requirements dictate route selection, with chronic administration needs driving formulation innovation toward patient-directed modalities.
- Intravenous:Dominates hospital-based administration for monoclonal antibody and enzyme inhibitor therapies, leveraging existing oncology infusion infrastructure. United States hospital neurology departments consolidate procurement authority through specialized neurodegenerative disease formulary carve-outs.
- Subcutaneous:Outpatient administration models for chronic prion protein suppression therapies are displacing hospital-centric dependencies. Japanese specialized clinics are piloting these protocols to reduce institutional bed utilization.
- Oral:Small-molecule inhibitors with blood-brain barrier penetration requirements.
- Intra-thecal:Direct central nervous system delivery for antisense oligonucleotide platforms requiring bypass of systemic circulation.
Procurement volume clusters in Intravenous; Subcutaneous formulations are gaining share fastest through outpatient chronic administration models.
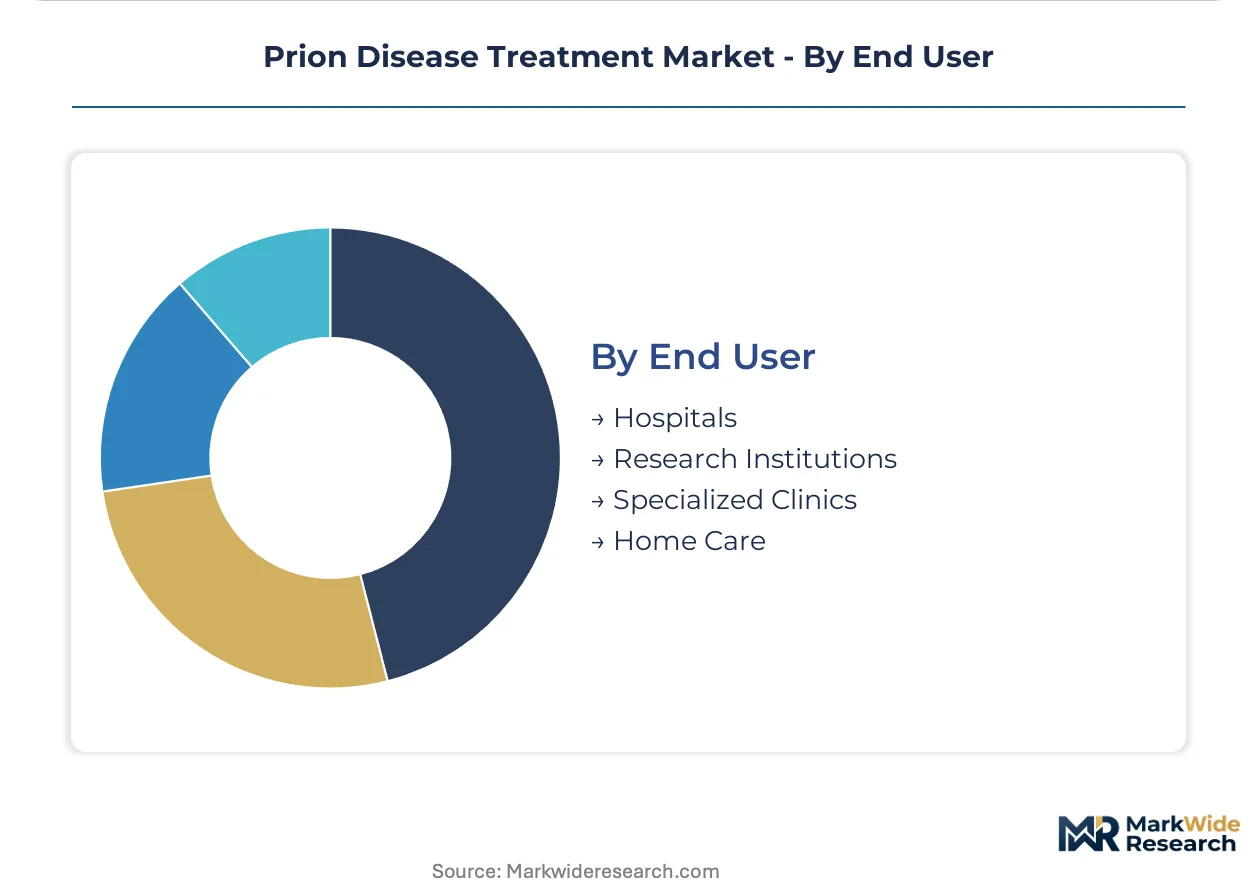
End User:
Customer type stratification reflects divergent purchasing authority and clinical trial access tiers across care settings.
- Hospitals:Academic medical centers with prion surveillance network affiliations control investigational therapy access and specialized referral pathways. Fewer than twelve centers across the United States, Germany, and Japan concentrate principal investigator expertise.
- Research Institutions:National brain banks and prion surveillance networks in Japan and Germany supply biosamples and biomarker validation infrastructure. FDA and EMA precautionary blood screening deferrals for variant CJD constrain sample availability from certain donor populations.
- Specialized Clinics:Dedicated prion disease programs with dedicated budgets displacing general neurology purchasing.
- Home Care:Emerging category dependent on subcutaneous formulation maturation and reimbursement pathway development.
Therapeutic volume flows through Hospitals; Specialized Clinics are expanding most quickly as regional referral networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug tax credits and EMA PRIME fee waivers are concentrating therapeutic development in specialized economic zones with established neurodegenerative research infrastructure.
United States
The National Prion Disease Pathology Surveillance Center in Cleveland anchors patient identification and biosample collection for clinical trials. FDA breakthrough therapy designation compresses review timelines for antisense oligonucleotide candidates. Academic medical centers in Boston and Baltimore concentrate principal investigator expertise for adaptive protocol designs.
Germany
Bavaria's national brain bank network accelerates biomarker validation and post-mortem diagnostic confirmation for Creutzfeldt-Jakob disease cases. EMA centralized procedure pathways harmonize market access across member states for orphan-designated therapies. Baden-Württemberg's academic medical centers in Heidelberg and Tübingen expand specialized clinic capacity for protein misfolding disorders.
Japan
PMDA consultation pathways provide scientific advice for gene-silencing platform developers prior to formal submission. The country's prion surveillance infrastructure identifies variant CJD cases through mandatory neuropathological examination. Tokyo and Osaka hospital neurology departments pilot subcutaneous administration protocols to reduce institutional bed utilization.
Switzerland
Swissmedic's accelerated assessment framework aligns with EMA procedures for ultra-rare neurodegenerative indications. Basel's pharmaceutical cluster hosts contract manufacturing organizations specializing in high-purity prion protein reagents. Zurich's university hospital network supplies cerebrospinal fluid collection media for biomarker-guided trials.
United Kingdom
The National CJD Research and Surveillance Unit in Edinburgh coordinates case reporting and tissue archive management across the devolved health systems. MHRA rolling review mechanisms mirror FDA breakthrough designation timelines for promising candidates. London's specialized neurology centers consolidate referral pathways for sporadic CJD cases from England and Wales.
Prion Disease Treatment Market Competitive Landscape
Top-tier vendors anchor antisense platform development, while mid-tier specialists concentrate on diagnostic reagents and biomarker services. The competitive structure reflects deep R&D intensity requirements and ultra-rare disease economics that favor concentrated expertise over broad portfolios. Three archetypes dominate: gene-silencing platform developers, monoclonal antibody manufacturers with established infusion infrastructure, and specialized diagnostic suppliers. Consolidation through strategic partnerships and technology licensing agreements is displacing standalone development models.
Among antisense platform specialists, Ionis Pharmaceuticals Inc represents the gene-silencing archetype with validated messenger RNA suppression approaches. Biogen Inc and F. Hoffmann-La Roche Ltd occupy positions within the neurodegenerative therapeutic tier, leveraging global clinical trial infrastructure and biomarker integration capabilities. These three companies exemplify the R&D intensity and regulatory navigation skills required for prion protein suppression therapy development.
| Leading Market Players |
|---|
| Ionis Pharmaceuticals Inc |
| Prionics AG |
| Biogen Inc |
| Pfizer Inc |
| Novartis AG |
| Amgen Inc |
| F. Hoffmann-La Roche Ltd |
| CureVac AG |
| Sangamo Therapeutics |
| Others |
Value Network & Pricing Analysis
Venture-backed gene-silencing specialists and family-owned diagnostic reagent producers anchor supply-side pricing discipline through captive manufacturing of high-purity prion protein reagents. Their concentrated ownership structures limit price transparency and reinforce premium positioning for antisense oligonucleotide platforms.
Pricing Analysis
Short lead-time premiums for specialized cerebrospinal fluid collection media and diagnostic-grade prion protein reagents command substantial markups over standard biologics inputs. Contract-based long-term offtake agreements dominate antibody manufacturing, with price differentiation driven by FDA orphan drug certification tier and geographic delivery cost to academic medical centers. Cost compression in first-generation monoclonal antibody therapies is intensifying because biosimilar competition encroaches on established infusion protocols. Research institutions exhibit highest price sensitivity due to constrained National Institutes of Health funding cycles, while hospital neurology departments with specialized formulary carve-outs demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for lipid nanoparticle delivery systems and high-purity prion protein reagents mandate multi-supplier qualification across German, Swiss, and Japanese specialty chemical manufacturers. Raw material dependencies center on synthetic nucleic acid building blocks, recombinant prion protein expression systems, and GMP-grade cerebrospinal fluid collection media. Single-source vulnerability in antisense oligonucleotide synthesis capacity creates structural exposure for pipeline developers. Distribution runs through hospital-based pharmacy procurement committees with National Prion Disease Pathology Surveillance Center affiliations, consolidating access to investigational therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where ultra-rare disease economics and concentrated principal investigator expertise force subscale developers toward strategic exits. Regulatory navigation capabilities and biomarker validation infrastructure separate viable platforms from stranded assets.
For Market Incumbents: Cement control over antisense oligonucleotide manufacturing capacity through backward integration into lipid nanoparticle production. Lock in exclusive cerebrospinal fluid collection partnerships with Japan's national brain bank network to preempt competitor biomarker access. Gene-silencing platform substitution threats from CRISPR-based approaches demand accelerated adaptive trial enrollment to establish clinical precedent. For New Entrants and Emerging Players: Enter via Bavaria and Baden-Württemberg's underpenetrated academic medical center networks, where specialized prion disease clinic capacity expansion outpaces incumbent coverage. Target subcutaneous formulation development for outpatient chronic administration, displacing hospital-centric infusion dependencies. Partner with German national brain bank infrastructure to secure biomarker validation credibility ahead of formal regulatory submission. For Investors and Strategic Acquirers: FDA breakthrough therapy designation awards to prion protein suppression candidates is the leading indicator that platform technologies have achieved investable de-risking thresholds. Five-to-ten-year viability hinges on antisense oligonucleotide developers with validated central nervous system penetration and established EMA PRIME eligibility. Watch for PMDA consultation pathway initiations in Japan as the earliest signal of competitive pipeline maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Advancement | EMA PRIME eligibility compresses review timelines for ultra-rare neurodegenerative candidates. |
| Biomarker-Guided Protocol Development | National brain bank partnerships in Germany validate surrogate endpoints for accelerated approval. |
| Subcutaneous Formulation Scale-Up | Outpatient administration models reduce hospital bed utilization in Japanese specialized clinics. |
| Orphan Drug Designation Pathway | FDA tax credits and waived user fees improve economics for prion protein suppression therapies. |
| Diagnostic Companion Development | Predictive neuroimaging platforms require EU AI Act compliance infrastructure for market access. |
Research Methodology
Document review covered FDA orphan drug designation databases, EMA PRIME eligibility records, ClinicalTrials.gov prion disease protocol registrations, and national brain bank annual reports, complemented by interviews with drug development executives at gene-silencing platform developers, regulatory affairs leads navigating EMA centralized procedures, hospital procurement managers at academic medical centers with National Prion Disease Pathology Surveillance Center affiliations, and formulary directors specializing in neurodegenerative disease carve-outs. Bottom-up patient population estimates for Creutzfeldt-Jakob disease incidence across the United States, Germany, and Japan were triangulated against top-down therapeutic revenue projections.
Segment-level outputs across antibodies, immunotherapies, enzyme inhibitors, and antiviral agents were generated through the projection horizon, with delivery mode stratification capturing intravenous, subcutaneous, oral, and intra-thecal administration routes. CAGRs were derived from modeled adoption curves for antisense oligonucleotide platforms and established monoclonal antibody infusion protocols. Forecast inputs incorporated PMDA consultation pathway progression rates and EMA accelerated assessment award frequencies as leading indicators of regulatory lag compression.
Revisions become necessary when FDA blood screening deferral policies expand to additional donor populations, EMA PRIME eligibility criteria shift toward adaptive trial validation requirements, or antisense oligonucleotide manufacturing capacity constraints materialize beyond current German and Swiss specialty chemical supplier projections. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Anemia Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market