
 Motion Sickness Treatment Market | 2026-2036
Motion Sickness Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Sickness Treatment Market Analysis
The capital-intensity divergence between large pharmaceutical manufacturers and specialty consumer health firms is rotating competitive dynamics toward scale-dependent R&D platforms. GlaxoSmithKline Plc leverages its established antihistamine portfolio to sustain shelf presence across retail pharmacy chains. Novartis AG anchors its position through prescription-grade scopolamine formulations that dominate hospital and clinical settings. Prestige Consumer Healthcare Inc. competes aggressively in the OTC aisle with private-label and branded alternatives.
Motion sickness treatment encompasses pharmacological and non-pharmacological interventions designed to prevent or alleviate nausea, vomiting, and autonomic disturbances triggered by perceived sensory conflict during movement; scopolamine transdermal patches deliver 1.0 mg over 72 hours through controlled membrane diffusion, while dimenhydrinate and meclizine tablets function as H1 receptor antagonists with central anticholinergic properties. The medications category occupies the largest revenue pool due to established reimbursement and physician familiarity, though transdermal delivery is gaining traction among frequent travelers seeking prolonged prophylaxis without sedation. Gaming applications represent the fastest-expanding segment as virtual reality headset proliferation exposes new user populations to visually induced motion sickness.
The FDA's OTC monograph reform is tightening documentation requirements for antihistamine safety profiles, while the EMA's pharmacovigilance framework demands enhanced post-market surveillance for transdermal scopolamine products. China's NMPA is accelerating generic approval timelines for motion sickness therapies as domestic manufacturers scale GMP-certified production. Stakeholders must monitor how regulatory divergence across these jurisdictions reshapes formulation strategies and market access investments.
Market Dynamics
The FDA's OTC monograph reform is compressing product development timelines for antihistamine-based therapies while simultaneously elevating documentation burdens for new entrants, fundamentally restructuring how manufacturers allocate R&D capital across formulation platforms.
Growth Catalysts
- Virtual reality headset proliferation:Gaming and simulation sectors are exposing millions of new users to visually induced motion sickness, expanding the addressable population beyond traditional travel contexts.
- China's high-speed rail network expansion:Domestic tourism corridors now incorporate routes with sustained acceleration profiles that trigger sensory conflict in susceptible passengers.
- EMA pharmacovigilance framework:Enhanced post-market surveillance requirements for transdermal scopolamine are validating long-term safety profiles and reinforcing physician confidence in prescription-grade prophylaxis.
Market Restraints
- Active pharmaceutical ingredient concentration:Scopolamine production relies on a narrow supplier base concentrated in specific cultivation regions, exposing finished goods manufacturers to agricultural yield volatility.
- Sedation liability of first-generation antihistamines:Dimenhydrinate's cognitive impairment profile limits its utility for operators of vehicles or machinery, constraining addressable use cases.
- Generic substitution pressure:China's NMPA accelerated approval timelines have flooded domestic markets with low-cost alternatives, compressing margin structures for originator formulations.
Strategic Opportunities
- Underpenetrated maritime worker segment:Commercial fishing and offshore energy operations in Brazil represent a concentrated occupational exposure population with limited access to prescription prophylaxis.
- Non-pharmacological device convergence:Wearable neuromodulation technologies paired with biofeedback applications are creating combination therapy protocols that reduce medication dependence.
- Cruise line formulary expansion:Onboard pharmacy inventories are upgrading from emergency rescue dosing to pre-emptive passenger amenity programs, opening direct procurement channels.
Industry Challenges
- Formulation scientist scarcity:Transdermal membrane engineering expertise resides within a limited cohort of specialists, constraining pipeline velocity for controlled-release innovations.
- Dual regulatory pathway complexity:Products positioned between OTC and prescription status must satisfy divergent evidentiary standards across FDA, EMA, and NMPA jurisdictions simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Sickness Treatment Market |
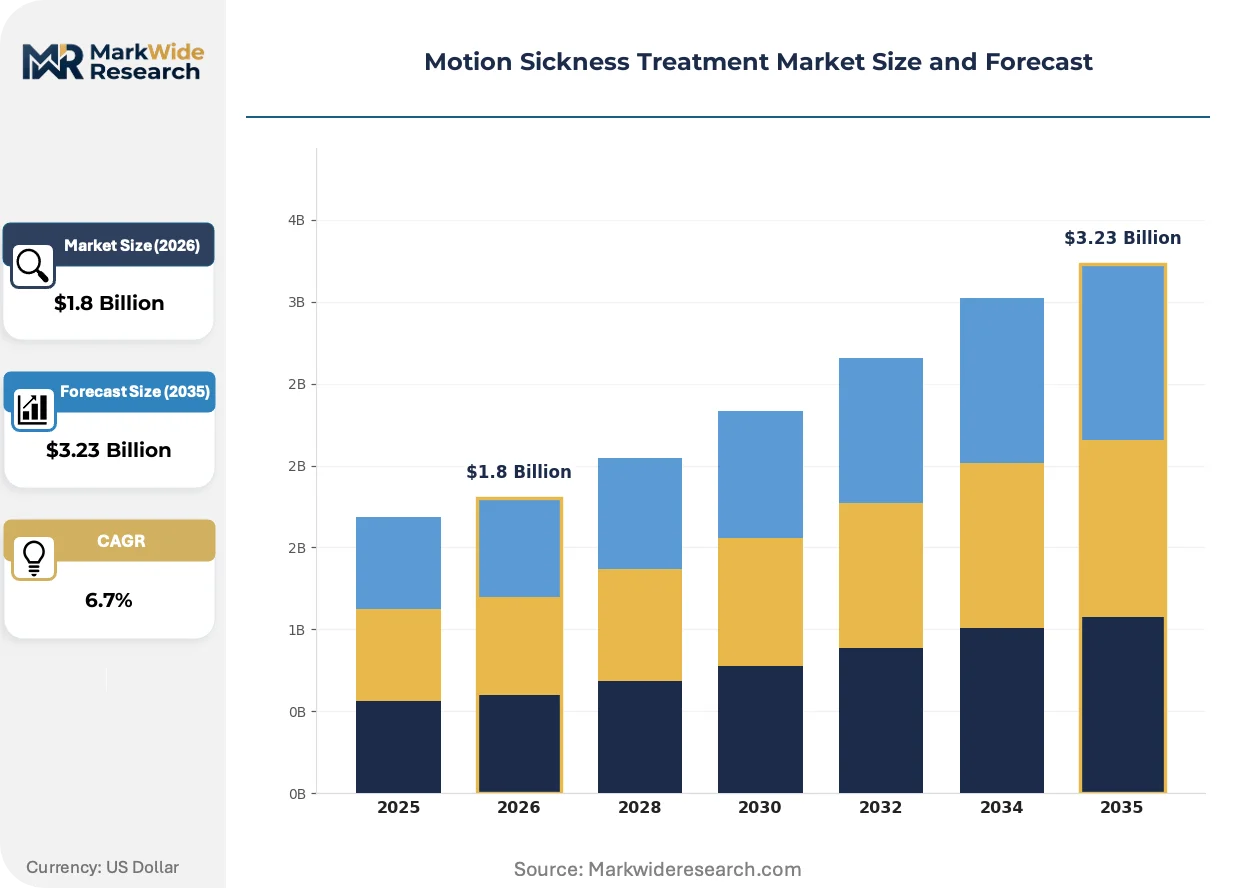
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Patches, Tablets, Sprays Application: Air Travel, Sea Travel, Vehicle Use, Gaming End User: Adults, Children, Pregnant Women, Elderly Delivery Mode: Oral, Transdermal, Injectable, Inhalation |
| Companies Covered | Prestige Consumer Healthcare Inc., GlaxoSmithKline Plc, Novartis AG, Teva Pharmaceutical Industries Ltd., Viatris Inc., Baxter International Inc., Sun Pharmaceutical Industries Ltd., WellSpring Pharmaceutical Corporation, Perrigo Company Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Sickness Treatment Market Emerging Trajectories
Transdermal delivery platforms are capturing share from oral formulations as travelers prioritize sustained prophylaxis without sedation, while regulatory convergence efforts are harmonizing safety documentation requirements across major jurisdictions.
Acupressure wristbands incorporating electrical stimulation are displacing pharmacological interventions among frequent business travelers who face employer restrictions on cognitive impairment. Corporate travel managers at Fortune 500 firms are mandating non-sedating alternatives for road warrior populations. The displacement is compressing revenue per user for antihistamine tablets while expanding the total addressable market for device-based prophylaxis.
REACH registration requirements for excipients used in transdermal patches are forcing reformulation of legacy adhesive systems across European manufacturing operations. ECHA substance evaluation workflows have flagged plasticizer compounds previously considered GRAS, triggering substitution programs. Small and mid-sized generic manufacturers without dedicated regulatory affairs capabilities are exiting the EU market rather than absorbing compliance costs.
Subscription-based replenishment models for transdermal patches are displacing episodic pharmacy purchases among cruise line loyalty program members and airline frequent flyers. Direct-to-consumer channels are capturing travelers who previously relied on airport convenience retail or onboard medical centers. The shift is most visible in US and UK markets where telehealth platforms have integrated motion sickness consultation into broader travel medicine services.
Motion Sickness Treatment Market Segmentation
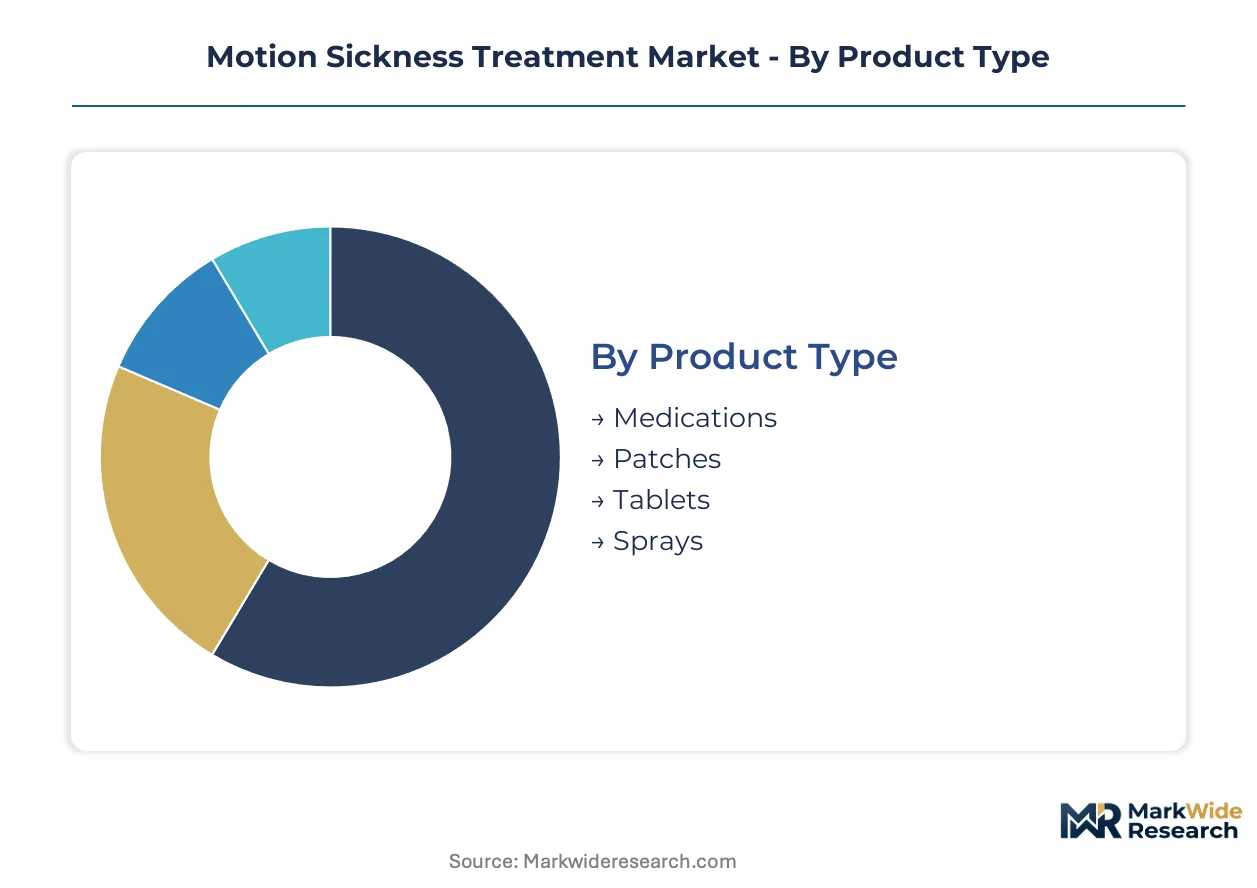
Segmentation in the motion sickness treatment market reveals divergent margin structures across delivery technologies and user populations. Manufacturers allocate R&D capital based on where reimbursement pathways and direct-to-consumer channels intersect with formulation complexity.
Product Type:
Margin pools concentrate in controlled-release formats where patent protection and manufacturing complexity limit generic substitution.
- Medications:Oral antihistamines and anticholinergics dominate prescription volumes through established physician familiarity. Demand concentrates in US retail pharmacy chains where FDA OTC monograph reform has streamlined entry for dimenhydrinate and meclizine formulations.
- Patches:Transdermal scopolamine systems deliver 1.0 mg over 72 hours through membrane-controlled diffusion. Adoption is climbing fastest among cruise line operators upgrading onboard pharmacy inventories to pre-emptive passenger amenity programs.
- Tablets:Compact oral dosage forms serve acute rescue dosing scenarios.
- Sprays:Nasal delivery systems target rapid onset for aviation and maritime emergency protocols.
Tablets hold installed capacity. Patches are rotating up the share rankings.
Application:
Volume concentration tracks transportation infrastructure expansion and emerging technology adoption curves.
- Air Travel:Commercial aviation exposes passengers to sustained linear acceleration and turbulence profiles. Demand concentrates in China where domestic tourism corridors multiply flight frequency on high-traffic routes.
- Gaming:Virtual reality headset proliferation exposes millions to visually induced sensory conflict. This segment is expanding most quickly as hardware manufacturers bundle prophylaxis recommendations with device documentation.
- Sea Travel:Maritime contexts generate severe symptoms due to multi-axis motion.
- Vehicle Use:Personal automotive and high-speed rail exposure drives OTC purchase patterns.
Sea Travel anchors historical revenue. Gaming is gaining share fastest.
End User:
Safety documentation requirements and dosing precision drive formulation differentiation across physiological vulnerability profiles.
- Adults:The largest addressable population with established tolerance for first-generation antihistamine sedation. Procurement concentrates through employer-sponsored travel medicine programs and direct-to-consumer subscription channels.
- Children:Pediatric formulations require weight-based dosing and palatability engineering. Regulatory scrutiny from FDA and EMA elevates development costs while limiting competitive entry.
- Pregnant Women:Teratogenicity concerns restrict pharmacological options to non-sedating alternatives.
- Elderly:Polypharmacy interactions and cognitive impairment liability constrain anticholinergic use.
Adults command current volume. Children represent the steepest expansion trajectory.
Delivery Mode:
Manufacturing capital allocation follows where bioavailability engineering intersects with patient compliance preferences.
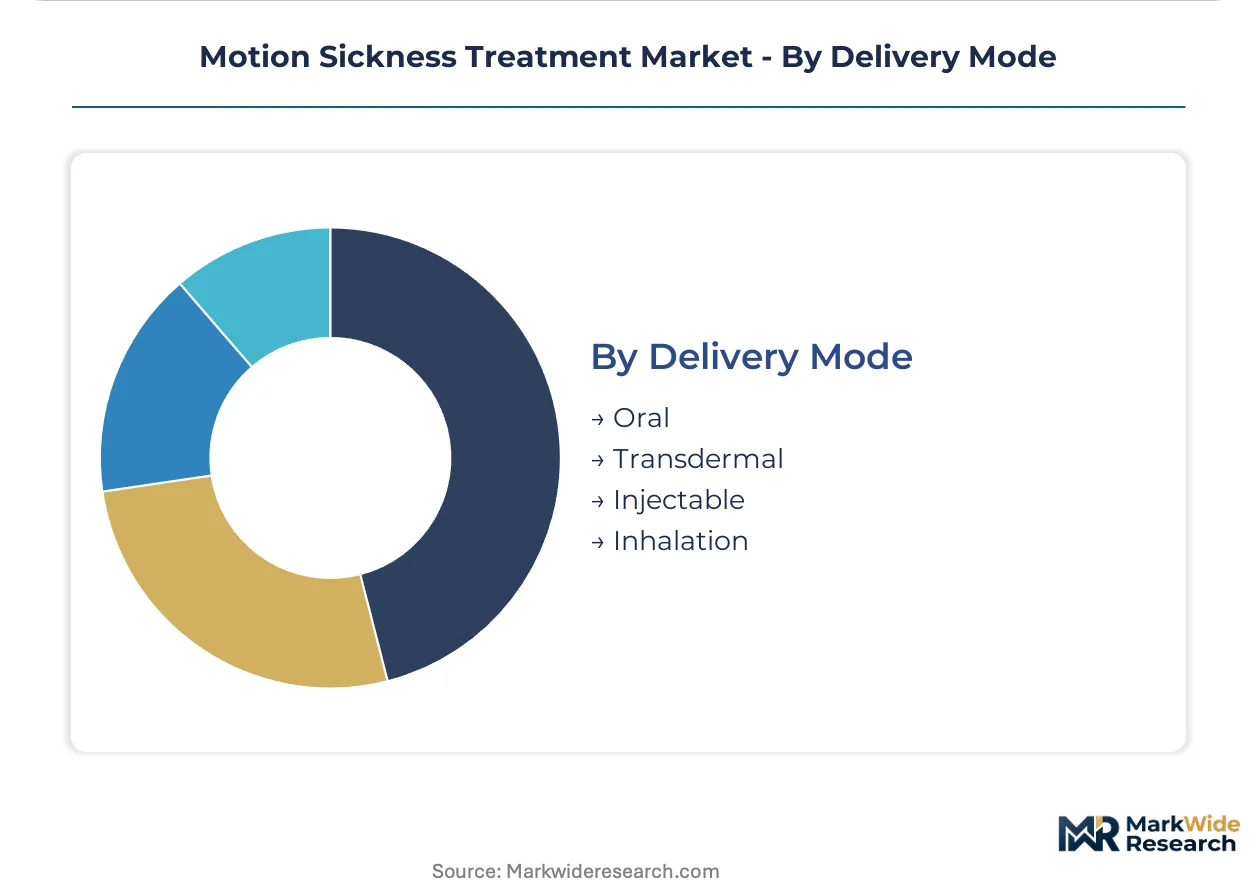
- Transdermal:Membrane-controlled diffusion eliminates first-pass metabolism and enables sustained plasma levels. Demand concentrates in frequent traveler populations seeking prophylaxis without cognitive impairment.
- Oral:Immediate and modified-release tablets dominate unit economics through scale manufacturing and distribution efficiency. China's NMPA accelerated generic approvals have flooded domestic markets with low-cost alternatives.
- Injectable:Parenteral routes serve hospital and emergency maritime medical protocols.
- Inhalation:Pulmonary delivery targets rapid onset for acute symptom rescue.
Oral maintains manufacturing scale. Transdermal is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of scopolamine raw material concentrate in southern China while finished transdermal patches move toward North American and European pharmacy chains. Import dependency for active pharmaceutical ingredients shapes formulation strategies across manufacturing hubs.
United States
Domestic tourism recovery and cruise line capacity expansion drive patch procurement through retail pharmacy networks. The FDA's OTC monograph reform streamlines entry for dimenhydrinate formulations while tightening documentation for new antihistamine entrants. Boston's pharmaceutical corridor hosts contract manufacturers scaling transdermal membrane production for cruise line supply contracts.
China
High-speed rail network expansion multiplies exposure scenarios across domestic tourism corridors connecting tier-one cities. The NMPA accelerates generic approval timelines for motion sickness therapies as domestic manufacturers scale GMP-certified production. The Yangtze River Delta cluster concentrates finished goods manufacturing for both domestic consumption and export to Southeast Asian markets.
Germany
Business travel volumes through Frankfurt and Munich airports sustain demand for non-sedating prophylaxis among corporate road warriors. The EMA's pharmacovigilance framework demands enhanced post-market surveillance for transdermal scopolamine products. The Rhine-Ruhr pharmaceutical belt houses formulation scientists specializing in controlled-release membrane engineering for patch technologies.
Japan
Aging demographics and polypharmacy concerns constrain anticholinergic prescribing, shifting preference toward device-based interventions. The PMDA maintains stringent stability requirements for transdermal adhesive systems used in humid summer conditions. The Kanto region around Tokyo concentrates distribution logistics for pharmacy chains serving domestic travelers and inbound tourism.
Brazil
Offshore energy operations and commercial fishing fleets represent concentrated occupational exposure populations with limited prescription access. ANVISA registration pathways for transdermal products lag oral generic approvals, creating access gaps. The São Paulo industrial corridor hosts importers distributing scopolamine patches to maritime medical suppliers serving Atlantic basin operations.
Motion Sickness Treatment Market Vendor Landscape
Concentration sits with large pharmaceutical manufacturers possessing established antihistamine portfolios and transdermal delivery platforms. Specialty consumer health firms compete aggressively through private-label penetration and direct-to-consumer channels. Two strategic archetypes dominate: diversified pharma conglomerates leveraging scale-dependent R&D, and focused OTC specialists optimizing retail shelf presence. Competitive moves center on portfolio diversification into gaming-applicable prophylaxis and geographic expansion through cruise line direct procurement channels.
Among the diversified pharmaceutical tier, GlaxoSmithKline Plc and Novartis AG occupy positions reflecting scale advantages in antihistamine development and prescription-grade formulation respectively. Prestige Consumer Healthcare Inc. exemplifies the OTC-specialist archetype, anchoring retail aisle presence through branded and private-label alternatives. These three entities represent the structural fault lines between prescription clinical positioning and mass-market accessibility.
| Leading Market Players |
|---|
| Prestige Consumer Healthcare Inc. |
| GlaxoSmithKline Plc |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Baxter International Inc. |
| Sun Pharmaceutical Industries Ltd. |
| WellSpring Pharmaceutical Corporation |
| Perrigo Company Plc |
| Others |
Supply Flow & Price Mechanics
Seventy-two-hour patch replenishment cycles concentrate procurement leverage with cruise line pharmacy buyers and subscription-platform operators, compressing margin capture for manufacturers without direct-to-consumer infrastructure. This inventory rhythm ties pricing power to membrane-engineering capabilities and scopolamine API access, segmenting manufacturers by vertical integration depth.
Pricing Analysis
The customization-premium spread separates standard dimenhydrinate tablets from patient-specific transdermal dosing regimens configured through telehealth platforms. Three-tier pricing structure across premium, standard, and economy levels tracks formulation complexity, with membrane-controlled diffusion commanding premium positioning over immediate-release oral generics. Pricing pressure stems from China's NMPA accelerated generic approvals flooding domestic markets with low-cost alternatives. Corporate travel managers exhibit highest price sensitivity due to employer mandates for non-sedating alternatives, while cruise line procurement teams prioritize reliability over unit cost.
Supply Chain Analysis
Inventory lead-times for scopolamine API stretch across agricultural cultivation cycles in southern China and extraction processing in the Yangtze River Delta. Finished transdermal patch manufacturing draws from membrane substrate suppliers in Germany and adhesive excipient producers subject to REACH registration requirements. Single-source vulnerability concentrates in narrow cultivation zones for tropane alkaloid feedstock. Distribution runs through retail pharmacy chains in the United States, direct procurement channels for cruise operators, and telehealth-integrated subscription platforms in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motion sickness treatment platforms are consolidating around wearable-device-pharmaceutical combinations, with interoperability between neuromodulation hardware and dosing algorithms creating ecosystem lock-in comparable to chronic disease management platforms.
For Market Incumbents: Secure transdermal membrane engineering talent pools in the Rhine-Ruhr pharmaceutical belt before formulation scientist scarcity constrains pipeline velocity. Deepen backward integration into scopolamine cultivation networks to buffer agricultural yield volatility threatening API supply security. For New Entrants and Emerging Players: Lead with wearable neuromodulation devices targeting Brazil's offshore energy workforce, where ANVISA registration gaps for transdermal patches leave occupational populations underserved. Pursue direct procurement relationships with Atlantic basin maritime medical suppliers rather than retail pharmacy distribution. For Investors and Strategic Acquirers: Long-term, this sits as a platform-economics play because subscription-based replenishment models for transdermal patches are displacing episodic pharmacy purchases among loyalty program travelers. Target acquisition candidates with integrated telehealth consultation capabilities and cruise line supply contracts. Monitor FDA OTC monograph reform implementation as inflection signal for competitive entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Membrane Capacity Expansion | Rhine-Ruhr specialists scaling production for cruise line direct procurement contracts. |
| Telehealth Platform Integration | Direct-to-consumer channels capturing travelers from airport convenience retail. |
| Scopolamine API Backward Integration | Cultivation network control buffers southern China agricultural yield volatility. |
| Wearable Neuromodulation Development | Electrical stimulation wristbands displacing antihistamine tablets among corporate travelers. |
| Pediatric Formulation Regulatory Pathway | FDA weight-based dosing requirements limiting competitive entry in children segment. |
Methodological Framework
Desk research of FDA OTC monograph filings, EMA pharmacovigilance databases, and NMPA generic approval records preceded structured interviews with transdermal formulation scientists, cruise line pharmacy procurement directors, and telehealth platform medical officers. Secondary validation drew from ClinicalTrials.gov entries, cruise industry financial disclosures, and REACH substance evaluation workflows. Bottom-up patch manufacturing cost models were triangulated against top-down market sizing from retail pharmacy audit data.
Variance decomposition across delivery mode, application context, and end-user physiology drove analytical framework construction over the projection horizon. Segmentation dimensions modeled encompassed product type, transportation exposure scenario, patient vulnerability profile, and regional regulatory cluster. CAGRs were synthesized from patent expiry timelines, generic penetration curves, and infrastructure expansion projections for China's high-speed rail network.
Underlying assumptions cover sustained virtual reality headset adoption, stable scopolamine cultivation yields, and regulatory convergence pace across FDA, EMA, and NMPA jurisdictions, with deviation risk concentrated in agricultural supply shocks and REACH excipient reclassification. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Global Fabry Disease Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Kidney Stones Management Market