
 Global Valves Market | 2026-2036
Global Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Valves Market Outlook
Chinese foundry capacity is rebalancing toward higher-grade castings for industrial valve bodies. Emerson Electric Co. leverages integrated digital valve positioning systems across process automation accounts. Flowserve Corporation anchors its position through aftermarket service networks in hydrocarbon processing. KSB SE & Co. KGaA specializes in engineered pump-valve packages for water infrastructure.
A valve is a mechanical device that regulates, directs, or controls fluid flow by opening, closing, or partially obstructing passageways, typically constructed with pressure ratings from ANSI Class 150 to 2500 and temperature tolerances spanning cryogenic to above 1000°F. Its primary purpose is to ensure safe, efficient, and precise management of liquids, gases, and slurries across process industries. Ball valves command premium positioning in oil and gas isolation service where zero-leakage standards dominate procurement specifications. Stainless steel material grades are displacing carbon steel in water treatment applications as corrosion resistance requirements tighten.
The EPA enforces emissions standards that mandate low-leakage packing and sealing technologies in US process facilities. REACH and the EU F-Gas Regulation restrict certain elastomer compounds and fluorinated gases used in valve actuation systems across European manufacturing. China's GB standards and SAMR certification requirements shape import access and domestic product qualification protocols. Stakeholders must monitor how evolving material compliance rules in multiple jurisdictions alter sourcing strategies and qualification timelines.
Market Dynamics
Combined-cycle power plant construction is accelerating valve procurement cycles, while EU material compliance mandates are forcing stainless steel substitution across carbon steel supply chains. This dual pressure is compressing qualification timelines and reshaping foundry capacity allocation.
Growth Catalysts
- Power Generation Expansion:Combined-cycle natural gas facilities in the United States and India are expanding isolation valve procurement for steam and feedwater systems. Utilities specify API 6D ball valves for critical service.
- REACH Compliance:The EU F-Gas Regulation and REACH restrictions on fluorinated elastomers are accelerating stainless steel valve adoption across European water treatment infrastructure. Municipal procurement specifications now mandate corrosion-resistant materials.
- Refinery Modernization:India's downstream capacity additions at Reliance Industries and Indian Oil facilities are compressing valve delivery cycles. CDSCO-equivalent pressure equipment certification requirements are tightening qualification protocols.
Market Restraints
- Foundry Concentration:Chinese casting capacity dominates high-grade valve body production, creating single-source risk for European and North American valve assemblers. Freight cost volatility amplifies margin pressure.
- Alloy Price Volatility:Nickel and molybdenum price swings distort stainless steel valve pricing, complicating long-term EPC contract bidding. Foundries pass through material cost spikes with 90-day lags.
- Actuator Substitution:Electric actuators are displacing pneumatic systems in low-pressure water applications, compressing traditional valve-actuator package margins. Compressed air infrastructure investments are being deferred.
Strategic Opportunities
- Digital Positioning Convergence:Integrated smart valve positioners combining HART protocol with edge analytics are opening premium service contracts. Process automation accounts are consolidating sensor and actuator procurement.
- Municipal Water Infrastructure:India's AMRUT 2.0 scheme and Smart Cities Mission are accelerating butterfly and gate valve procurement for distribution networks. State-level water boards are bundling valve and meter purchases.
- Hydrogen Service Qualification:Hydrogen embrittlement testing protocols for high-pressure isolation valves are creating first-mover advantages. German TÜV and US DOT PHMSA certification requirements are establishing technical barriers.
Industry Challenges
- Weld Qualification Bottlenecks:ASME Section IX certified welders for high-pressure valve repair are scarce across North American service networks. Training pipeline gaps extend field service response times.
- Legacy System Integration:Retrofitting digital positioners onto 1990s-era pneumatic valve installations requires custom mounting kits and signal conditioning. DCS compatibility testing consumes engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Valves Market |
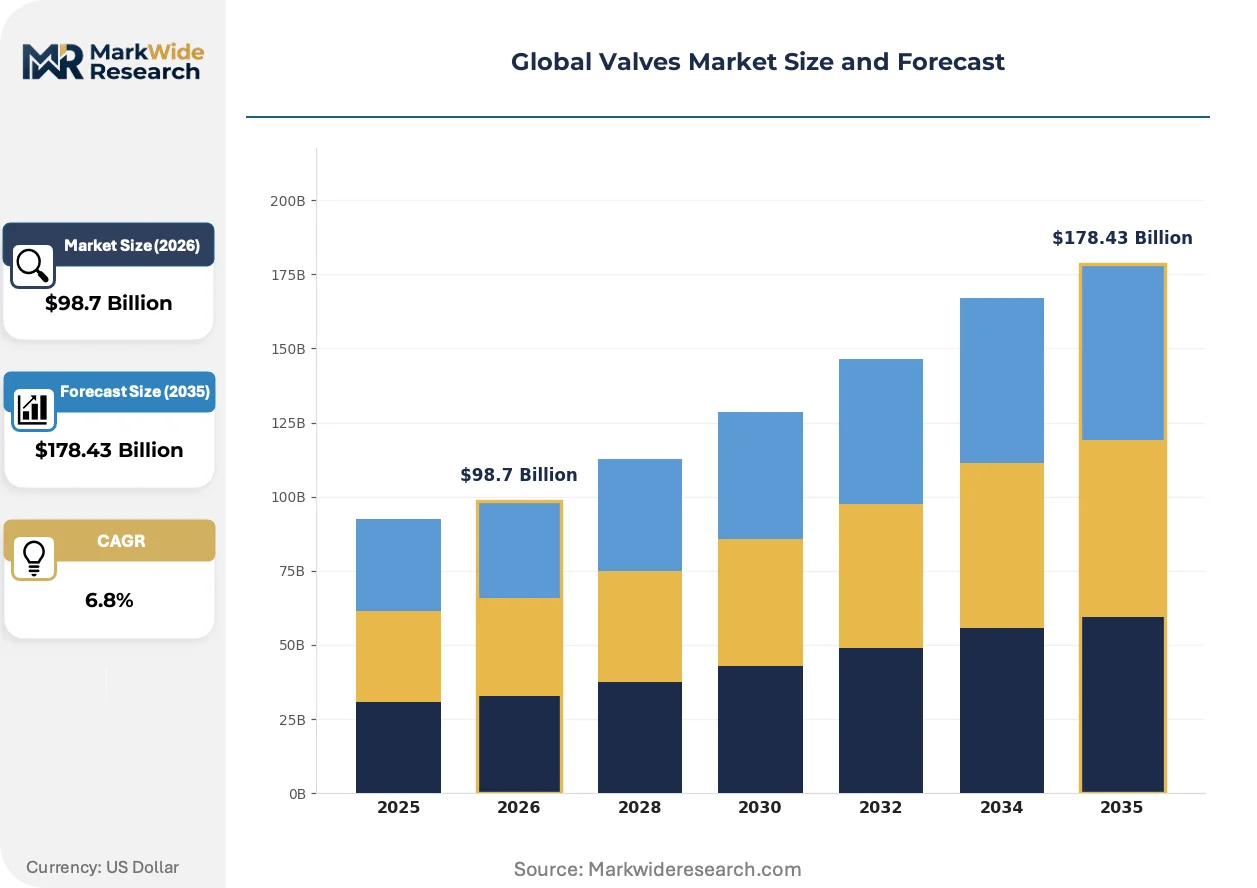
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Globe Valves, Check Valves Material: Stainless Steel, Bronze, PVC, Carbon Steel Application: Pipelines, Water Treatment, HVAC Systems, Oil & Gas End User: Industrial, Commercial, Residential, Power Generation |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, SLB, Crane Company, IMI, Alfa Laval, KSB SE & Co. KGaA, Kitz Corporation, Velan Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Valves Market Strategic Shifts
Electrification of valve actuation systems is compressing pneumatic infrastructure requirements across process plants. Digital twin integration and predictive maintenance algorithms are reshaping aftermarket service economics.
Electro-hydraulic valve actuators are electrifying high-torque isolation applications previously reserved for pneumatic or pure hydraulic systems. Offshore platform operators in the North Sea are adopting these for subsea choke valves. The technology is electrifying actuator vendor competitive positioning by collapsing the traditional pneumatic-hydraulic segmentation.
EPA methane emissions standards are mandating low-leakage packing technologies across US onshore production facilities. Fugitive emissions monitoring requirements are forcing replacement of legacy rising-stem valves with quarter-turn designs. The Permian Basin and Bakken shale plays are experiencing the most intensive retrofit activity.
Asset owners are unbundling valve maintenance from OEM service contracts and awarding multi-vendor framework agreements to independent repair specialists. Hydrocarbon processing facilities in the US Gulf Coast are consolidating aftermarket spend across rotating and static equipment. This procurement restructuring is most visible among mid-sized refineries seeking to reduce MRO procurement overhead.
Global Valves Market Segmentation
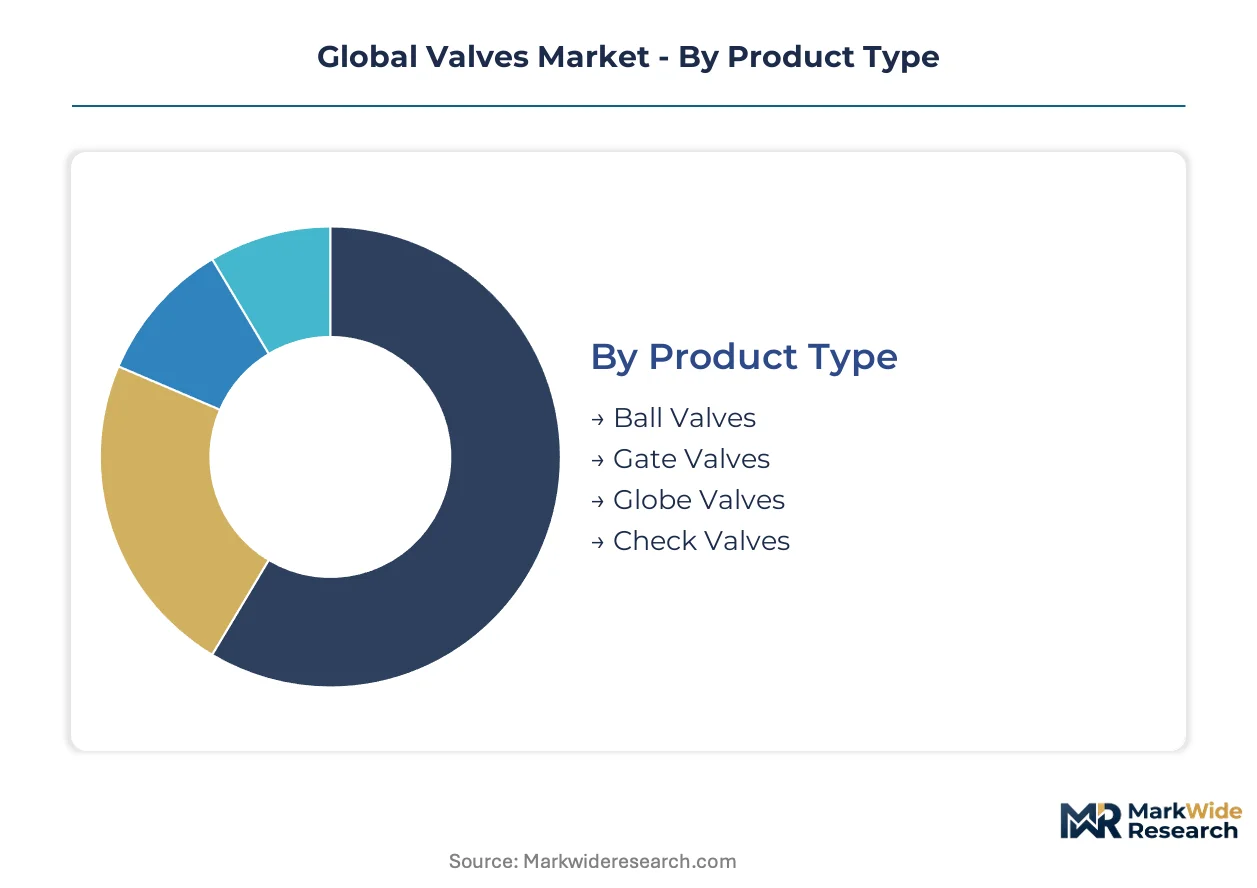
Valve procurement specifications diverge sharply across product categories, with certification requirements from API, ASME, and ISO governing material selection and pressure ratings. Segment boundaries determine sourcing strategies, foundry partnerships, and aftermarket service economics for manufacturers and distributors.
Product Type:
API 6D certification governs pipeline service valves, while API 598 testing standards apply to general-purpose isolation equipment. ASME B16.34 pressure-temperature ratings differentiate procurement tiers across upstream and downstream applications.
- Ball Valves:Quarter-turn isolation devices utilizing floating or trunnion-mounted ball configurations with metal-to-metal or soft seats. Zero-leakage procurement specifications from US onshore shale operators and Indian refinery expansions at Reliance Jamnagar are compressing delivery cycles for API 6D certified units.
- Gate Valves:Linear-motion isolation valves with wedge or parallel slide configurations designed for full-flow, low-pressure-drop service. Municipal water infrastructure projects under India's AMRUT 2.0 scheme are accelerating cast iron and ductile iron gate valve procurement for distribution mains.
- Globe Valves:Throttling control valves with S-shaped flow paths enabling precise flow regulation across steam and chemical service.
- Check Valves:Automatic backflow prevention devices including swing, lift, and dual-plate configurations for pump protection.
Ball valves sit at the top of the volume ranking, with gate valves climbing the fastest on water infrastructure momentum.
Material:
Material selection correlates directly with corrosion allowance specifications and lifecycle cost calculations across process industries. Foundry capacity allocation and alloy pricing volatility segment the supply base into captive casting operations and merchant suppliers.
- Stainless Steel:Austenitic and duplex grades offering superior corrosion resistance in chloride-bearing environments. REACH compliance mandates and EU F-Gas Regulation restrictions on fluorinated elastomers are displacing carbon steel in European municipal water treatment procurement specifications.
- Carbon Steel:ASTM A216 WCC and WCB grades dominating high-pressure hydrocarbon service where corrosion rates remain manageable. US Permian Basin production facilities specify carbon steel ball valves with low-leakage packing to meet EPA methane emissions standards.
- Bronze:Copper-tin alloys specified for seawater and brackish water applications in marine and coastal infrastructure.
- PVC:Thermoplastic valves for low-pressure chemical resistance in water distribution and irrigation systems.
Stainless steel commands the premium pricing tier, while carbon steel maintains volume leadership in hydrocarbon processing.
Application:
Application segmentation tracks capital expenditure cycles across utility, industrial, and building construction markets. Project finance availability and regulatory enforcement intensity determine procurement timing and specification stringency.
- Oil & Gas:Upstream production, midstream transportation, and downstream refining applications requiring fire-safe testing and fugitive emissions certification. German TÜV and US DOT PHMSA hydrogen embrittlement protocols are creating qualification barriers for high-pressure isolation service.
- Water Treatment:Municipal potable water, wastewater, and desalination infrastructure requiring NSF/ANSI 61 and WRAS material approvals. China's GB standards and SAMR certification requirements shape import access for foreign valve suppliers.
- Pipelines:Long-distance crude oil, natural gas, and product transmission systems.
- HVAC Systems:Building automation and district heating networks requiring pressure-independent control capabilities.
Oil and gas applications anchor revenue concentration, with water treatment expanding most quickly on infrastructure stimulus programs.
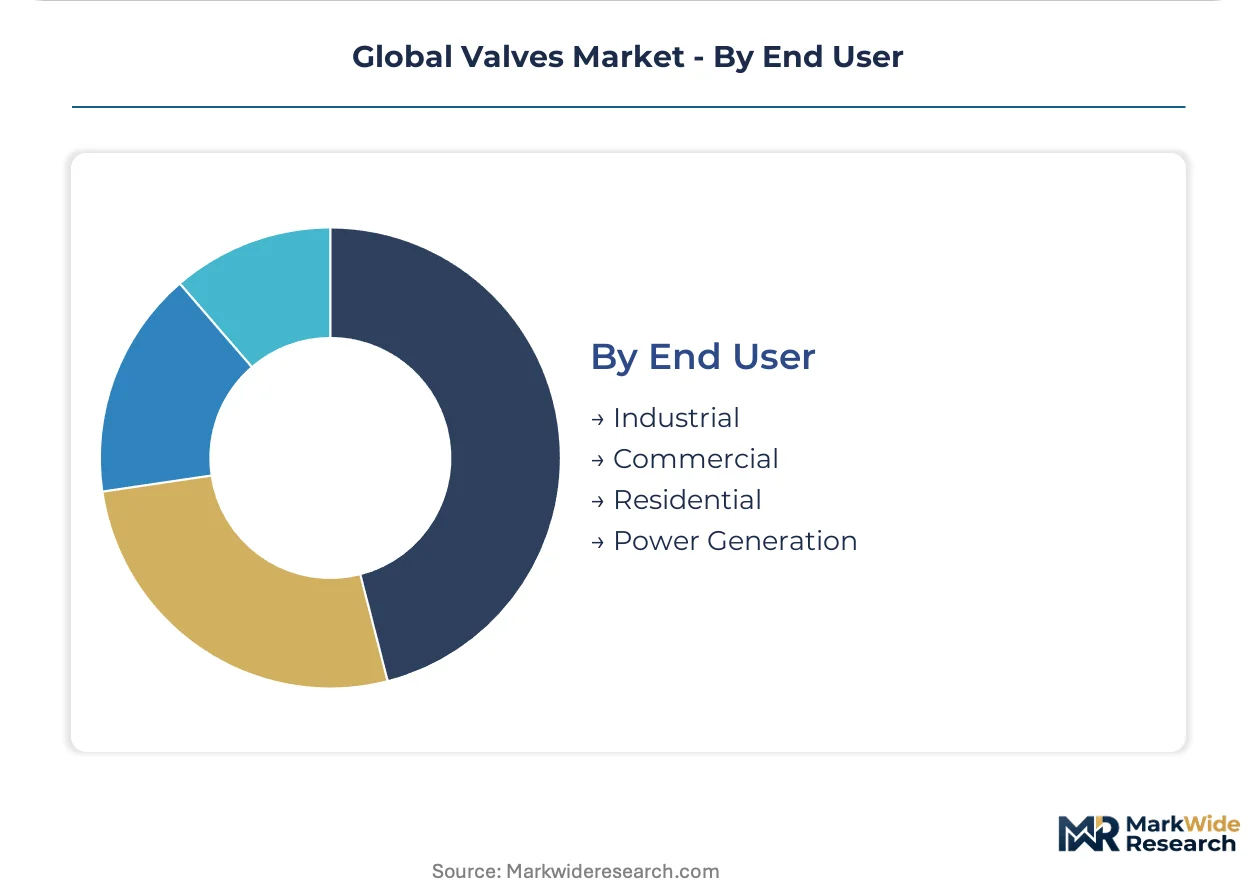
End User:
End user segmentation reveals divergent procurement behaviors between specification-driven industrial accounts and price-sensitive commercial and residential channels. Framework agreement structures and MRO consolidation patterns vary significantly across these categories.
- Industrial:Chemical processing, petrochemical, and manufacturing facilities requiring asset integrity management and predictive maintenance integration. US Gulf Coast refineries are unbundling valve maintenance from OEM contracts and awarding multi-vendor framework agreements to independent repair specialists.
- Power Generation:Combined-cycle natural gas, coal, and nuclear facilities specifying ASME Section III nuclear or B31.1 power piping compliance. Utilities in the United States and India are expanding isolation valve procurement for steam and feedwater systems.
- Commercial:Institutional buildings, hospitals, and retail infrastructure requiring standardized specifications.
- Residential:Single-family and multi-family construction with cost-driven procurement through distribution channels.
Industrial end users dominate specification complexity, with power generation gaining share fastest on capacity expansion cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's refinery expansion pace now exceeds China's municipal infrastructure build-out, though both depend on overlapping foundry supply chains for high-grade castings. Geographic procurement patterns diverge sharply between EPA-driven methane compliance in North American shale plays and REACH-mandated material substitution across European water networks.
United States
Combined-cycle natural gas facilities in Texas and the Southeast are expanding isolation valve procurement for steam and feedwater systems. EPA methane emissions standards mandate low-leakage packing technologies across Permian Basin and Bakken shale production sites. Houston anchors aftermarket service consolidation as Gulf Coast refineries unbundle valve maintenance from OEM contracts.
Germany
Hydrogen embrittlement testing protocols for high-pressure isolation valves are creating qualification barriers at industrial clusters in the Ruhr and Bavaria. TÜV certification requirements and EU F-Gas Regulation restrictions on fluorinated elastomers accelerate stainless steel adoption. Munich-based engineering consultancies are shaping technical specifications for hydrogen service valves across European energy infrastructure.
China
Foundry capacity is rebalancing toward higher-grade castings for industrial valve bodies to serve domestic refinery and power generation demand. GB standards and SAMR certification requirements shape import access and domestic product qualification protocols. Yangtze River Delta manufacturing clusters are absorbing technology transfers for API 6D certified ball valve production.
India
Reliance Industries and Indian Oil downstream capacity additions are compressing valve delivery cycles at Jamnagar and Paradip refinery complexes. CDSCO-equivalent pressure equipment certification requirements tighten qualification protocols for imported equipment. State-level water boards under AMRUT 2.0 are bundling butterfly and gate valve purchases for municipal distribution networks.
United Arab Emirates
Offshore platform operators in the Arabian Gulf are adopting electro-hydraulic valve actuators for subsea choke valve applications. ADNOC procurement specifications are converging toward international certification standards for high-pressure isolation service. Dubai and Abu Dhabi engineering hubs are consolidating aftermarket framework agreements across hydrocarbon processing facilities.
Global Valves Market Competitive Environment
North American producers anchor one tier; German and Japanese specialists hold premium positioning in engineered applications. The vendor base organizes around three strategic archetypes: integrated automation conglomerates with digital positioning capabilities, dedicated valve fabricators with captive foundry relationships, and aftermarket service specialists with ASME-certified repair networks. Competitive moves concentrate on M&A for actuator technology access and geographic expansion through local qualification partnerships.
Within the integrated automation tier, Emerson Electric Co. and Flowserve Corporation exemplify the convergence of valve hardware with process control systems. KSB SE & Co. KGaA anchors the engineered pump-valve package segment, particularly for water infrastructure applications. These three entities occupy positions that span specification influence at major utilities through aftermarket service penetration, representing distinct competitive vectors rather than direct product rivalry.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| SLB |
| Crane Company |
| IMI |
| Alfa Laval |
| KSB SE & Co. KGaA |
| Kitz Corporation |
| Velan Inc. |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation mandates on fluorinated elastomers are compressing procurement timelines for stainless steel valve alternatives, forcing foundries to rebalance capacity toward higher-grade castings and amplifying alloy cost pass-through into European municipal water contracts.
Pricing Analysis
Distributor markups on API 6D certified ball valves stratify across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Price differentiation hinges on ASME Section IX weld qualification and HART-enabled digital positioning capabilities. Cost compression in carbon steel gate valves is intensifying because electric actuator substitution erodes traditional valve-actuator package margins. Municipal water boards exhibit highest price sensitivity, while hydrogen service qualification commands premium positioning with minimal buyer resistance.
Supply Chain Analysis
Freight cost volatility from Chinese foundry clusters to European and North American valve assemblers is amplifying margin pressure on high-grade castings. Supply concentrates in China, India, and Germany for valve body production, drawing from nickel, molybdenum, and specialty alloy feedstocks. Single-source vulnerability in Chinese casting capacity creates structural risk for API 6D certified units. Distribution runs through OEM direct sales for industrial accounts and authorized distributor networks for municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through stainless steel substitution premiums and digital positioning service contracts, with alloy cost pass-through mechanisms protecting foundry margins against raw material volatility.
For Market Incumbents: Acquire electro-hydraulic actuator technology capabilities to defend against electric actuator substitution in low-pressure water applications. Deepen backward integration into captive foundry operations in India to compress delivery cycles for Reliance Industries and Indian Oil refinery expansions. Invest in TÜV hydrogen embrittlement certification to establish technical barriers around German industrial clusters. For New Entrants and Emerging Players: Launch via independent aftermarket service networks targeting US Gulf Coast refineries unbundling valve maintenance from OEM contracts. Target India's AMRUT 2.0 municipal water infrastructure as the most penetrable segment, where state-level water boards bundle butterfly and gate valve purchases with minimal incumbent lock-in. Lead with WRAS and NSF/ANSI 61 pre-certified product lines to accelerate procurement qualification. For Investors and Strategic Acquirers: Asymmetric upside sits with engineered pump-valve package specialists holding captive foundry relationships and water infrastructure exposure. Long-term viability favors participants with integrated digital positioning capabilities and hydrogen service qualification pipelines. Watch German TÜV and US DOT PHMSA certification timeline acceleration as the signal for hydrogen infrastructure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Operations | Secures high-grade casting supply for API 6D certification requirements amid Chinese capacity concentration. |
| Hydrogen Service Qualification Investment | Establishes TÜV and DOT PHMSA certification barriers ahead of European energy infrastructure conversion. |
| Digital Positioner Platform Integration | Captures HART protocol and edge analytics premiums in process automation accounts consolidating sensor procurement. |
| Aftermarket Service Network Expansion | Addresses ASME Section IX welder scarcity extending field service response times across North American repair markets. |
| Municipal Water Infrastructure Partnership | Aligns with India's AMRUT 2.0 bundling requirements and European REACH-mandated stainless steel substitution. |
Study Parameters
Coverage spans the United States, Germany, China, India, and the United Arab Emirates, with primary inputs from each region combining interviews with plant engineers, OEM procurement teams, aftermarket service heads, and municipal water board technical directors. Secondary validation draws from API certification databases, ASME boiler and pressure vessel code filings, EPA enforcement records, ECHA REACH substance restrictions, and customs trade data for alloy castings. Bottom-up project pipeline analysis triangulates against top-down foundry capacity and utility capital expenditure tracking.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include valve product type, material grade, application sector, and end-user procurement behavior. CAGRs derive from weighted capacity expansion schedules, regulatory compliance timeline assumptions, and substitution elasticity estimates for electric versus pneumatic actuation systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel and molybdenum price spike scenarios or accelerated hydrogen infrastructure deployment. Forecasts reflect assumptions about foundry capacity rebalancing, certification timeline compression, and alloy cost pass-through mechanisms. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pipeline Pigging System Market
Valves
Axial and Radial Seals Market
Valves
Industrial Safety Valves Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Curb Valves Market
Valves
Mobile Hydraulic Valves Market
Valves
Instrumentation Valves and Fittings Market
Valves
Gate Impellers Market
Valves
Air Jet Ejectors Market
Valves
Sand Control System Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Pressure Reducing Valve Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Safety Valve Test Benches Market
Valves
Dense Phase Vessels Market
Valves
Construction Valve Seat Insert Market