
 Enterprise Manufacturing Intelligence Market | 2026-2036
Enterprise Manufacturing Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Manufacturing Intelligence Market Intelligence
Automotive OEMs is pivoting toward predictive quality systems as electric vehicle production complexity multiplies data generation points across battery module assembly and powertrain integration. Siemens AG leverages its digital twin portfolio to anchor factory-floor deployments across European and North American automotive plants. Rockwell Automation Inc. competes through its FactoryTalk Analytics platform, sustaining deep integration with programmable logic controller ecosystems that dominate discrete manufacturing environments.
Enterprise Manufacturing Intelligence denotes software and hardware systems that aggregate operational data from programmable logic controllers, distributed control systems, and industrial IoT sensors into unified analytics layers for real-time decision support, typically processing sub-second cycle times and terabyte-scale historical datasets to optimize throughput, yield, and energy intensity. The software segment dominates current revenue as platform licensing models expand, while AI-enabled modules within the technology dimension represent the fastest-expanding margin pool as manufacturers prioritize autonomous anomaly detection over descriptive dashboards. Cloud Computing deployments are maturing fastest among electronics producers with distributed assembly footprints, whereas on-premise solutions retain preference in pharmaceutical companies governed by stringent data residency requirements.
The FDA's 21 CFR Part 11 electronic records framework shapes pharmaceutical sector demand by mandating audit trails and data integrity protocols that influence platform validation requirements. Germany's KBA and the EU AI Act collectively pressure automotive and aerospace manufacturers to demonstrate algorithmic transparency in automated quality decisions, tightening procurement specifications for explainable AI modules. Stakeholders must weigh cloud migration timelines against evolving cross-border data governance frameworks before committing to multi-year platform architectures.
Market Dynamics
Edge-to-cloud architecture adoption is compressing deployment timelines as automotive OEMs demand sub-second analytics at assembly stations while maintaining centralized data lakes for enterprise-wide optimization.
Growth Catalysts
- EU AI Act compliance mandates:Automotive manufacturers in Germany and France must deploy explainable AI modules for automated quality decisions, tightening procurement specifications and accelerating platform upgrades.
- Pharmaceutical data integrity requirements:FDA's 21 CFR Part 11 framework mandates audit trails that drive validation-intensive deployments of manufacturing intelligence platforms in drug production facilities.
- Battery module complexity:Electric vehicle powertrain integration multiplies sensor density across assembly lines, generating terabyte-scale datasets that require real-time analytics infrastructure.
Market Restraints
- Semiconductor supply concentration:Industrial edge computing hardware depends on foundry capacity concentrated in Taiwan and South Korea, creating procurement bottlenecks for latency-sensitive deployments.
- Cross-border data governance friction:Germany's BSI IT security standards and China's data localization requirements impose conflicting architectural constraints on multinational platform rollouts.
- Legacy PLC integration costs:Brownfield facilities running 1990s-era programmable logic controller networks face capital-intensive retrofitting to enable unified data aggregation layers.
Strategic Opportunities
- India PLI scheme manufacturing expansion:Electronics and automotive component producers establishing greenfield capacity under production-linked incentive programs represent unserved demand for cloud-native platform deployments.
- Digital twin convergence with AI:Physics-based simulation merging with machine learning anomaly detection creates new module categories for predictive maintenance in semiconductor fabrication.
- Outcome-based service contracting:Platform vendors can capture recurring revenue through uptime-guarantee arrangements rather than perpetual licensing, particularly in pharmaceutical contract manufacturing.
Industry Challenges
- OT-IT cybersecurity skill scarcity:Manufacturing intelligence deployments require personnel fluent in both operational technology protocols and enterprise IT security frameworks, a combination rare in current labor markets.
- Validation timeline compression:Pharmaceutical manufacturers face 18-24 month platform qualification cycles under FDA guidelines that conflict with agile software release cadences.
- Multi-protocol data harmonization:Facilities running OPC-UA, Modbus, and proprietary fieldbus networks simultaneously encounter integration complexity that delays unified analytics layer deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Manufacturing Intelligence Market |
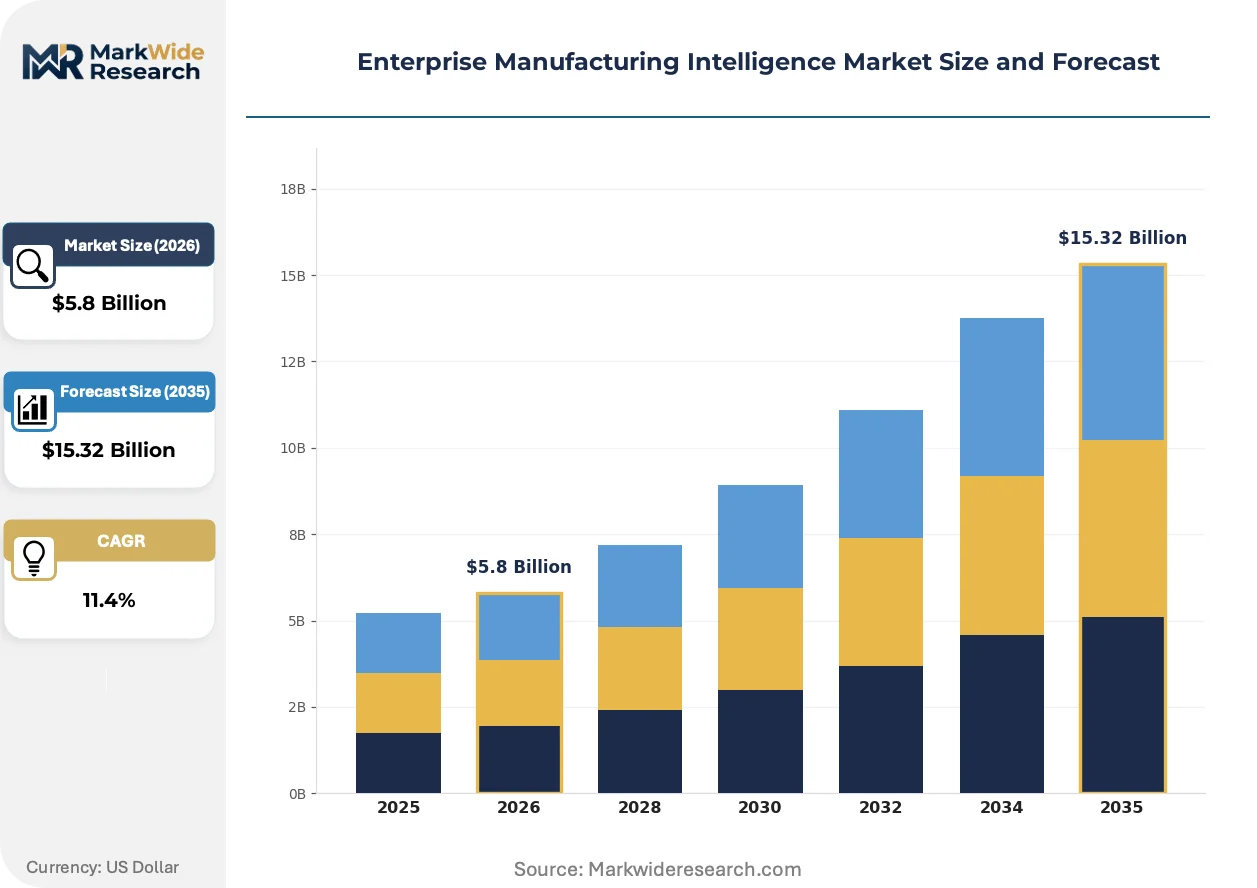
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions Technology: Cloud Computing, IoT, Big Data, AI Application: Production Planning, Quality Control, Inventory Management, Supply Chain Monitoring End User: Automotive OEMs, Aerospace Manufacturers, Electronics Producers, Pharmaceutical Companies |
| Companies Covered | Siemens AG, ABB Ltd., Rockwell Automation Inc., Honeywell International Inc., Schneider Electric SE, Aspen Technology Inc., Dassault Systèmes SE, SAP SE, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Manufacturing Intelligence Market Strategic Shifts & Innovations
Real-time analytics architectures are fragmenting into specialized configurations as edge computing maturity diverges across regulatory environments and end-use verticals with incompatible data sovereignty requirements.
Digital twin technology is consolidating factory-floor deployments by unifying physics-based simulation with live sensor streams into single-pane visualization environments. Automotive OEMs in Germany and the United States are standardizing on these integrated platforms for battery assembly validation. The technology is consolidating previously separate MES and SCADA upgrade cycles into unified procurement decisions.
REACH chemical substance restrictions and the EU Green Deal carbon border adjustments are forcing materials traceability modules into manufacturing intelligence platforms. Electronics producers must now document supply chain emissions and substance compliance at batch level. German automotive suppliers face the tightest compliance deadlines and are pre-qualifying platforms based on audit-ready reporting capabilities.
Buying committees are expanding to include chief sustainability officers and legal counsel alongside traditional operations stakeholders, elongating sales cycles but increasing contract values. Subscription pricing models are displacing perpetual licenses in electronics manufacturing where capital expenditure constraints favor operational expenditure treatment. This pattern is most pronounced in South Korean and Taiwanese semiconductor fabrication facilities.
Enterprise Manufacturing Intelligence Market Segmentation
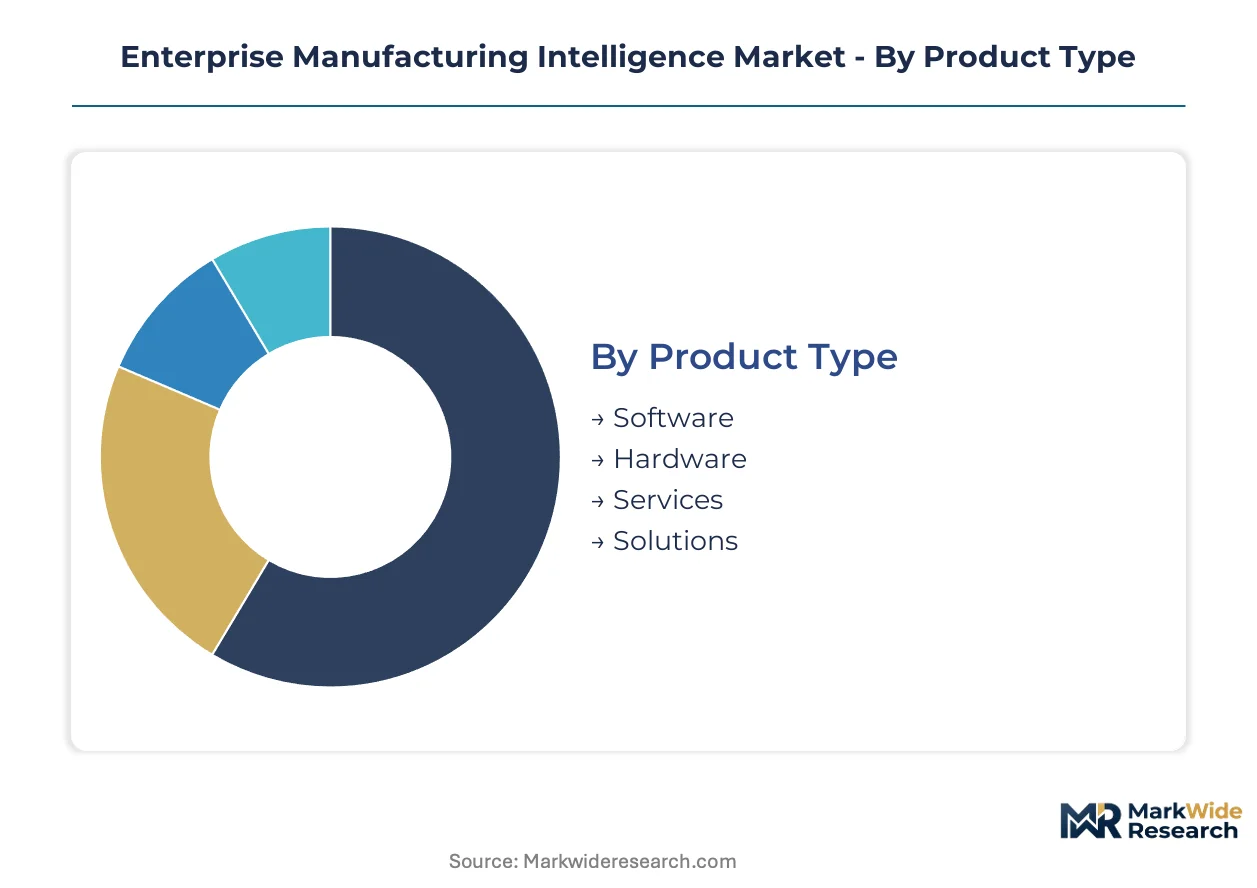
Enterprise manufacturing intelligence platforms fragment across four structural dimensions that determine deployment architecture and procurement priorities. Product type governs revenue recognition models and margin profiles. Technology selection constrains latency performance and regulatory compliance pathways.
Product Type:
Software commands premium pricing while hardware anchors volume deployment. Services capture recurring revenue through validation-intensive pharmaceutical engagements.
- Software:Platform licensing and module subscriptions aggregate programmable logic controller data into unified analytics layers. Pharmaceutical companies in Germany drive validation-intensive procurement under FDA 21 CFR Part 11 mandates, compressing vendor selection timelines. Cloud-native architectures displace perpetual licenses in electronics manufacturing where operational expenditure treatment dominates capital allocation.
- Hardware:Edge computing appliances and industrial IoT gateways process sub-second cycle times at assembly stations. Automotive OEMs in Germany specify latency thresholds below 50 milliseconds for battery module quality inspection, concentrating procurement with Siemens and Rockwell channel partners. Taiwan and South Korean foundry capacity constraints create procurement bottlenecks for GPU-accelerated inference nodes.
- Services:Implementation, validation, and managed analytics contracts span 18-24 month engagement cycles. FDA qualification protocols extend pharmaceutical deployment timelines while securing multi-year recurring revenue streams.
- Solutions:Bundled software-hardware-service packages consolidate vendor relationships and simplify procurement for brownfield retrofit projects. Mittelstand manufacturers favor outcome-based contracting with uptime guarantees.
Today's leader: Software. Tomorrow's challenger: Solutions.
Technology:
Cloud deployments mature fastest in distributed electronics assembly while edge architectures retain pharmaceutical preference for data residency compliance.
- Cloud Computing:Centralized data lakes enable enterprise-wide optimization across multi-site manufacturing footprints. Electronics producers with distributed Asian assembly networks standardize on cloud-native platforms to avoid capital-intensive on-premise infrastructure.
- IoT:Sensor networks and industrial edge gateways generate terabyte-scale datasets from battery module assembly lines. Electric vehicle powertrain integration multiplies data generation points across German and North American automotive plants.
- Big Data:Historical dataset processing and pattern recognition support yield optimization and energy intensity reduction. Semiconductor fabrication facilities in Taiwan and South Korea deploy petabyte-scale analytics for predictive maintenance.
- AI:Autonomous anomaly detection modules command the steepest expansion trajectory as manufacturers prioritize predictive quality over descriptive dashboards. EU AI Act transparency mandates tighten procurement specifications for explainable AI in German automotive quality decisions.
Cloud Computing anchors current deployment value. AI modules are climbing the fastest as regulatory pressure and production complexity converge.
Application:
Quality control absorbs the largest platform investment while production planning integrates most deeply with existing manufacturing execution systems.
- Production Planning:Real-time scheduling optimization synchronizes material flows with demand signals across multi-tier supply chains. Automotive OEMs deploy these modules to manage electric vehicle platform complexity and battery supply volatility.
- Quality Control:Automated visual inspection and statistical process control systems validate battery module assembly integrity. German KBA regulations and EU AI Act compliance requirements mandate algorithmic transparency in automated quality decisions, favoring vendors with explainable AI capabilities.
- Inventory Management:Batch-level traceability modules document REACH chemical compliance and carbon emissions for EU Green Deal reporting. Electronics producers face the tightest documentation deadlines.
- Supply Chain Monitoring:Multi-tier visibility platforms track component provenance and supplier performance. REACH restrictions and carbon border adjustments force materials traceability integration into core manufacturing intelligence architectures.
Quality control dominates current procurement cycles. Supply chain monitoring is gaining share fastest as sustainability reporting mandates tighten.
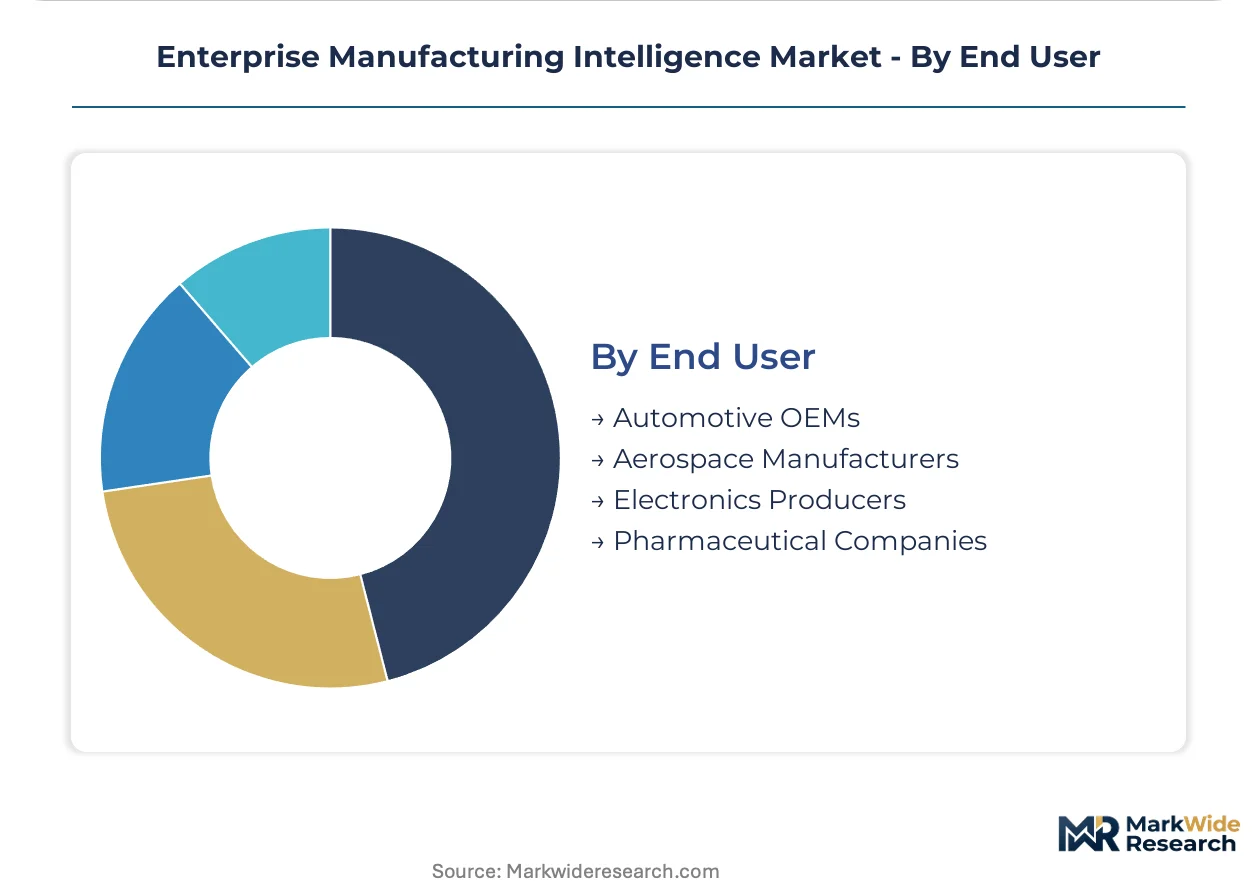
End User:
Automotive OEMs drive platform innovation while pharmaceutical companies impose the most stringent validation requirements.
- Automotive OEMs:Battery module assembly and powertrain integration generate unprecedented sensor density across European and North American plants. Real-time analytics platforms optimize throughput while maintaining EU AI Act compliance for automated quality decisions.
- Aerospace Manufacturers:Traceability and certification documentation requirements span decades-long product lifecycles. These deployments prioritize audit-ready reporting and long-term data archival over real-time performance.
- Electronics Producers:Distributed assembly footprints and rapid product cycles favor cloud-native platform architectures with subscription pricing. South Korean and Taiwanese semiconductor fabrication facilities lead operational expenditure treatment adoption.
- Pharmaceutical Companies:FDA 21 CFR Part 11 mandates enforce audit trails and data integrity protocols that extend platform qualification to 18-24 months. Data residency requirements retain preference for on-premise or hybrid edge-to-cloud deployments.
Automotive OEMs anchor platform roadmap decisions. Pharmaceutical companies represent the highest-margin segment despite elongated sales cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns trace divergent compliance cost trajectories across manufacturing jurisdictions. Automotive OEMs relocate battery module assembly toward jurisdictions with streamlined AI validation pathways. Pharmaceutical contract manufacturers cluster in regions offering harmonized FDA-EMA inspection protocols.
United States
Electric vehicle powertrain investments by Detroit automakers multiply sensor deployment across Michigan and Ohio assembly corridors. FDA's 21 CFR Part 11 framework governs pharmaceutical platform qualification timelines extending 18-24 months. The Boston-Cambridge biotech cluster drives demand for audit-ready manufacturing intelligence in contract drug manufacturing.
Germany
Mittelstand automation programs concentrate procurement in Baden-Württemberg and Bavaria industrial zones. KBA vehicle approval requirements and EU AI Act transparency mandates tighten algorithmic quality decision specifications. Stuttgart automotive suppliers pre-qualify platforms based on explainable AI capabilities for battery assembly validation.
China
Dual carbon goals accelerate energy intensity optimization modules in Yangtze River Delta electronics fabrication. MIIT industrial internet standards shape platform interoperability requirements for smart factory certification. Shenzhen semiconductor packaging facilities deploy edge-to-cloud architectures for distributed assembly network coordination.
India
PLI scheme incentives attract electronics and automotive component greenfield capacity in Tamil Nadu and Karnataka. BIS certification requirements influence platform localization strategies for multinational vendors. Pune automotive clusters represent unserved demand for cloud-native manufacturing intelligence deployments.
South Korea
Semiconductor fabrication leadership in Gyeonggi Province drives petabyte-scale predictive maintenance analytics. MFDS pharmaceutical data integrity guidelines align with FDA frameworks for export-oriented drug manufacturing. Samsung and SK Hynix supply chain requirements propagate platform specifications across Asian electronics assembly networks.
Enterprise Manufacturing Intelligence Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with industrial automation conglomerates anchoring automotive deployments and software vendors capturing pharmaceutical validation cycles. The vendor base concentrates around three strategic archetypes: diversified industrial technology conglomerates with digital twin portfolios, pure-play manufacturing intelligence platforms with cloud-native architectures, and enterprise software vendors extending ERP modules into operational technology layers. Dominant competitive moves include M&A activity targeting edge computing hardware capabilities and strategic partnerships between automation vendors and hyperscale cloud providers.
Among diversified industrial technology conglomerates, Siemens AG and ABB Ltd. exemplify the integrated hardware-software-service archetype that dominates brownfield retrofit procurement in European automotive plants. Rockwell Automation Inc. occupies a distinct position anchoring programmable logic controller ecosystem integration for discrete manufacturing environments in North America. These three entities represent divergent geographic anchoring strategies—German engineering heritage, Swiss-Swedish industrial automation consolidation, and American factory-floor protocol dominance—shaping competitive positioning across regional procurement committees.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Schneider Electric SE |
| Aspen Technology Inc. |
| Dassault Systèmes SE |
| SAP SE |
| Emerson Electric Co. |
| Others |
Cost & Logistics Intelligence
Captive edge-computing hardware production within Siemens and Rockwell Automation anchors both supply security and pricing power across European automotive deployments, insulating these vendors from foundry bottlenecks that squeeze pure-play software competitors. This vertical integration into GPU-accelerated inference nodes allows tier-one automation conglomerates to maintain margin structures while cloud-native entrants absorb Taiwan semiconductor foundry premiums.
Pricing Analysis
Distributor margin layers concentrate pricing power with channel partners serving Mittelstand manufacturers in Baden-Württemberg and Bavaria. Three-tier pricing structure across premium digital-twin bundles, standard analytics modules, and economy sensor-gateway configurations stratifies procurement committees by validation intensity. Cost compression in economy tiers intensifies because South Korean and Taiwanese foundry capacity constraints propagate into edge hardware bill-of-materials. Pharmaceutical contract manufacturers exhibit lowest price sensitivity due to FDA qualification lock-in effects, whereas electronics producers with distributed Asian assembly networks drive hardest subscription-versus-perpetual negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing and Samsung Foundry for GPU-accelerated edge inference nodes that automotive OEMs specify below 50-millisecond latency thresholds. Industrial IoT sensor fabrication draws from China, Vietnam, and Mexico for cost-optimized assemblies, while high-reliability programmable logic controller modules rest on German and Japanese component ecosystems. Tariff exposure runs through US-China semiconductor equipment restrictions that disrupt brownfield retrofit timelines. Distribution runs through Rockwell and Siemens channel partners for automotive OEMs, direct enterprise sales for pharmaceutical validation engagements, and hyperscale cloud marketplaces for electronics producers with distributed footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in India's PLI scheme corridors, where Tamil Nadu electronics fabrication incentives undercut German automation heritage costs by eliminating EU AI Act compliance overhead for non-EU export production.
For Market Incumbents: Anchor platform roadmap decisions around explainable AI modules that preempt EU AI Act transparency mandates tightening across German automotive procurement specifications. Deepen backward integration into edge computing hardware through foundry partnerships with Taiwan and South Korean suppliers, securing GPU-accelerated inference node allocation ahead of semiconductor fabrication competitors. Defensive priority rests on locking pharmaceutical validation cycles through FDA 21 CFR Part 11 pre-qualified deployment templates that elongate competitor sales timelines. For New Entrants and Emerging Players: System integrators specializing in brownfield PLC retrofit represent the most penetrable channel partner type for cloud-native platforms lacking Rockwell or Siemens ecosystem integration. White-space targets cluster in India's Pune automotive clusters and Karnataka electronics corridors, where PLI scheme greenfield capacity lacks incumbent automation vendor relationships. Target outcome-based contracting with uptime guarantees for Mittelstand manufacturers seeking to consolidate software-hardware-service procurement under single-vendor accountability. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap manufacturing intelligence specialists with validated FDA qualification protocols because pharmaceutical sector procurement extends customer lifetime value through 18-24 month platform validation cycles that deter switching. Long-term viability framing centers on AI module margin expansion as autonomous anomaly detection displaces descriptive dashboard licensing. Acquisition target archetype: cloud-native platforms with pre-built pharmaceutical validation documentation and existing BIS certification for Indian market entry. Watch EU AI Act enforcement variance across German KBA versus French ANSM interpretations as inflection indicator for explainable AI module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Architecture Integration | Automotive OEMs in Germany compress deployment timelines while maintaining centralized data lakes for enterprise optimization. |
| Explainable AI Module Development | EU AI Act transparency mandates tighten procurement specifications for automated quality decisions in Stuttgart battery assembly plants. |
| Pharmaceutical Validation Pre-Qualification | FDA 21 CFR Part 11 compliance templates secure 18-24 month engagement cycles with multi-year recurring revenue lock-in. |
| Foundry Partnership for GPU Acceleration | Taiwan and South Korean semiconductor capacity constraints create procurement bottlenecks for latency-sensitive edge deployments. |
| Outcome-Based Service Contracting | Uptime-guarantee arrangements displace perpetual licensing in Mittelstand manufacturing favoring operational expenditure treatment. |
Research Approach
Bottom-up automotive and pharmaceutical deployment modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core of this study. Primary interviews with plant engineers, OEM platform procurement leads, pharmaceutical validation specialists, and channel sales heads at industrial automation distributors combined with secondary validation against SEC 10-K filings, FDA 510(k) submission databases, EU AI Act regulatory drafts, and IHS Markit vehicle production data. Triangulation across these sources ensures demand-side consumption patterns align with supply-side component availability constraints.
Historical trendline analysis of platform licensing revenue and edge hardware shipment volumes established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, application function, and end-use vertical intensity. CAGRs derive from regression analysis against industrial automation capital expenditure cycles and electric vehicle production ramp schedules. Industry-specific forecast inputs incorporate battery module assembly sensor density multipliers and pharmaceutical FDA inspection queue backlogs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan semiconductor foundry capacity allocation shifts and EU AI Act enforcement variance across national regulators. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Policy Orchestration Market
Digital Solutions
Captioning and Subtitling Solutions Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Big Data Technology Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Change Management Software Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Decision Support System Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Digital Notepad Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Condition Monitoring Software Market