
 Global Genealogy Products and Services Market | 2026-2036
Global Genealogy Products and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Genealogy Products and Services Market Analysis
ISO 15189 accreditation for medical laboratory quality management is redrawing competitive boundaries in genetic genealogy. Ancestry leverages its proprietary database scale to dominate consumer DNA matching. MyHeritage competes through multilingual platform access across European markets. 23andMe differentiates via health-trait integration beyond pure ancestry reporting.
Genealogy products and services encompass DNA testing kits, family tree software, and subscription-based record databases that employ autosomal, Y-chromosome, and mitochondrial analysis with SNP-chip densities exceeding 700,000 markers to establish biological relationships and ethnic origin estimates. DNA testing kits capture the largest revenue share among product types due to high per-unit pricing and repeat purchase potential for specialized tests. Online subscription services generate recurring revenue streams with lower customer acquisition costs over time. Cloud-based solutions within the technology segment enable real-time collaboration between distant family members and institutional researchers.
FDA oversight of direct-to-consumer genetic health risk assessments shapes product development timelines and marketing claims in the United States. EMA guidance on in vitro diagnostic medical devices influences regulatory pathways for European market entry. GDPR data portability and consent requirements constrain cross-border genetic data flows from EU member states. Stakeholders must monitor evolving classification of ancestry databases as clinical research infrastructure versus consumer entertainment platforms.
Market Dynamics
Consumer DNA testing platforms are compressing the traditional archival research cycle from months to hours, forcing institutional genealogical services to restructure their value proposition around interpretation and verification rather than raw record retrieval.
Growth Catalysts
- GDPR data portability mandates:European consumers can now transfer genetic profiles between platforms, lowering switching costs and expanding addressable market size for secondary providers.
- SNP-chip density advancement:Next-generation microarrays exceeding 700,000 markers enable granular ethnic origin estimates that satisfy demand from amateur historians seeking precise geographic attribution.
- Cloud-based collaboration tools:Real-time family tree editing across distributed research teams is displacing siloed desktop software in the United States, the United Kingdom, and Germany.
Market Restraints
- Illumina supply concentration:Single-source dependency for sequencing chip fabrication creates vulnerability to production bottlenecks and price volatility.
- FDA premarket review timelines:Direct-to-consumer health risk assessments face extended approval pathways that delay product launches and compress marketing windows.
- Archival digitization costs:Church and civil record holders in Southern Europe demand prohibitive licensing fees for historical document scanning.
Strategic Opportunities
- India's unpenetrated market:Low DNA testing penetration among 1.4 billion people with strong oral tradition culture creates first-mover potential for platforms adapting to caste-sensitive privacy frameworks.
- Health system integration:Pharmacogenomic data from ancestry databases is converging with clinical decision support tools, opening reimbursement pathways through national health services.
- Brazil's ANVISA streamlined pathway:Recent regulatory harmonization reduces import barriers for testing kits, enabling direct distribution without local laboratory partnerships.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of computational biologists capable of interpreting complex admixture algorithms constrains product development velocity.
- ISO 15189 accreditation timelines:Medical laboratory quality certification requires 18-24 month implementation cycles that delay service line expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Genealogy Products and Services Market |
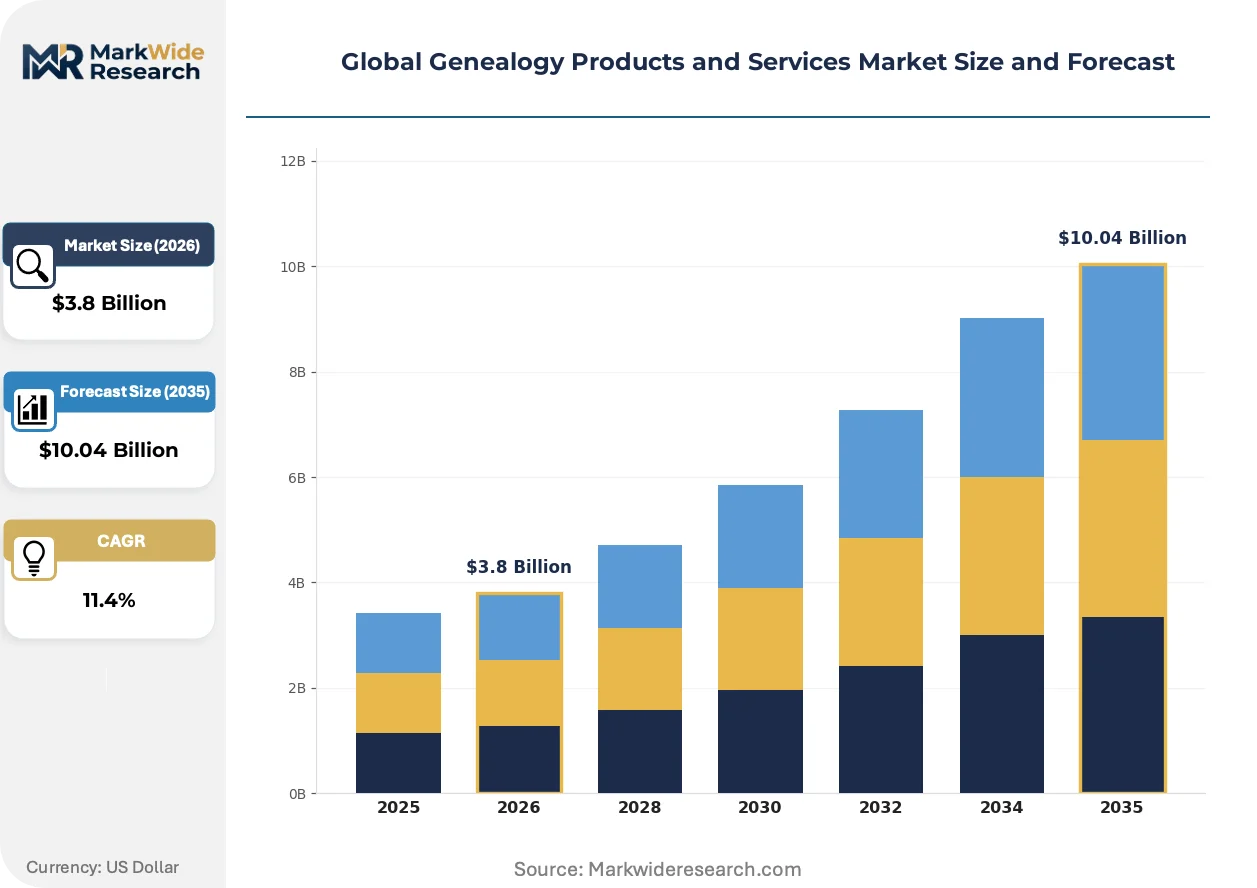
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Testing Kits, Family Tree Software, Books, Online Subscription Services End User: Individuals, Research Institutions, Educational Organizations, Libraries Technology: Cloud-Based Solutions, Mobile Applications, Database Management Systems, Genetic Analysis Tools Service Type: Consulting Services, Research Services, Data Analysis, Educational Workshops |
| Companies Covered | Ancestry, MyHeritage, 23andMe, FamilySearch, Geneanet, Findmypast, Family Tree DNA, Living DNA, WikiTree, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Genealogy Products and Services Market Emerging Trajectories
Artificial intelligence is resequencing how genetic matches are prioritized and presented, compressing the interpretive burden on users while raising computational infrastructure requirements across the vendor base.
Whole-genome sequencing at consumer price points is displacing SNP-chip arrays as the default technology for serious genealogists and medical researchers seeking comprehensive variant detection. Early adopters in the United States and United Kingdom are migrating to platforms offering 30x coverage depth. This shift is compressing the addressable market for chip-based testing while expanding subscription revenue from raw data interpretation services.
EMA guidance on in vitro diagnostic medical devices is reclassifying ancestry platforms with health-adjacent reporting, triggering conformity assessment obligations that favor larger database operators with dedicated regulatory affairs functions. Smaller entrants face documentation burdens that extend European market entry timelines. The directive most acutely affects German and French platforms attempting to add pharmacogenomic features.
Subscription unbundling is fragmenting the traditional all-access model as users in Germany and the United Kingdom purchase narrow record sets for specific surname or parish research rather than annual commitments. Genealogy societies and local archives are capturing disaffected customers through pay-per-document microtransactions. This behavioral shift is most visible among users aged 55-70 conducting targeted immigrant ancestor verification.
Global Genealogy Products and Services Market Segmentation
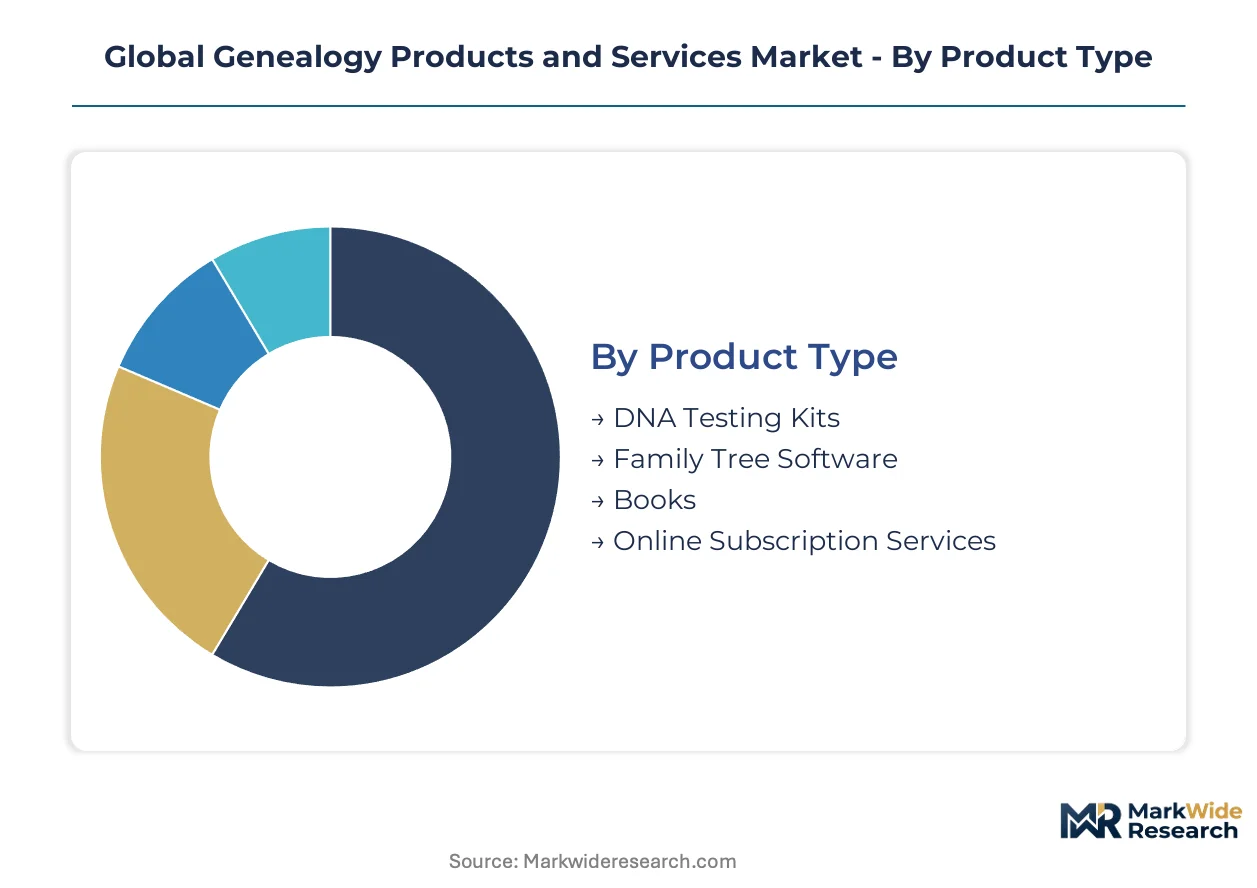
Genealogy market segmentation reveals distinct procurement patterns across consumer and institutional channels. Product type and technology choices diverge sharply between amateur family historians seeking convenience and research institutions demanding analytical depth.
Product Type:
DNA Testing Kits and Family Tree Software dominate export volumes from United States and United Kingdom manufacturing bases, while Books and Online Subscription Services concentrate domestic consumption in Germany and France.
- DNA Testing Kits:Autosomal, Y-chromosome, and mitochondrial analysis platforms utilizing SNP-chip densities exceeding 700,000 markers. Demand concentrates in the United States and United Kingdom where direct-to-consumer health integration drives repeat purchases for specialized panels.
- Family Tree Software:Desktop and hybrid cloud-desktop applications enabling pedigree construction and source citation management. German-speaking markets show strongest adoption due to stringent data localization preferences and GDPR-driven on-premise storage requirements.
- Books:Printed genealogical guides, regional record inventories, and surname dictionaries serving reference collections. Public libraries in France and Italy maintain procurement budgets for physical reference materials despite digital transition pressures.
- Online Subscription Services:Recurring-access platforms to digitized civil, church, and military records. United Kingdom and Irish repositories command premium licensing fees that compress margins for secondary aggregators.
DNA Testing Kits holds the largest share; momentum sits with Online Subscription Services as recurring revenue models displace one-time kit purchases.
End User:
Customer type determines pricing architecture, with Individuals purchasing through retail channels and Research Institutions negotiating enterprise licenses for database access.
- Individuals:Amateur family historians, adoptees seeking biological relatives, and ethnicity-curious consumers purchasing through e-commerce and pharmacy retail. United States consumers drive volume through seasonal promotional cycles.
- Research Institutions:Universities, government archives, and private genealogical research firms requiring bulk record access and API integration. British and German national archives sponsor institutional subscriptions to democratize historical document access.
- Educational Organizations:Secondary schools and undergraduate programs incorporating genealogical methods into history and biology curricula. Irish heritage tourism programs embed DNA testing into educational travel packages.
- Libraries:Public and academic library systems providing patron access to subscription databases through authenticated terminals. Municipal library networks in Canada and Australia aggregate demand for multi-branch licensing.
Individuals generate the highest transaction volume; Research Institutions deliver the steepest expansion trajectory as academic genealogy programs proliferate.
Technology:
Technology selection tracks infrastructure maturity, with Cloud-Based Solutions penetrating urban markets and Mobile Applications capturing rural and developing-region users.
- Cloud-Based Solutions:Real-time collaborative family tree editing and distributed record indexing platforms. United States and United Kingdom adoption rates reflect broadband penetration and comfort with cross-border data hosting.
- Mobile Applications:Smartphone-native genealogy tools with offline record caching and camera-based document capture. Indian and Brazilian markets show fastest uptake where mobile-first internet access predominates.
- Database Management Systems:Enterprise-grade archival platforms supporting multi-terabyte record repositories. Vatican Apostolic Archive and national archives in Spain deploy these for centuries-spanning document preservation.
- Genetic Analysis Tools:Bioinformatics pipelines for admixture modeling, haplogroup assignment, and relationship probability calculation. Research hospitals in Sweden and Denmark integrate these into clinical genetics workflows.
Cloud-Based Solutions command current infrastructure investment; Mobile Applications are climbing the fastest as smartphone penetration extends addressable markets.
Service Type:
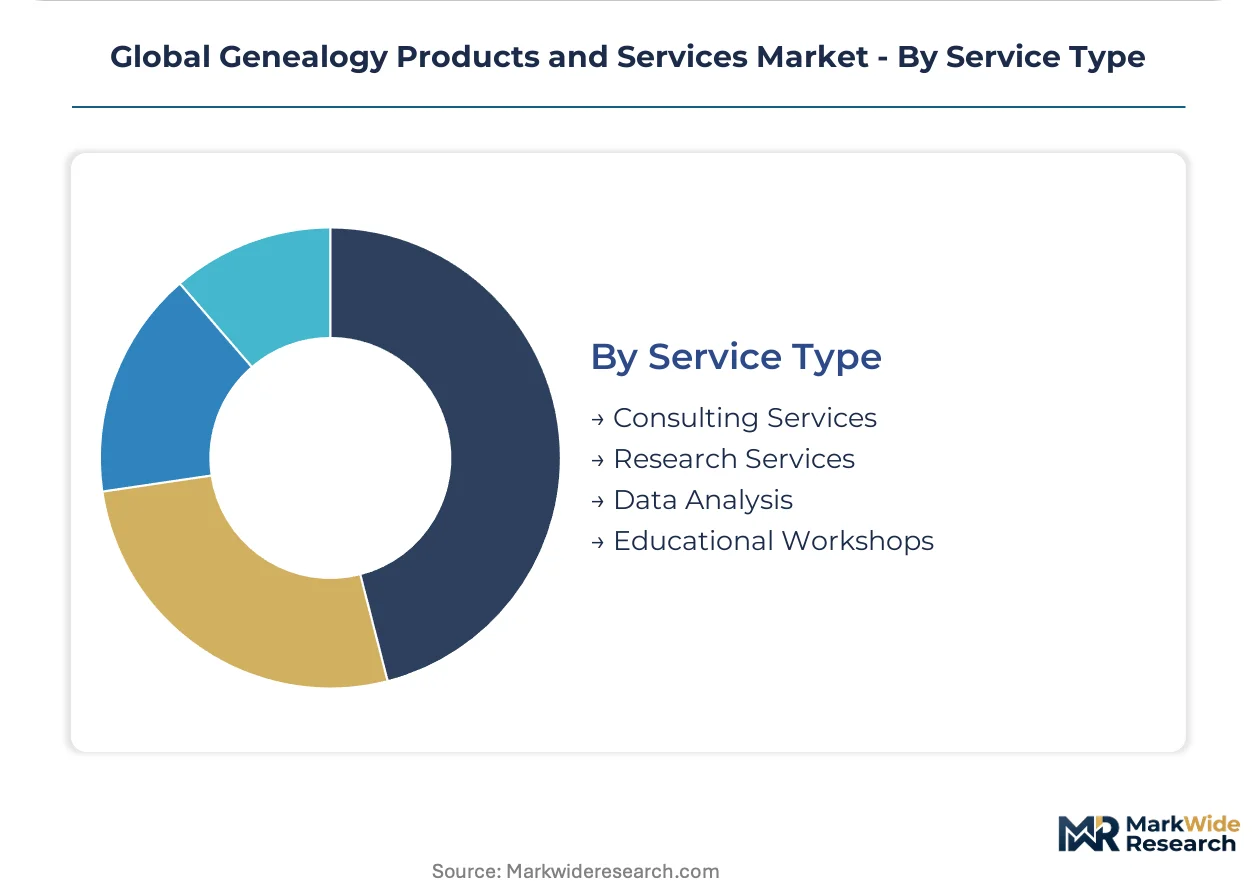
Service procurement splits between self-directed digital tools and professional assistance for complex research problems or language-barrier records.
- Consulting Services:Professional genealogist engagement for brick-wall ancestor identification and lineage society documentation. Demand clusters in United States and Australia where lineage-based organizations require certified documentation.
- Research Services:Commissioned record retrieval from specific archives, churches, or civil registrars. Italian and Polish regional specialists capture this demand for non-digitized parish records.
- Data Analysis:Interpretation of DNA match lists, chromosome segment mapping, and ethnicity estimate refinement. United Kingdom and Netherlands markets show growing uptake as test-taker databases mature.
- Educational Workshops:In-person and virtual training on research methodology, DNA interpretation, and archival navigation. Genealogical societies in Germany and France organize these to retain membership relevance.
Consulting Services retains the largest revenue pool; Data Analysis is gaining share fastest as genetic genealogy complexity outpaces consumer self-sufficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government digitization grants and data protection frameworks are redrawing geographic opportunity maps for genealogy providers. National archive investment programs in the United States, United Kingdom, Germany, Brazil, and India are accelerating platform localization requirements.
United States
Seasonal promotional cycles through pharmacy retail channels drive consumer DNA kit volume. FDA premarket review timelines for direct-to-consumer health risk assessments compress marketing windows for integrated platforms. The Greater Boston corridor hosts bioinformatics clusters developing admixture algorithms for ethnicity estimation.
United Kingdom
Premium licensing fees for Irish and British civil record repositories compress margins for secondary aggregators. GDPR data portability mandates enable genetic profile transfers between platforms, lowering consumer switching costs. London-based genealogical societies are capturing disaffected customers through pay-per-document microtransactions.
Germany
Stringent data localization preferences and GDPR-driven on-premise storage requirements favor hybrid cloud-desktop family tree applications. EMA guidance on in vitro diagnostic medical devices triggers conformity assessments for health-adjacent ancestry reporting. Bavarian municipal archives are deploying enterprise-grade database management systems for centuries-spanning document preservation.
Brazil
ANVISA regulatory harmonization has reduced import barriers for testing kits, enabling direct distribution without local laboratory partnerships. Mobile-first internet access patterns favor smartphone-native genealogy tools with offline record caching. São Paulo's emerging consumer base shows fastest uptake for camera-based document capture applications.
India
Low DNA testing penetration among 1.4 billion people with strong oral tradition culture creates first-mover potential for privacy-adapted platforms. The country's national pharmaceutical regulator is developing frameworks for direct-to-consumer genetic health assessments. Maharashtra's urban centers are piloting cloud-based collaboration tools for real-time family tree editing.
Global Genealogy Products and Services Market Vendor Landscape
Player mix skews toward database-scale operators with proprietary genetic repositories and subscription-based record platforms. The vendor base concentrates around three strategic archetypes: integrated health-ancestry providers, pure-play DNA matching services, and archival record aggregators. Competitive dynamics center on M&A activity targeting regional record repositories and technology licensing partnerships for SNP-chip fabrication.
Within the database-scale tier, Ancestry and MyHeritage exemplify divergent geographic strategies, with the former leveraging North American market depth and the latter occupying a position across multilingual European access points. 23andMe represents the health-ancestry integration archetype, anchoring the segment where pharmacogenomic data converges with clinical decision support tools.
| Leading Market Players |
|---|
| Ancestry |
| MyHeritage |
| 23andMe |
| FamilySearch |
| Geneanet |
| Findmypast |
| Family Tree DNA |
| Living DNA |
| WikiTree |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month ISO 15189 accreditation timelines compress inventory turnover for genetic testing laboratories and concentrate pricing power with Illumina as the sole qualified chip fabricator. This lead-time rigidity forces ancestry platforms to pre-position SNP-chip stockpiles ahead of seasonal promotional cycles, amplifying working capital intensity while constraining margin flexibility for secondary entrants.
Pricing Analysis
Certification level creates the primary spread between premium clinical-grade and standard consumer-tier offerings. The dominant pricing structure runs through tiered subscription models with annual commitments for record database access alongside per-unit transactional pricing for DNA testing kits. Price differentiation rests on FDA premarket review status and GDPR compliance depth, with health-integrated platforms commanding substantial premiums over pure ancestry services. Cost compression in the entry tier is intensifying because Illumina supply bottlenecks force smaller aggregators to absorb chip price volatility. Research institutions exhibit the lowest price sensitivity due to enterprise licensing budgets, while individual hobbyists in developing markets demonstrate acute elasticity.
Supply Chain Analysis
Strategic stockpiling of SNP-chips dominates inventory strategy given single-source fabrication vulnerability and seasonal demand spikes. Geographic supply concentrates in the United States for cloud infrastructure and bioinformatics talent, Germany for precision manufacturing equipment, and China for sequencing consumables. Raw material dependencies include silicon wafers, polymerase reagents, and specialized packaging for biological specimen collection. Single-source vulnerability for microarray fabrication represents the critical structural risk. Distribution runs through direct-to-consumer e-commerce channels and pharmacy retail partnerships in North America, with hybrid cloud-desktop delivery for software solutions in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery driven by post-pandemic archive digitization grants and deferred health system integration projects. Recovery durability hinges on sustained consumer discretionary spending and regulatory clarity for pharmacogenomic data sharing.
For Market Incumbents: Compound database network effects through exclusive licensing agreements with national archives in India and Brazil before competitors establish local laboratory partnerships. Invest in ISO 15189 accreditation for core processing facilities to defend margin position against emerging clinical-grade entrants. Prioritize backward integration into bioinformatics talent pipelines to alleviate computational biologist scarcity constraining product velocity.
For New Entrants and Emerging Players: Differentiate on caste-sensitive privacy frameworks and oral tradition digitization tools to penetrate India's unaddressed 1.4 billion population base. Target pay-per-document microtransaction models among disaffected subscription users aged 55-70 in Germany and the United Kingdom. Pursue camera-based document capture applications for mobile-first markets in Brazil where offline functionality addresses connectivity gaps.
For Investors and Strategic Acquirers: Long-term, this sits as a data infrastructure play because proprietary genetic repositories appreciate in value through network effects and health system integration pathways. Acquisition targets should emphasize regional record aggregators with exclusive parish and civil document holdings in Southern Europe. Watch FDA guidance on direct-to-consumer pharmacogenomic reporting as the inflection signal for clinical revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Archive Licensing | Locks in proprietary content pipelines from Vatican Apostolic Archive and Bavarian municipal repositories. |
| ISO 15189 Accreditation | Opens reimbursement pathways through NHS England and German statutory health insurance frameworks. |
| Mobile-First Platform Launch | Captures Brazilian and Indian consumers where smartphone penetration exceeds desktop access. |
| Pharmacogenomic Integration | Converges ancestry databases with clinical decision support tools in Swedish and Danish hospital systems. |
| GDPR-Compliant Data Portability | Enables profile transfers that expand addressable market for secondary European providers. |
Methodological Framework
Cross-validation between primary interviews with genetic testing laboratory directors and secondary analysis of FDA premarket notification filings anchors the qualitative findings. Conversations with bioinformatics pipeline architects, regulatory affairs specialists at ancestry platforms, archivists at national record repositories, and procurement officers at research institutions generated operational insight. Secondary sources include EMA guidance documents on in vitro diagnostic classification, GDPR enforcement decisions from European data protection authorities, ANVISA regulatory harmonization notices, and customs trade data for sequencing equipment imports. Bottom-up triangulation of kit shipment volumes and subscription renewal rates converges with top-down expenditure estimates from national digitization grant programs.
Sensitivity analysis across SNP-chip pricing scenarios and archive licensing fee trajectories informs the projection envelope. The analytical framework segments by product type, end user archetype, technology deployment model, and geographic regulatory cluster across the analysis window. CAGRs derive from logistic adoption curves for DNA testing penetration and recurring revenue retention modeling for subscription services. Industry-specific inputs include Illumina supply capacity announcements, FDA review timeline distributions, and GDPR portability utilization rates.
Material uncertainties — regulatory reclassification of ancestry databases as clinical research infrastructure, Illumina production disruptions, and archival digitization cost inflation — sit outside the modeled envelope. Forecasts reflect assumptions about sustained consumer discretionary spending and stable intellectual property frameworks for genetic data. Revision becomes warranted when health system integration adoption crosses institutional procurement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mexico Online Gambling Market
Digital Solutions
Product Data Management Market
Digital Solutions
Agriculture Software Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Equipment Tracking Software Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Web Performance Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Change and Configuration Management Market