
 Dating Services Market | 2026-2036
Dating Services Market Size, Share, and Industry Trends Forecast 2026-2036
Dating Services Market Intelligence
Premium subscription tiers is rotating toward the center of revenue strategy across the Dating Services Market. Match Group, Inc. leverages its portfolio breadth to sustain multi-brand dominance across demographic niches. Bumble Inc. differentiates through women-first messaging architecture that anchors brand loyalty in North American and European cities. eHarmony, Inc. specializes in compatibility psychology, occupying a defensible position among marriage-oriented users.
Dating services encompass digital platforms and offline intermediaries that facilitate romantic partner discovery through algorithmic profiling, user-generated content, and mediated communication channels. Core technical specifications include real-time geolocation engines, machine learning-based compatibility scoring, and end-to-end encrypted messaging protocols designed to optimize match probability while preserving user privacy. Subscription-based monetization leads the service type architecture, while freemium models represent the fastest-growing acquisition funnel as platforms prioritize scale before conversion. Mobile app distribution dominates platform type engagement, with behavioral matching algorithms capturing disproportionate R&D investment as swipe-fatigue drives demand for predictive compatibility systems.
FCC guidelines on digital advertising transparency and GDPR data minimization requirements in Europe constrain how platforms collect and monetize user behavioral data. India's TRAI framework for digital consumer protection and the EU AI Act's risk classification for biometric inference systems are forcing architectural redesigns of recommendation engines. Stakeholders must monitor emerging algorithmic accountability legislation across multiple jurisdictions to anticipate compliance costs that could reshape competitive economics.
Market Dynamics
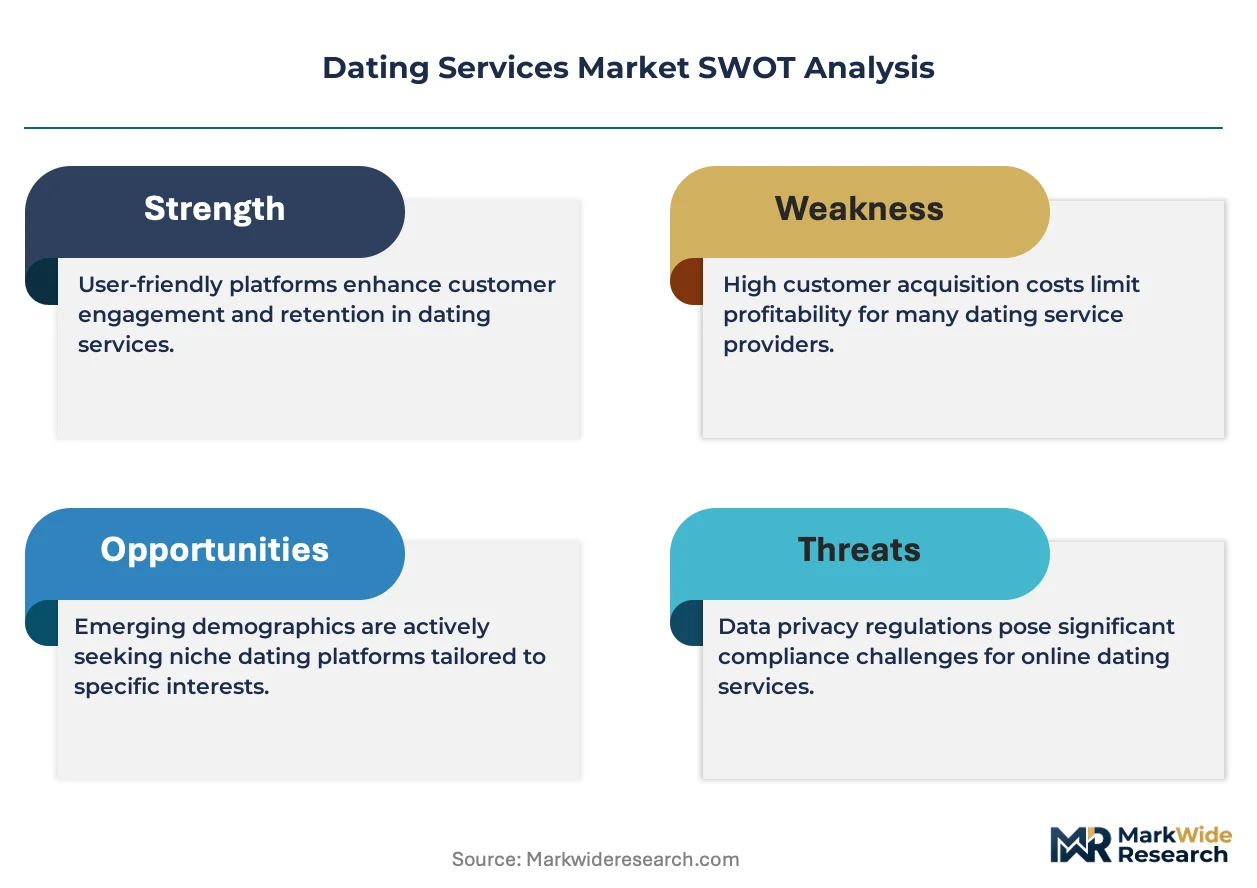
AI-powered matching architectures and biometric inference systems are forcing platform operators to rebuild recommendation engines around explainability requirements, compressing development timelines while elevating compliance costs across jurisdictions.
Growth Catalysts
- GDPR Data Portability Mandates:European users gain frictionless account migration rights, reducing switching costs and intensifying platform competition for retention engineering.
- Behavioral Matching Algorithms:Machine learning systems analyzing communication patterns and engagement timing now outperform static profile-based compatibility scoring in user satisfaction metrics.
- Urban Young Professionals:Dense metropolitan clusters in the United States, China, and India generate network effects that accelerate organic user acquisition without proportional marketing spend.
Market Restraints
- Biometric Inference Restrictions:The EU AI Act's high-risk classification for emotion recognition and facial analysis limits deployment of photo-based attraction prediction models.
- Input Cost Volatility:Cloud compute pricing for real-time geolocation engines and machine learning inference fluctuates with energy markets, squeezing gross margins on freemium tiers.
- Platform Concentration Risk:Apple and Google app store duopoly control over mobile distribution enables unilateral commission rate adjustments and policy enforcement.
Strategic Opportunities
- Voice-First Interfaces:Audio-based profile browsing and asynchronous voice messaging converge with podcast consumption habits among commuter demographics in India.
- Offline Event Integration:Curated experiences and speed-dating partnerships create hybrid revenue streams less dependent on digital engagement metrics.
- India's TRAI Digital Consumer Framework:Emerging data localization and consent management rules favor domestic platform operators with compliant infrastructure already deployed.
Industry Challenges
- Machine Learning Talent Scarcity:Competition for recommendation system engineers with privacy-preserving computation expertise outpaces supply in all major hiring markets.
- Cross-Border Data Architecture Complexity:Reconciling GDPR right-to-explanation requirements with China's data sovereignty rules forces costly regional infrastructure duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dating Services Market |
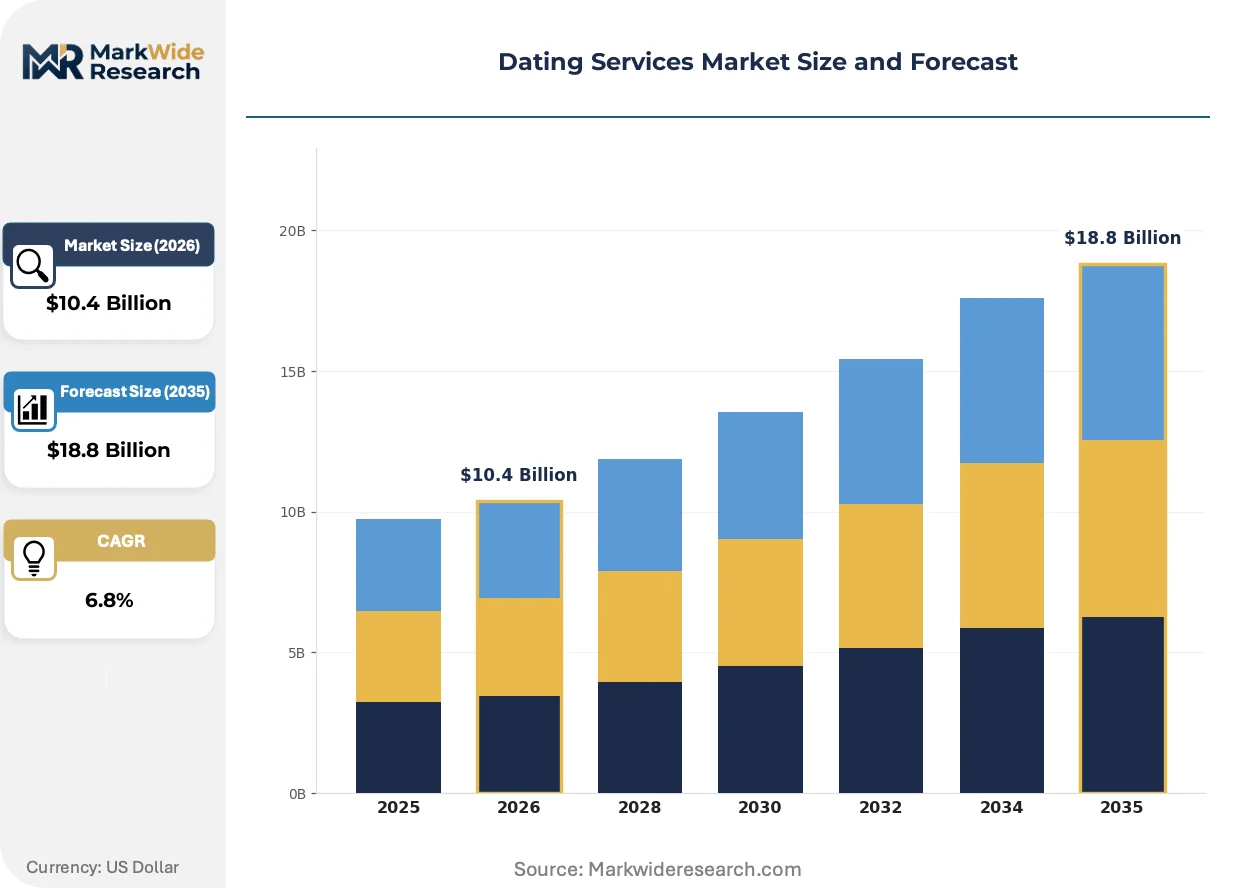
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $18.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription-Based, Freemium, Pay Per Message, Premium Target Audience: Singles, Couples, LGBTQ+, Seniors Platform Type: Mobile App, Website, Social Media, Events Matching Algorithm: Personality Based, Interest-Based, Location-Based, Behavioral |
| Companies Covered | Match Group, Inc., Bumble Inc., eHarmony, Inc., Grindr LLC, Spark Networks SE, The Meet Group, Inc., Love Group Global Ltd., Coffee Meets Bagel, Zoosk, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dating Services Market Strategic Shifts & Innovations
Generative AI and multimodal content creation tools are compressing the traditional profile-building workflow, while regulatory pressure on algorithmic transparency accelerates investment in interpretable matching systems.
Natural language processing for conversation coaching is decomposing the traditional human-mediated dating advice market. Young professionals in North American and European cities adopt AI-generated opening messages and response suggestions at accelerating rates. This capability compression threatens standalone coaching apps and premium human matchmaker services by embedding equivalent functionality into base platform subscriptions.
The EU AI Act's risk classification framework for biometric inference systems is mandating architectural audits of photo-based attraction algorithms. Platform operators must document training data provenance and model decision boundaries for European regulators. Marriage-oriented services relying heavily on facial symmetry analysis face the steepest compliance redesign costs and timeline extensions.
Subscription fatigue among digital natives is fragmenting willingness to pay across multiple concurrent dating platforms. Users in the United States increasingly rotate between three or more apps seasonally rather than maintaining single-platform loyalty. This behavior compresses lifetime value calculations and forces operators toward higher-velocity conversion funnels and shorter free trial periods.
Dating Services Market Segmentation
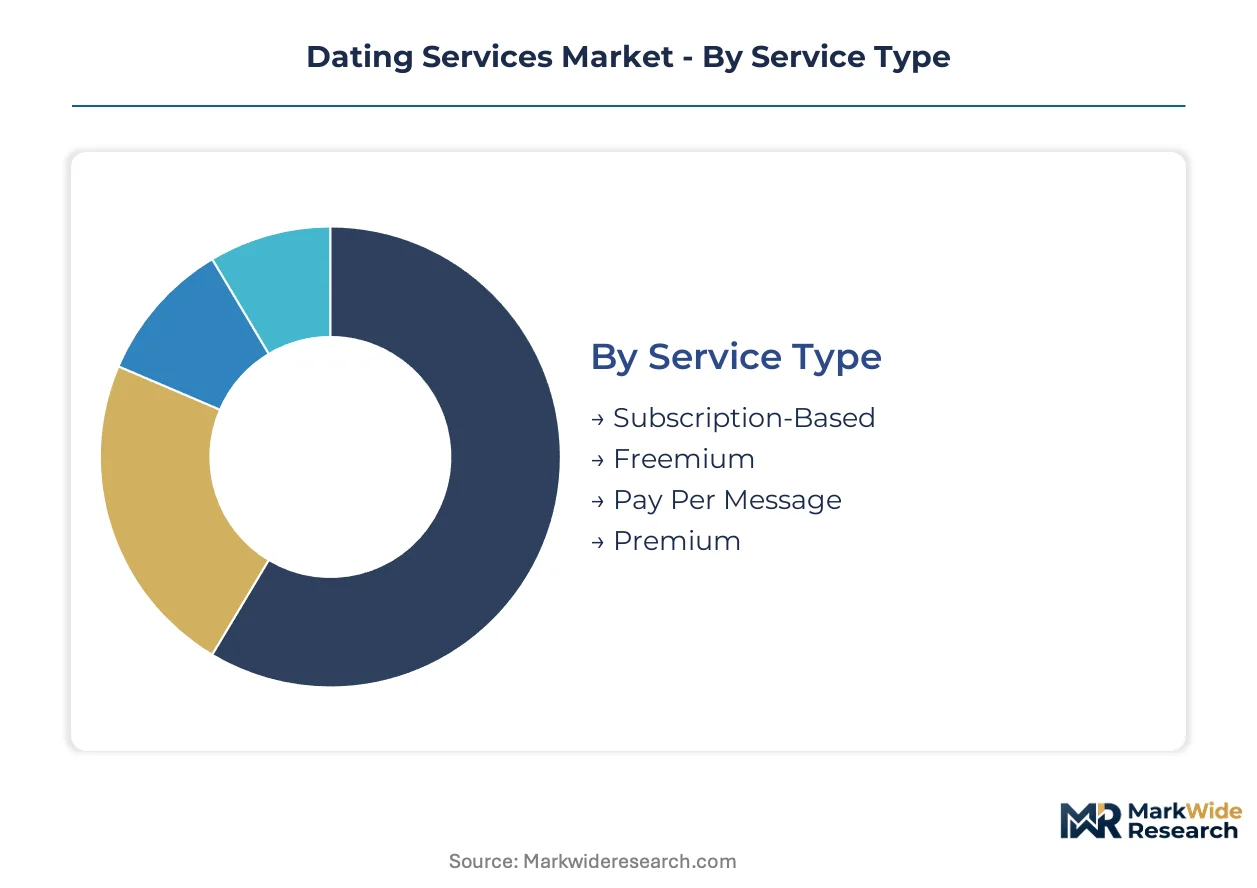
Segmentation in dating services reveals divergent monetization architectures and user acquisition strategies. Each category reflects distinct technical investments, regulatory exposure, and geographic penetration patterns that shape competitive economics.
Service Type:
Subscription models dominate revenue concentration in the United States and United Kingdom, while freemium architectures drive user scale in India and Brazil. Pay-per-message systems cluster in markets with lower credit card penetration.
- Subscription-Based:Recurring revenue streams lock in predictable cash flows through monthly or annual billing cycles. Young professionals in dense metropolitan clusters sustain the highest renewal rates as platforms optimize retention engineering through algorithmic curation.
- Freemium:Zero-cost entry tiers convert users through engagement depth rather than upfront commitment. Indian and Southeast Asian markets exhibit the highest freemium-to-paid conversion velocity as mobile-first adoption accelerates across tier-2 cities.
- Pay Per Message:Microtransaction models align costs with actual usage intensity. Emerging markets with variable income patterns favor this structure over fixed subscription commitments.
- Premium:White-glove tiers bundle human matchmaker access, profile optimization, and priority algorithmic placement. Marriage-oriented demographics in South Korea and Japan sustain disproportionate premium tier attachment.
Subscription-Based commands the established base. The steepest expansion runs through Freemium.
Target Audience:
Audience segmentation maps directly to platform design priorities and content moderation investments. Singles categories concentrate in North American and European urban centers, while senior demographics show accelerating adoption in Japan and Germany.
- Singles:Unpartnered individuals seeking romantic connections constitute the core addressable market. Urban young professionals across the United States, China, and India generate network effects that reduce customer acquisition costs.
- Couples:Established partnerships seeking social networking or activity coordination represent an adjacent expansion vector. European cities exhibit the highest couple-oriented platform engagement outside traditional dating contexts.
- LGBTQ+:Specialized safety features and community verification protocols address distinct privacy requirements. Brazil and Thailand host the most concentrated LGBTQ+ platform development outside North America.
- Seniors:Simplified interfaces and fraud protection systems accommodate lower digital literacy rates. Japan's aging population drives the most advanced senior-specific feature development globally.
Singles anchors volume concentration. Seniors are climbing the fastest as demographic tailwinds intensify.
Platform Type:
Distribution architecture determines regulatory exposure and monetization mechanics. Mobile-first strategies dominate in India and Nigeria, while website persistence remains significant in German and Japanese markets with older user bases.
- Mobile App:Native iOS and Android applications capture the dominant share of session time through push notification engagement. Apple's App Store and Google's Play Store duopoly constrains distribution economics through commission structures.
- Website:Browser-based access persists among desktop-oriented demographics and privacy-conscious users. European markets maintain higher website engagement rates relative to mobile-only platforms.
- Social Media:Integration with existing social graphs reduces profile creation friction. Instagram and TikTok embedded dating features threaten standalone platform retention in younger demographics.
- Events:Curated offline experiences generate hybrid revenue streams less dependent on digital engagement metrics. Speed-dating partnerships in London and New York command premium pricing through exclusivity.
Mobile App holds the volume base. Events are gaining share fastest as swipe-fatigue intensifies.
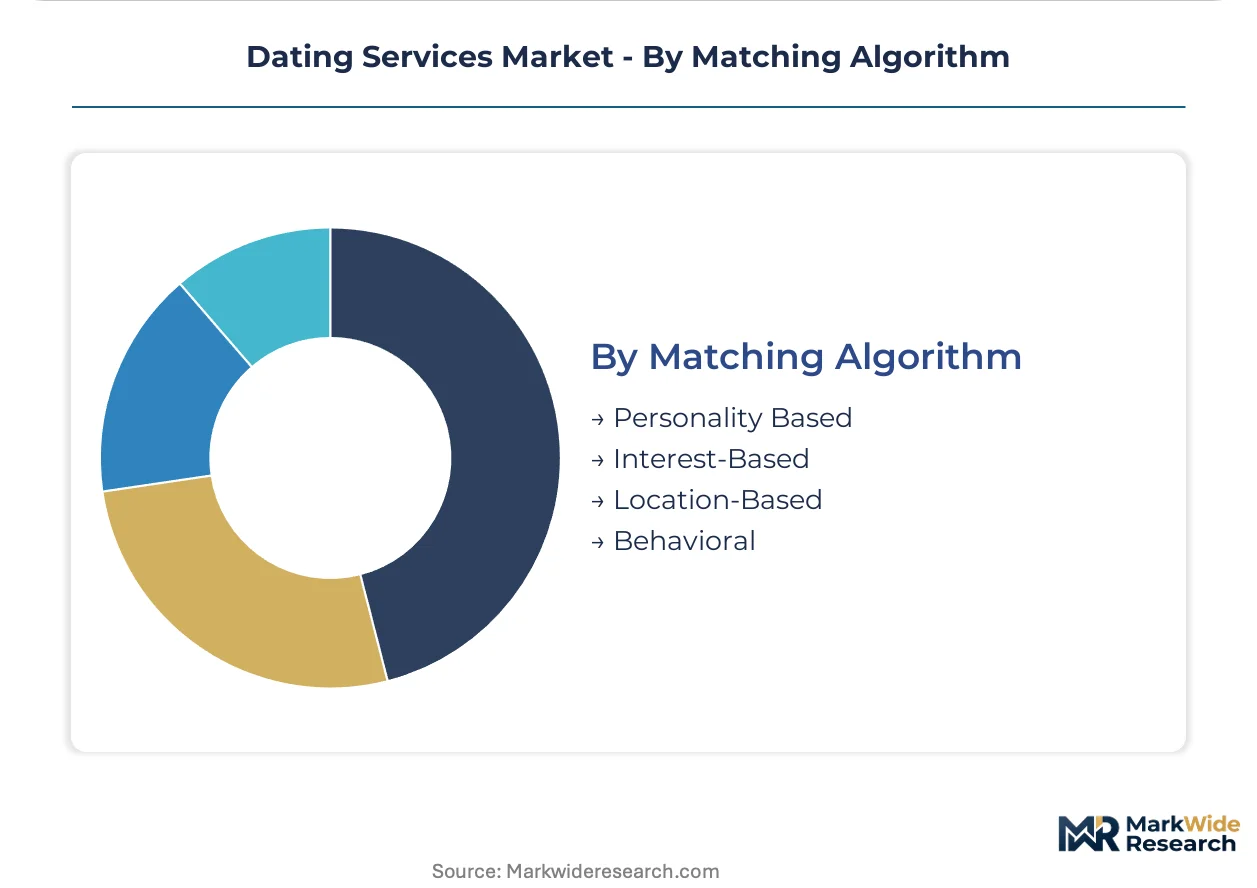
Matching Algorithm:
Algorithmic sophistication separates premium positioning from commodity competition. Behavioral systems attract the highest R&D investment in Silicon Valley and Tel Aviv, while personality-based approaches retain strength in German-speaking markets.
- Personality Based:Psychometric assessment batteries generate compatibility scores through validated psychological frameworks. eHarmony pioneered this architecture, sustaining defensible positioning among marriage-oriented users.
- Interest-Based:Shared hobby and activity preferences drive matching logic through explicit user declarations. Niche platforms targeting specific subcultures deploy this approach to minimize algorithmic development costs.
- Location-Based:Real-time geolocation engines prioritize proximity over compatibility depth. Urban density in São Paulo and Jakarta maximizes the efficacy of pure location-driven discovery.
- Behavioral:Machine learning systems infer preference from swipe patterns, message timing, and engagement duration. GDPR right-to-explanation requirements and EU AI Act biometric restrictions constrain deployment in European markets.
Personality Based retains the loyalist base. Behavioral systems show the steepest expansion trajectory as predictive accuracy improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform development concentrates in jurisdictions with mature mobile infrastructure and favorable regulatory treatment of algorithmic systems. The United States, China, and India generate the dominant share of user acquisition velocity and R&D investment flows.
United States
Urban young professionals in New York, Los Angeles, and Austin sustain the highest subscription renewal rates among developed markets. FCC guidelines on digital advertising transparency constrain behavioral data collection practices. Silicon Valley maintains the deepest concentration of machine learning engineering talent for recommendation system development.
China
MIIT data localization requirements and SAMR platform governance rules shape architectural decisions for domestic operators. Dense metropolitan clusters in Shanghai, Beijing, and Shenzhen generate network effects that reduce customer acquisition costs. The country's national consumer protection regulator enforces strict consent management protocols for biometric inference systems.
India
TRAI's emerging digital consumer framework favors domestic operators with compliant infrastructure already deployed. Tier-2 cities across Maharashtra and Karnataka exhibit accelerating mobile-first adoption among young professionals. Bangalore anchors the regional engineering base for voice-first interface development targeting commuter demographics.
Germany
GDPR right-to-explanation requirements and EU AI Act biometric restrictions elevate compliance costs for behavioral matching algorithms. Berlin and Hamburg maintain higher website engagement rates relative to mobile-only platforms. The country's federal data protection authority enforces strict model documentation standards for photo-based attraction prediction systems.
United Kingdom
Subscription models dominate revenue concentration in London and Manchester metropolitan clusters. The Information Commissioner's Office mandates algorithmic transparency audits for platforms processing sensitive demographic data. Edinburgh hosts specialized development teams focused on privacy-preserving computation techniques for compatibility scoring.
Dating Services Market Key Industry Players
Concentration sits with multi-brand portfolio operators and women-first messaging architectures. The market exhibits tiered structure with consolidated dominance at the top and fragmented specialization below. Three archetypes define competitive positioning: portfolio conglomerates with demographic niche coverage, differentiation-focused platforms with distinct interaction protocols, and psychology-specialized services for marriage-oriented segments. Dominant competitive moves include portfolio diversification across age cohorts and strategic partnerships with offline event curators.
Within the portfolio conglomerate tier, Match Group, Inc. and Bumble Inc. exemplify divergent approaches to multi-brand architecture. Match Group, Inc. anchors breadth-based positioning across demographic niches through its collection of distinct platform identities. Bumble Inc. occupies a defensible position through its women-first messaging protocol that generates brand loyalty in North American and European urban centers. eHarmony, Inc. represents the psychology-specialized archetype, sustaining attachment among marriage-oriented users through compatibility assessment frameworks.
| Leading Market Players |
|---|
| Match Group, Inc. |
| Bumble Inc. |
| eHarmony, Inc. |
| Grindr LLC |
| Spark Networks SE |
| The Meet Group, Inc. |
| Love Group Global Ltd. |
| Coffee Meets Bagel |
| Zoosk, Inc. |
| Others |
Cost & Logistics Intelligence
GDPR data minimization requirements and the EU AI Act's biometric inference restrictions simultaneously gate supplier qualification for algorithmic matching systems and compress price differentiation between compliance-heavy European deployments and lighter-touch jurisdictions. Subscription fatigue among digital natives feeds back into supply chain choices as platforms prioritize cloud infrastructure elasticity over fixed-capacity commitments.
Pricing Analysis
GDPR data portability mandates dictate the pricing tier structure across European deployments, forcing operators to absorb higher compliance costs in premium tiers while standard offerings face margin compression. Three-tier pricing structure across premium, standard, and economy levels separates white-glove human matchmaker bundles from algorithmic-only access and freemium entry points. Price differentiation hinges on privacy-preserving computation certification levels and geographic data residency compliance. Margins are tightening in standard tiers due to cloud compute pricing volatility for real-time geolocation engines. Young professionals in dense metropolitan clusters exhibit the lowest price sensitivity, while rotating seasonal users across multiple platforms drive the highest acquisition cost pressure.
Supply Chain Analysis
The United States and India anchor machine learning engineering talent for behavioral matching algorithm development, while Ireland and Singapore host regional data infrastructure for GDPR-compliant European operations. Cloud compute capacity for real-time inference draws from hyperscaler facilities concentrated in Virginia, Mumbai, and Frankfurt. Supply chain risk centers on Apple and Google's app store duopoly control over mobile distribution, enabling unilateral commission adjustments that squeeze platform economics. Distribution runs through native iOS and Android applications with website persistence in privacy-conscious European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dating services sit in early-cycle expansion as AI-powered matching architectures penetrate beyond early adopter urban demographics into tier-2 cities across India and Southeast Asia.
For Market Incumbents: Shield core subscription revenue through accelerated investment in privacy-preserving computation expertise as GDPR right-to-explanation requirements deepen. Consolidate defensible positioning by acquiring voice-first interface specialists in Bangalore before commuter demographic penetration accelerates. Backward integration into curated offline event infrastructure reduces dependence on digital engagement metrics vulnerable to swipe-fatigue churn. For New Entrants and Emerging Players: Anchor in India's tier-2 cities where TRAI's emerging data localization rules favor domestic operators with compliant infrastructure already deployed. Target senior demographics in Japan and Germany with simplified interfaces and fraud protection systems that incumbent platforms underinvest in. Pursue podcast-integrated voice-first go-to-market strategies that converge with existing audio consumption habits among commuter populations. For Investors and Strategic Acquirers: EU AI Act implementation milestones reshape the acquisition landscape toward platforms with documented model decision boundaries and training data provenance. Long-term viability favors marriage-oriented services with psychology-specialized compatibility frameworks over swipe-based volume plays. Watch for algorithmic transparency audit requirements as the inflection signal separating compliant acquisition targets from costly remediation candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Computation Investment | Edinburgh-based engineering teams address GDPR right-to-explanation requirements for behavioral matching systems. |
| Voice-First Interface Development | Bangalore anchors regional capability targeting commuter demographics in Maharashtra and Karnataka. |
| Offline Event Integration | Curated speed-dating partnerships in London and New York generate hybrid revenue streams. |
| Algorithmic Transparency Audit Preparation | Documentation standards for photo-based attraction prediction satisfy EU AI Act biometric restrictions. |
| Senior-Specific Feature Development | Japan's aging population drives advanced fraud protection and simplified interface investments. |
Research Approach
Initial hypotheses were tested against primary input from platform engineering directors, regulatory compliance officers, and user acquisition leads and refined through secondary validation. Primary interviews engaged machine learning specialists at recommendation system developers, data protection authorities in Germany and the United Kingdom, and mobile app distribution strategists at portfolio conglomerates. Secondary sources encompassed SEC filings from listed platform operators, TRAI digital consumer framework consultations, EU AI Act implementation guidance documents, and App Annie engagement metrics. Bottom-up user cohort modeling triangulated against top-down market sizing from subscription revenue disclosures.
Variance decomposition across service type, target audience, platform type, and matching algorithm dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating mobile-first adoption velocity in tier-2 Indian cities and voice-first interface penetration among commuter demographics. Forecast inputs included GDPR data portability switching cost elasticities and cloud compute pricing sensitivity for freemium tier economics.
Decision-makers should treat outputs as directional under sustained mobile-first adoption and regulatory stability assumptions; material deviation in biometric inference restrictions or app store commission structures would warrant model refresh. Recalibration cycles align with material shifts in EU AI Act enforcement patterns and TRAI framework finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Onboarding Software Market
Digital Solutions
IT As a Service Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
France ICT Market
Digital Solutions
Change and Configuration Management Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
Utility App Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market